
 United Kingdom Floor Covering Market | 2026-2036
United Kingdom Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Floor Covering Market Analytics
Aftermarket service revenue from commercial carpet maintenance and tile restoration is rewriting profitability expectations for UK flooring specialists. Victoria PLC leverages its vertically integrated manufacturing base in Kidderminster to control wool-to-weave quality and sustain margin capture across mid-market commercial projects. James Halstead PLC anchors its position through specialist vinyl flooring for healthcare and education, where hygiene certification and slip resistance create durable contract relationships. Interface Inc. competes on carbon-negative carpet tile claims, differentiating its offer as UK corporate clients tighten environmental procurement standards.
United Kingdom floor covering encompasses textile, resilient, and wood-based surface materials installed to protect subfloors, provide thermal and acoustic insulation, and define interior aesthetics in built environments. Products span tufted broadloom carpets with pile weights from 20 to 40 oz per square yard, multi-layer vinyl compositions with wear layers exceeding 0.55mm for commercial duty, and engineered hardwood with cross-laminated cores for dimensional stability over underfloor heating systems. Carpet retains the largest installed base in UK residential stock, though vinyl and laminate segments are capturing faster growth as waterproof rigid-core formats displace traditional materials in kitchens and bathrooms. Commercial application channels concentrate margin pools in specification-driven projects where contractors and designers influence material selection through long-term maintenance cost modelling rather than first-cost procurement.
The British Standards Institution governs slip resistance testing under BS 7976 and flammability performance under BS EN 13501, directly determining product eligibility for public building contracts and insurance-backed installations. Building Regulations Part E on impact sound transmission and Part L on thermal bridging compel manufacturers to publish acoustic and thermal performance data, raising compliance costs for imported products lacking UK-specific certification. The UK government's Future Homes Standard and proposed tightening of embodied carbon thresholds in construction will force stakeholders to trace supply chain emissions and validate recycled content claims through third-party verification.
Market Dynamics
Building Regulations Part L updates on thermal efficiency are forcing flooring manufacturers to recalibrate product specifications and thermal bridging data for new-build compliance, compressing development cycles and elevating certification costs across the supply base.
Growth Catalysts
- Residential renovation cycles:Greater London and South East housing stock turnover is accelerating replacement demand toward premium vinyl and engineered hardwood formats.
- Future Homes Standard:The UK government's proposed embodied carbon thresholds are compelling developers to specify lower-carbon flooring systems with verified recycled content.
- Underfloor heating penetration:Cross-laminated engineered hardwood cores are capturing specification share as hydronic and electric systems expand in residential retrofits.
Market Restraints
- Wool input cost volatility:UK wool prices fluctuate with agricultural subsidy reforms and Australian supply, squeezing margin predictability for domestic carpet weavers.
- Import certification friction:Products lacking British Standards Institution slip resistance testing under BS 7976 face automatic exclusion from public sector frameworks.
- Rigid-core vinyl substitution:Waterproof SPC and WPC formats are compressing demand for traditional sheet vinyl in kitchen and bathroom applications.
Strategic Opportunities
- Northern England underpenetration:Housing stock turnover and commercial refurbishment cycles in Manchester and Leeds lag London by 18-24 months, creating white space for early positioning.
- Carbon-negative carpet tile specification:Corporate environmental procurement standards are opening contract pathways for manufacturers with third-party verified cradle-to-gate emissions data.
- Healthcare hygiene certification:Slip resistance and infection control standards under NHS Estates guidance are locking in durable supplier relationships for vinyl flooring specialists.
Industry Challenges
- Acoustic engineer scarcity:Building Regulations Part E compliance demands for impact sound transmission testing exceed available UK laboratory capacity, extending product launch timelines.
- Supply chain reconfiguration costs:Post-Brexit Rules of Origin documentation and customs delays are forcing inventory holding pattern changes at distribution hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Floor Covering Market |
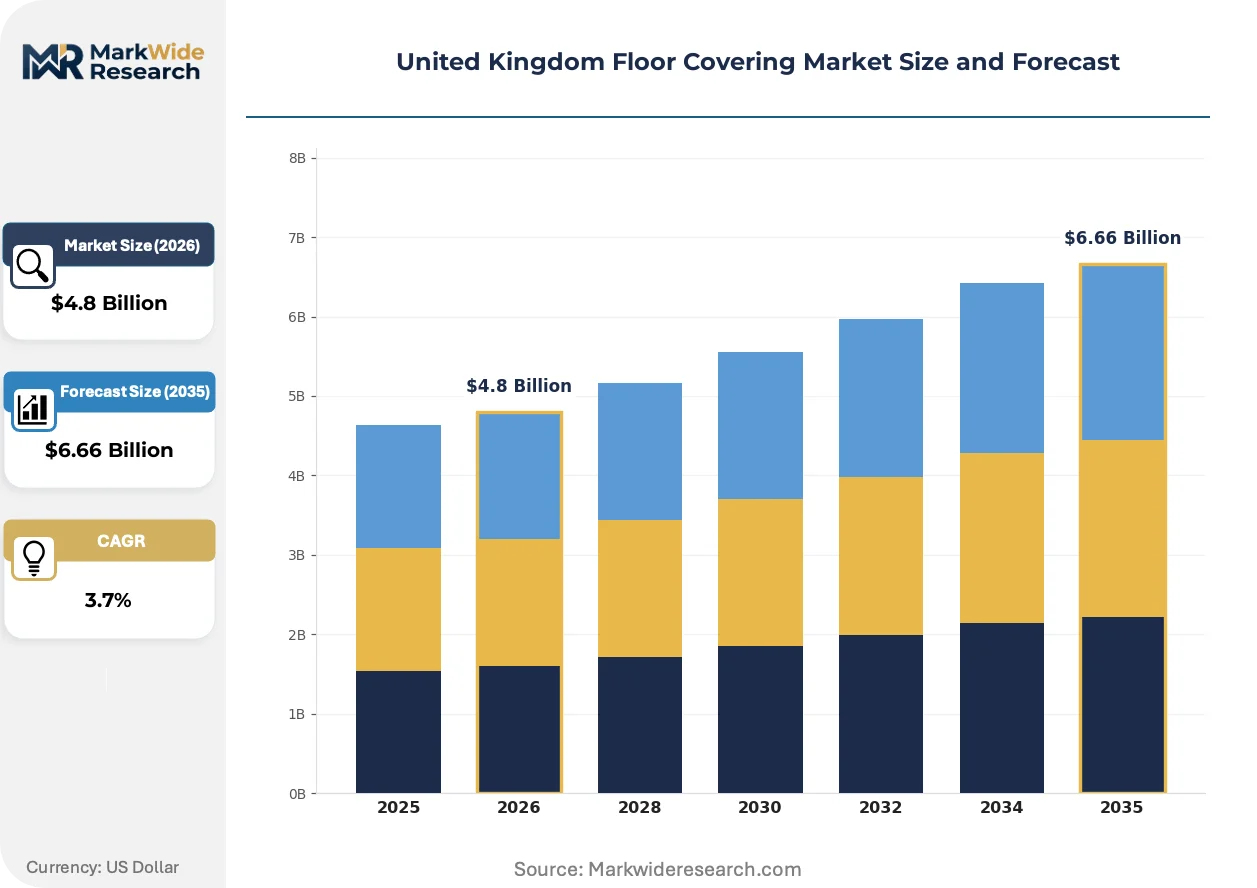
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Laminate, Vinyl, Hardwood Application: Residential, Commercial, Industrial, Hospitality End User: Homeowners, Contractors, Retailers, Designers Distribution Channel: Online, Retail Stores, Distributors, Wholesalers |
| Companies Covered | Interface Inc., Shaw Industries Group, Victoria PLC, Gerflor Group, Forbo Flooring Systems, Tarkett SA, Mohawk Industries, Armstrong Flooring, James Halstead PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Floor Covering Market Evolving Landscape
Material science advances and procurement model evolution are compressing traditional category boundaries, with performance specifications now trumping aesthetic heritage in contract specification decisions across UK commercial and residential channels.
Rigid-core vinyl flooring is migrating from niche waterproofing applications to mainstream whole-home specification. Residential developers in the South East are specifying 5mm SPC planks with 0.3mm wear layers as standard in new-build apartments. The technology is migrating from bathroom perimeter use to open-plan living zones, compressing demand for laminate and engineered wood in moisture-adjacent spaces.
Building Regulations Part L conservation of fuel and power amendments are mandating U-value calculations for complete floor build-ups rather than surface materials alone. Manufacturers must now publish thermal resistance data for underlay and adhesive combinations. Engineered hardwood suppliers with pre-certified system solutions are capturing specification share from component-only vendors in London new-build projects.
Corporate facilities managers are unbundling installation from lifecycle maintenance contracts, forcing flooring contractors to bid separately on supply, fit, and aftercare. Specialist carpet maintenance and tile restoration services are emerging as standalone profit pools. This pattern is most visible in Greater London commercial refurbishment, where five-year maintenance cost modelling now precedes capital expenditure approval.
United Kingdom Floor Covering Market Segmentation
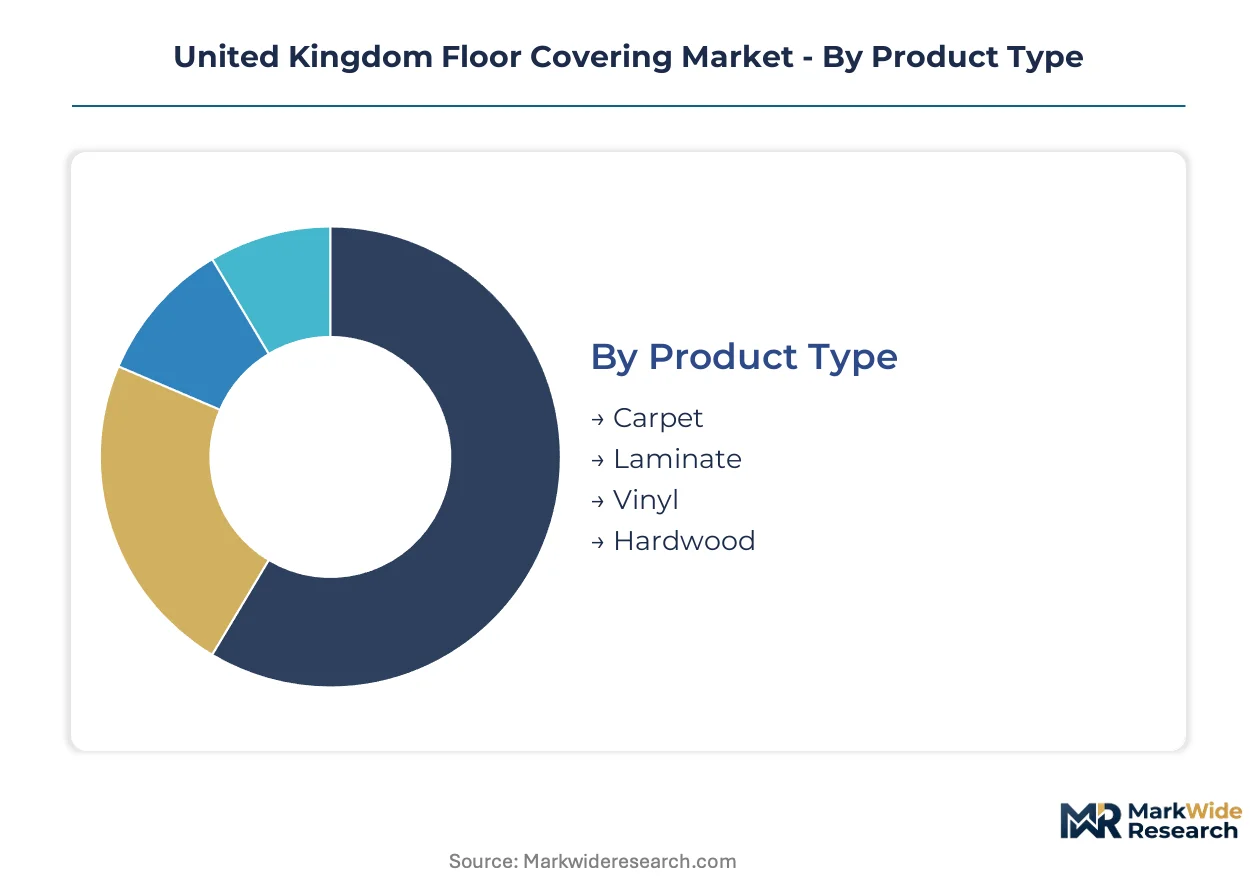
Segmentation in the United Kingdom floor covering market exposes divergent specification logics across residential renovation, commercial refurbishment, and new-build channels. Each dimension reveals how thermal compliance, hygiene certification, and procurement centralization reshape competitive positioning among material categories and supply routes.
Product Type:
The use-case spectrum stretches from acoustic comfort in urban apartments to waterproof durability in healthcare estates, with each material commanding distinct specification authority among architects, facilities managers, and homeowners.
- Carpet:Tufted broadloom constructions with 20-40 oz pile weights dominate bedroom and living room installations across Greater London Victorian housing stock. Specification concentrates in mid-market residential refurbishment where thermal insulation and sound absorption justify premium over vinyl alternatives.
- Vinyl:Multi-layer compositions with wear layers exceeding 0.55mm for commercial duty are capturing specification share in NHS Estates-guided healthcare and education projects. Demand clusters in the South East where Building Regulations Part L thermal bridging calculations favor system-certified resilient flooring over component-only supply.
- Laminate:Fiberboard-core floating floors serve cost-conscious residential replacement cycles in northern England housing stock. Manchester and Leeds renovation lag behind London by 18-24 months, compressing margin pools in budget-tier distribution.
- Hardwood:Cross-laminated engineered formats with dimensional stability certification for underfloor heating systems are specified in premium South East new-build apartments. Hydronic system penetration in residential retrofits is accelerating displacement of solid timber in moisture-adjacent zones.
The dominant share belongs to Carpet, while Vinyl is closing the gap fastest.
Application:
Cost tier stratification separates capital-light residential replacement from specification-heavy commercial frameworks where lifecycle maintenance modelling determines award.
- Residential:Renovation-driven demand in Greater London and South East housing turnover pulls specification toward premium vinyl and engineered hardwood. Building Regulations Part L updates on thermal efficiency are forcing recalibration of complete floor build-up U-value calculations.
- Commercial:Corporate facilities managers in London unbundle installation from lifecycle maintenance contracts, creating standalone profit pools for carpet maintenance and tile restoration specialists. Five-year maintenance cost modelling now precedes capital expenditure approval in refurbishment cycles.
- Industrial:Heavy-duty resilient flooring with slip resistance certification under BS 7976 serves manufacturing and logistics estates. Specification concentrates in distribution hubs where post-Brexit inventory holding pattern changes elevate local contractor relationships.
- Hospitality:Design-led specification in hotel and restaurant refurbishment balances aesthetic differentiation with hygiene certification requirements. Procurement runs through specialist contract channels where designers influence material selection through long-term maintenance cost modelling.
Commercial commands the deepest margin pools, though Residential delivers the highest volume velocity.
End User:
Customer type determines whether procurement flows through centralized frameworks or fragmented retail channels, with stark differences in technical documentation requirements and certification burden.
- Homeowners:South East owner-occupiers driving premium vinyl and engineered hardwood specification in kitchen and bathroom renovations. Waterproof rigid-core formats displace traditional materials as whole-home specification expands beyond moisture-adjacent zones.
- Contractors:Public sector framework compliance demands BS EN 13501 flammability performance data and BS 7976 slip resistance testing. Products lacking British Standards Institution certification face automatic exclusion from NHS Estates and education authority contracts.
- Retailers:Multi-branch flooring specialists in Greater London compete on installation speed and aftercare service unbundling. Aftermarket maintenance revenue is rewriting profitability expectations for mid-market operators.
- Designers:Corporate environmental procurement standards are opening contract pathways for manufacturers with third-party verified cradle-to-gate emissions data. Carbon-negative carpet tile claims differentiate specification in London commercial refurbishment.
Contractors control the specification gate for commercial volume, while Homeowners drive residential material mix shifts.
Distribution Channel:
Supply concentration patterns reflect post-Brexit customs friction and the geographic clustering of housing stock turnover versus commercial refurbishment density.
- Online:Rigid-core vinyl samples and engineered hardwood visualizers serve time-constrained South East homeowners in early-stage renovation planning. Digital specification tools compress the traditional showroom visit cycle.
- Retail Stores:Greater London flagship locations combine material display with in-house installation bidding. Five-year maintenance contract unbundling is visible first in these metropolitan showrooms.
- Distributors:Regional stockholding hubs in Manchester and Leeds serve northern England contractor networks where housing stock turnover lags the capital. Post-Brexit Rules of Origin documentation is forcing inventory depth adjustments.
- Wholesalers:Volume supply to multi-site commercial contractors concentrates in specification-grade carpet tile and certified vinyl for healthcare frameworks. Thermal resistance data publication requirements under Part L are elevating compliance costs for imported products.
Retail Stores anchor residential specification in the South East, while Wholesalers capture commercial framework volume through certified system supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across UK sub-regions. Greater London buyers absorb premium specifications without volume contraction, while northern England markets compress margin pools through cost-first procurement.
London and South East
Residential stock turnover in Kensington, Chelsea, and Surrey drives specification toward engineered hardwood and rigid-core vinyl. Building Regulations Part L thermal bridging calculations compel developers to source system-certified flooring with published U-value data. Victoria PLC's Kidderminster manufacturing base supplies commercial carpet tile for Canary Wharf refurbishment cycles.
Midlands
Birmingham and Coventry logistics hubs concentrate distribution capacity for national contractor networks. Post-Brexit Rules of Origin documentation delays force inventory depth adjustments at regional stockholding points. The British Standards Institution certification burden falls heaviest on imported sheet vinyl competing for education authority frameworks.
North England
Manchester and Leeds housing renovation trails London by 18-24 months, creating white space for early positioning in premium vinyl segments. NHS Estates hygiene certification requirements lock in durable supplier relationships for vinyl flooring specialists serving hospital estates in Liverpool and Newcastle. Local contractor networks remain fragmented compared to southern concentration.
Scotland
Edinburgh and Glasgow commercial refurbishment runs on distinct procurement calendars from English markets. Scottish Building Standards on energy performance create parallel compliance pathways for thermal resistance data publication. Hydronic underfloor heating penetration in residential retrofits accelerates engineered hardwood specification in suburban developments.
Wales
Cardiff and Swansea construction activity concentrates in social housing retrofit programs where cost constraints dominate material selection. Welsh Government procurement frameworks emphasize local supplier preference, reshaping competitive access for England-based distributors. Acoustic performance requirements under Part E exceed available testing laboratory capacity, extending product launch timelines.
United Kingdom Floor Covering Market Competitive Landscape
Capability concentration sits with specialist manufacturers holding vertical control over raw material quality; scale advantage sits with diversified flooring conglomerates serving multi-regional contract frameworks. The vendor base organizes around three archetypes: wool-to-weave carpet specialists, healthcare-certified vinyl fabricators, and carbon-negative carpet tile innovators. Consolidation pressure operates through M&A activity targeting regional distribution networks and backward integration into polymer compounding for rigid-core production.
Among UK-based specialists, Victoria PLC exemplifies the vertically integrated carpet manufacturer archetype, while James Halstead PLC occupies a position within healthcare-certified vinyl supply. Interface Inc. represents the carbon-negative specification tier competing on third-party verified emissions data. These three anchors illustrate how competitive positioning diverges across material categories and end-use certification requirements.
| Leading Market Players |
|---|
| Interface Inc. |
| Shaw Industries Group |
| Victoria PLC |
| Gerflor Group |
| Forbo Flooring Systems |
| Tarkett SA |
| Mohawk Industries |
| Armstrong Flooring |
| James Halstead PLC |
| Others |
Value Network & Pricing Analysis
Port of Felixstowe container handling cost dynamics compress margin predictability for UK flooring distributors while amplifying price differentiation between system-certified suppliers and component-only vendors serving London new-build developers.
Pricing Analysis
Aftermarket maintenance and restoration service contracts now drive lifetime value capture for UK flooring specialists. Three-tier pricing structure across premium, standard, and economy levels separates specification-grade carpet tile with carbon-negative certification from mid-market vinyl and budget laminate. Price differentiation rests on Building Regulations Part L thermal compliance documentation and BS 7976 slip resistance certification. Cost compression in economy-tier laminate intensifies because northern England housing renovation lags compress volume velocity. Contractors in public sector frameworks exhibit lowest price sensitivity; northern England homeowners in replacement cycles show highest.
Supply Chain Analysis
Tariff exposure between the European Union and United Kingdom dominates supply chain risk calculus for flooring importers. Manufacturing concentrates in Belgium, Germany, and China for carpet tile backing, vinyl wear-layer compounds, and engineered hardwood cores. Raw material dependencies draw from petroleum-based plasticizers, wool fiber from Australian and New Zealand agricultural sources, and cross-laminated timber cores from Baltic states. Single-source vulnerability in BS 7976 testing laboratory capacity extends product launch timelines. Distribution runs through Midlands logistics hubs serving national contractor networks with post-Brexit inventory depth adjustments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK floor covering is a service-attach opportunity where aftermarket carpet maintenance and tile restoration revenue layers expand faster than material supply margins.
For Market Incumbents: Insulate specification share by deepening backward integration into polymer compounding for rigid-core vinyl production and securing captive wool supply through agricultural contracting. Rigid-core substitution threatens traditional sheet vinyl margins. Certification investment in Part L system solutions captures London new-build specification from component-only rivals. For New Entrants and Emerging Players: Northern England commercial refurbishment in Manchester and Leeds represents the most penetrable entry point given 18-24 month lag behind London cycles. Healthcare hygiene certification under NHS Estates guidance locks in durable supplier relationships for vinyl flooring specialists. Direct contractor engagement bypassing fragmented retail channels accelerates initial traction. For Investors and Strategic Acquirers: Regional distribution networks with post-Brexit customs clearance capabilities and Part E acoustic testing partnerships offer the strongest acquisition profile. Long-term viability hinges on tracing supply chain emissions for Future Homes Standard compliance. Watch for embodied carbon threshold tightening as inflection indicator for specification-grade product demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of SPC core material reduces tariff exposure and compresses lead times for rigid-core vinyl production. |
| Part L System Certification Investment | Pre-certified thermal build-up solutions capture London new-build specification from component-only competitors. |
| Healthcare Hygiene Certification Pathway | NHS Estates compliance locks in durable contract relationships for vinyl flooring in hospital refurbishment cycles. |
| Regional Distribution Network Acquisition | Midlands and northern England hubs with customs clearance capabilities secure post-Brexit supply continuity. |
| Carbon-Negative Product Line Launch | Third-party verified cradle-to-gate emissions data opens corporate procurement pathways in London commercial refurbishment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the UK floor covering value chain. Primary interviews engaged facilities managers at NHS Estates, commercial contractors in London refurbishment, procurement leads at housing developers, and aftermarket service specialists. Secondary validation drew from British Standards Institution certification records, Building Regulations compliance databases, UK trade customs data, and industry association shipment reports. Bottom-up volume modeling triangulated against top-down construction activity indices.
Calibration against historical specification trends and regulatory implementation timelines anchored the analytical framework. Segmentation dimensions modeled include product type, application channel, end-user archetype, and geographic demand cluster. CAGRs were derived from regression analysis of replacement cycle velocity and new-build completion rates. Underfloor heating penetration rates and embodied carbon threshold proposals served as industry-specific forecast inputs across the projection horizon.
Practitioners should monitor wool price volatility, Part L thermal compliance enforcement intensity, and rigid-core vinyl substitution rates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Lightweight Acoustic Floor Systems Market
Flooring, Carpets, and Rugs
Entrance Matting Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
India Carpets and Rugs Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Hardwood Flooring Market
Flooring, Carpets, and Rugs
Europe Carpet Tile Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Asia-Pacific Floor Covering Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market