
 United Arab Emirates Interior Design Market | 2026-2036
United Arab Emirates Interior Design Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Interior Design Market Analytics
Dubai's construction pipeline is rewriting procurement patterns for interior fit-out services. Bishop Design leverages its hospitality specialization across landmark hotel projects on Sheikh Zayed Road. Godwin Austen Johnson anchors large-scale commercial developments through integrated architecture and interiors capabilities. XBD Collective differentiates via technology-led design workflows that compress project timelines for developer clients.
Interior design encompasses the art and science of enhancing indoor environments through spatial planning, material selection, lighting design, and furniture specification to achieve functional and aesthetically optimized spaces. The discipline applies technical parameters including lux levels, acoustic ratings, and fire-resistance classifications to ensure occupant safety and comfort. Residential project types command sustained volume as expatriate populations expand villa and apartment fit-out requirements. Hospitality applications represent the fastest-growing segment, driven by hotel stock expansion ahead of major events. Contemporary and minimalist design styles capture premium margin pools among ultra-high-net-worth homeowners in Emirates Hills and Palm Jumeirah.
MOHAP enforces building safety and environmental health standards that mandate material emissions testing for interior finishes across healthcare and hospitality settings. Dubai Municipality's green building regulations require specified recycled content thresholds in commercial interior fit-outs. Stakeholders must monitor evolving sustainability mandates and local content preferences that will reshape supplier qualification criteria and project award mechanisms.
Market Dynamics
MOHAP building code revisions are compressing project timelines across UAE commercial fit-outs. Developers must now integrate energy-efficiency specifications from schematic design through final handover, fundamentally restructuring how interior specialists coordinate with MEP contractors and material suppliers.
Growth Catalysts
- MOHAP energy-efficiency mandates:Tighter building codes for commercial interiors are accelerating specification of low-emission finishes and smart lighting systems across Dubai healthcare and hospitality projects.
- Hospitality stock expansion:Hotel pipeline growth ahead of major events is driving demand for luxury fit-out services along Sheikh Zayed Road and waterfront corridors.
- Expatriate residential demand:Villa and apartment fit-out requirements in Emirates Hills and Palm Jumeirah are sustaining volume for contemporary minimalist design specialists.
Market Restraints
- Material cost volatility:Imported stone, engineered timber, and specialty metals face price instability tied to shipping lane disruptions and currency fluctuations affecting UAE procurement budgets.
- Specialized labor concentration:Skilled millwork craftsmen and certified MEP integrators cluster in Dubai and Abu Dhabi, creating bottlenecks for projects in emerging emirates.
- Recycled content thresholds:Dubai Municipality green building regulations mandate specified percentages for commercial interiors, limiting supplier pools and extending qualification timelines.
Strategic Opportunities
- Ras Al Khaimah and Fujairah hospitality:Secondary emirate tourism development offers first-mover positioning for interior specialists ahead of competitor saturation.
- Technology-led workflow convergence:Building information modeling paired with virtual reality visualization is compressing client approval cycles and reducing rework costs.
- Healthcare interior specialization:MOHAP material emissions testing requirements for clinical settings create defensible expertise moats for compliant design practices.
Industry Challenges
- Certified sustainability credentialing:LEED AP and WELL Accredited Professional qualifications remain scarce among mid-level designers, constraining firm scaling for green building mandates.
- Legacy MEP coordination:Existing building stock in older Dubai commercial towers requires complex retrofit integration with modern low-voltage lighting and HVAC controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Interior Design Market |
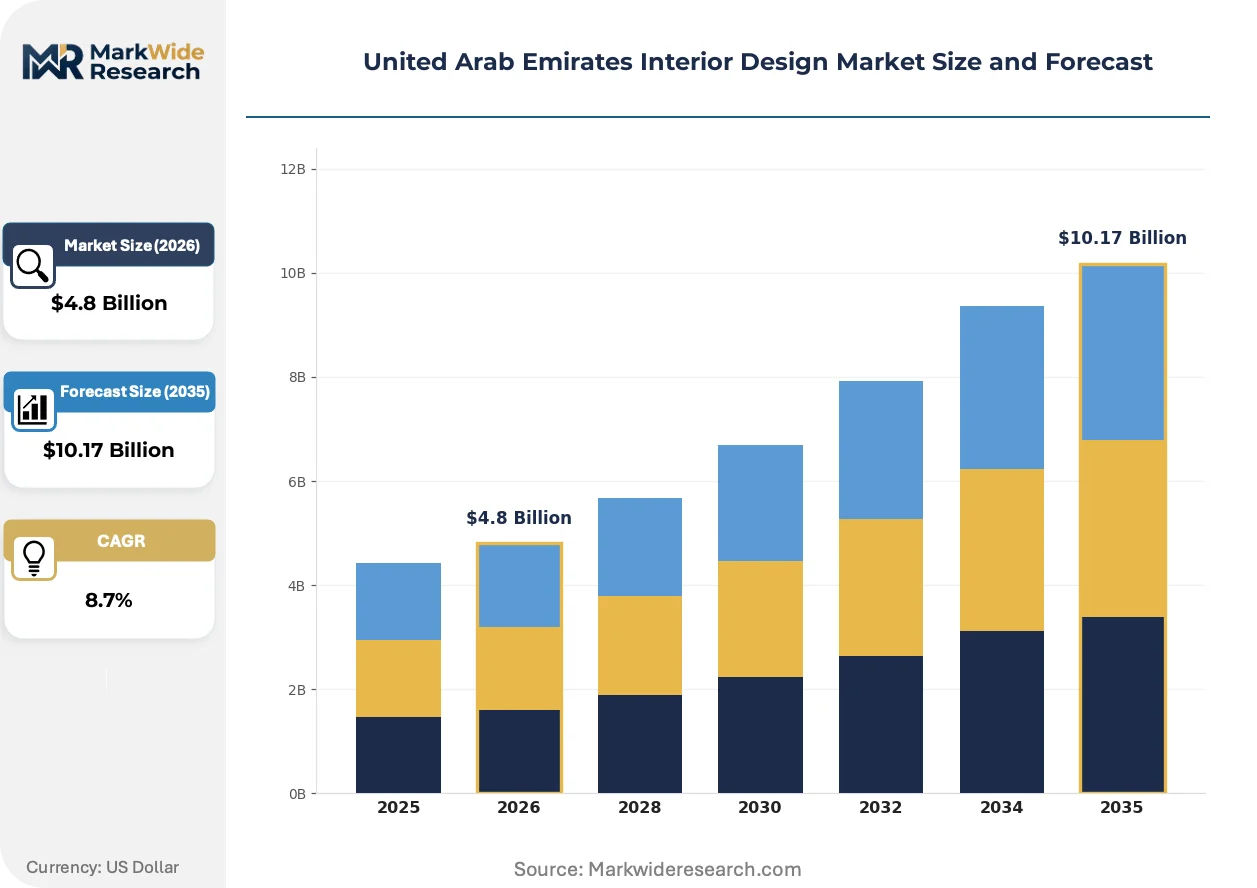
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Hospitality, Retail Design Style: Modern, Traditional, Contemporary, Minimalist Material: Wood, Glass, Metal, Fabric End User: Homeowners, Corporates, Developers, Entrepreneurs |
| Companies Covered | Bishop Design, Fajr Interiors, Design Divine, Godwin Austen Johnson, Zen Interiors, Algedra, XBD Collective, Muse Interior Design, CK Architecture, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Interior Design Market Evolving Landscape
Digital fabrication and regulatory tightening are compressing traditional design-to-delivery cycles across UAE fit-out projects. Three developments are actively restructuring competitive positioning.
Parametric design software coupled with CNC manufacturing is collapsing the gap between concept visualization and physical production. High-end residential developers in Palm Jumeirah and Emirates Hills are adopting these workflows to achieve complex geometric millwork and bespoke metal screens without traditional prototyping delays. This compression is eliminating smaller studios lacking in-house digital fabrication partnerships.
MOHAP material emissions testing protocols for healthcare and hospitality interiors are hardening specification standards. Suppliers must now submit third-party certifications for VOC content and fire-resistance ratings before project approval. Hospitality fit-outs along Dubai's Sheikh Zayed Road corridor face the tightest compliance scrutiny, driving consolidation toward pre-qualified vendor networks.
Developer procurement teams are unbundling design and build contracts that previously ran through single-source general contractors. Direct engagement with specialized interior firms allows tighter control over finish quality and accelerates decision cycles for luxury residential towers. This disintermediation is most visible in waterfront projects where contemporary minimalist aesthetics command premium positioning.
United Arab Emirates Interior Design Market Segmentation
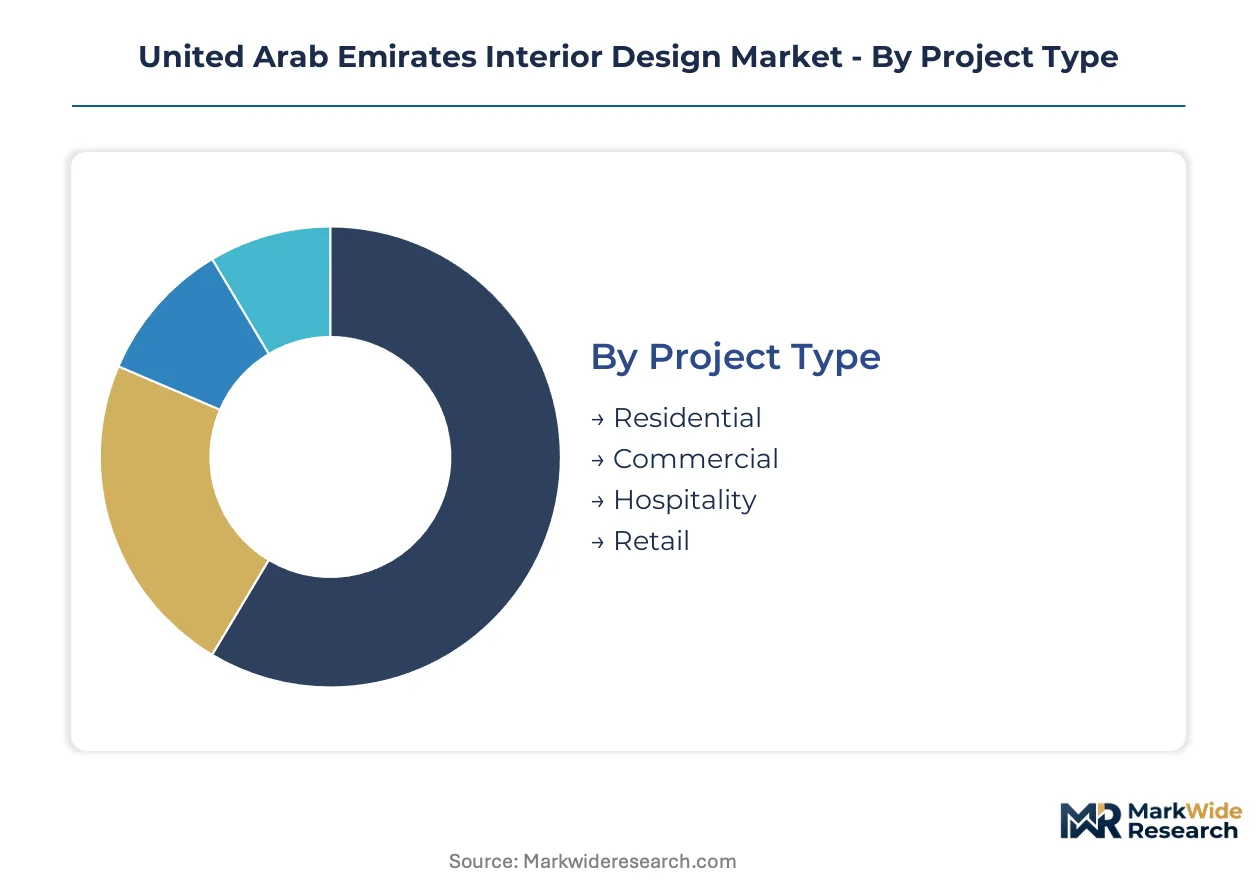
UAE interior design procurement patterns diverge sharply across project types, with hospitality and residential towers commanding premium fee structures while retail fit-outs operate on compressed margins. Design style preferences cluster geographically, with contemporary minimalism dominating waterfront developments and traditional motifs persisting in heritage districts. Material specification and end-user sophistication determine supplier qualification tiers and contract award mechanisms.
Project Type:
Application scope determines fee structures, coordination complexity, and regulatory exposure across the Emirates.
- Residential:Villa and apartment fit-outs in Emirates Hills and Palm Jumeirah sustain volume for bespoke millwork and smart home integration. Expatriate population expansion drives demand for turnkey furnishing packages in new waterfront towers.
- Hospitality:Luxury hotel fit-outs along Sheikh Zayed Road and waterfront corridors face MOHAP energy-efficiency mandates and accelerated timelines ahead of major events. This segment commands the highest design fees and tightest vendor qualification standards.
- Commercial:Office interiors in Dubai International Financial Centre and Abu Dhabi Global Market prioritize flexible workspace configurations and wellness-certified environments.
- Retail:Mall fit-outs in Dubai Mall and Mall of the Emirates operate on rapid turnaround cycles with standardized fixture systems.
Residential commands the established base. The steepest expansion runs through Hospitality.
Design Style:
Customer aesthetic preferences stratify across price tiers and developer positioning strategies.
- Contemporary:Clean lines and neutral palettes dominate ultra-high-net-worth residential towers along the Arabian Gulf coastline. Dubai developers specify this style for premium positioning in Palm Jumeirah.
- Minimalist:Reduced material palettes and concealed storage systems align with sustainability mandates and smaller residential footprints. Abu Dhabi waterfront projects increasingly specify this approach.
- Modern:Open-plan layouts and industrial material combinations persist in commercial interiors and co-working spaces.
- Traditional:Mashrabiya screens and ornate metalwork retain demand in heritage hospitality projects and cultural institutions.
Contemporary holds the revenue concentration. Minimalist is climbing the fastest as MOHAP efficiency requirements tighten.
Material:
Supply chain geography and certification requirements shape specification feasibility.
- Wood:Engineered timber and certified hardwoods face price volatility from shipping lane disruptions. Emirates Green Building Council preferences favor FSC-certified sources for commercial fit-outs.
- Metal:Brass and bronze finishes command premium positioning in luxury hospitality projects. Local fabrication capabilities in Dubai Industrial City reduce lead times for bespoke screens and fixtures.
- Glass:Smart glazing and acoustic-rated panels meet MOHAP thermal performance standards for high-rise residential towers.
- Fabric:Fire-resistant textiles and low-VOC upholstery satisfy MOHAP emissions testing for healthcare and hospitality interiors.
Wood anchors the specification volume. Metal is gaining share fastest as parametric design adoption spreads.
End User:
Procurement sophistication and decision velocity vary dramatically across buyer categories.
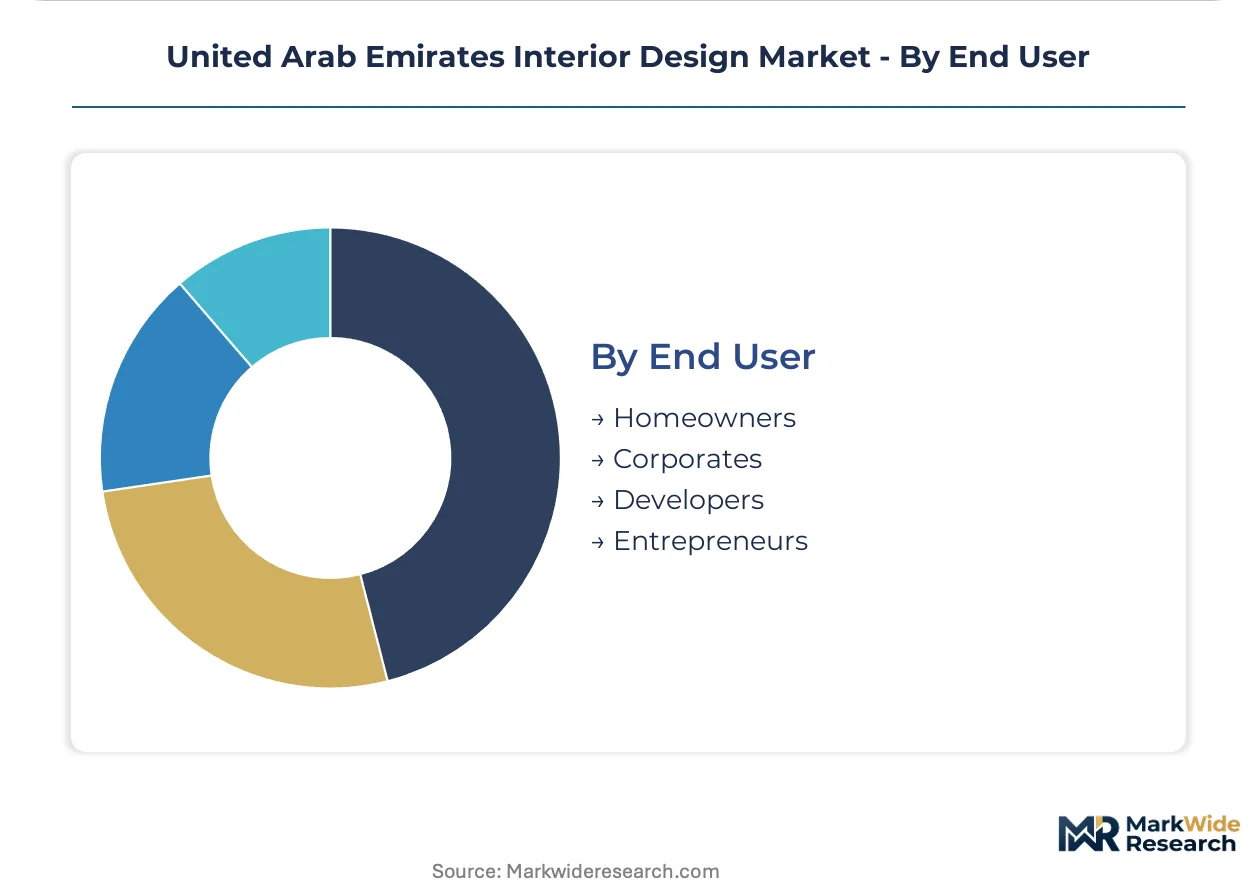
- Developers:Large-scale residential and hospitality projects in Dubai and Abu Dhabi leverage direct interior firm engagement, bypassing general contractors to compress timelines and control finish quality.
- Corporates:Multinational headquarters in Dubai International Financial Centre mandate WELL certification and flexible workspace systems with short renewal cycles.
- Homeowners:Ultra-high-net-worth individuals in Emirates Hills and Palm Jumeirah commission bespoke interiors with extended design phases and unlimited revision scopes.
- Entrepreneurs:Restaurant and boutique retail operators in secondary emirates prioritize speed-to-market over customization, favoring standardized fit-out packages.
Developers control the project pipeline. Corporates are expanding their design budgets fastest as ESG reporting requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MOHAP building codes anchor regulatory intensity across the Emirates, with energy-efficiency mandates tightening fastest in commercial corridors. Interior specialists must coordinate across seven emirates with divergent enforcement timelines and local content preferences.
Dubai
Luxury hospitality fit-outs along Sheikh Zayed Road and the Arabian Gulf coastline drive specification volume for low-emission finishes and smart lighting systems. Dubai Municipality green building regulations mandate recycled content thresholds in commercial interiors, compressing supplier qualification timelines. The Palm Jumeirah and Emirates Hills clusters concentrate ultra-high-net-worth residential demand for contemporary minimalist design.
Abu Dhabi
Waterfront residential towers on Al Reem Island and Saadiyat Island prioritize concealed storage systems and reduced material palettes aligned with efficiency mandates. The Department of Municipalities and Transport enforces sustainability standards that parallel Dubai's framework with stricter local content incentives. Al Maryah Island's financial district generates corporate interior demand for WELL-certified flexible workspaces.
Sharjah
Cultural and heritage hospitality projects sustain demand for traditional mashrabiya screens and ornate metalwork specifications. The Sharjah Investment and Development Authority promotes design-led tourism infrastructure with distinct aesthetic requirements from Dubai's contemporary dominance. University City and healthcare clusters drive clinical interior specialization under MOHAP emissions testing protocols.
Ras Al Khaimah
Secondary emirate tourism development offers first-mover positioning for interior specialists ahead of competitor saturation. The Ras Al Khaimah Tourism Development Authority accelerates hotel pipeline approvals with streamlined permitting for sustainable fit-outs. Al Marjan Island and Jebel Jais mountain resorts concentrate emerging hospitality stock with compressed project timelines.
Northern Emirates
Fujairah and Ajman present underserved corridors where standardized fit-out packages serve entrepreneur-led restaurant and retail operators. Federal MOHAP standards apply uniformly, though enforcement capacity varies across municipal jurisdictions. Industrial zones in these emirates attract manufacturing-adjacent interior demand with lower cost structures than Dubai or Abu Dhabi.
United Arab Emirates Interior Design Market Competitive Landscape
Hospitality specialists and integrated architecture-interiors practices split the market between project-type depth and full-service scale. The vendor base clusters around three strategic archetypes: luxury hospitality boutiques, multidisciplinary design-build firms, and technology-enabled workflow specialists. Consolidation pressure runs through direct developer engagement models that disintermediate general contractors. Competitive moves center on parametric design capability acquisition and secondary emirate geographic expansion.
Within the hospitality-specialist tier, Bishop Design exemplifies luxury hotel fit-out positioning across landmark Sheikh Zayed Road projects. Godwin Austen Johnson occupies the integrated architecture-interiors vector through large-scale commercial development capabilities. XBD Collective represents technology-led workflow convergence, compressing project timelines via building information modeling and virtual reality visualization for developer clients.
| Leading Market Players |
|---|
| Bishop Design |
| Fajr Interiors |
| Design Divine |
| Godwin Austen Johnson |
| Zen Interiors |
| Algedra |
| XBD Collective |
| Muse Interior Design |
| CK Architecture |
| Others |
Value Network & Pricing Analysis
Italian marble quarries and engineered timber mills in Southeast Asia concentrate premium material supply, anchoring margin pools in Dubai's luxury hospitality fit-out tier where developers absorb markups for certified low-emission finishes. Pricing power cascades downstream through pre-qualified vendor networks that MOHAP emissions testing protocols have consolidated.
Pricing Analysis
Dubai commands 35-50% fee premiums over Ras Al Khaimah and Fujairah for equivalent hospitality scope, with contemporary minimalist residential towers in Palm Jumeirah extracting the widest spreads. Project-based fee structures dominate, with differentiation driven by WELL certification status and parametric design capability. Cost compression in standardized retail fit-outs is intensifying as mall operators demand rapid turnaround packages. Entrepreneur-led restaurant operators in secondary emirates exhibit highest price sensitivity; ultra-high-net-worth homeowners in Emirates Hills show least.
Supply Chain Analysis
Export-control scrutiny on CNC machinery and smart glazing technology from European and East Asian suppliers limits fabrication capacity expansion for complex geometric millwork. Material flows draw from Italy, Spain, and Turkey for stone and ceramics; Southeast Asia and Scandinavia for engineered timber; China and South Korea for smart lighting and HVAC controls. Single-source vulnerability concentrates in certified fire-resistant textiles where MOHAP-approved mills number under a dozen. Distribution runs through Dubai Industrial City fabrication hubs serving fit-out contractors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MOHAP's tightening energy-efficiency mandates are disrupting traditional procurement patterns, compressing timelines and consolidating vendor qualification around certified low-emission material networks.
For Market Incumbents: Harden defensibility through captive supply agreements with FSC-certified timber mills and third-party emissions testing laboratories. Bishop Design and Godwin Austen Johnson should deepen parametric design partnerships before technology-enabled specialists capture developer direct-engagement contracts. Vertical integration into CNC fabrication insulates against machinery import bottlenecks.
For New Entrants and Emerging Players: Build out healthcare interior specialization around MOHAP clinical material testing requirements, where compliant design practices remain scarce among mid-level firms. Ras Al Khaimah and Fujairah hospitality pipelines offer penetrable white-space before incumbent saturation. Target first-mover positioning via direct developer relationships disintermediating general contractors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hospitality specialists holding Sheikh Zayed Road project portfolios. Long-term viability hinges on technology-led workflow convergence and secondary emirate geographic expansion. Watch for MOHAP building code alignment across Northern Emirates as inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Design Capability Acquisition | CNC manufacturing partnerships collapse prototyping delays for Palm Jumeirah residential developers. |
| Healthcare Interior Specialization | MOHAP emissions testing requirements create defensible expertise moats in clinical settings. |
| Secondary Emirate Geographic Expansion | Ras Al Khaimah Tourism Development Authority streamlines permitting ahead of competitor saturation. |
| Direct Developer Engagement Models | Unbundled contracts bypass general contractors to compress decision cycles for waterfront towers. |
| Certified Material Supply Integration | FSC and low-VOC pre-qualification locks out non-compliant vendors from hospitality procurement. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of Dubai Municipality building permits, Emirates Green Building Council certification databases, and hospitality project development trackers. Primary interviews engaged interior design principals, procurement directors at master developers, MEP contractors, and material suppliers across Dubai, Abu Dhabi, and Sharjah. Secondary sources included MOHAP regulatory filings, Dubai Chamber of Commerce trade data, and SEC disclosures from listed construction materials distributors. Bottom-up project pipeline enumeration triangulates against top-down sectoral expenditure estimates from federal statistical releases.
Forecast inputs incorporate hospitality stock expansion timelines, residential tower completion schedules, and MOHAP regulatory phase-in dates across the analysis window. Segmentation models disaggregate by project type, design style, material specification, and end-user procurement sophistication. CAGRs derive from fitted trend extrapolation adjusted for policy inflection points and construction cycle dynamics. Specific inputs include expatriate population projections and hotel pipeline data from tourism authority disclosures.
The forecast holds incumbent behavior within observed patterns; aggressive technology acquisition or vertical integration moves by mid-cap specialists would shift outcomes. Cross-checking against Dubai Department of Economy and Tourism construction expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Homecare and Decor
United States Decorative Laminates Market
Homecare and Decor
Pillow Market
Homecare and Decor
North America Sustainable Home Decor Market
Homecare and Decor
India Sustainable Home Decor Market
Homecare and Decor
US Mattress Bases Market
Homecare and Decor
US Wallcovering Market
Homecare and Decor
US Wallpaper Market
Homecare and Decor
India Decorative Laminates Market
Homecare and Decor
Wall Covering Market
Homecare and Decor
United States Wall Coverings Market
Homecare and Decor
Revolving Doors Market
Homecare and Decor
US Steam Rooms Market
Homecare and Decor
Mattresses and Accessories Market
Homecare and Decor
Smart Curtain Market
Homecare and Decor
India Interior Design Market
Homecare and Decor
Gas Fire Table Market