
 United States Laminate Flooring Market | 2026-2036
United States Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
United States Laminate Flooring Market Analytics
Southeastern U.S. flooring mills is repositioning capacity toward water-resistant laminate grades to capture replacement demand from vinyl-sensitive homeowners. Mohawk Industries leverages its Dalton, Georgia manufacturing base to sustain cost leadership in standard thickness categories. Shaw Industries Group anchors its position through captive resin operations and direct-to-contractor distribution. Mannington Mills differentiates via specialty embossing technology that mimics reclaimed hardwood aesthetics.
United States laminate flooring comprises a multi-layer composite surface material built from a high-density fiberboard core, decorative paper impregnated with melamine resin, and a transparent aluminum oxide wear layer rated by AC durability class. Its primary commercial purpose is delivering cost-efficient, dimensionally stable floor coverings that replicate hardwood or stone appearances while tolerating residential and light commercial foot traffic. Premium laminates occupy the strongest margin pool as homeowners trade up from entry-level products toward thicker 12mm and 15mm click-lock systems with enhanced moisture barriers. Direct-pressure laminates dominate unit volume in builder-grade residential channels where price sensitivity compresses specification tolerance.
The EPA enforces TSCA Title VI formaldehyde emission limits that constrain substrate sourcing and compel third-party certification through accredited laboratories. The California Air Resources Board maintains its ATCM 93120 standard, which functions as a de facto national benchmark given the state's market weight and supplier compliance consolidation. OSHA workplace exposure rules and the FTC's Green Guides additionally shape product labeling and installation material disclosures. Stakeholders must monitor evolving state-level PFAS restrictions and EPD reporting requirements that could recalibrate material specifications and supplier qualification thresholds.
Market Dynamics
EPA TSCA Title VI formaldehyde emission standards are compressing substrate sourcing toward certified low-emission fiberboard mills, forcing supply chain requalification and regional capacity consolidation among Southeast U.S. manufacturers.
Growth Catalysts
- First-time homebuyer renovation:Residential construction activity in Texas and Florida is expanding specification of click-lock laminate systems among entry-level housing purchasers seeking cost-efficient hardwood alternatives.
- ATCM 93120 compliance consolidation:California Air Resources Board standards function as de facto national benchmarks, streamlining supplier certification and reducing multi-state regulatory fragmentation for substrate producers.
- Humidity-resistant click-lock technology:Moisture-barrier advancements in 12mm and 15mm thickness categories are capturing replacement demand from vinyl-sensitive homeowners in Gulf Coast states.
Market Restraints
- High-density fiberboard input volatility:Resin and wood pulp cost fluctuations compress margin stability for direct-pressure laminate producers serving builder-grade residential channels.
- Southeast supply concentration:Manufacturing gravity in Georgia and adjacent states creates weather-related disruption exposure and freight cost asymmetries for Western U.S. distribution.
- Luxury vinyl tile substitution:Waterproof rigid core vinyl products are displacing laminate specification in moisture-prone commercial applications and basement installations.
Strategic Opportunities
- PFAS restriction preparation:Anticipated state-level fluorinated compound regulations create first-mover advantage for mills with pre-certified PFAS-free substrate formulations and transparent supply chain documentation.
- EPD reporting differentiation:Environmental Product Declaration requirements in public procurement and LEED-adjacent specifications reward manufacturers with lifecycle-assessed product portfolios.
- Direct-to-contractor distribution:Bypassing traditional distributor tiers through captive logistics networks captures margin and specification influence in multi-family and light commercial segments.
Industry Challenges
- Third-party certification timelines:TSCA Title VI laboratory accreditation delays and CARB-ATCM recertification cycles extend product launch windows and inventory holding costs.
- Specialty embossing equipment capex:Reclaimed hardwood aesthetic replication requires precision press investments that strain mid-tier mill balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Laminate Flooring Market |
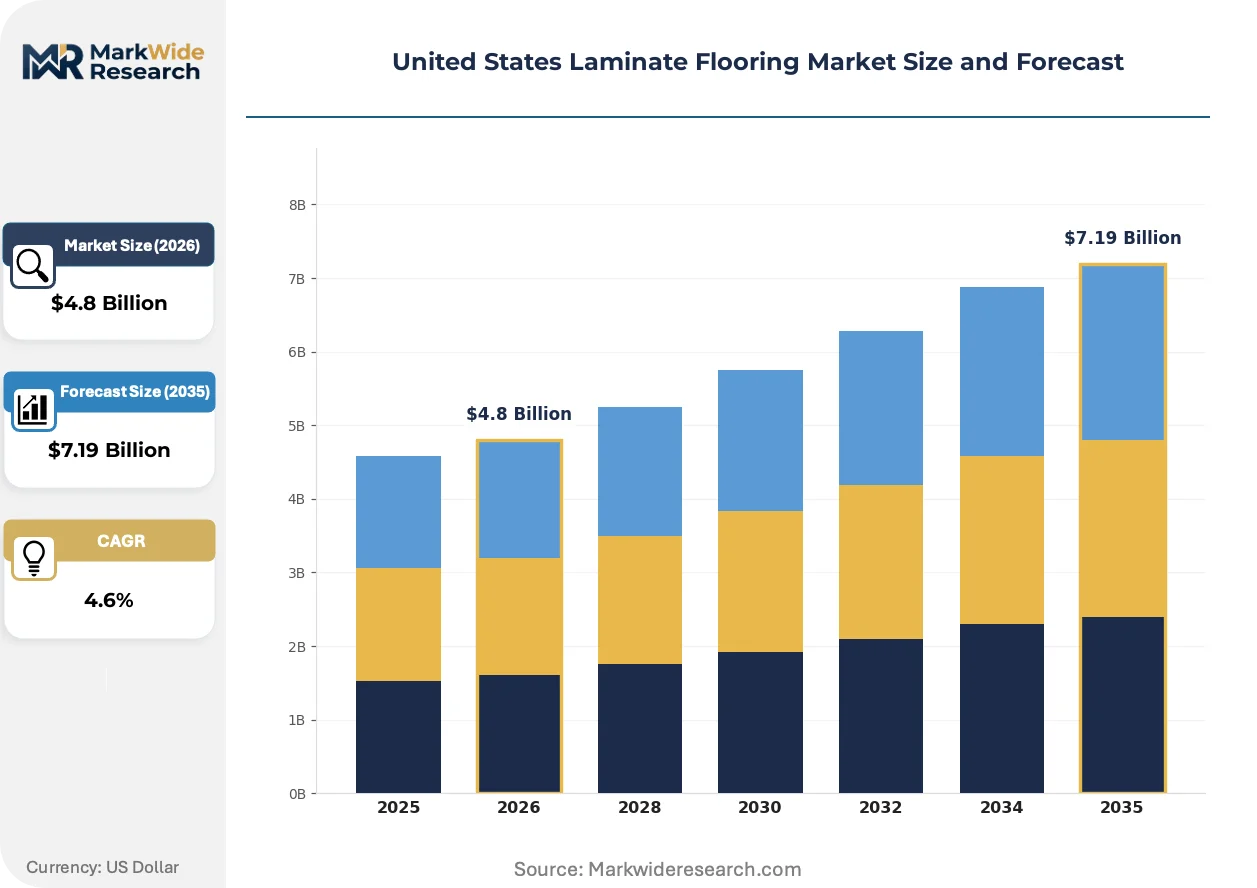
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminates, Direct-Apex Laminates, Premium Laminates, Standard Laminates Thickness: 8mm, 10mm, 12mm, 15mm Installation Type: Glue Down, Click Lock, Nail Down, Floating End User: Residential, Commercial, Industrial, Retail |
| Companies Covered | Mohawk Industries Inc, Shaw Industries Group Inc, Armstrong Flooring Inc, Mannington Mills Inc, Tarkett SA, Pergo, Quick-Step, Kronospan Limited, Swiss Krono Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Laminate Flooring Market Evolving Landscape
Water-resistant laminate technology is consolidating competitive advantage among Southeastern mills while regulatory emission standards and buyer procurement sophistication reshape specification protocols across residential and light commercial channels.
Aluminum oxide wear layer advancement is consolidating durability performance across AC3-AC5 rating classes, enabling 15mm thickness systems to penetrate light commercial foot traffic segments previously reserved for engineered hardwood. Property developers in Texas and Florida are specifying these upgraded laminates for rental property renovations at accelerating rates. The technology is consolidating margin pools around premium thickness categories while compressing specification tolerance for entry-level 8mm products in new single-family construction.
EPA TSCA Title VI enforcement is tightening substrate sourcing documentation requirements, compelling mills to maintain chain-of-custody records from fiberboard origin through finished goods. Industrial consequence includes disqualification of uncertified overseas substrate suppliers and accelerated domestic mill capacity expansion. Southeast U.S. manufacturers with captive resin operations are responding fastest, locking in compliant supply bases before enforcement windows narrow.
Buyer certification literacy is reshaping procurement criteria among national homebuilders and multi-family developers, displacing price-primary specification with emission-grade and EPD documentation requirements. Traditional distributor showrooms are losing influence to direct mill-contractor relationships where technical compliance data transfers immediately. This behavioral shift concentrates most visibly in Florida and California markets where municipal green building codes intersect with corporate sustainability procurement mandates.
United States Laminate Flooring Market Segmentation
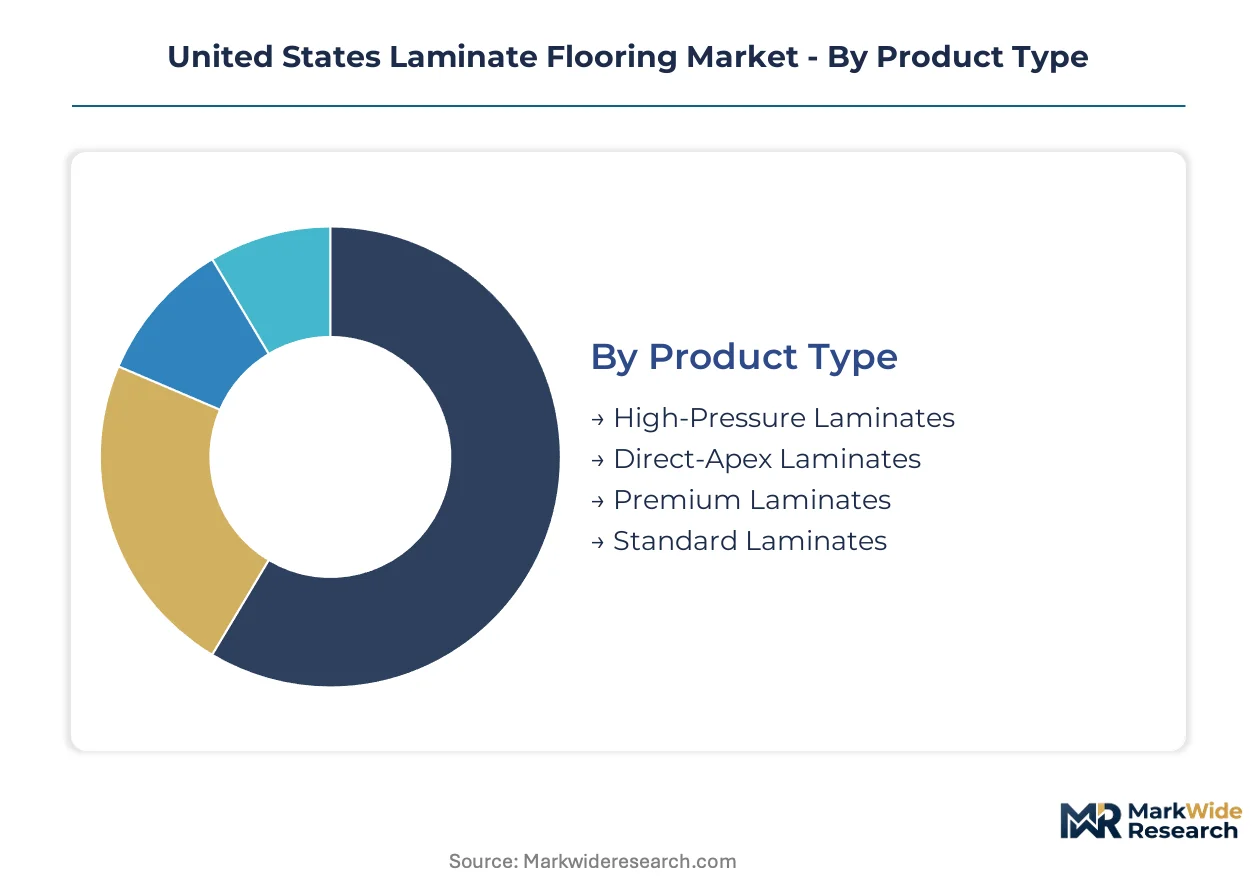
Segmentation in the United States laminate flooring market reveals how specification criteria diverge across buyer budgets, installation constraints, and regulatory exposure. Each dimension carries distinct margin implications and supply chain requirements that shape manufacturer positioning.
Product Type:
Buyers in this category separate by price tolerance and performance specification, with premium grades commanding specification in renovation channels while standard grades dominate new construction volume plays.
- High-Pressure Laminates:Constructed through simultaneous application of heat and pressure to multiple resin-impregnated layers, yielding superior density and impact resistance. Demand concentrates in Florida multi-family developments where AC4-AC5 durability ratings satisfy replacement cycle requirements under humidity stress. The manufacturing process requires specialized press equipment that limits supplier base to capital-intensive mills.
- Direct-Apex Laminates:Produced via short-cycle pressing of decorative paper onto substrate without separate overlay lamination, enabling cost-efficient output for volume residential channels. Texas first-time homebuyer renovation activity drives specification in entry-level single-family housing where price compression dominates procurement criteria.
- Premium Laminates:Thicker 12mm and 15mm systems with enhanced moisture barriers and embossed surface replication of reclaimed hardwood aesthetics. California green building code compliance and LEED-adjacent procurement mandates steer specification toward documented low-emission substrates.
- Standard Laminates:Builder-grade 8mm direct-pressure products serving price-sensitive new construction. Southeast U.S. manufacturing concentration supports freight cost efficiency for regional homebuilder accounts.
Standard Laminates lead volumes today; Premium Laminates is gaining share fastest.
Thickness:
Specification in this category tracks installation environment constraints and acoustic performance requirements, with thicker boards capturing moisture-prone applications and elevated subfloor conditions.
- 12mm:Balances structural stability with click-lock installation efficiency. Gulf Coast residential replacement demand favors this thickness for humidity-resistant floating floor systems that tolerate seasonal expansion without adhesive failure.
- 15mm:Maximum residential thickness category with integrated underlayment and superior sound dampening. Texas rental property developers specify these systems for multi-family renovations where tenant noise complaints drive durability investment.
- 8mm:Entry-level specification for cost-optimized new construction. Direct-pressure manufacturing keeps per-square-foot pricing competitive against vinyl alternatives in basement and secondary room applications.
- 10mm:Mid-tier option bridging price-performance requirements. Light commercial foot traffic segments in California retail environments specify this thickness for moderate durability without premium cost escalation.
8mm leads volumes today; 15mm is gaining share fastest.
Installation Type:
Buyer differentiation here centers on skill requirements, subfloor condition tolerance, and reversibility needs, with floating systems capturing DIY renovation while glue-down secures permanent commercial specification.
- Click Lock:Tongue-and-groove edge profiling enables tool-free assembly and disassembly. Florida and Texas residential renovation channels favor this system for first-time homebuyers seeking hardwood aesthetics without professional installation cost.
- Glue Down:Direct adhesive bonding to subfloor delivers maximum dimensional stability in moisture-variable environments. Commercial specification in California retail and hospitality segments prioritizes this method for heavy foot traffic durability.
- Floating:Interlocking planks installed over underlayment without subfloor attachment. Southeast U.S. new construction specifies this method for speed of installation and subfloor imperfection tolerance.
- Nail Down:Traditional fastening method requiring plywood or OSB subfloor. Limited laminate application restricted to specific engineered wood hybrid products in niche renovation segments.
Click Lock leads volumes today; Glue Down is gaining share fastest.
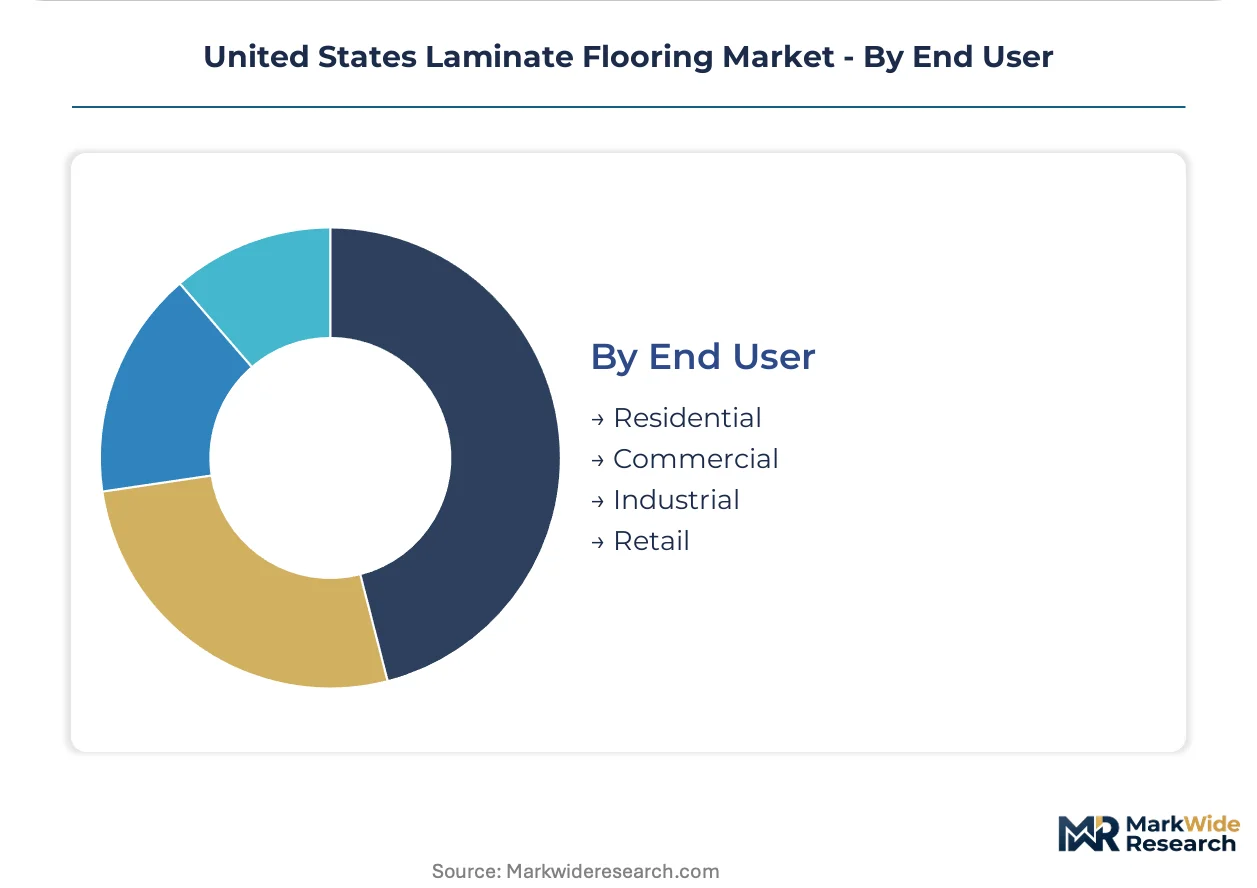
End User:
This category separates by procurement sophistication, with residential buyers prioritizing aesthetics and cost while commercial and industrial accounts impose certification and lifecycle documentation requirements.
- Residential:Single-family and multi-family housing accounts driving volume demand. Texas and Florida renovation activity concentrates specification in click-lock systems among first-time homebuyers trading up from vinyl flooring.
- Commercial:Office, hospitality, and retail environments requiring AC4-AC5 durability ratings and EPD documentation. California municipal green building codes and corporate sustainability procurement mandates shape specification protocols.
- Retail:Flooring showrooms and home improvement channels serving as specification influencers. Direct-to-contractor distribution networks are displacing traditional distributor influence in this segment.
- Industrial:Light manufacturing and warehouse applications with heavy static and rolling load requirements. Limited laminate penetration due to vinyl and polished concrete substitution in moisture-prone environments.
Residential leads volumes today; Commercial is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic mills exploit regulatory compliance gaps to consolidate substrate sourcing advantages, while coastal states impose emission-grade mandates that redirect procurement flows toward certified supply bases. Regional differentiation sharpens as humidity-resistant product specifications diverge across climatic zones.
Southeast
Florida and Georgia anchor laminate manufacturing concentration, with humidity-resistant click-lock systems capturing replacement demand from vinyl-sensitive homeowners. EPA TSCA Title VI enforcement tightens fiberboard sourcing documentation, disqualifying uncertified overseas suppliers. Dalton, Georgia manufacturing clusters sustain cost leadership through captive resin operations and direct-to-contractor distribution networks.
Southwest
Texas first-time homebuyer renovation activity drives specification of entry-level click-lock laminates in Houston and Dallas-Fort Worth metro areas. California Air Resources Board ATCM 93120 standards function as de facto national benchmarks, streamlining supplier certification for products distributed into Western markets. San Antonio manufacturing nodes expand capacity to serve regional homebuilder accounts with freight cost efficiency.
West Coast
California green building codes and municipal sustainability procurement mandates reshape specification protocols in Los Angeles and San Francisco Bay Area construction. EPD documentation requirements and LEED-adjacent certifications concentrate demand among documented low-emission substrate producers. Pacific Northwest moisture-barrier product uptake accelerates in Seattle and Portland residential renovation channels.
Midwest
Chicago and Detroit metropolitan areas sustain builder-grade volume demand for standard thickness laminates in multi-family housing developments. OSHA workplace exposure rules shape installation material disclosures and contractor qualification requirements. Ohio and Indiana distribution hubs manage freight cost asymmetries from Southeast manufacturing concentration.
Northeast
New York and Boston corridor procurement prioritizes premium thickness categories with enhanced acoustic performance for multi-family renovations. State-level PFAS restriction anticipation creates specification uncertainty, favoring mills with pre-certified fluorinated compound-free formulations. Philadelphia and Baltimore channels intermediate between Southeast supply bases and coastal premium demand.
United States Laminate Flooring Market Competitive Landscape
Southeast U.S. producers anchor the cost-leadership tier; European specialists hold premium positioning through technology licensing arrangements. Market structure consolidates around capital-intensive mills with captive resin operations and direct distribution networks, compressing mid-tier players toward specialty niche differentiation. Three archetypes dominate: vertically integrated domestic manufacturers, technology-licensed European entrants, and specialty embossing equipment operators. Competitive dynamics center on supply chain requalification speed and direct-to-contractor channel capture.
Among domestic integrated manufacturers, Mohawk Industries Inc and Shaw Industries Group Inc exemplify scale-driven archetypes with Southeast manufacturing concentration and captive supply chain control. Mannington Mills Inc occupies specialty differentiation positioning through precision surface replication capabilities. These three companies represent the competitive tension between volume-cost efficiency and premium aesthetic technology that defines current market segmentation.
| Leading Market Players |
|---|
| Mohawk Industries Inc |
| Shaw Industries Group Inc |
| Armstrong Flooring Inc |
| Mannington Mills Inc |
| Tarkett SA |
| Pergo |
| Quick-Step |
| Kronospan Limited |
| Swiss Krono Group |
| Others |
Value Network & Pricing Analysis
First-time homebuyer procurement in Texas and Florida is forcing Southeast mills to absorb resin cost volatility while maintaining click-lock price points, compressing margin buffers and accelerating direct-to-contractor channel bypass.
Pricing Analysis
Distributor margin layers separate premium from standard laminate tiers, with builder-grade 8mm products carrying thinner markups than 15mm moisture-barrier systems. Price differentiation rests on CARB-ATCM certification grade and captive resin integration. Cost compression in entry-level direct-pressure laminates is intensifying because pulp and melamine resin inputs fluctuate with energy markets. National homebuilders exhibit highest price sensitivity; California green-code-compliant developers show lowest.
Supply Chain Analysis
High-density fiberboard supply rests on Georgia, Alabama, and Tennessee mill clusters with captive resin operations. Raw material dependencies include formaldehyde-based adhesives, decorative paper from South Carolina printers, and aluminum oxide abrasives. Single-source vulnerability concentrates in certified substrate qualification under EPA TSCA Title VI. Distribution runs through Dalton, Georgia manufacturing bases to regional homebuilder accounts and direct contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States laminate flooring market represents a late-cycle quality story as California green building codes and LEED-adjacent procurement displace price-primary specification toward documented low-emission substrates.
For Market Incumbents: Anchor cost leadership through captive resin operations in Dalton, Georgia while accelerating PFAS-free substrate certification ahead of anticipated Northeast state restrictions. Luxury vinyl tile waterproofing advances threaten moisture-prone commercial segments; defend through 15mm click-lock moisture-barrier R&D and direct-to-contractor distribution lock-in. For New Entrants and Emerging Players: West Coast multi-family developers remain underserved by mills with pre-certified EPD documentation and transparent chain-of-custody records. Pacific Northwest humidity-resistant product gaps and Northeast PFAS-compliant substrate shortages offer penetrable entry points. Lead with specification-influencer education on emission-grade differentiation rather than price competition. For Investors and Strategic Acquirers: Asymmetric upside sits with specialty embossing equipment operators capable of reclaimed hardwood aesthetic replication at mid-tier scale. Long-term viability favors mills with backward integration into resin production and direct distribution infrastructure. Watch EPA enforcement window narrowing on overseas substrate suppliers as inflection indicator for domestic capacity valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| PFAS-Free Substrate Certification | Anticipated Northeast state restrictions reward pre-certified mills with specification priority in municipal procurement. |
| Direct-to-Contractor Distribution | Bypassing traditional distributor tiers captures margin and influences specification in Texas and Florida multi-family segments. |
| Specialty Embossing Equipment Investment | Precision press capabilities for reclaimed hardwood replication command premium positioning in California renovation channels. |
| Captive Resin Operation Expansion | Backward integration into adhesive production insulates margin stability against pulp and energy input volatility. |
| EPD Documentation Portfolio Development | Lifecycle-assessed product credentials satisfy LEED-adjacent mandates in Los Angeles and San Francisco Bay Area construction. |
Research Methodology
Coverage spans Southeast, Southwest, West Coast, Midwest, and Northeast regions, with primary inputs from each. The analysis combines interviews with flooring mill operations directors, national homebuilder procurement managers, California multi-family developer sustainability officers, and Dalton, Georgia distribution channel heads with secondary validation from EPA TSCA Title VI filings, CARB-ATCM certification databases, SEC 10-K disclosures from publicly traded flooring manufacturers, and U.S. Census residential construction permits. Bottom-up volume triangulation across product thickness and installation type categories reconciles with top-down market value estimates.
Granularity-level modeling disaggregates volume and value across product type, thickness tier, installation method, and end-user segment throughout the forecast period. CAGRs derive from segment-level growth rate synthesis rather than single-point extrapolation. Industry-specific forecast inputs include Texas and Florida residential permit trajectories, EPA enforcement intensity assumptions, and luxury vinyl tile substitution elasticity in moisture-prone applications.
Underlying measurement precision varies by segment; premium laminate and commercial end-use categories carry tighter precision than standard builder-grade volume estimates due to certification documentation availability. Forecasts reflect assumptions on regulatory enforcement timing and resin cost normalization that could revise if PFAS restrictions accelerate or pulp markets destabilize. A small set of named triggers—EPA substrate sourcing disqualifications, Northeast PFAS legislation passage, and Southeast weather-related mill disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Europe Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Germany Floor Covering Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
Wood Flooring Market