
 Netherlands Home Furniture Market | 2026-2036
Netherlands Home Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Home Furniture Market Foresight
Online-to-offline furniture retail is rewriting how Dutch households discover and purchase home furnishings. IKEA leverages its click-and-collect network to sustain dominance across the Randstad urban corridor. Beliani competes through pure-play digital distribution, while JYSK anchors market presence with value-positioned stores in secondary cities like Groningen and Eindhoven.
Netherlands home furniture encompasses movable domestic fixtures crafted from wood, metal, plastic, or upholstered composites, designed for residential living, dining, and storage functions with dimensional tolerances typically ranging from compact 120-centimeter apartment sofas to extendable 240-centimeter dining tables. Sofas and upholstered seating command the widest margin pools due to fabric customization and replacement cycle frequency, while Scandinavian-style tables and cabinets attract the fastest-growing demand cohort among millennial first-time buyers in Utrecht and The Hague. Wood material segments retain structural volume leadership, though metal-framed industrial-style products are gaining share in loft conversions across North Holland.
The Dutch Economic Affairs ministry enforces EU Timber Regulation due diligence, while the Netherlands Food and Consumer Product Safety Authority monitors chemical compliance in upholstery foams and surface coatings under REACH frameworks. These standards elevate compliance costs for imported Asian components but simultaneously create market access advantages for European-certified domestic producers. Stakeholders must monitor whether forthcoming EU Ecodesign requirements will mandate recycled content thresholds that reshape material sourcing strategies for mid-range cabinet and table manufacturers.
Market Dynamics
The EU Green Deal's timber traceability mandates are forcing Dutch retailers to requalify entire supplier networks, compressing margins for non-certified Asian imports while elevating Baltic and domestic wood processors.
Growth Catalysts
- REACH chemical compliance:Upholstery foam certification under ECHA frameworks is locking out uncertified competitors and securing shelf space for compliant Dutch manufacturers in Randstad retail corridors.
- Modular seating systems:Space-efficient configurations are capturing Amsterdam and Rotterdam apartment dwellers facing sub-50-square-meter living constraints.
- Hybrid online-showroom channels:Click-and-collect fulfillment is collapsing discovery-to-purchase timelines for millennial first-time buyers in Utrecht and The Hague.
Market Restraints
- Asian component cost volatility:Container freight swings and hardwood veneer shortages from Southeast Asian mills are destabilizing landed costs for mid-range cabinet producers.
- EU Timber Regulation due diligence:The Dutch Economic Affairs ministry enforcement is extending supplier audit timelines by 40-60 days, freezing working capital for import-dependent retailers.
- Metal-frame substitution:Industrial-style loft furniture using steel tubing is displacing wood-dominant SKUs in North Holland conversions, eroding traditional carpentry volumes.
Strategic Opportunities
- Ecodesign recycled content mandates:Forthcoming EU thresholds for post-consumer wood fiber will advantage domestic particleboard producers with established circular sourcing.
- Secondary city retail penetration:Groningen and Eindhoven exhibit underdeveloped Scandinavian-style dining set saturation relative to Randstad density.
- Digital-native pure-play expansion:Direct-to-consumer logistics platforms are bypassing legacy showroom overhead for upholstered sofa customization at 15-20 percent price advantages.
Industry Challenges
- Certified upholstery foam scarcity:REACH-compliant chemical supply is concentrating among three European compounders, creating allocation bottlenecks for mid-size Dutch seating manufacturers.
- Legacy ERP integration:Timber traceability documentation requirements are crashing against decades-old inventory systems at family-owned regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Home Furniture Market |
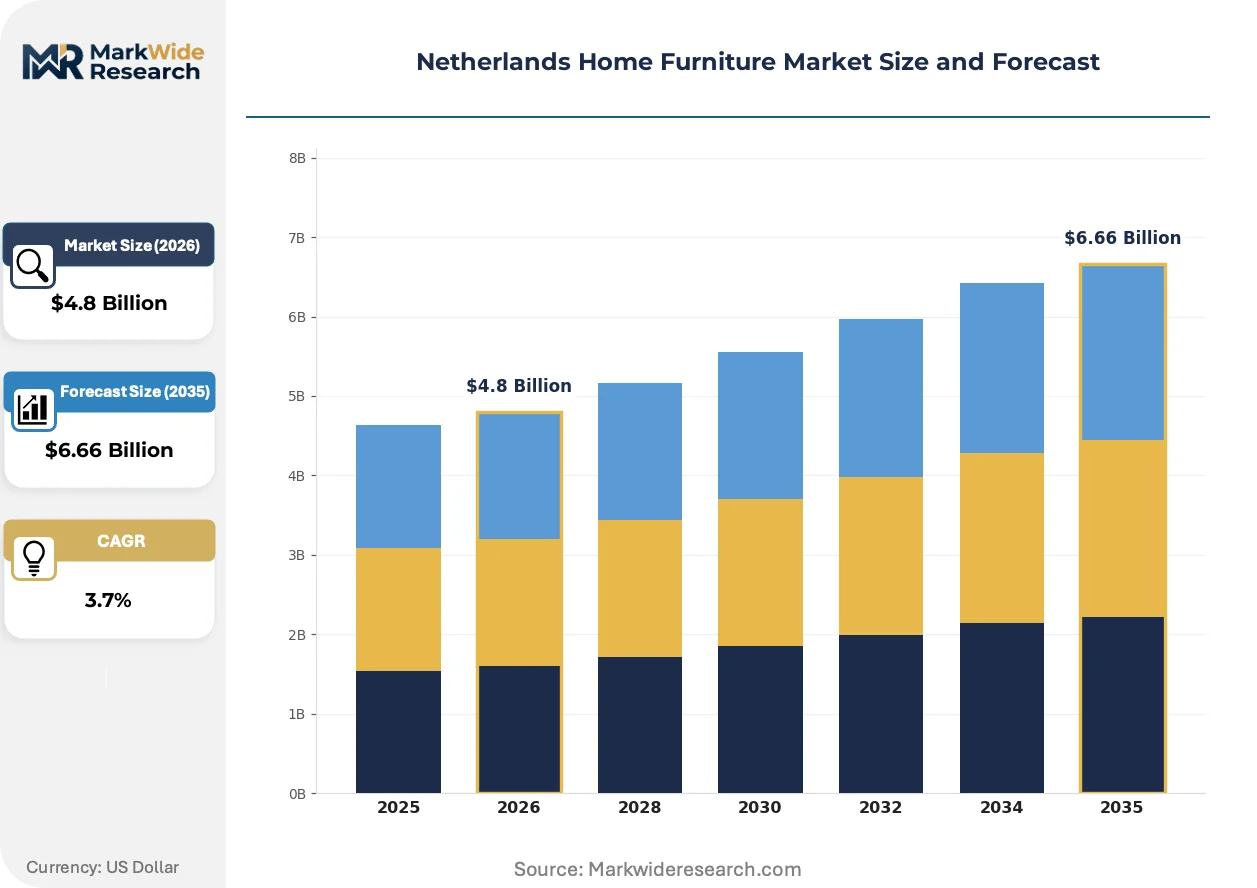
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Chairs, Tables, Cabinets Material: Wood, Metal, Plastic, Upholstered Style: Modern, Traditional, Scandinavian, Rustic Price Tier: Luxury, Mid-Range, Budget, Discount |
| Companies Covered | Leen Bakker, Meubella, IKEA, Made by Valk, Eichholtz, XXXLutz, Beliani, Zara Home, JYSK, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Home Furniture Market Shifts & Advancements
Three intersecting forces are compressing traditional furniture retail cycles: digital configuration tools collapsing customization lead times, regulatory chemistry mandates filtering supplier bases, and urban spatial constraints redefining dimensional specifications.
Parametric design software paired with CNC fabrication is rendering obsolete the six-to-eight-week sofa customization timelines that once defined premium positioning. Amsterdam-based interior designers and Rotterdam property developers are specifying these systems for 48-hour fabric-to-frame turnaround. The compression is eliminating inventory-holding advantages of legacy wholesalers and transferring margin capture to digitally integrated manufacturers.
EU Green Deal timber traceability requirements are reshaping procurement documentation burdens for Dutch retailers. The Netherlands Food and Consumer Product Safety Authority now demands chain-of-custody certificates at port of entry, rejecting containerized Asian hardwood shipments lacking FSC or PEFC verification. Upholstered seating importers are responding by dual-sourcing Baltic birch frames to maintain stock continuity.
Apartment-dwelling millennials in Utrecht and The Hague are abandoning traditional furniture showrooms for augmented reality visualization tools. These buyers are configuring modular sectional dimensions through smartphone apps before scheduling 30-minute warehouse appointments for tactile verification. The behavior is collapsing the discovery phase into digital channels while compressing final purchase decisions to single-site visits.
Netherlands Home Furniture Market Segmentation
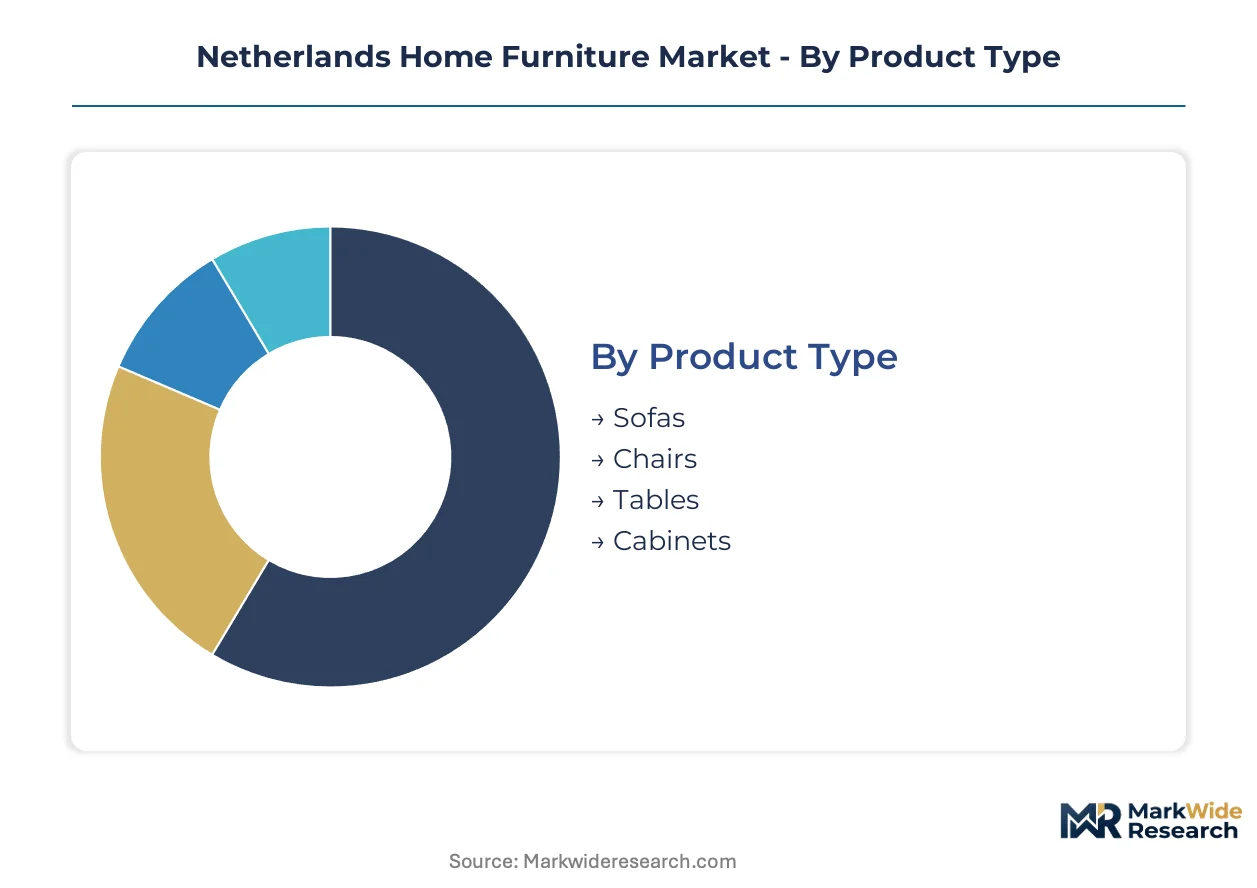
Dutch retailers configure inventory around apartment dimensions and certification requirements rather than broad style categories. Segmentation reveals where margin pools concentrate and where regulatory compliance creates supplier lockouts.
Product Type:
After-sales service intensity varies dramatically across furniture categories, with upholstered items demanding fabric replacement programs and frame warranty fulfillment while hard furniture requires minimal post-purchase support.
- Sofas:Multi-component assemblies combining hardwood frames, steel suspension systems, and polyurethane foam cushioning with fabric or leather upholstery. Amsterdam and Rotterdam apartment dwellers are specifying compact 180-220 centimeter widths with modular sectionals for sub-50-square-meter living rooms, driven by space constraints and frequent relocation patterns among young professionals.
- Chairs:Dining, accent, and recliner configurations spanning wood, metal, and upholstered constructions with ergonomic adjustability features. Demand concentrates in Utrecht and The Hague among millennial first-time buyers purchasing Scandinavian-style dining sets through hybrid online-showroom channels, constrained by REACH chemical compliance requirements for foam components.
- Tables:Dining, coffee, and console surfaces in extendable and fixed dimensions.
- Cabinets:Storage and display units with shelving systems and enclosed compartments.
By volume, Sofas leads. By growth pace, Chairs is ahead.
Material:
Cost tier stratification separates certified European timber from imported alternatives, with compliance documentation adding 12-18 percent to landed costs for non-EU sourcing.
- Wood:Solid hardwoods, engineered particleboard, and plywood substrates with veneer finishes. North Holland loft conversions are specifying reclaimed oak and FSC-certified birch from Baltic processors to satisfy EU Timber Regulation chain-of-custody requirements enforced at Dutch ports.
- Metal:Steel tubing, aluminum extrusions, and powder-coated iron frames. Rotterdam industrial-style furniture producers are displacing wood-dominant SKUs with metal-framed shelving and seating for warehouse-to-residential conversions, climbing the fastest among material categories.
- Plastic:Polypropylene, polycarbonate, and recycled polymer constructions.
- Upholstered:Fabric, leather, and synthetic textile coverings over foam and fiberfill.
By installed base, Wood dominates. By substitution momentum, Metal is expanding most quickly.
Style:
Customer type alignment shows millennials clustering in minimalist aesthetics while established households retain traditional preferences, creating distinct inventory strategies for Randstad versus secondary city retailers.
- Modern:Clean lines, neutral palettes, and functional minimalism with hidden hardware. Groningen and Eindhoven furniture retailers are reporting inventory turnover gaps versus Randstad density, presenting penetration opportunities for direct-to-consumer platforms bypassing legacy showroom overhead.
- Scandinavian:Light woods, tapered legs, and hygge-inspired comfort prioritization. Utrecht and The Hague first-time buyers are driving steepest expansion trajectory for this segment through augmented reality visualization tools that collapse discovery-to-purchase timelines.
- Traditional:Ornate detailing, dark finishes, and classical proportioning.
- Rustic:Distressed surfaces, reclaimed materials, and farmhouse-inspired silhouettes.
By revenue concentration, Modern leads. By generational capture, Scandinavian is gaining share fastest.
Price Tier:
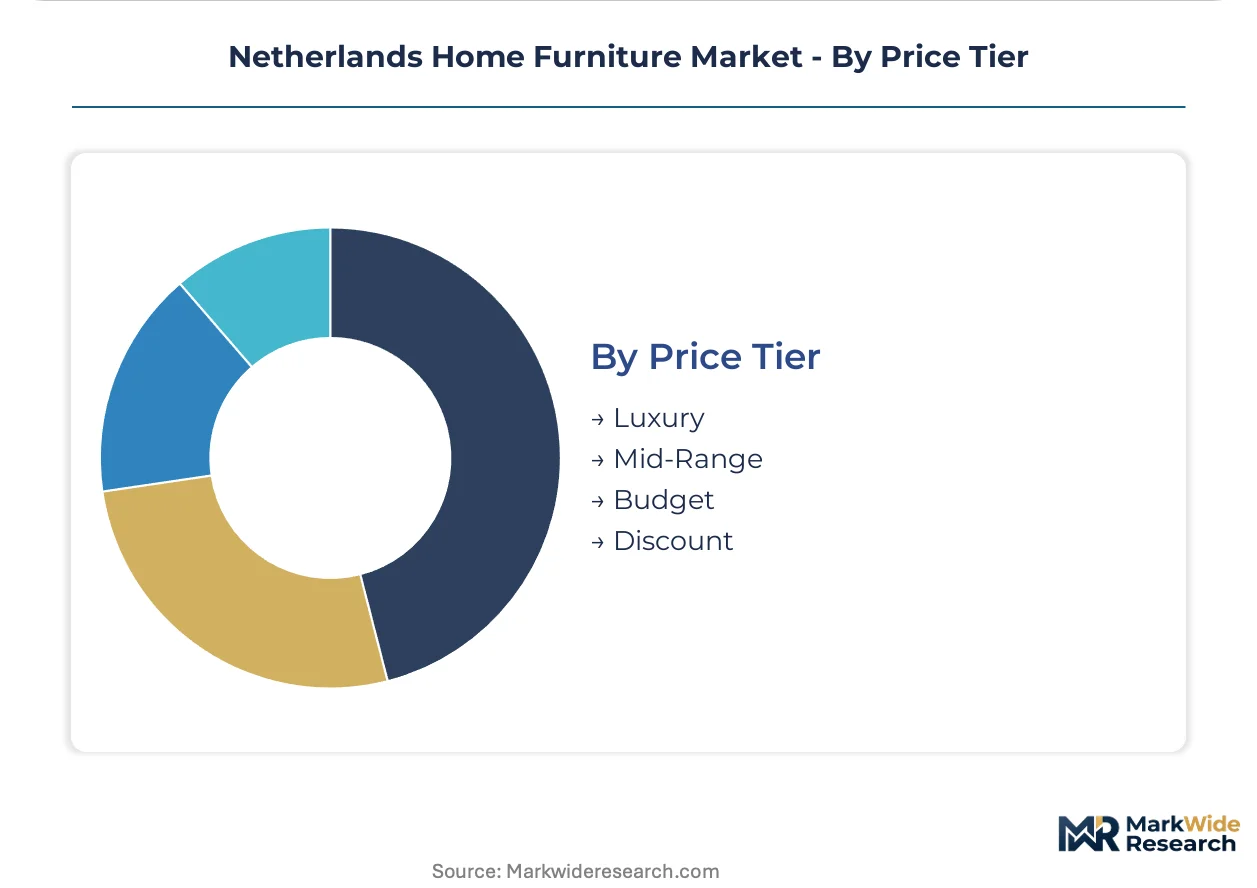
Margin structure inverts between tiers, with mid-range producers capturing widest spreads through customization premiums while discount operators compete on logistics velocity.
- Mid-Range:Positioned between mass-market and designer labels with material quality signaling and limited configuration options. Dutch family-owned regional distributors are struggling with legacy ERP integration against timber traceability documentation requirements, freezing working capital and compressing margin capture.
- Luxury:Bespoke craftsmanship, premium materials, and designer attribution with extended lead times.
- Budget:Standardized dimensions, flat-pack distribution, and rapid inventory turnover.
- Discount:Promotional pricing, closeout sourcing, and minimal service attachment.
By unit velocity, Budget leads. By margin per transaction, Mid-Range is ahead.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Randstad furniture retailers command 15-20 percent price premiums over Brabant and Northern Netherlands distributors for identical Scandinavian-style dining sets, reflecting showroom density asymmetries and logistics cost differentials across Dutch provinces.
Randstad
Amsterdam and Rotterdam apartment dwellers are driving demand for sub-180-centimeter modular sofas configured through augmented reality tools. The Netherlands Food and Consumer Product Safety Authority enforces REACH chemical compliance on upholstery foams entering Rotterdam port. Utrecht and The Hague millennial buyers are collapsing purchase timelines through hybrid online-showroom channels with 48-hour warehouse appointments.
Brabant
Eindhoven furniture retailers report inventory turnover gaps versus Randstad density for Scandinavian-style dining sets. EU Timber Regulation chain-of-custody requirements enforced by the Dutch Economic Affairs ministry extend supplier audit timelines for import-dependent distributors. Tilburg and Breda showrooms are experiencing working capital pressure from documentation burdens on Asian hardwood shipments.
Eindhoven Region
Tech-sector professionals are specifying metal-framed industrial furniture for loft conversions in former Philips industrial zones. REACH-compliant upholstery foam scarcity is concentrating supply among three European compounders, creating allocation bottlenecks for regional seating manufacturers. Design Academy Eindhoven graduates are launching direct-to-consumer platforms bypassing legacy showroom overhead.
Northern Netherlands
Groningen retailers exhibit underdeveloped saturation for space-efficient modular seating relative to Randstad penetration. The Dutch Economic Affairs ministry timber traceability mandates are freezing working capital for family-owned regional distributors with decades-old ERP systems. Leeuwarden and Assen furniture merchants are dual-sourcing Baltic birch frames to maintain stock continuity amid Asian certification rejections.
North Holland
Haarlem and Alkmaar loft conversions are displacing wood-dominant SKUs with steel-tubing industrial shelving systems. EU Green Deal timber traceability requirements are elevating Baltic and domestic wood processors over non-certified Asian imports. IJmond harbor logistics clusters are reshaping landed cost calculations for mid-range cabinet producers facing container freight volatility.
Netherlands Home Furniture Market Competitive Landscape
Pan-European mass-market operators and domestic value-positioned chains split the Netherlands home furniture market, with digital-native pure-plays carving a third vector. The vendor base concentrates around three strategic tiers: scale-driven flat-pack distributors with click-and-collect networks, mid-market family-owned regional distributors with legacy showroom footprints, and direct-to-consumer logistics platforms. M&A activity targets ERP modernization capabilities, while capacity expansion concentrates in Baltic wood processing to satisfy EU Timber Regulation compliance.
Within the mass-market tier, IKEA anchors Randstad retail corridors through integrated click-and-collect fulfillment. JYSK occupies a position among value-positioned Scandinavian-format chains with secondary city penetration in Groningen and Eindhoven. Beliani exemplifies the digital-native archetype through pure-play distribution without showroom overhead. These three players represent distinct strategic responses to hybrid online-offline demand patterns and regulatory documentation burdens reshaping supplier qualification.
| Leading Market Players |
|---|
| Leen Bakker |
| Meubella |
| IKEA |
| Made by Valk |
| Eichholtz |
| XXXLutz |
| Beliani |
| Zara Home |
| JYSK |
| Others |
Supply & Pricing Matrix
Baltic wood processing clusters around Riga and Tallinn are consolidating frame supply leverage for Dutch upholstered seating manufacturers, translating certification scarcity into 12-18 percent cost premiums for REACH-compliant foam configurations versus uncertified Asian alternatives.
Pricing Analysis
Configured-to-order pricing for modular sofas commands 15-20 percent premiums over standard SKUs, reflecting fabric customization and parametric design software investments. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified Baltic birch frames from particleboard alternatives and promotional flat-pack imports. Pricing pressure stems from container freight volatility destabilizing landed costs for mid-range cabinet producers sourcing Southeast Asian hardwood veneers. Budget-tier buyers in Groningen and Eindhoven exhibit highest price sensitivity, while Randstad millennials purchasing through augmented reality channels accept customization premiums.
Supply Chain Analysis
Tariff exposure between Vietnam and the Netherlands compounds EU Timber Regulation documentation burdens, extending supplier audit timelines for import-dependent retailers. Raw material flows draw from Baltic birch processors, Chinese steel tubing mills, and European polyurethane compounders concentrated in Germany and Belgium. Single-source vulnerability concentrates in REACH-compliant upholstery foam supply, where three European compounders control allocation to mid-size Dutch seating manufacturers. Distribution runs through hybrid online-showroom channels with click-and-collect fulfillment collapsing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across secondary city retail corridors and digital-native distribution creates niche capture opportunities for specialized players, as millennial demand for Scandinavian-style modular seating outpaces legacy showroom capacity in Groningen and Eindhoven.
For Market Incumbents: Insulate margin pools by dual-sourcing Baltic birch frames to maintain stock continuity amid Asian certification rejections at Rotterdam port. Invest in ERP modernization to collapse timber traceability documentation timelines that currently freeze working capital for family-owned regional distributors. Prioritize click-and-collect infrastructure density across Randstad urban corridors where IKEA anchors competitive positioning. For New Entrants and Emerging Players: Pursue direct-to-consumer logistics platforms targeting Eindhoven tech-sector professionals with metal-framed industrial furniture for loft conversions, bypassing legacy showroom overhead at 15-20 percent price advantages. Penetrate underdeveloped Scandinavian-style dining set saturation in Groningen and Northern Netherlands through augmented reality visualization tools that collapse discovery-to-purchase timelines for first-time buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors digitally integrated manufacturers with parametric design software and CNC fabrication capabilities over inventory-holding legacy wholesalers. Long-term viability across the analysis window hinges on circular sourcing infrastructure for forthcoming EU Ecodesign recycled content mandates. Monitor allocation bottlenecks in REACH-compliant upholstery foam supply as inflection indicator for mid-size seating manufacturer distress.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Modernization for Traceability | Collapses supplier audit timelines frozen by decades-old inventory systems at family-owned distributors. |
| Dual-Source Baltic Birch Procurement | Maintains stock continuity for Dutch retailers facing Asian hardwood certification rejections at port. |
| Direct-to-Consumer Platform Launch | Bypasses legacy showroom overhead in Eindhoven and Groningen through augmented reality visualization. |
| Circular Sourcing Infrastructure Buildout | Positions domestic particleboard producers for EU Ecodesign recycled content mandates. |
| Click-and-Collect Network Expansion | Captures Randstad millennial buyers collapsing purchase timelines through hybrid online-showroom channels. |
Research Methodology
The analysis maps upholstered seating, hard furniture, and storage systems segments, each validated through procurement managers at Dutch retailers, supply chain directors at Baltic wood processors, and compliance officers at foam compounders. Primary interviews with category buyers at Randstad furniture chains, logistics specialists at IJmond harbor clusters, and regulatory affairs leads at Netherlands Food and Consumer Product Safety Authority combined with secondary validation through EU Timber Regulation filings, REACH compliance databases, and customs trade records. Bottom-up demand modeling and top-down supply capacity estimates triangulate volume and value outputs.
Assumptions held fixed include EU Green Deal timber traceability enforcement intensity and REACH chemical compliance scope; varied parameters encompass container freight rate trajectories and millennial channel preference evolution. Segmentation dimensions modeled span product type, material certification tier, style archetype, and price positioning across the projection horizon. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and substitution momentum in metal-framed industrial furniture.
The forecast holds incumbent behavior within observed patterns; aggressive moves by digitally integrated pure-plays or Baltic wood processor consolidators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Furniture
Indonesia Home Furniture Market
Furniture
Upholstered Furniture Market
Furniture
Middle East and Africa Free Standing Electrical Height-Adjustable Tables Market
Furniture
China Furniture Market
Furniture
Furniture and Home Furnishing Store Market
Furniture
UK Sustainable Home Furniture Market
Furniture
Ergonomic Chair Market
Furniture
Furniture Laminate Market
Furniture
Global Home Furniture Market
Furniture
Eco-Friendly Furniture Market
Furniture
Medium-Density Fibreboard (MDF) Market
Furniture
Italy Furniture Retail Market
Furniture
Global Furniture Fittings Market
Furniture
Portering Chair Market
Furniture
GCC Smart Furniture Market
Furniture
Bounding Table Market