
 Global Flooring Market | 2026-2036
Global Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flooring Market Analysis
Premium-performance specification tiers is unwinding legacy commodity positioning across the flooring industry. Mohawk Industries leverages captive nylon fiber production to control input costs across carpet and resilient categories. Shaw Industries Group anchors its position through extensive extrusion capacity in luxury vinyl tile. Tarkett SA differentiates via integrated linoleum and rubber flooring expertise with strong European specification relationships.
Flooring comprises finished surface materials installed over subfloors to provide wear resistance, aesthetics, and functional performance in built environments. Modern resilient flooring achieves impact sound ratings below 17 decibels through multi-layer constructions with cork or foam backings. Vinyl and laminate material types currently occupy the fastest-expanding margin pools as waterproof formulations displace traditional hardwood in moisture-prone residential and commercial zones. Carpet retains institutional dominance in healthcare and education segments where acoustic performance and underfoot safety command specification priority.
EPA formaldehyde emission standards under TSCA Title VI constrain composite wood flooring imports into the United States. REACH restrictions on phthalate plasticizers and the EU Green Deal's carbon footprint disclosure rules are redirecting European formulation strategies toward bio-based plasticizers and recycled PVC feedstocks. Stakeholders must monitor evolving EPD requirements and embodied carbon thresholds as specification gatekeepers increasingly weight lifecycle metrics alongside installed cost in procurement decisions.
Market Dynamics
Waterproof vinyl plank systems are compressing specification cycles across residential and commercial verticals, forcing legacy hardwood and carpet manufacturers to reconfigure product portfolios around moisture resistance and embodied carbon metrics.
Growth Catalysts
- Suburban renovation intensity:North American homeowners are stripping out aging carpet and solid hardwood in favor of click-lock vinyl systems that tolerate basement moisture and pet traffic.
- REACH phthalate restrictions:ECHA's tightening plasticizer rules are accelerating European adoption of bio-based polyurethane binders and recycled PVC feedstocks in resilient flooring formulations.
- Commercial retrofit compression:China's tier-one cities are shortening office and retail lease cycles, driving faster flooring replacement schedules in Shanghai, Beijing, and Shenzhen.
Market Restraints
- Petrochemical input volatility:PVC resin and plasticizer costs fluctuate with crude oil and chlorine markets, squeezing margin predictability for vinyl flooring producers.
- Carbon disclosure burdens:EU Green Deal embodied carbon thresholds and emerging EPD mandates are raising compliance costs for manufacturers without lifecycle assessment infrastructure.
- Acoustic performance ceilings:Thin-profile luxury vinyl tile struggles to match carpet's impact sound ratings below 17 decibels in healthcare and education specifications.
Strategic Opportunities
- India's underpenetrated resilient segment:BIS standards evolution and urban housing stock expansion create whitespace for waterproof laminate and SPC flooring in Mumbai and Delhi NCR.
- Healthcare specification pivot:Infection control protocols are opening demand for seamless sheet vinyl and rubber flooring with heat-welded seams in hospital renovation programs.
- Digital specification platforms:Architect and designer procurement is migrating to BIM-integrated product libraries, enabling direct-to-specifier bypass of traditional distribution.
Industry Challenges
- Cross-functional talent scarcity:Formulation chemistry expertise in bio-based binders and recycled content engineering remains concentrated among a narrow cohort of European and Japanese specialists.
- Legacy system integration friction:ERP and inventory systems at established distributors resist real-time synchronization with manufacturer EPD databases and carbon accounting platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flooring Market |
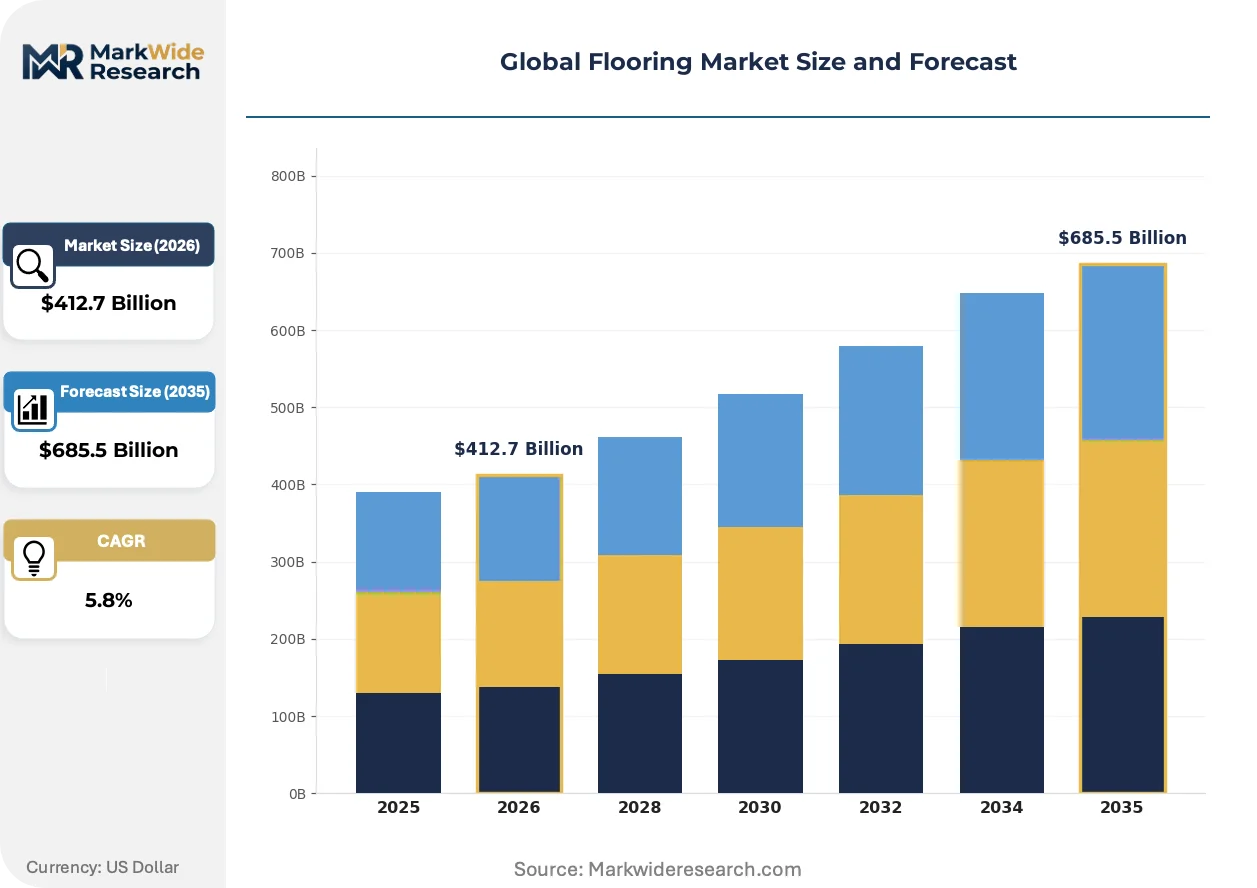
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $685.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Hardwood, Laminate, Vinyl, Carpet End User: Residential, Commercial, Industrial, Institutional Installation Method: Glue-Down, Floating, Nail-Down, Click-Lock Design Style: Traditional, Modern, Rustic, Contemporary |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Tarkett SA, Armstrong Flooring, Inc., Forbo Flooring Systems, Interface, Inc., Gerflor Group, Beaulieu International Group, Mannington Mills, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flooring Market Emerging Trajectories
Specification authority is migrating from distributors to architect-specifier platforms, while material innovation splits performance tiers and regulatory pressure forces disclosure transparency.
Multi-layer rigid core flooring is bifurcating the residential market between stone-polymer composite and wood-plastic composite constructions. Home improvement retailers are allocating shelf space disproportionately to SPC for its superior dimensional stability in humid climates. This material split is compressing mid-range laminate demand while expanding premium-margin waterproof categories.
EPA TSCA Title VI formaldehyde emission standards are constraining composite wood flooring imports into the United States. Manufacturers without certified supply chains face exclusion from federal procurement and large-scale residential development projects. The regulation is accelerating domestic production of CARB Phase 2-compliant engineered hardwood and redirecting import sourcing toward Southeast Asian panel producers with third-party certification.
Building information modeling is rewiring how architects evaluate flooring alternatives during schematic design. Specifiers now embed acoustic performance, carbon footprint, and maintenance cost data directly into digital material libraries, bypassing traditional sample-based selection. This behavioral shift is most pronounced in German and Dutch commercial construction markets where public procurement mandates digital submission.
Global Flooring Market Segmentation
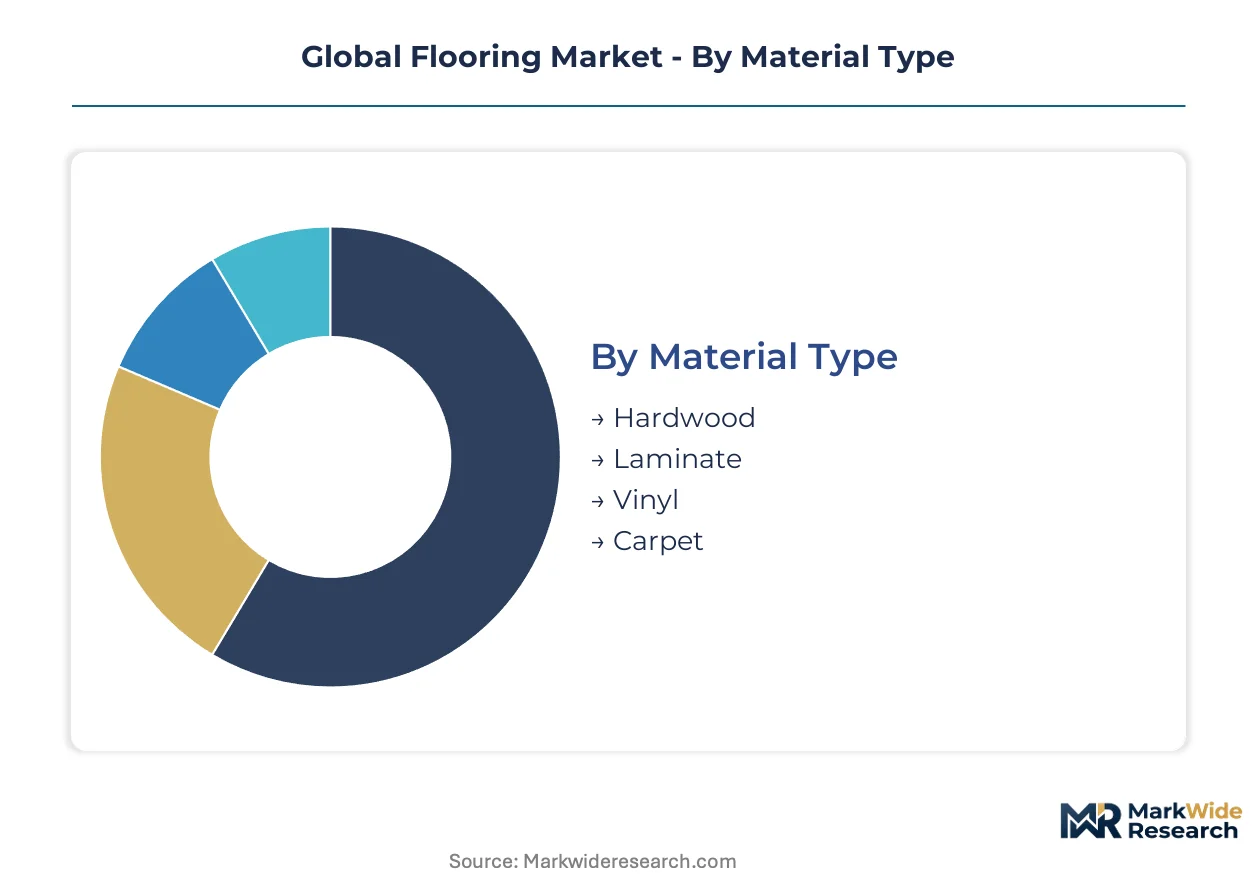
Flooring segmentation reveals divergent supply chain configurations across material categories. Export intensity varies sharply between commodity hardwood and engineered vinyl systems.
Material Type:
Vinyl and laminate formulations dominate cross-border trade flows, while hardwood and carpet production clusters closer to end markets.
- Vinyl:Multi-layer constructions with SPC or WPC rigid cores achieve waterproof performance through calcium carbonate-polymer matrices. Demand concentrates in China's tier-one cities where commercial retrofit cycles compress replacement schedules. REACH phthalate restrictions redirect European formulation toward bio-based plasticizers.
- Carpet:Tufted and woven constructions using nylon, polyester, or wool face fibers deliver acoustic ratings below 17 decibels. Healthcare and education specifications in the United States and Germany retain carpet dominance where underfoot safety commands priority. Mohawk's captive nylon fiber production controls input costs across premium tiers.
- Hardwood:Solid and engineered plank systems face EPA TSCA Title VI formaldehyde constraints on composite imports.
- Laminate:HDF core boards with decorative paper overlays occupy mid-range residential positioning in European and North American markets.
Vinyl holds the largest share; momentum sits with waterproof rigid core formulations.
End User:
Margin structure separates project-scale commercial procurement from fragmented residential decision-making.
- Commercial:Office, retail, and hospitality specifications demand 10-20 year wear warranties and EPD documentation. Procurement concentrates through architect-specifier platforms in Germany and the Netherlands where BIM mandates accelerate digital selection.
- Residential:Single-family and multi-family renovation drives click-lock vinyl adoption in suburban United States and Canadian markets. Home improvement retailers allocate disproportionate shelf space to SPC systems for basement moisture tolerance.
- Industrial:Manufacturing and warehouse environments specify heavy-duty rubber or polished concrete overlays.
- Institutional:Healthcare infection control protocols favor seamless sheet vinyl with heat-welded seams in hospital renovation programs across France and Japan.
Residential commands volume leadership; institutional specifications offer the steepest expansion trajectory for certified antimicrobial systems.
Installation Method:
Labor cost differentials between developed and emerging markets favor floating systems over adhesive-dependent alternatives.
- Click-Lock:Mechanical joining systems enable DIY installation and rapid commercial deployment without subfloor preparation. Floating configurations dominate waterproof vinyl plank distribution in Australia and the United Kingdom.
- Glue-Down:Full-spread adhesive application delivers dimensional stability for sheet vinyl and carpet tile in high-traffic commercial environments. Specification persists in German healthcare and education sectors where acoustic performance thresholds apply.
- Floating:Interlocking plank systems with attached underlayment compress installation timeframes in residential renovation.
- Nail-Down:Traditional hardwood fastening requires skilled carpentry and limits application to wood subfloors.
Glue-down retains commercial specification authority; click-lock gains share fastest in residential channels.
Design Style:
Aesthetic segmentation maps to regional construction traditions and generational renovation preferences.
- Modern:Clean lines, wide planks, and matte finishes align with minimalist interiors in Scandinavian and Japanese markets. Large-format porcelain-look vinyl tiles specify into Dutch and Belgian commercial projects.
- Rustic:Hand-scraped textures and distressed wood visuals satisfy farmhouse and industrial-loft aesthetics in Texas, Tennessee, and Alberta residential construction.
- Traditional:Narrow plank dimensions and classic oak or maple species persist in New England and Mid-Atlantic heritage renovation.
- Contemporary:Geometric patterns and mixed-material visuals target urban condominium specifications in Toronto, Vancouver, and Sydney.
Modern styling leads specification frequency; rustic textures climb fastest in suburban North American renovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for resilient flooring concentrates in the United States, Germany, and China, with each hub serving distinct regulatory environments and specification standards. Raw material processing for vinyl systems clusters near petrochemical corridors, while hardwood finishing operations track proximity to timber resources and export infrastructure.
United States
Suburban renovation demand in Texas, Tennessee, and the Southeast drives specification of waterproof vinyl plank systems for basement moisture tolerance. EPA TSCA Title VI formaldehyde emission standards constrain composite wood flooring imports, accelerating domestic production of CARB Phase 2-compliant engineered hardwood. Carpet manufacturing clusters in Georgia and Alabama retain institutional specification dominance in healthcare and education segments.
Germany
REACH phthalate restrictions redirect formulation strategies toward bio-based polyurethane binders and recycled PVC feedstocks across resilient flooring production. BIM-integrated procurement mandates in public construction accelerate digital specification platforms in Berlin and Hamburg commercial markets. Acoustic performance thresholds below 17 decibels sustain glue-down carpet and sheet vinyl specification in healthcare and education verticals.
China
Tier-one cities including Shanghai, Beijing, and Shenzhen compress commercial real estate retrofit cycles, driving faster flooring replacement schedules in office and retail environments. MIIT industrial standards and dual carbon goals pressure manufacturers toward lifecycle assessment infrastructure and embodied carbon disclosure. SPC and WPC rigid core production concentrates in Guangdong and Zhejiang provinces for export markets.
India
Urban housing stock expansion in Mumbai and Delhi NCR creates whitespace for waterproof laminate and SPC flooring adoption in underpenetrated resilient segments. BIS standards evolution and DGFT import regulations reshape competitive positioning for domestic versus foreign manufacturers. Flooring distribution networks concentrate in Maharashtra and Gujarat with expanding retail presence in Bangalore and Hyderabad.
Japan
Minimalist interior preferences in Tokyo and Osaka metropolitan areas sustain demand for large-format porcelain-look vinyl tiles with matte finishes. METI energy efficiency standards and JIS quality certifications constrain product entry for non-compliant imports. Rubber flooring specification for healthcare infection control protocols concentrates in hospital renovation programs across Kansai and Chubu regions.
Global Flooring Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the flooring industry. The vendor base separates into three tiers: integrated polymer producers with captive fiber or resin supply, specialized flooring manufacturers with specification relationships, and regional fabricators serving price-sensitive residential channels. Strategic moves concentrate on portfolio diversification around waterproof formulations and backward integration into recycled content engineering.
Among North American integrated manufacturers, Mohawk Industries, Shaw Industries Group, and Armstrong Flooring exemplify distinct archetypes. Mohawk represents captive supply chain control through in-house nylon fiber production. Shaw anchors scale-driven extrusion capacity in luxury vinyl tile systems. Armstrong occupies position within resilient flooring specialization. These three entities collectively illustrate how technology differentiation and cost discipline split across separate organizational models rather than consolidating within single players.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Tarkett SA |
| Armstrong Flooring, Inc. |
| Forbo Flooring Systems |
| Interface, Inc. |
| Gerflor Group |
| Beaulieu International Group |
| Mannington Mills, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts for PVC resin and plasticizer feedstocks lock in both supply access and price visibility for vinyl flooring manufacturers navigating petrochemical input volatility. These arrangements concentrate pricing power among integrated producers in the United States and Germany while exposing non-integrated fabricators to spot market fluctuations.
Pricing Analysis
EU Green Deal embodied carbon thresholds dictate the pricing tier structure across European resilient flooring markets. Three-tier pricing structure across premium, standard, and economy levels separates EPD-certified systems with recycled content cores from commodity vinyl imports. Price differentiation hinges on certification grade and geographic delivery cost. Pricing pressure stems from REACH compliance investments in bio-based polyurethane binders. Residential renovation channels exhibit highest price sensitivity; institutional healthcare specifications tolerate premium positioning.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes compress inventory buffers for SPC and WPC rigid core imports. Manufacturing gravity centers on China, the United States, and Germany. Raw material dependencies draw from PVC resin, calcium carbonate fillers, and plasticizer additives. Single-source vulnerability concentrates in Guangdong province extrusion capacity. Distribution runs through home improvement retail chains and architect-specifier platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flooring market functions as a defensive-moat industry where regulatory entrenchment creates durable competitive advantages. EPD certification requirements and embodied carbon disclosure mandates erect structural barriers that favor established players with lifecycle assessment infrastructure.
For Market Incumbents: Consolidate specification relationships through BIM-integrated product libraries that bypass traditional distribution channels. Deepen backward integration into recycled PVC feedstock engineering to neutralize petrochemical cost volatility. Capture architect procurement workflows before digital platforms commoditize product selection.
For New Entrants and Emerging Players: CARB Phase 2 fast-track certification unlocks federal procurement and large-scale residential development access in the United States. India's underpenetrated resilient segment offers whitespace for waterproof laminate and SPC flooring in Mumbai and Delhi NCR. Target healthcare infection control protocols with seamless sheet vinyl positioning.
For Investors and Strategic Acquirers: Specialized flooring manufacturers with European specification relationships and integrated linoleum expertise represent attractive acquisition targets. Long-term viability rests on regulatory compliance infrastructure rather than scale alone. Monitor EPD database expansion rates as inflection indicator for specification gatekeeper influence.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Content | EU Green Deal thresholds favor manufacturers with captive recycled PVC feedstock engineering capabilities. |
| BIM-Integrated Specification Platform | German and Dutch public procurement mandates accelerate digital architect-procurement bypass of distribution. |
| Healthcare Certification Investment | Seamless sheet vinyl with heat-welded seams commands premium positioning in hospital renovation programs. |
| India Market Entry | BIS standards evolution and urban housing expansion create whitespace for waterproof rigid core systems. |
| Bio-Based Binder Formulation | REACH phthalate restrictions redirect European production toward polyurethane alternatives with specification pull-through. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with flooring procurement managers, architect-specifiers, plant operations directors, and distribution channel heads. Secondary validation drew from EPA TSCA Title VI filings, ECHA REACH substance registrations, customs trade databases, and SEC 10-K disclosures from listed manufacturers. Bottom-up volume modeling triangulated against top-down macroeconomic construction indicators.
Across the analysis window, forecasts segmented by material type, end-user vertical, installation method, and design style. CAGRs derived from historical elasticity patterns applied to construction spending projections and retrofit cycle compression trends. Modeled inputs included suburban renovation intensity indices, commercial lease duration data, and regulatory compliance cost trajectories.
Decision-makers should treat outputs as directional under stable petrochemical pricing and continued EU carbon disclosure tightening; material deviation would warrant model refresh. Specific risks include abrupt REACH amendment timing, MIIT standard acceleration in China, and container logistics disruption. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Indoor Flooring Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
North America Vinyl Flooring Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
US Terrazzo Market
Flooring, Carpets, and Rugs
Rigid Core Flooring Market
Flooring, Carpets, and Rugs
Quarter Sawn Flooring Market