
 Egypt Floor Covering Market | 2026-2036
Egypt Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Egypt Floor Covering Market Foresight
Modular tile systems and loose-lay plank configurations are restructuring buyer choice across Egyptian commercial fit-outs. Oriental Weavers leverages its integrated weaving capacity to dominate carpet and rug supply for hospitality chains. Ceramica Cleopatra Group anchors the ceramic tile segment through captive clay sourcing and kiln scale. Mohawk Industries competes on luxury vinyl technology leadership, positioning its click-lock systems for premium residential towers.
Floor covering encompasses surface materials installed to protect subfloors, provide thermal and acoustic insulation, and define interior aesthetics through wear-layer thickness, slip-resistance ratings, and dimensional stability under load. Ceramic tiles fired at high temperatures dominate Egyptian production volumes due to local kaolin deposits and established kiln infrastructure. The vinyl segment grows fastest among synthetics, driven by moisture tolerance and lower installed cost in coastal hospitality projects. Natural fiber rugs sustain niche margin pools among heritage-conscious buyers in Cairo's luxury residential market.
Egypt's Housing and Building National Research Center enforces fire-resistance and VOC-emission standards that filter imported products at port entry. The Industrial Development Authority coordinates with Egyptian Standards under the Ministry of Trade to certify local manufacturers for public procurement eligibility. Stakeholders must monitor compliance cost trajectories and local-content thresholds as the government expands infrastructure and new-city construction programs.
Market Dynamics
The Egyptian floor covering market is restructuring around the Housing and Building National Research Center's tightening fire-resistance and VOC-emission standards, which filter imports at port entry and redirect procurement toward certified domestic manufacturers.
Growth Catalysts
- New Administrative Capital Corridor:Government infrastructure programs in Greater Cairo generate sustained demand for ceramic and vinyl surfaces across residential towers and commercial complexes.
- Coastal Hospitality Expansion:Resort zone developments in Red Sea and Mediterranean coastal areas specify moisture-tolerant synthetic flooring for high-traffic guest environments.
- Local-Content Procurement Mandates:Egyptian Standards certification requirements under the Ministry of Trade prioritize domestic manufacturers for public construction tenders.
Market Restraints
- Energy Cost Volatility:Natural gas price fluctuations directly impact kiln firing economics for ceramic tile producers concentrated in Suez Canal industrial zones.
- Import Dependency for Petrochemical Feedstocks:Vinyl resin and plasticizer supply chains remain exposed to currency fluctuation and foreign exchange availability constraints.
- Technical Limitation in Natural Fiber Processing:Domestic wool and cotton rug production lacks automated dyeing and finishing capacity compared to Turkish and Iranian competitors.
Strategic Opportunities
- Upper Egypt Industrial Zones:Underdeveloped governorates including Minya and Sohag offer land and labor cost advantages for tile manufacturing capacity expansion.
- Healthcare Facility Specification:Hospital and clinic construction programs create demand for antimicrobial surface treatments and slip-resistant vinyl sheet flooring.
- Digital Specification Platforms:Architect and designer procurement through Building Information Modeling-integrated material libraries reduces traditional distributor intermediation.
Industry Challenges
- Skilled Kiln Operator Shortage:Ceramic firing process expertise remains concentrated among aging workforce cohorts with limited vocational training pipeline replacement.
- Certification Timeline Compression:Egyptian Standards testing protocols for new product introductions create 4-6 month market entry delays that disadvantage innovative formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Egypt Floor Covering Market |
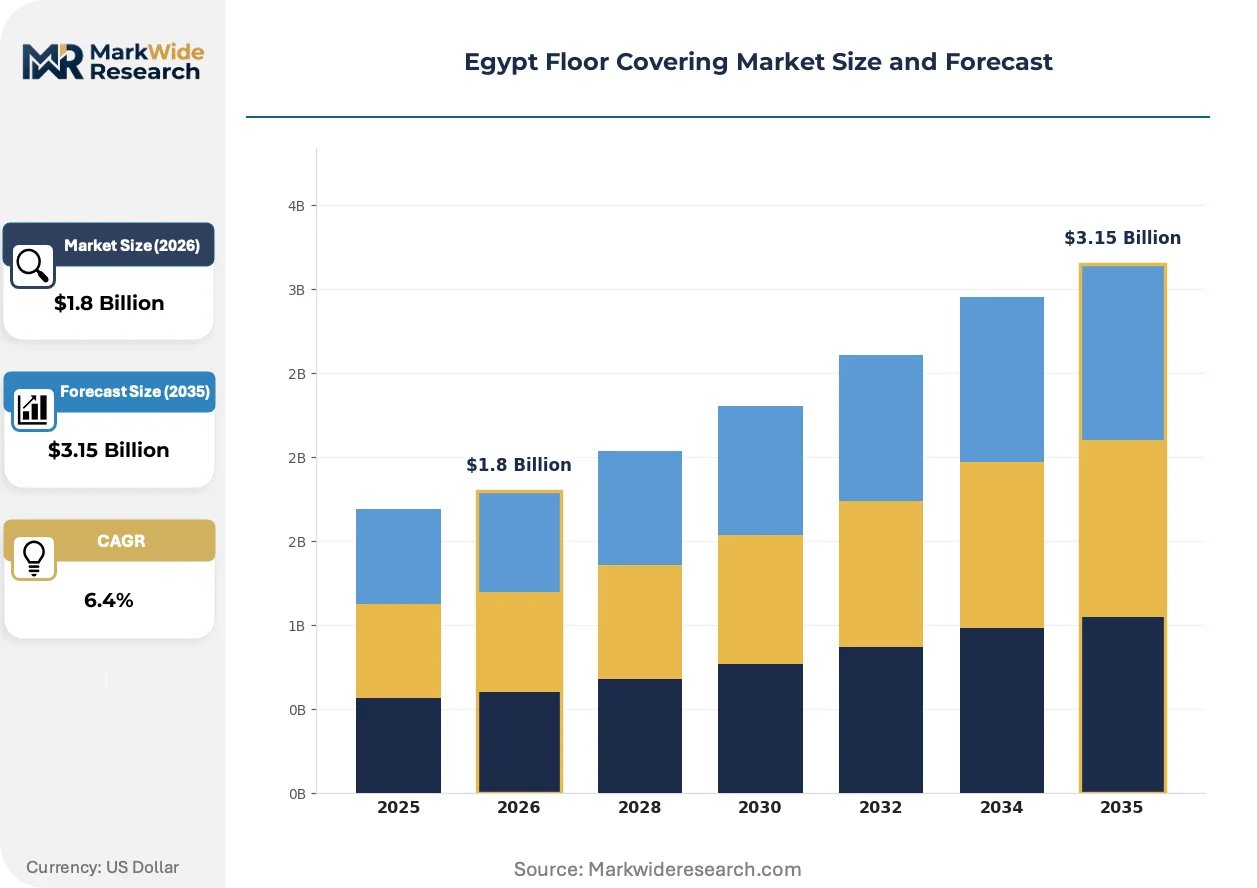
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpets, Rugs, Vinyl, Tiles Material: Nylon, Polyester, Natural Fiber, PVC End User: Residential, Commercial, Hospitality, Industrial Installation Type: Glue Down, Loose Lay, Click Lock, Stretch In |
| Companies Covered | Mohawk Industries, Gemma, Oriental Weavers, Interface, Moquette Centre, Ceramica Cleopatra Group, RAK Ceramics, Lecico, Tarkett S.A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Egypt Floor Covering Market Shifts & Advancements
Digital printing technology and modular installation systems are compressing traditional specification cycles while regulatory pressure on material safety accelerates domestic supply chain reconfiguration across Egyptian construction markets.
Dry-ink digital decoration is integrating high-resolution surface replication onto ceramic and vinyl substrates with minimal water consumption. Hospitality developers in Alexandria and Sharm El Sheikh specify these digitally printed surfaces for rapid brand-standard rollouts. The technology is integrating design flexibility with reduced lead times, compressing the advantage of imported premium tiles.
The Housing and Building National Research Center enforces updated fire-resistance classifications and VOC emission ceilings that exceed prior Egyptian Standards baselines. Imported flooring products face extended laboratory testing and documentation requirements at port entry. Ceramic and resilient flooring categories experience the most significant compliance cost increases, prompting domestic manufacturers to accelerate in-house testing laboratory investments.
Architects and interior designers in Cairo's premium residential segment are consolidating specification authority through direct manufacturer relationships. Traditional distributor networks lose margin share as project-scale buyers negotiate volume pricing and technical support directly with Ceramica Cleopatra Group and vinyl importers. Alexandria's design-build firms demonstrate the most advanced disintermediation, with procurement teams managing logistics and installation coordination internally.
Egypt Floor Covering Market Segmentation
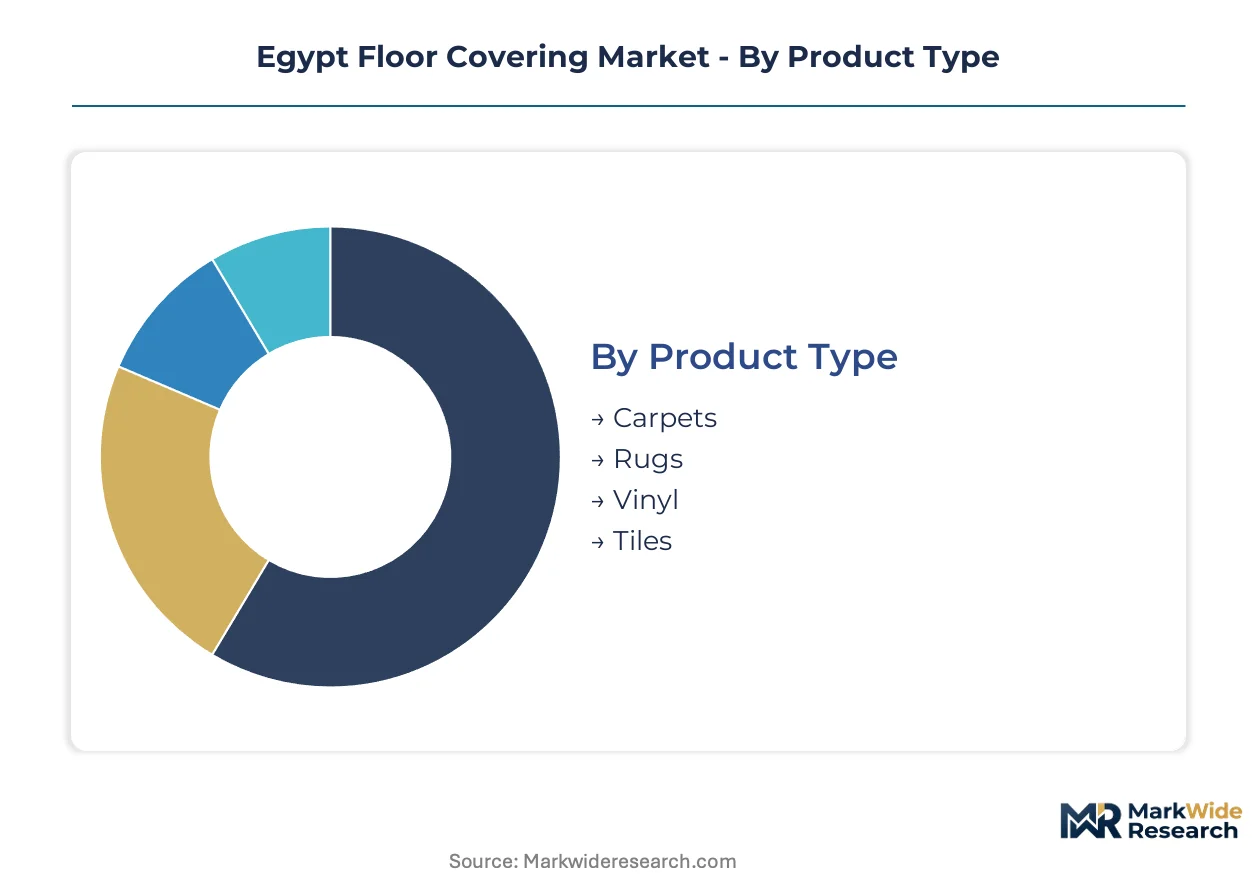
Floor covering procurement in Egypt diverges sharply across surface technologies and installation methods, with specification authority concentrating among Cairo-based architects and Alexandria hospitality developers. Understanding segment boundaries clarifies where technical compliance, cost engineering, and brand positioning intersect.
Product Type:
Surface technology specifications determine thermal performance, moisture tolerance, and fire-resistance ratings under Housing and Building National Research Center protocols.
- Tiles:Ceramic and porcelain surfaces fired at high temperatures dominate Egyptian production volumes due to captive kaolin deposits and established kiln infrastructure in Suez Canal industrial zones. Greater Cairo's new administrative capital corridor generates sustained demand for large-format glazed tiles in residential towers and commercial complexes.
- Vinyl:Synthetic resilient surfaces incorporate PVC wear layers with moisture-resistant backing systems suited to coastal humidity. Red Sea and Mediterranean resort developments specify luxury vinyl plank and sheet formats for high-traffic guest environments where slip resistance and rapid installation matter.
- Carpets:Broadloom and modular textile surfaces provide acoustic insulation and thermal comfort in conditioned interior spaces.
- Rugs:Portable textile floor coverings serve decorative and functional roles in residential and hospitality settings.
Tiles lead on scale; vinyl leads on momentum.
Material:
Raw material sourcing economics and regulatory compliance thresholds shape manufacturing location decisions and import dependency.
- PVC:Petrochemical-derived polymer resin forms the substrate for vinyl flooring production, with supply chains exposed to currency fluctuation and foreign exchange availability constraints at Egyptian ports.
- Natural Fiber:Wool and cotton rug production serves heritage-conscious buyers in Cairo's luxury residential market, though domestic operations lack automated dyeing and finishing capacity compared to Turkish competitors.
- Nylon:Synthetic polymer fiber provides durability and stain resistance in commercial carpet applications.
- Polyester:Petroleum-based fiber offers cost advantages in mass-market carpet and rug production.
PVC dominates volume throughput; natural fiber commands premium positioning.
End User:
Application environment dictates performance specifications, maintenance protocols, and procurement authority structures across Egyptian construction markets.
- Residential:Cairo and Alexandria developers expanding orders for ceramic and vinyl surfaces in new-build towers and renovation projects. Individual homeowners and investor-landlords drive replacement demand through direct retail and contractor channels.
- Hospitality:Coastal resort zones in Sharm El Sheikh and Hurghada specify moisture-tolerant synthetic flooring for guest rooms, lobbies, and food-service areas with accelerated wear cycles.
- Commercial:Office complexes and retail environments require fire-rated surfaces with acoustic and ergonomic performance characteristics.
- Industrial:Manufacturing and logistics facilities demand chemical-resistant, heavy-load-bearing floor systems with anti-static properties.
Residential anchors volume; hospitality shows steepest expansion trajectory.
Installation Type:
Mechanical attachment methods determine labor skill requirements, project timeline compression, and substrate preparation costs.
- Click Lock:Interlocking plank systems enable floating floor installation without adhesive, reducing skilled labor dependency and accelerating project completion in premium residential towers.
- Glue Down:Full-surface adhesive bonding provides dimensional stability for commercial vinyl sheet and tile applications in healthcare and hospitality environments.
- Loose Lay:Friction-based installation relies on weight and perimeter retention, suited to temporary or reconfigurable commercial fit-outs.
- Stretch In:Tension-mounted carpet installation requires specialized tools and skilled technicians for proper seam and edge finishing.
Glue down retains commercial dominance; click lock gains share fastest in residential specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egypt's floor covering industry traces its manufacturing roots to mid-20th century kiln operations clustered along the Nile Delta, where captive clay deposits and river transport enabled ceramic tile production at scale.
Greater Cairo and the New Administrative Capital
Residential tower construction and government complex development drive ceramic and vinyl surface demand across Cairo's eastern expansion corridor. The Housing and Building National Research Center enforces updated fire-resistance classifications for all materials specified in public infrastructure tenders. 10th of Ramadan City and Obour industrial zones host concentrated tile manufacturing capacity serving this corridor.
Alexandria and the Mediterranean Coast
Commercial fit-out activity and hospitality renovation projects specify moisture-tolerant synthetic flooring for high-traffic environments. Egyptian Standards certification requirements under the Ministry of Trade filter imported products at Alexandria port entry. Borg El Arab industrial city anchors vinyl processing and distribution logistics for northern governorates.
Red Sea Resort Zones
Hurghada and Sharm El Sheikh hospitality developments accelerate wear-cycle replacement demand for slip-resistant sheet vinyl and luxury plank systems. Coastal humidity and salt exposure elevate material performance specifications beyond interior standards. Suez Canal industrial zones supply processed petrochemical feedstocks for regional vinyl production.
Upper Egypt Governorates
Underdeveloped industrial land in Minya and Sohag offers labor cost advantages for tile manufacturing capacity expansion targeting price-sensitive residential segments. The Industrial Development Authority coordinates investment incentives for manufacturers relocating from congested northern zones. Beni Suef and Assiut cluster emerging kiln operations with access to local clay reserves.
Suez Canal Economic Zone
Energy-intensive ceramic firing operations concentrate near natural gas infrastructure and port access for export markets. Currency fluctuation and foreign exchange availability constraints impact imported resin supply chains for vinyl producers. Ismailia and Port Said industrial areas integrate logistics corridors connecting Egyptian production to regional distribution networks.
Egypt Floor Covering Market Competitive Landscape
The competitive structure tilts toward integrated domestic manufacturers with captive raw material access and established distribution networks. Ceramic tile production concentrates among operators controlling clay sourcing and kiln scale, while synthetic flooring segments attract multinational technology licensors and regional importers. Three archetypes dominate: vertically integrated domestic ceramic producers, international resilient flooring specialists, and textile-based carpet and rug weavers with hospitality supply relationships. Capacity expansion and direct specification relationships with Cairo-based architects represent the dominant competitive moves reshaping procurement patterns.
Among integrated domestic manufacturers, Ceramica Cleopatra Group and Oriental Weavers exemplify contrasting archetypes—ceramic production anchored by captive clay reserves versus textile weaving capacity serving hospitality chains. Mohawk Industries occupies a position as the international technology licensor for premium vinyl systems. These three anchors illustrate how local resource control, hospitality supply relationships, and imported technology leadership partition competitive terrain across Egyptian construction markets.
| Leading Market Players |
|---|
| Mohawk Industries |
| Gemma |
| Oriental Weavers |
| Interface |
| Moquette Centre |
| Ceramica Cleopatra Group |
| RAK Ceramics |
| Lecico |
| Tarkett S.A |
| Others |
Supply & Pricing Matrix
Public procurement mandates from the Housing and Building National Research Center are compressing specification windows for imported flooring, forcing distributors to absorb compliance testing costs or pivot toward certified domestic manufacturers with captive kiln capacity.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates luxury vinyl plank systems from ceramic tile commodity grades and basic PVC sheet alternatives. Price differentiation reflects Egyptian Standards certification status and volume scale in public tender participation. Cost compression in economy-grade ceramic segments is intensifying because energy subsidies for natural gas feedstock remain unpredictable. Residential developers in Greater Cairo demonstrate highest price sensitivity, while hospitality chains in Red Sea zones prioritize performance specifications over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with petrochemical resin imports concentrated in Saudi Arabia, China, and South Korea for PVC substrate production. Egyptian vinyl manufacturing draws from these feedstock origins while ceramic tile production rests on captive kaolin deposits in Suez Canal industrial zones. Tariff exposure on imported plasticizers and stabilizers creates margin volatility for synthetic flooring processors. Distribution runs through Alexandria port logistics corridors and Cairo-based specification houses serving architect-led procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Egypt's floor covering market represents a late-cycle quality story as hospitality developers and healthcare facility constructors shift specification authority toward fire-rated, low-VOC certified surfaces.
For Market Incumbents: Anticipate margin compression from Turkish ceramic exporters by securing backward integration into clay beneficiation and accelerating in-house laboratory certification capacity under Egyptian Standards protocols. Channel control through direct architect relationships in Cairo's design-build firms offers defensive positioning against distributor disintermediation. For New Entrants and Emerging Players: Launch via digital specification platforms integrated with Building Information Modeling libraries to bypass traditional distributor networks. Upper Egypt governorates present the most penetrable geography for greenfield tile manufacturing, with Minya and Sohag offering land cost advantages and access to local clay reserves for price-sensitive residential segments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale ceramic producers possessing captive raw material access and incomplete certification coverage for public procurement eligibility. Long-term viability hinges on regulatory compliance infrastructure rather than volume scale alone. Watch for inflection in Housing and Building National Research Center enforcement intensity at Alexandria port entry as signal for import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Laboratory Certification Investment | In-house testing capacity under Egyptian Standards protocols accelerates product introduction timelines for public tenders. |
| Direct Architect Specification Programs | Bypassing distributor intermediation secures volume pricing authority in Cairo's premium residential tower developments. |
| Upper Egypt Manufacturing Relocation | Land and labor cost advantages in Minya and Sohag governorates target price-sensitive ceramic tile demand segments. |
| Digital Platform Integration | Building Information Modeling-integrated material libraries compress specification cycles for hospitality and healthcare verticals. |
| Antimicrobial Surface Treatment Development | Healthcare facility construction programs create specification pull for slip-resistant vinyl with embedded antimicrobial properties. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ceramic plant managers, hospitality procurement directors, Cairo-based specification architects, and Alexandria port logistics operators with secondary validation against Egyptian Standards documentation, Industrial Development Authority investment incentive records, Suez Canal trade flow data, and Housing and Building National Research Center regulatory filings. Bottom-up production volume estimates from kiln operators triangulated against top-down construction sector expenditure patterns.
Segment-weighting across product type, material composition, end-use application, and installation method dimensions shaped volume and value outputs across the analysis window. CAGRs derived from trend extrapolation of construction sector expenditure patterns, regulatory compliance cost trajectories, and feedstock price elasticity assumptions. Industry-specific inputs included natural gas tariff adjustment schedules and coastal humidity exposure coefficients for material performance degradation modeling.
Several conditions sit outside the modeled scope, including unannounced regulatory enforcement intensity variations, currency devaluation magnitude beyond historical bands, and geopolitical disruption to Red Sea shipping corridors. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
China Laminate Flooring Market
Flooring, Carpets, and Rugs
Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Wooden Floor Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tiles Market
Flooring, Carpets, and Rugs
GCC Flooring Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
United States Commercial Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
United States Floor Covering Market
Flooring, Carpets, and Rugs
US Vinyl Floor Covering Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market