
 Wooden Decking Market | 2026-2036
Wooden Decking Market Size, Share, and Industry Trends Forecast 2026-2036
Wooden Decking Market Analysis
Commercial hospitality developers is reorganizing demand patterns away from pure residential DIY channels. Trex Company Inc leverages its composite technology leadership to capture specification-driven projects. Fiberon anchors its position through proprietary co-extrusion processes that reduce thermal expansion. UFP Industries Inc controls distribution density across North American lumber yards and pro-contractor networks.
Wooden decking comprises structural and decorative platform surfaces fabricated from sawn lumber, engineered wood composites, or tropical hardwoods, typically spanning joist systems at load ratings between 50 and 100 pounds per square foot depending on species and span configuration. Treated lumber dominates volume flows in residential retrofit markets where first-cost sensitivity governs selection, while composite decking commands margin pools in commercial and hospitality segments demanding extended service life with minimal maintenance intervention. Professional installation captures premium labor value in custom-built and modular systems where code compliance and warranty validation require certified craft labor.
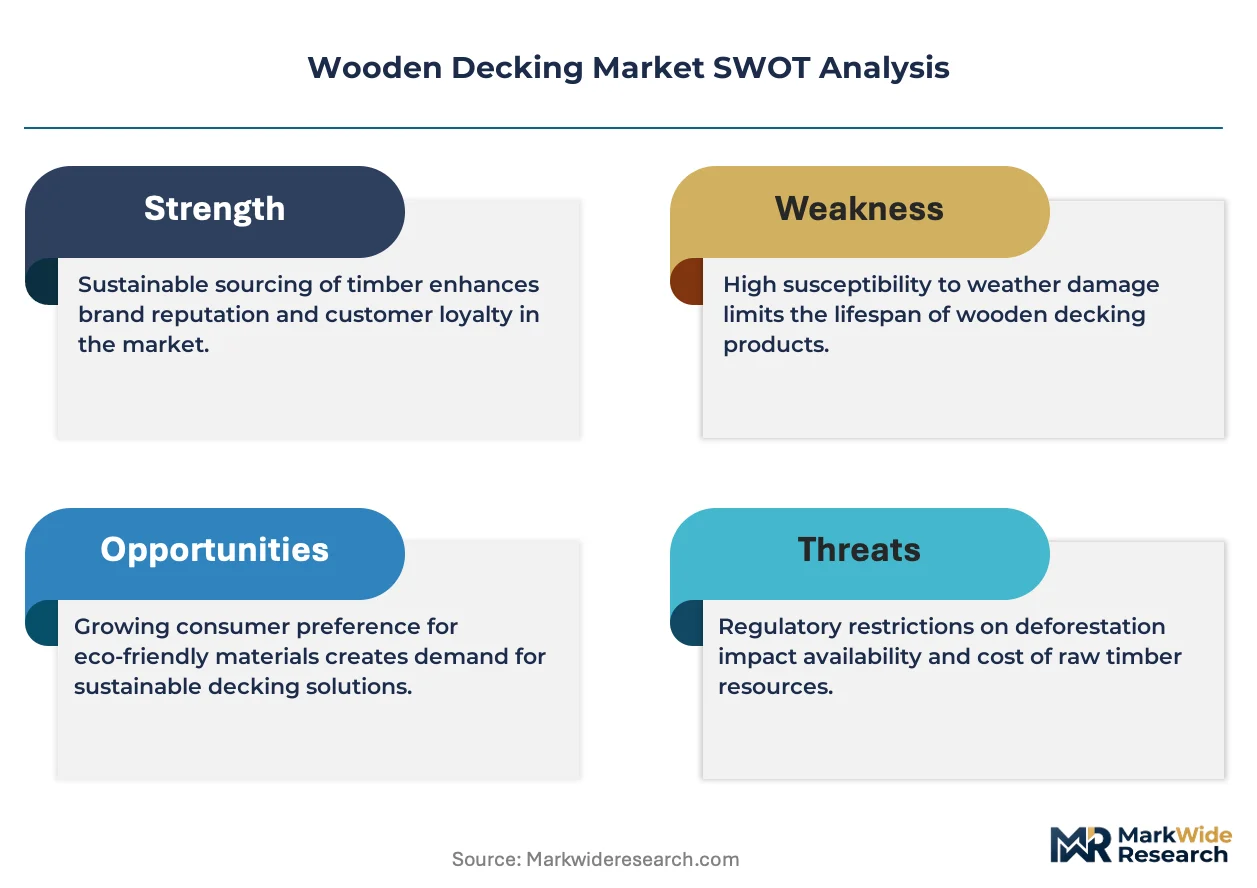
EPA regulates preservative chemical loading in pressure-treated lumber through pesticide registration and tolerance standards, while EU Timber Regulation mandates chain-of-custody documentation for tropical hardwood imports. FSC and PEFC certification schemes further constrain supply availability for spec-grade projects. Stakeholders must monitor evolving embodied-carbon accounting rules that threaten to reclassify chemically treated softwoods against lower-carbon composite alternatives in public procurement frameworks.
Market Dynamics
Residential renovation cycles in suburban United States, Germany, and Australia are accelerating specification rates for engineered wood and composite alternatives, while EPA-treated wood standards and EU Timber Regulation compliance requirements simultaneously reshape material sourcing protocols across distribution networks.
Growth Catalysts
- Suburban outdoor living upgrades:Residential retrofit activity in coastal United States markets sustains procurement volumes for pressure-treated lumber and composite systems as homeowners expand usable living space.
- EU Timber Regulation chain-of-custody mandates:Compliance documentation requirements for tropical hardwood imports are consolidating supplier relationships around certified FSC and PEFC sources.
- Coastal hospitality construction:Commercial developers in Australia specify extended-service-life decking materials to minimize maintenance intervention in high-traffic boardwalk and resort applications.
Market Restraints
- Softwood lumber price volatility:Input cost swings for southern yellow pine and SPF species compress margin pools for treated lumber producers serving first-cost-sensitive residential channels.
- Tropical hardwood supply concentration:Sourcing dependencies on Southeast Asian and South American forest concessions expose spec-grade projects to documentation gaps and availability constraints.
- Embodied-carbon accounting emergence:Public procurement frameworks in Germany and the United States threaten to reclassify chemically treated softwoods against lower-carbon composite alternatives.
Strategic Opportunities
- Underpenetrated Australian commercial segment:Composite decking specification rates in hospitality and municipal boardwalk projects lag United States penetration levels, creating white space for technology transfer.
- EU Green Deal circularity incentives:Recycled-content mandates and extended producer responsibility frameworks favor composite manufacturers with established reclaimed plastic feedstock networks.
- Pro-contractor channel digitization:Lumber yard and professional installer networks in the United States are adopting specification tools that reduce thermal expansion and warranty claim friction.
Industry Challenges
- Certified installation labor scarcity:Code compliance and warranty validation requirements for modular and custom-built systems outpace craft labor certification capacity in high-growth United States metro corridors.
- Preservative chemistry registration timelines:EPA pesticide tolerance reviews and state-level regulatory variations delay new treated wood product commercialization by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wooden Decking Market |
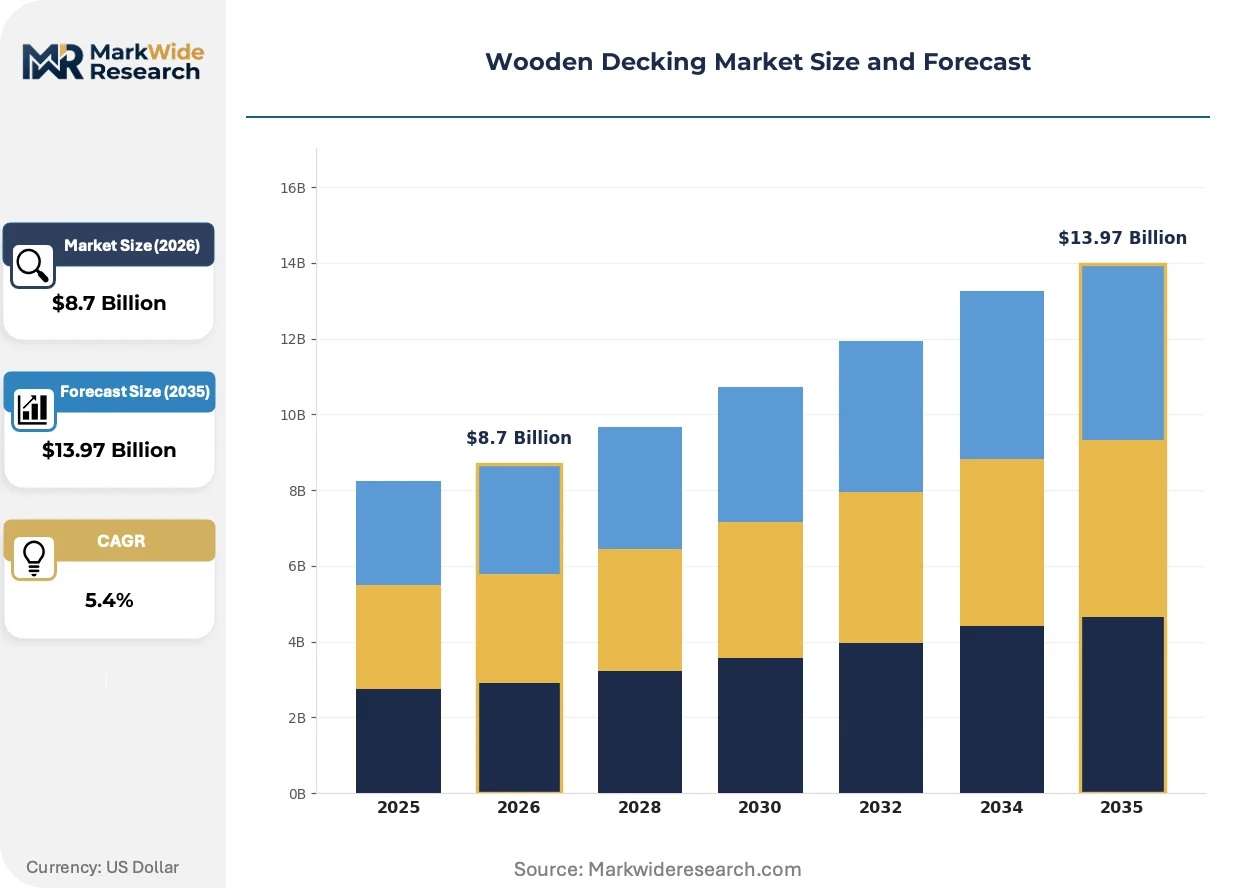
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Treated Lumber, Composite Decking, Hardwoods, Softwoods End User: Residential, Commercial, Hospitality, Recreational Installation Type: DIY, Professional, Modular, Custom Built Maintenance Type: Sealing, Staining, Cleaning, Restoration |
| Companies Covered | Trex Company Inc, The AZEK Company LLC, Fiberon, UFP Industries Inc, Weyerhaeuser Company, West Fraser Timber Co Ltd, UPM-Kymmene Corporation, Metsä Group, James Latham Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wooden Decking Market Emerging Trajectories
Material science advances and procurement digitization are compressing traditional specification cycles while regulatory pressure on chemical treatments accelerates alternative technology validation.
Co-extrusion composite manufacturing is fragmenting the traditional wood-plastic composite category into performance-tiered subsegments. Hospitality developers in Australia and coastal United States markets specify these systems for boardwalk applications requiring minimal thermal expansion. The technology is fragmenting specification authority away from residential DIY channels toward engineered-solutions providers.
REACH chemical restriction proposals in Europe are tightening preservative loading limits for pressure-treated lumber used in residential proximity applications. Industrial consequence includes accelerated substitution toward thermally modified softwoods and modified wood technologies in German and Nordic markets. Commercial specifiers are responding by mandating third-party emission testing documentation for all treated wood submissions.
Professional installer networks are consolidating specification influence through warranty-conditional installation requirements. Lumber yard pro-desk channels in the United States now capture premium labor value previously fragmented across independent contractors. This concentration is most visible in custom-built residential projects where certified craft labor validates manufacturer warranty terms.
Wooden Decking Market Segmentation
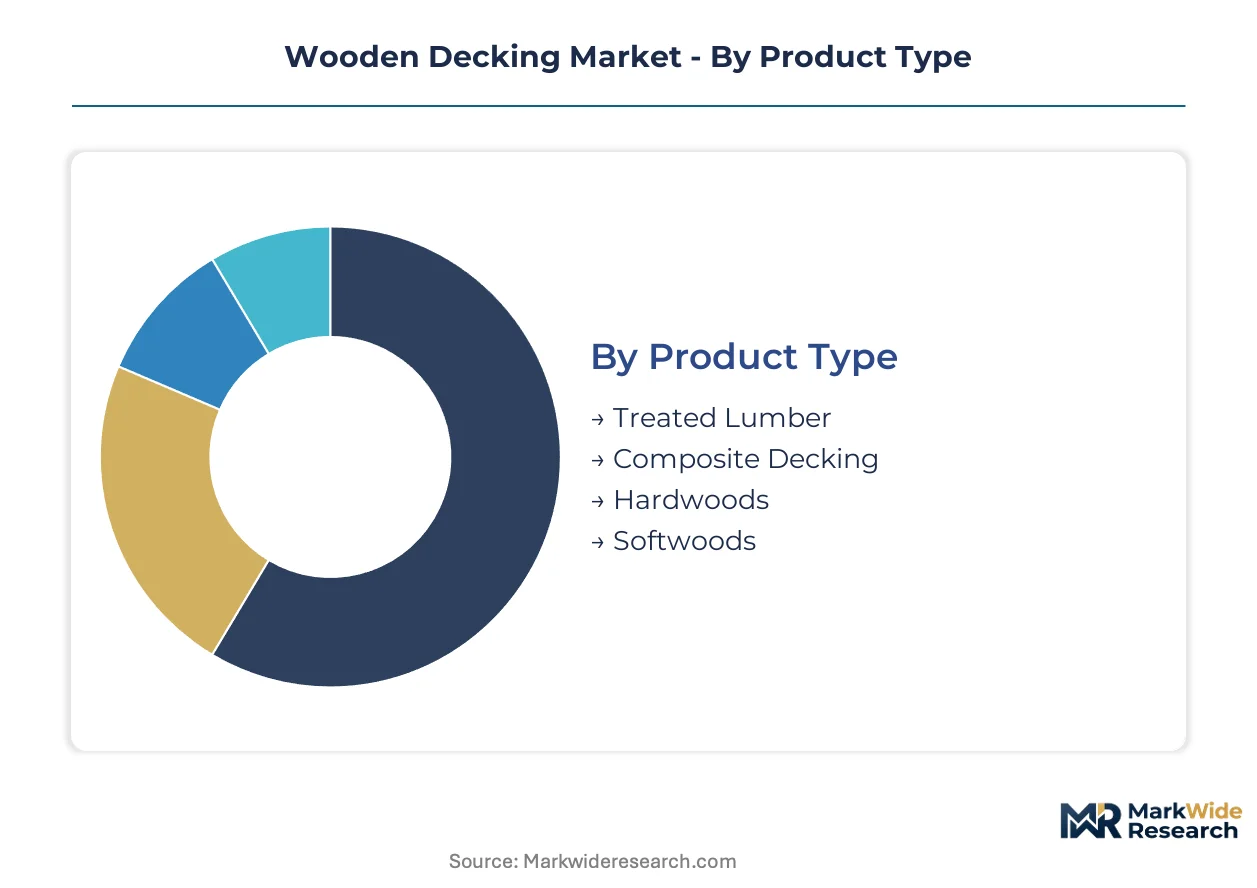
Segmentation in wooden decking reveals how material chemistry and installation protocols fragment procurement authority across residential DIY and commercial specification channels. Understanding these divisions exposes where composite technologies displace traditional lumber and where certified labor commands premium positioning.
Product Type:
Substitution pressure from low-maintenance alternatives reshapes material selection hierarchies across end-use segments, with chemical treatment regulations accelerating displacement timelines in residential proximity applications.
- Treated Lumber:Pressure-treated southern yellow pine and SPF species dominate first-cost-sensitive residential retrofit channels. EPA pesticide tolerance standards and state-level regulatory variations compress margin pools while extending commercialization timelines for new preservative formulations.
- Composite Decking:Wood-plastic and co-extrusion systems command specification authority in commercial and hospitality segments demanding extended service life. Trex and Fiberon technologies capture boardwalk and resort projects through thermal expansion control and warranty-validated performance.
- Hardwoods:Tropical species face EU Timber Regulation chain-of-custody constraints and FSC certification requirements that consolidate supplier relationships around documented concessions.
- Softwoods:Untreated cedar and redwood retreat to premium aesthetic applications where natural weathering patterns justify higher initial material outlays.
Treated lumber anchors the volume base while composite decking gains share at the steepest rate.
End User:
Customer type stratification separates price-driven renovation cycles from specification-engineered new construction where warranty validation and code compliance govern procurement.
- Residential:Suburban outdoor living upgrades in coastal United States markets sustain procurement volumes for pressure-treated systems. Homeowner first-cost sensitivity preserves lumber dominance despite composite marketing investments.
- Commercial:Developers prioritize total cost of ownership calculations that favor composite and modified wood technologies in high-traffic installations.
- Hospitality:Australian resort and boardwalk construction specifies extended-service-life materials to minimize maintenance intervention in salt-air environments.
- Recreational:Municipal trail systems and marina infrastructure balance accessibility requirements against durability specifications in public procurement frameworks.
Residential channels anchor the volume base while hospitality applications climb the fastest as coastal development intensifies.
Installation Type:
Volume concentration in professional channels reflects warranty-conditional requirements and code compliance complexity that fragment authority away from independent contractors.
- DIY:Big-box retail and lumber yard consumer divisions serve renovation-driven homeowners with pre-cut kit systems and installation guidance content.
- Professional:Certified craft labor validates manufacturer warranty terms in custom-built residential and commercial projects. Labor scarcity in high-growth United States metro corridors constrains capacity expansion.
- Modular:Prefabricated panel systems reduce on-site labor requirements in multi-family and hospitality applications where schedule compression drives value.
- Custom Built:Design-build contractors capture premium labor value through architect-specified geometries and integrated railing systems.
Professional installation anchors the volume base while modular systems expand most quickly as labor costs escalate.
Maintenance Type:
Service lifecycle economics differentiate material categories, with maintenance burden driving substitution toward composite alternatives in commercial ownership structures.
- Sealing:Annual or biennial applications preserve dimensional stability in pressure-treated lumber exposed to cyclic wetting.
- Staining:Pigmented film-forming products provide UV protection for natural wood aesthetics in residential display applications.
- Cleaning:Pressure washing and chemical brightening restore surface appearance on composite and hardwood installations without structural intervention.
- Restoration:Sanding and resurfacing extends service life for solid-sawn lumber in heritage or high-value architectural contexts.
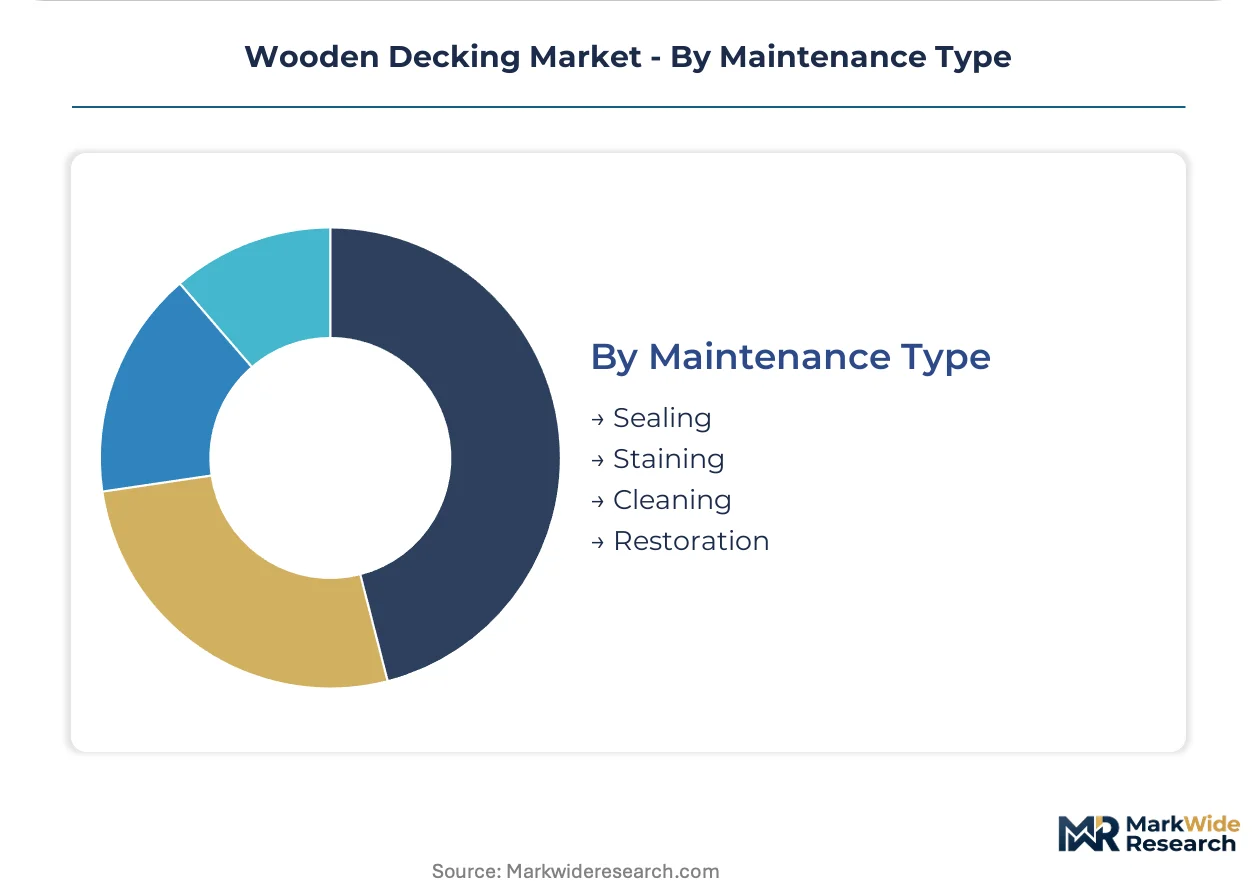
Cleaning protocols anchor the volume base as composite penetration reduces structural restoration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sawmills and treatment facilities cluster in timber-rich jurisdictions where forest concessions and chemical processing permits align. Procurement flows concentrate through coastal distribution hubs serving suburban renovation and hospitality construction cycles.
United States
Suburban outdoor living upgrades in Florida, California, and Texas metro areas sustain pressure-treated lumber volumes. EPA pesticide tolerance standards govern preservative loading in southern yellow pine processing. Distribution density concentrates across Georgia-Pacific and Weyerhaeuser networks in the Southeast and Pacific Northwest.
Germany
EU Timber Regulation chain-of-custody mandates reshape tropical hardwood sourcing for spec-grade commercial projects. REACH chemical restriction proposals tighten preservative limits for residential proximity applications. Modified wood technology clusters in Baden-Württemberg and Bavaria displace chemically treated alternatives.
Australia
Coastal hospitality construction in Queensland and New South Wales specifies extended-service-life materials for salt-air boardwalk environments. TGA-equivalent building code authorities enforce warranty-validation requirements for commercial installations. Sydney and Gold Coast pro-contractor networks consolidate specification authority.
Canada
SPF species harvesting in British Columbia feeds cross-border treatment facilities serving US residential retrofit channels. Health Canada/PMRA regulates preservative chemistry registration timelines extending commercialization cycles. Vancouver and Toronto distribution hubs anchor North American supply chain flows.
United Kingdom
FSC and PEFC certification requirements constrain tropical hardwood availability for London commercial developments. Building Regulations Part A structural standards govern load-rated decking specifications. Southeast England pro-desk networks capture premium installation labor value in custom residential projects.
Wooden Decking Market Vendor Landscape
Concentration sits with integrated composite technology developers and North American lumber treatment specialists. The vendor base separates into three strategic archetypes: proprietary co-extrusion manufacturers, pressure-treated commodity producers, and tropical hardwood importers with certified chain-of-custody documentation. Competitive positioning hardens through M&A consolidation of distribution networks and technology licensing agreements for thermal expansion control.
Among composite technology developers, Trex Company Inc and Fiberon exemplify the specification-driven tier where engineered material science displaces traditional lumber in commercial and hospitality channels. UFP Industries Inc anchors the treated lumber and distribution density archetype across North American pro-contractor networks. These three represent divergent strategic positions: proprietary manufacturing versus distribution control versus material innovation.
| Leading Market Players |
|---|
| Trex Company Inc |
| The AZEK Company LLC |
| Fiberon |
| UFP Industries Inc |
| Weyerhaeuser Company |
| West Fraser Timber Co Ltd |
| UPM-Kymmene Corporation |
| Metsä Group |
| James Latham Plc |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between Australian hospitality developers and Southeast Asian tropical hardwood suppliers lock in both supply access and price visibility for spec-grade boardwalk projects, insulating procurement teams from spot market volatility in FSC-certified concessions.
Pricing Analysis
EPA pesticide tolerance standards dictate the pricing tier structure across pressure-treated lumber categories, separating residential-grade southern yellow pine from commercial-specification modified wood alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and thermal expansion performance metrics. Cost compression in economy-tier treated lumber intensifies because softwood input volatility compresses margin pools for first-cost-sensitive residential channels. Homeowners in suburban retrofit markets exhibit highest price sensitivity, while hospitality developers prioritize total cost of ownership over initial material outlays.
Supply Chain Analysis
Port congestion along Southeast Asian export lanes disrupts container availability for EU-bound tropical hardwood shipments, extending lead times for FSC-certified decking imports. Production gravity centers on Indonesia, Malaysia, and Brazil for tropical species, while southern yellow pine treatment facilities cluster in the United States Southeast. Feedstock draws from SPF harvesting in British Columbia and chemical preservative formulations registered under EPA and PMRA protocols. Single-source vulnerability concentrates in certified concession documentation gaps. Distribution runs through lumber yard pro-desk networks and big-box retail channels serving distinct residential and commercial buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority fragmentation across residential DIY and commercial engineered-solution channels creates niche entry points for specialized composite technology providers and certified installation networks.
For Market Incumbents: Secure backward integration into reclaimed plastic feedstock networks to defend composite margin pools against emerging bio-based material entrants. Anchor distribution density through pro-contractor certification programs that validate warranty terms and lock out independent installer competition. Trex and Fiberon technology licensing agreements demonstrate how thermal expansion control patents create switching costs for hospitality specifiers.
For New Entrants and Emerging Players: Anchor in Australian commercial hospitality segments where composite penetration lags United States specification rates by substantial margins. Target municipal boardwalk and salt-air resort applications demanding extended service life with minimal maintenance intervention. Pursue co-extrusion technology licensing partnerships with established European modified wood clusters to bypass EPA registration timelines for new preservative chemistries.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among pro-contractor installation networks capturing annual maintenance and restoration service contracts. Five-to-ten-year viability favors composite manufacturers with established circular feedstock infrastructure over commodity-treated lumber producers facing embodied-carbon reclassification risks. Monitor EU Green Deal circularity incentive implementation as inflection indicator for recycled-content mandate acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Co-extrusion Technology Licensing | Fiberon and Trex patent portfolios enable thermal expansion control in Australian boardwalk specifications. |
| Pro-Contractor Certification Program | Lumber yard networks in Florida and California capture premium labor value through warranty-validated installation. |
| Reclaimed Plastic Feedstock Integration | EU Green Deal circularity incentives favor composite manufacturers with established post-consumer waste networks. |
| FSC Chain-of-Custody Documentation | EU Timber Regulation compliance consolidates supplier relationships around certified Southeast Asian concessions. |
| Modified Wood Technology Cluster Partnership | Baden-Württemberg and Bavaria facilities displace chemically treated alternatives under REACH restriction proposals. |
Methodological Framework
Cross-validation between primary interviews with lumber yard procurement managers, pro-contractor installation network heads, and hospitality development executives anchors the qualitative findings against secondary validation from EPA pesticide registration databases, EU Timber Regulation compliance filings, and FSC chain-of-custody documentation. Bottom-up volume modeling triangulates with top-down value estimates derived from treated lumber and composite decking trade flow analysis.
Sensitivity analysis across material substitution scenarios tests forecast robustness over the projection horizon. Segmentation dimensions include product chemistry tier, end-use application, installation protocol, and regional regulatory cluster. CAGRs derive from installed base replacement cycles and new construction specification rate trajectories. Embodied-carbon accounting rule evolution and preservative chemistry registration timelines constitute critical forecast inputs.
Material uncertainties — embodied-carbon reclassification in German public procurement, EPA pesticide tolerance review delays, tropical hardwood concession documentation gaps — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and feedstock availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor Decor
India Outdoor Furniture Market
Outdoor Decor
Garden Rooms Market
Outdoor Decor
Outdoor Bar Furniture Market
Outdoor Decor
North America Awnings Market
Outdoor Decor
Brush Rocker Market
Outdoor Decor
Brazil Sustainable Home Decor Market
Outdoor Decor
Patio Umbrella Market
Outdoor Decor
Spray Covers Market
Outdoor Decor
Outdoor Furniture Market
Outdoor Decor
Camping Furniture Market
Outdoor Decor
Freestanding Retractable Awnings Market
Outdoor Decor
Middle East Outdoor and Indoor Furniture Market
Outdoor Decor
Floating Fountains Market
Outdoor Decor
Adirondack Chairs Market
Outdoor Decor
Retractable Awnings Market
Outdoor Decor
Outdoor Kitchen Cabinets Market