
 Germany Floor Covering Market | 2026-2036
Germany Floor Covering Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Floor Covering Market Foresight
Market Context
Modular click-lock flooring bundles is recalibrating buyer choice across German distribution channels. Parador GmbH leverages its domestic manufacturing footprint to sustain rapid fulfillment for trade customers. Nora Systems GmbH anchors its position through specialized rubber and vinyl compounds for healthcare and education applications. Tarkett S.A. competes across multiple product tiers while navigating stringent indoor air quality certifications.
Technical Definition and Segment Structure
Germany floor covering encompasses laminated wood composites, resilient vinyl layers, solid hardwood planks, natural cork sheets, bamboo strips, and stone tiles engineered for thermal insulation, acoustic dampening, and abrasion resistance in built environments. Laminate and vinyl segments dominate volume flows due to cost efficiency and moisture tolerance in multi-family housing, while hardwood commands premium positioning among interior designers specifying for heritage restoration projects. Click lock and floating installation methods are gaining share as skilled labor scarcity drives demand for reduced-skill, faster-deploy systems in commercial complexes and residential buildings.
Regulatory Frame and Outlook
The German Institute for Standardization (DIN) and the Committee for Health-Related Evaluation of Building Products (AgBB) set emissions thresholds and durability benchmarks that filter market access for imported materials. REACH compliance through ECHA and Germany's federal GEG thermal regulations collectively elevate product testing costs while rewarding low-VOC, thermally efficient formulations. Stakeholders must monitor evolving circular economy packaging rules and building renovation wave funding allocations to anticipate demand inflection points.
Market Dynamics
Click-lock floating installation systems are compressing project timelines across German residential and commercial construction, forcing distributors to reconfigure inventory toward reduced-skill deployment formats and away from traditional adhesive-bound products.
Growth Catalysts
- GEG Thermal Mandates:Germany's Building Energy Act mandates stricter insulation performance in flooring systems, pulling demand toward thermally efficient laminates and engineered composites in renovation corridors.
- Healthcare Facility Modernization:Acoustic dampening specifications in hospitals and eldercare facilities are accelerating specification of specialized rubber-vinyl compounds for corridor and patient room applications.
- Bavaria Housing Stock Renewal:Elevated demolition-rebuild rates in Munich and Nuremberg metro corridors concentrate demand for moisture-tolerant flooring suited to multi-family basement and ground-level installations.
Market Restraints
- Petrochemical Input Volatility:Resilient vinyl production faces margin compression from propylene and plasticizer price swings, forcing mid-tier manufacturers toward thinner-gauge product lines.
- AgBB Certification Friction:Germany's Committee for Health-Related Evaluation of Building Products imposes multi-month emissions testing timelines that delay market entry for imported laminate and engineered wood products.
- Hardwood Substitution Pressure:Ceramic tile and polished concrete are capturing premium residential kitchen and bath specification from solid plank flooring due to superior moisture immunity.
Strategic Opportunities
- North Rhine-Westphalia Retrofit Wave:Düsseldorf and Cologne municipal housing associations are bundling flooring replacement into facade insulation contracts, creating captive demand for integrated thermal-acoustic systems.
- Circular Economy Packaging Rules:Evolving federal requirements for recyclable palletization and reduced plastic film are rewarding domestic manufacturers with closed-loop logistics infrastructure.
- Biobased Binder Convergence:Soy and lignin adhesive formulations meeting AgBB thresholds are opening specification pathways in education and municipal buildings with strict VOC procurement policies.
Industry Challenges
- Skilled Installer Scarcity:Traditional parquet and glued-down vinyl application requires certified craftspeople whose training pipeline through German chamber of commerce apprenticeships has constricted over the past decade.
- REACH Pre-registration Burden:ECHA chemical substance notifications for novel surface treatments and wear-layer additives impose documentation costs that disproportionately burden smaller compound suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Floor Covering Market |
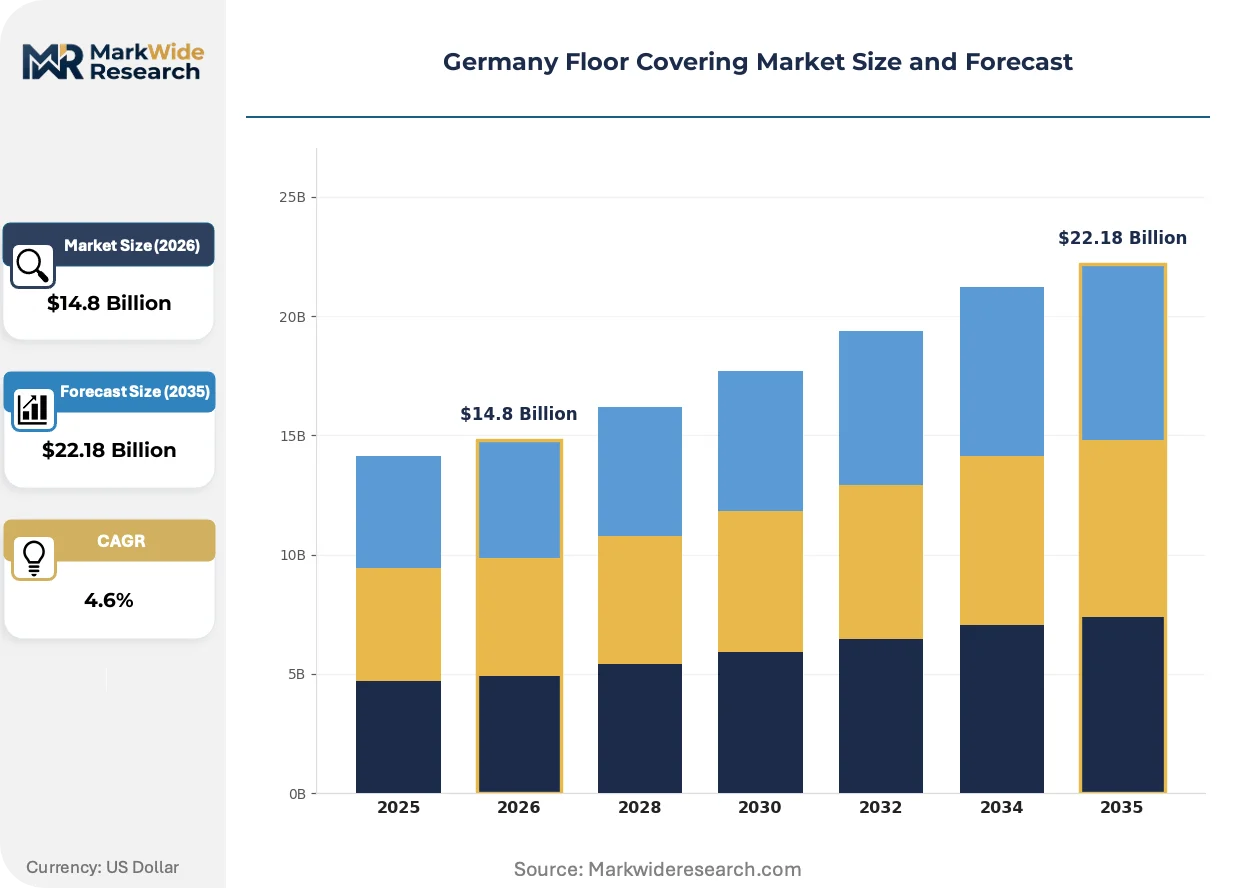
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $22.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laminate, Vinyl, Hardwood, Cork, Bamboo, Stone Application: Residential Buildings, Commercial Complexes, Educational Institutes, Hospitality Venues, Sports Facilities, Public Infrastructure Installation Method: Glue Down, Floating, Nail Down, Click Lock, Loose Lay, Staple Down End User: Homeowners, Interior Designers, Contractors, Real Estate Developers, Facility Managers, Retailers |
| Companies Covered | Parador GmbH, Nora Systems GmbH, Tarkett S.A., HARO Cork Floors, Gerflor, Forbo Flooring GmbH, Egger Group, PolyFlor, Mohawk Industries (Quick-Step), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Floor Covering Market Shifts & Advancements
Digital surface replication and thermal-performance layering are converging to redefine product specification criteria across German distribution channels, compressing the gap between premium aesthetics and mid-tier pricing.
Photorealistic embossed-in-register laminate surfaces are rewriting buyer expectations for wood-grain authenticity at sub-hardwood price points. Specifiers in heritage renovation projects across Hamburg and Berlin are specifying these products for listed building interiors where solid timber replacement faces preservation restrictions. The technology is compressing the addressable market for entry-grade hardwood imports from Eastern European suppliers.
Germany's federal GEG thermal regulations are mandating minimum R-values for flooring systems in all new construction and deep renovation permits. Manufacturers are responding with multi-layer rigid core constructions integrating cork or foam underlayment bonded at the factory. Bavarian and Baden-Württemberg building authorities are enforcing these standards most stringently, creating regional product fragmentation.
Direct-to-trade digital procurement platforms are displacing traditional wholesale showroom relationships among mid-sized German installation contractors. These buyers now specify products through distributor apps with real-time stock visibility and next-day fulfillment guarantees. The shift is most advanced in North Rhine-Westphalia, where dense contractor networks support platform economics absent in eastern federal states.
Germany Floor Covering Market Segmentation
Floor covering procurement in Germany fragments across technical specifications, installation complexity, and end-user sophistication. Each segmentation axis reveals distinct margin structures and regulatory exposure that shape manufacturer positioning.
Product Type:
Standalone flooring products dominate residential renovation workflows, while integrated thermal-acoustic systems embed directly into GEG-compliant building envelopes.
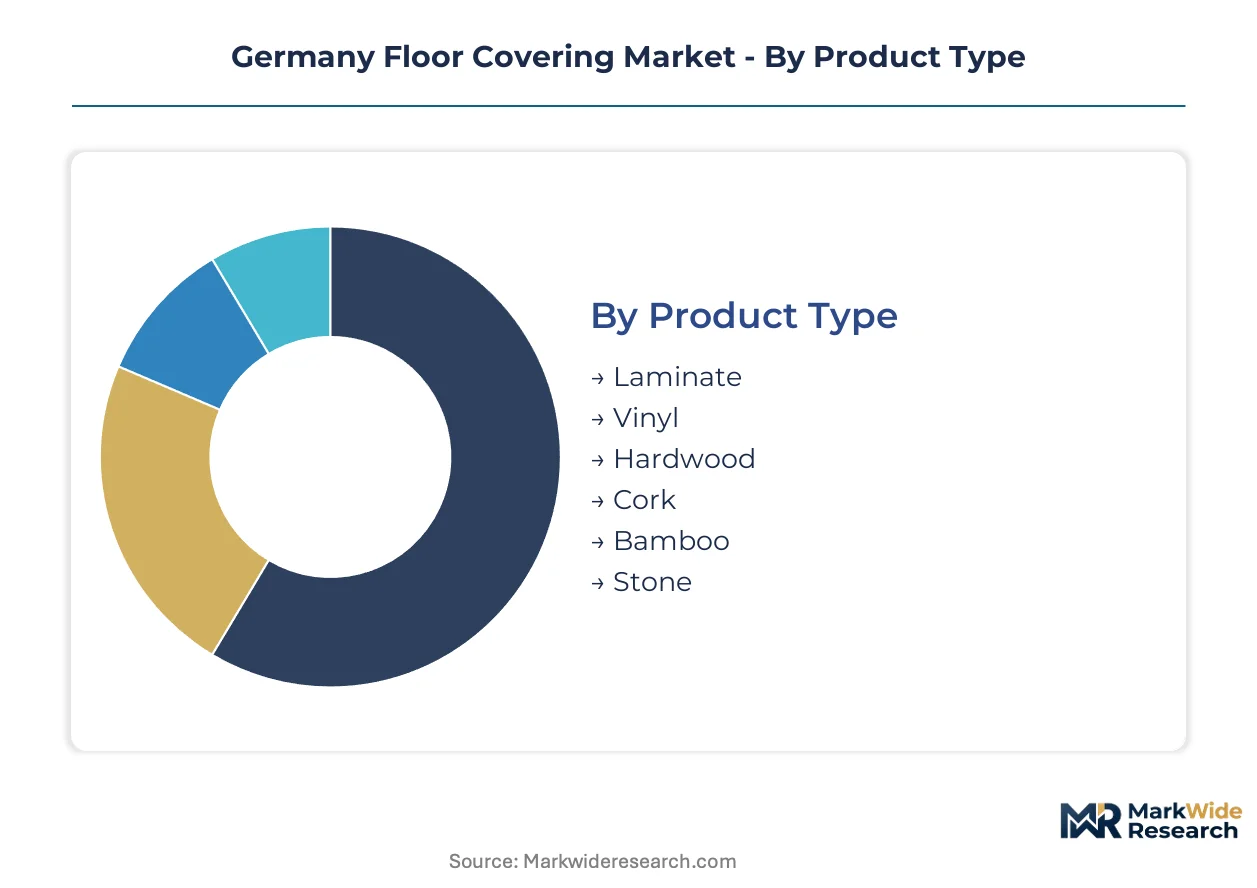
- Laminate:Multi-layer wood composite with melamine wear surface and HDF core, engineered for click-lock assembly without adhesives. Bavarian housing associations specify these for basement installations where moisture tolerance and thermal bridging control intersect. GEG thermal mandates pull specification toward factory-bonded underlayment configurations.
- Vinyl:PVC or bio-based polymer wear layers over mineral or fiberglass cores, delivering acoustic dampening and chemical resistance. Healthcare corridors in North Rhine-Westphalia drive demand for homogeneous sheet formats with welded seams. AgBB emissions certification filters import competition.
- Hardwood:Solid or engineered timber planks prized for heritage restoration and premium residential specification.
- Cork:Natural bark composite with inherent thermal insulation and sound absorption properties.
- Bamboo:Grass-derived strips processed into strand-woven or horizontal grain formats.
- Stone:Ceramic, porcelain, or natural stone tiles specified for wet zones and high-abrasion commercial entryways.
Laminate leads volumes today; vinyl is gaining share fastest.
Application:
Cost tier stratification separates specification-driven institutional projects from price-sensitive residential replacement cycles.
- Residential Buildings:Single-family and multi-family housing units undergoing renovation or new construction. North Rhine-Westphalia municipal housing associations bundle flooring into facade insulation contracts, creating integrated thermal-acoustic demand clusters.
- Commercial Complexes:Office, retail, and mixed-use developments requiring rapid installation and lease-cycle durability. Click-lock floating systems compress fit-out timelines where skilled installer scarcity bites hardest.
- Educational Institutes:Schools and universities with strict VOC procurement policies and heavy foot traffic.
- Hospitality Venues:Hotels and restaurants balancing aesthetic specification with maintenance economics.
- Sports Facilities:Gymnasiums and recreation centers requiring shock absorption and point-load resistance.
- Public Infrastructure:Transit stations, government buildings, and healthcare facilities with extended durability requirements.
Residential Buildings anchor volume; Commercial Complexes show steepest expansion trajectory.
Installation Method:
Volume concentration favors reduced-skill formats as German chamber of commerce apprenticeship pipelines constrict.
- Click Lock:Mechanical edge profiling enabling tool-free assembly and disassembly without adhesives. Contractors across Hamburg and Berlin metro corridors specify these for multi-unit residential projects where timeline compression outweighs material cost premiums.
- Floating:Interlocking planks or tiles installed over underlayment without structural attachment to subfloor. Baden-Württemberg building authorities enforce GEG thermal standards most stringently here, fragmenting regional product configurations.
- Glue Down:Direct adhesive bonding requiring certified craftspeople and extended curing periods.
- Nail Down:Traditional hardwood fastening demanding skilled carpentry and timber subfloor compatibility.
- Loose Lay:Friction-fit systems relying on perimeter retention and weight distribution.
- Staple Down:Pneumatic fastening for engineered wood over plywood substrates.
Click Lock commands the largest installed base; Floating shows the most rapid adoption curve.
End User:
Customer type determines procurement channel and technical support intensity, from self-directed homeowner purchases to specification-driven institutional tenders.
- Contractors:Mid-sized installation firms purchasing through distributor apps with real-time stock visibility. North Rhine-Westphalia's dense contractor networks support platform economics absent in eastern federal states.
- Homeowners:Direct retail purchasers influenced by digital surface replication quality and DIY installation feasibility.
- Interior Designers:Specification professionals selecting materials for heritage restoration and premium residential projects.
- Real Estate Developers:Volume purchasers standardizing across multi-unit portfolios.
- Facility Managers:Maintenance-focused buyers prioritizing lifecycle cost and replacement modularity.
- Retailers:Distribution intermediaries curating assortments for local market conditions.
Contractors drive the highest transaction velocity; Interior Designers command the steepest premium capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German floor covering manufacturing traces its industrial lineage to the post-war reconstruction era, when domestic wood processing and chemical industries converged to supply rebuilding demand across Central Europe. This heritage established specialized clusters that persist today.
Bavaria
Munich and Nuremberg metro corridors drive elevated demolition-rebuild rates that concentrate demand for moisture-tolerant flooring in multi-family basement installations. The federal GEG thermal regulations receive their most stringent enforcement from Bavarian building authorities, fragmenting product configurations toward factory-bonded underlayment systems. Parador GmbH leverages its domestic manufacturing footprint to sustain rapid fulfillment for trade customers across this southern cluster.
North Rhine-Westphalia
Düsseldorf and Cologne municipal housing associations bundle flooring replacement into facade insulation contracts, creating captive demand for integrated thermal-acoustic systems. Dense contractor networks here support direct-to-trade digital procurement platforms with real-time stock visibility absent in eastern federal states. The region's healthcare corridor specifications pull specialized rubber-vinyl compounds for hospital and eldercare facility applications.
Baden-Württemberg
Stuttgart's manufacturing heritage sustains precision-engineered laminate demand among specification professionals serving heritage restoration projects. GEG thermal standards enforcement creates regional product fragmentation toward multi-layer rigid core constructions. The state's vocational training infrastructure partially offsets skilled installer scarcity affecting traditional parquet application methods.
Hamburg
The port city's logistics advantages position it as a distribution node for click-lock floating systems serving northern renovation corridors. Photorealistic embossed-in-register laminate surfaces gain traction among specifiers navigating listed building interior restrictions where solid timber replacement faces preservation constraints. Contractors here specify reduced-skill formats to compress multi-unit residential project timelines.
Berlin-Brandenburg
Capital region housing stock renewal concentrates demand for cost-efficient laminate and vinyl segments in multi-family renovations. Digital procurement platform adoption advances rapidly among mid-sized installation firms purchasing through distributor apps with next-day fulfillment guarantees. The metropolitan density supports platform economics that remain underdeveloped in surrounding eastern federal states.
Germany Floor Covering Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification intensity and thermal performance engineering, with DIN and AgBB compliance thresholds filtering import competition and rewarding domestic testing infrastructure. The vendor base clusters around three strategic archetypes: integrated domestic manufacturers with closed-loop logistics, specialized compound formulators serving healthcare and education verticals, and multinational volume producers navigating multi-tier product positioning. Consolidation pressure operates through M&A activity targeting thermal-acoustic system capabilities, while portfolio diversification into bio-based binder formulations opens specification pathways in municipal procurement.
Among Germany-based fabricators, Parador GmbH and Nora Systems GmbH exemplify contrasting strategic positions—Parador occupying the integrated domestic manufacturer archetype with rapid fulfillment infrastructure, Nora Systems anchoring the specialized compound formulator tier through rubber and vinyl expertise for institutional verticals. Tarkett S.A. represents the multinational volume producer archetype, competing across multiple product tiers while navigating stringent indoor air quality certifications. These three entities collectively illustrate the competitive tension between domestic responsiveness and scale-driven cost positioning that defines procurement dynamics across German distribution channels.
| Leading Market Players |
|---|
| Parador GmbH |
| Nora Systems GmbH |
| Tarkett S.A. |
| HARO Cork Floors |
| Gerflor |
| Forbo Flooring GmbH |
| Egger Group |
| PolyFlor |
| Mohawk Industries (Quick-Step) |
| Others |
Supply & Pricing Matrix
GEG thermal mandates pulling specification toward factory-bonded underlayment systems are forcing manufacturers to absorb certification and materials costs or cede share to domestic competitors with closed-loop logistics. This demand-side pressure compresses mid-tier margins while rewarding integrated producers who control thermal-layer sourcing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates AgBB-certified thermal-acoustic systems from commodity laminates and entry vinyl. Price differentiation rests on certification grade and factory-bonded underlayment integration. Cost compression in standard-tier laminates is intensifying because propylene and plasticizer volatility squeezes compound suppliers. Municipal housing associations in North Rhine-Westphalia exhibit highest price sensitivity; heritage restoration specifiers in Baden-Württemberg show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Belgian and Dutch petrochemical hubs supplying plasticizers and PVC resins to German vinyl processors. Raw material dependencies draw from Nordic timber for HDF cores, Middle Eastern oil derivatives for polymer feedstocks, and Portuguese cork for thermal underlayment. Tariff exposure on Chinese laminate imports threatens cost-competitive supply. Distribution runs through Düsseldorf and Hamburg logistics nodes serving dense contractor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through biobased binder adoption that commands premium positioning in education and municipal procurement while reducing petrochemical cost exposure.
For Market Incumbents: Extend thermal-acoustic system capabilities through backward integration into cork underlayment production. Consolidate distributor relationships in North Rhine-Westphalia before digital procurement platforms commoditize trade channels. Ceramic tile substitution in premium residential wet zones threatens hardwood positioning; defend through AgBB-certified moisture-tolerant laminate introductions. For New Entrants and Emerging Players: Direct-to-trade digital procurement routes in Berlin-Brandenburg offer lowest competitive density against established distributor incumbents. Target municipal housing association bundled contracts in eastern federal states where platform economics remain underdeveloped. Lead with click-lock floating systems that compress installation timelines where skilled labor scarcity bites hardest. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized compound formulators holding healthcare and education vertical relationships. Long-term viability favors manufacturers with biobased adhesive pipelines and closed-loop packaging infrastructure aligned with evolving federal circular economy rules. Watch AgBB certification timeline compression as signal for import competition inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Biobased Binder Development | Soy and lignin adhesive formulations meeting AgBB thresholds open education and municipal specification pathways. |
| Thermal-Acoustic System Integration | Factory-bonded underlayment configurations capture GEG-mandated renovation demand in Bavaria and North Rhine-Westphalia. |
| Direct-to-Trade Platform Launch | Digital procurement with real-time stock visibility displaces traditional wholesale relationships among mid-sized contractors. |
| Closed-Loop Packaging Infrastructure | Recyclable palletization and reduced plastic film align with evolving federal circular economy requirements. |
| Healthcare Vertical Specialization | Specialized rubber-vinyl compounds for acoustic dampening specifications capture hospital and eldercare facility demand. |
Research Methodology
Direct dialogue with flooring procurement managers at municipal housing associations, installation contractors in Hamburg and Berlin corridors, distributor operations heads, and technical specification professionals at Parador GmbH and Nora Systems GmbH grounded qualitative findings. Secondary validation drew from DIN standards documentation, AgBB emissions test registries, GEG regulatory filings, federal circular economy packaging rule drafts, and trade data through German customs authorities. Bottom-up demand modeling triangulated against top-down construction permit analysis.
Segmented outputs across product type, application, installation method, and end user combined with regional demand clustering to generate volume and value trajectories throughout the forecast period. CAGRs derived from housing stock renewal rate projections, GEG enforcement intensity by federal state, and healthcare facility modernization pipelines. Modeled inputs included skilled labor scarcity indices and petrochemical price volatility bands.
The model assumes a particular technology adoption path; alternative pathways for biobased adhesive convergence would alter the outlook if lignin formulation costs compress faster than projected. Forecasts reflect assumptions around GEG thermal standard enforcement consistency and circular economy packaging rule implementation timing. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
GCC Floor Covering Market
Flooring, Carpets, and Rugs
India Wood Flooring Market
Flooring, Carpets, and Rugs
Europe Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Resilient Flooring Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
North America Laminate Flooring Market
Flooring, Carpets, and Rugs
China Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Asia Pacific Flooring Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
Global Soft Covering Flooring Market
Flooring, Carpets, and Rugs
Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
Luxury Vinyl Tile (LVT) Flooring Market
Flooring, Carpets, and Rugs
Flooring for Tile and Stone Market
Flooring, Carpets, and Rugs
Global Vinyl Floor Covering Market