
 Australia & New Zealand Flooring Market | 2026-2036
Australia & New Zealand Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Australia & New Zealand Flooring Market Insights
Premium commercial-grade specifications is rotating toward engineered hardwood and high-performance vinyl across Australia & New Zealand. Godfrey Hirst Australia leverages vertical integration from fiber production to retail distribution. Armstrong Flooring Australia anchors its position through specification relationships with national hospitality chains. Altro APAC specializes in safety flooring for healthcare and wet-environment applications.
Australia & New Zealand flooring encompasses finished surface materials installed for foot traffic, spanning wear-layer thicknesses from 0.3 mm residential vinyl to 2.5 mm commercial safety flooring, manufactured through calendering, extrusion, or timber milling processes to deliver structural support, acoustic dampening, and aesthetic finish in built environments. Carpet retains mature volume leadership in residential replacement cycles but carries thinner margins than specification-driven segments. Vinyl captures the fastest structural expansion, fueled by waterproof rigid-core formulations displacing laminate in moisture-prone commercial settings across both countries.
TGA building-product conformity requirements and Australia's National Construction Code, alongside New Zealand's Building Code compliance administered by MBIE, establish slip-resistance, fire-performance, and VOC-emission thresholds that filter import eligibility and shape domestic manufacturing priorities. The Australian Competition and Consumer Commission enforces product-safety recalls that elevate brand-accountability standards for distributed flooring lines. Stakeholders must track evolving biogenic-content thresholds in green-building certification schemes, as these rating tools increasingly determine specification outcomes in government and institutional procurement.
Market Dynamics
Hospitality renovation pipelines across Sydney and Auckland are accelerating specification-grade vinyl and hardwood procurement, while Australia's National Construction Code updates on slip resistance and fire ratings are compressing product certification timelines for domestic and import suppliers alike.
Growth Catalysts
- Queensland residential corridor expansion:Population inflows into Brisbane and Gold Coast are driving new-build flooring volumes across detached housing and multi-residential developments.
- NCC slip-resistance mandates:Australia's National Construction Code updates are forcing specification upgrades in commercial wet environments, lifting safety flooring demand in aged care and hospital sectors.
- Rigid-core vinyl technology:Waterproof SPC and WPC formulations are capturing laminate's historical share in moisture-prone settings across both countries.
Market Restraints
- Timber input cost volatility:Australian native hardwood supply constraints and shipping rate fluctuations from Southeast Asian engineered timber sources are compressing margin stability.
- Import certification friction:TGA building-product conformity requirements and extended MBIE compliance timelines in New Zealand are filtering lower-tier Asian suppliers from eligibility pools.
- Ceramic tile substitution in premium residential:Large-format porcelain is capturing share in high-end Sydney and Melbourne renovations where thermal mass and longevity outweigh timber aesthetics.
Strategic Opportunities
- Auckland commercial precinct densification:Central business district rezoning and transit-oriented development are expanding specification-grade flooring procurement pools for mixed-use towers.
- Biogenic-content thresholds in Green Star certification:New Zealand's NZGBC and Australia's GBCA rating tools are creating preferential procurement pathways for low-carbon timber and recycled-content vinyl.
- Direct-to-contractor digital platforms:B2B marketplaces are compressing distributor layers in residential replacement cycles, enabling margin capture by manufacturers with logistics scale.
Industry Challenges
- Fire-rating certification backlog:Third-party testing laboratory capacity constraints in Australia are extending product launch timelines by four to six months for imported rigid-core lines.
- Skilled installation labor scarcity:Subcontractor shortages in Auckland and Perth are delaying project completion and inflating fit-out costs for commercial clients.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia & New Zealand Flooring Market |
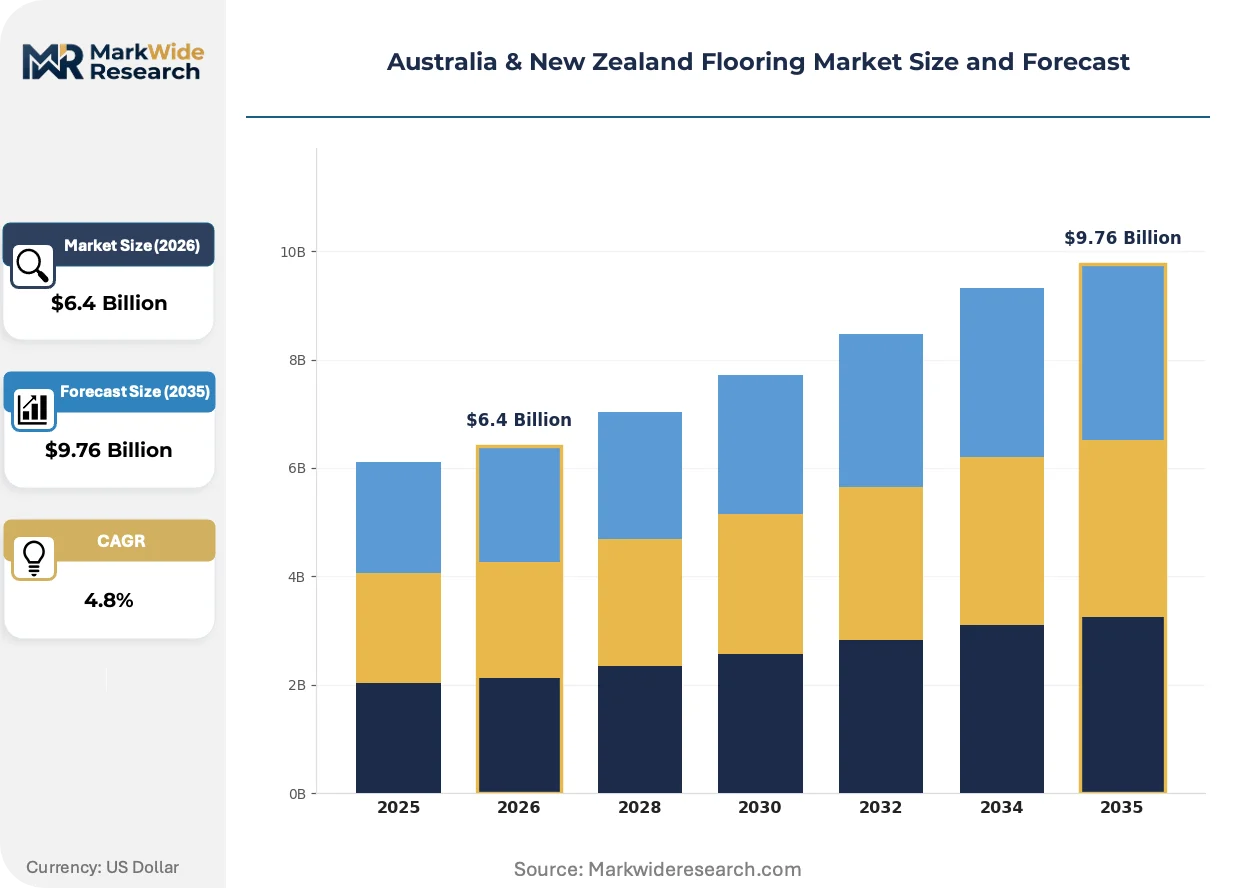
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $9.76 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Laminate, Vinyl, Hardwood End User: Residential, Commercial, Industrial, Hospitality Material: Polypropylene, PVC, Wood, Bamboo Installation Type: Glue-Down, Floating, Nail-Down, Click-Lock |
| Companies Covered | Sika Australia, Antiskid Industries, Godfrey Hirst Australia Pty. Ltd., Multiblast Flooring Pty. Ltd., Bethell Flooring, Armstrong Flooring Australia, Roxset Australia, HARO Flooring New Zealand, Altro APAC Pty. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia & New Zealand Flooring Market Trends and Innovations
Material science advances and procurement digitization are compressing traditional product lifecycles while elevating performance specifications in commercial segments across both countries.
Rigid-core SPC flooring with integrated acoustic underlayment is displacing traditional engineered timber in multi-residential and hospitality specifications where impact sound transmission ratings determine code compliance. Australian developers in Sydney and Melbourne are specifying these systems at accelerating rates for apartment towers above retail podiums. The shift is compressing demand for separate underlay procurement and reshaping distributor inventory profiles toward pre-integrated systems.
MBIE in New Zealand and Australia's ACCC are tightening product-safety recall protocols for flooring adhesives and surface coatings with elevated VOC emissions. The regulatory pressure is forcing reformulation investments among import-dependent distributors and elevating compliance costs for smaller retail chains. Healthcare and education procurement panels in both countries are now requiring third-party VOC certification as a mandatory pre-qualification criterion.
Architects and facilities managers are consolidating flooring specifications around multi-performance platforms that bundle slip resistance, acoustic dampening, and biogenic-content credentials into single product lines. This bundled-performance procurement model is displacing single-attribute selection criteria that historically prioritized upfront cost. Government and institutional tenders in Queensland and Auckland are leading this consolidation, with private commercial following twelve to eighteen months behind.
Australia & New Zealand Flooring Market Segmentation
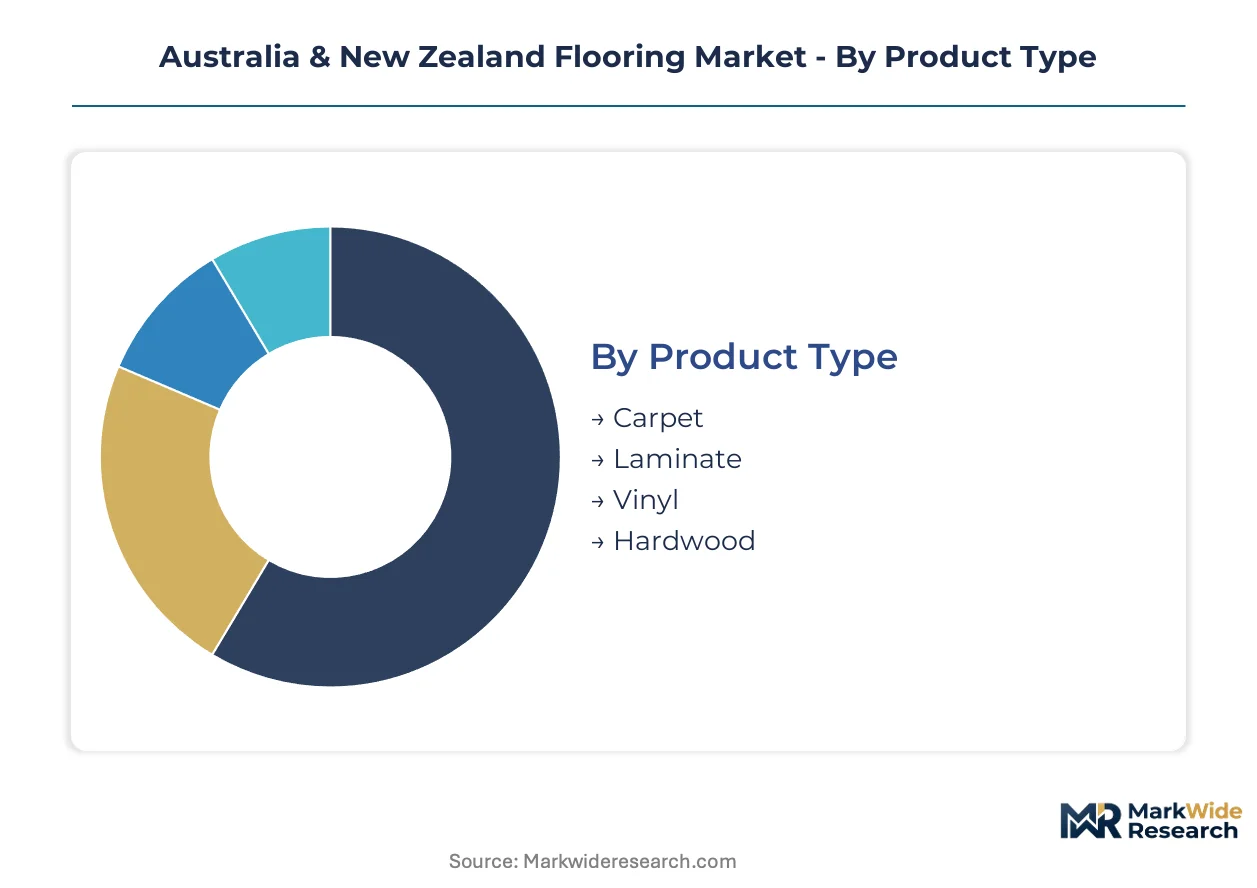
Flooring procurement across Australia and New Zealand fragments across performance specifications, installation logistics, and end-use compliance requirements. Understanding segment boundaries reveals where specification-grade premiums concentrate versus where price competition dominates volume.
Product Type:
Domestic manufacturing anchors carpet and hardwood supply chains, while vinyl and laminate sourcing leans heavily on Southeast Asian import channels. TGA certification timelines and MBIE compliance requirements create divergent entry barriers across these four product streams.
- Carpet:Tufted and woven constructions from wool and synthetic fiber retain dominant share in residential replacement cycles across Australian suburbs. Queensland's detached housing corridor and Auckland's established neighborhoods sustain consistent demand, though margin compression from import alternatives limits domestic manufacturer pricing power.
- Vinyl:Rigid-core SPC and WPC formulations with integrated acoustic underlayment are displacing traditional engineered timber in multi-residential towers above retail podiums across Sydney and Melbourne. Waterproof performance satisfies NCC slip-resistance mandates in aged care and hospital wet environments, accelerating specification-grade procurement.
- Hardwood:Australian native species and imported engineered timber serve premium residential renovations and commercial hospitality fit-outs where biogenic-content credentials factor into Green Star procurement decisions.
- Laminate:Moisture-susceptible fiberboard core limits deployment to dry interior environments, with rigid-core vinyl capturing historical share in moisture-prone settings across both countries.
Carpet commands the established base. The steepest expansion runs through vinyl.
End User:
Cost tiers separate specification-driven commercial procurement from price-sensitive residential replacement, with hospitality and industrial occupying intermediate positions on performance-per-dollar metrics.
- Residential:Replacement cycles in established Australian suburbs and Auckland neighborhoods drive volume through retail and direct-to-contractor channels. Carpet and laminate dominate detached housing, while multi-residential shifts toward rigid-core vinyl for acoustic compliance.
- Commercial:Office towers and retail precincts in Sydney, Melbourne, and Auckland's central business districts prioritize safety flooring and engineered hardwood with documented fire ratings and VOC certifications. MBIE and TGA compliance requirements filter supplier pools toward established distributors with testing laboratory relationships.
- Hospitality:Renovation pipelines across Sydney and Auckland hotels and restaurants are lifting specification-grade vinyl and hardwood volumes, with procurement panels bundling slip resistance, acoustic dampening, and biogenic-content credentials into single product lines.
- Industrial:Warehouse and manufacturing facilities prioritize durability and chemical resistance over aesthetic finish, with safety flooring dominating wet-process environments.
Residential absorbs the volume base. Hospitality is climbing the fastest on renovation-driven specification upgrades.
Material:
Supply concentration varies sharply: polypropylene carpet fiber production clusters in Australia, while PVC resin and bamboo processing remain import-dependent from Southeast Asian sources.
- Polypropylene:Synthetic fiber dominates Australian carpet manufacturing, with Godfrey Hirst's vertical integration from fiber production through retail distribution capturing cost advantages in residential segments.
- PVC:Vinyl resin formulations span flexible sheet, luxury vinyl tile, and rigid-core constructions, with import certification friction under TGA building-product conformity requirements elevating compliance costs for smaller distributors.
- Wood:Native Australian hardwood supply constraints and shipping rate volatility from Southeast Asian engineered timber sources compress margin stability across the value chain.
- Bamboo:Rapid-renewal grass species serve sustainability-focused procurement in green-building certification schemes, though limited domestic processing capacity constrains scale.
Polypropylene anchors the volume foundation. PVC is gaining share fastest on rigid-core technology adoption.
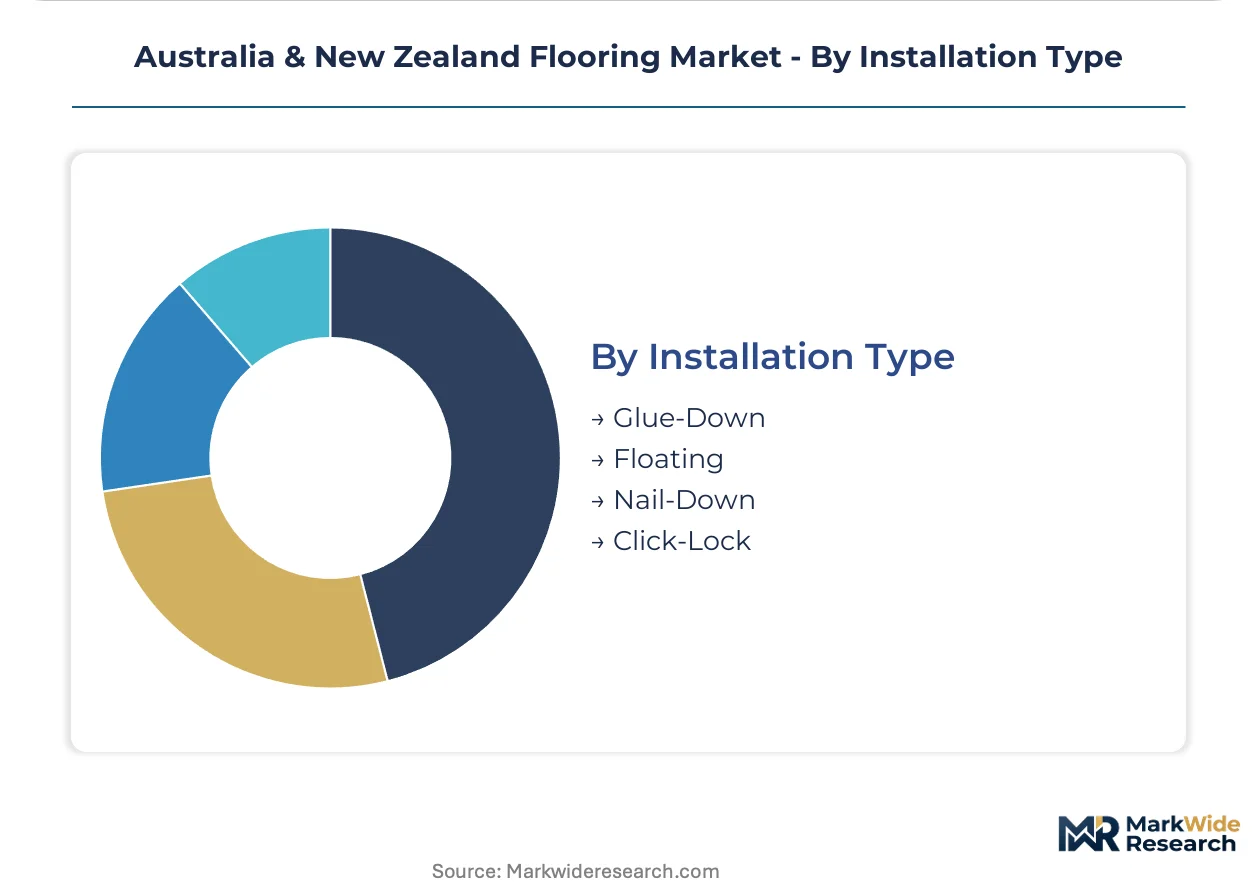
Installation Type:
Customer type separates professional-specified systems from retail-accessible solutions, with skilled labor scarcity in Auckland and Perth creating completion delays and cost inflation for complex glue-down and nail-down methods.
- Glue-Down:Permanent adhesion systems dominate commercial safety flooring and sheet vinyl in healthcare and aged care facilities where NCC slip-resistance mandates require certified installation protocols.
- Floating:Interlocking systems without subfloor attachment enable rapid deployment in residential replacement cycles and multi-residential towers where acoustic underlayment integration satisfies impact sound transmission ratings.
- Nail-Down:Traditional solid hardwood installation persists in premium residential renovations where thermal mass and longevity outweigh upfront cost considerations, though ceramic tile substitution pressures this segment in Sydney and Melbourne high-end markets.
- Click-Lock:Tool-free assembly characterizes rigid-core vinyl and laminate retail products, with direct-to-contractor digital platforms compressing distributor layers and enabling margin capture by manufacturers with logistics scale.
Floating installations command the established base. Click-Lock is expanding most quickly through digital channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence defines the Australia & New Zealand flooring trade balance, with rigid-core vinyl and engineered timber arriving primarily from Southeast Asian manufacturing clusters while domestic production concentrates on carpet fiber and native hardwood processing.
New South Wales
Sydney's hospitality renovation pipeline is accelerating specification-grade vinyl and hardwood procurement for hotel and restaurant fit-outs. TGA building-product conformity requirements filter import eligibility through extended certification timelines. The Parramatta commercial precinct and inner-city apartment towers are driving multi-residential rigid-core specification.
Victoria
Melbourne's central business district office towers prioritize safety flooring with documented fire ratings and VOC certifications for commercial leasing compliance. Australia's National Construction Code updates on slip resistance tighten product certification requirements for aged care and hospital sectors. Southbank and Docklands mixed-use developments are expanding engineered timber specification pools.
Queensland
Population inflows into Brisbane and Gold Coast are driving new-build flooring volumes across detached housing and multi-residential developments. Green Star certification biogenic-content thresholds create preferential procurement pathways for low-carbon timber. The Sunshine Coast residential corridor is seeing accelerated carpet and laminate replacement cycles.
Western Australia
Perth's commercial construction recovery is lifting safety flooring demand for healthcare and education facilities under NCC compliance mandates. Skilled installation labor scarcity is delaying project completion and inflating fit-out costs for commercial clients. The Fiona Stanley Hospital precinct and suburban aged care developments concentrate specification activity.
New Zealand
Auckland's central business district rezoning and transit-oriented development are expanding specification-grade flooring procurement for mixed-use towers. MBIE compliance timelines filter lower-tier Asian suppliers from eligibility pools. The Christchurch rebuild pipeline continues sustaining commercial and institutional flooring volumes.
Australia & New Zealand Flooring Market Competitive Landscape
Concentration sits with vertically integrated domestic carpet manufacturers and specification-focused import distributors serving commercial compliance-driven segments. The vendor base stratifies across three tiers: large-scale fiber-to-retail integrators, mid-size specification distributors with testing laboratory relationships, and import-dependent retailers competing on price. Dominant competitive moves include backward integration into fiber production and strategic partnerships with hospitality procurement panels.
Among Australia-based manufacturers, Godfrey Hirst Australia Pty. Ltd. exemplifies the vertically integrated archetype with captive supply advantages, while Armstrong Flooring Australia occupies a position within the specification distributor tier. Altro APAC Pty. Ltd. represents the safety flooring specialist archetype serving healthcare and wet-environment applications. These three anchors illustrate how competitive positioning fragments across integration depth, specification relationships, and segment focus.
| Leading Market Players |
|---|
| Sika Australia |
| Antiskid Industries |
| Godfrey Hirst Australia Pty. Ltd. |
| Multiblast Flooring Pty. Ltd. |
| Bethell Flooring |
| Armstrong Flooring Australia |
| Roxset Australia |
| HARO Flooring New Zealand |
| Altro APAC Pty. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Rigid-core vinyl displacing engineered timber in moisture-prone commercial settings simultaneously redraws procurement geography toward Southeast Asian extrusion centers and compresses price premiums previously commanded by Australian hardwood distributors. This substitution dynamic funnels specification-grade volumes through import channels while domestic carpet manufacturers defend margin positions through captive fiber production.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in Australia & New Zealand flooring procurement. Price differentiation separates specification-grade products with TGA fire-rating certification from uncertified import alternatives and domestic retail-grade lines. Cost compression in the standard tier is intensifying because rigid-core vinyl imports from Vietnam and China are eroding laminate's historical price positioning. Residential replacement buyers exhibit highest price sensitivity, while hospitality procurement panels demonstrate lowest sensitivity given bundled-performance requirements.
Supply Chain Analysis
Container availability fluctuations on Southeast Asian trade lanes into Sydney and Melbourne ports are elevating landed cost volatility for rigid-core vinyl and engineered timber shipments. Manufacturing concentration centers on China, Vietnam, and Malaysia for vinyl resin formulations and bamboo processing, while Australian domestic production retains polypropylene carpet fiber and native hardwood milling. Raw material dependencies draw from PVC resin, synthetic fiber, and tropical timber feedstocks. Single-source vulnerability runs through Southeast Asian extrusion capacity for SPC core production. Distribution runs through national distributor networks with testing laboratory relationships serving commercial specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement patterns as direct-to-contractor digital marketplaces compress traditional distributor layers and enable manufacturers to capture margin through logistics scale rather than channel intermediation.
For Market Incumbents: Consolidate specification relationships with national hospitality chains and healthcare procurement panels before rigid-core vinyl commoditization erodes premium positioning. Deepen backward integration into fiber production to defend cost advantages against import-dependent competitors. Prioritize certification investment with TGA and MBIE to extend compliance timelines that filter lower-tier Asian suppliers from eligibility pools. For New Entrants and Emerging Players: Lead with Auckland commercial precinct densification as the most penetrable geography, where transit-oriented development is expanding specification-grade procurement pools faster than incumbent distributor coverage. Target Queensland residential corridor expansion for volume scale through direct-to-contractor digital platforms. Pursue biogenic-content credentialing as the primary go-to-market angle to access Green Star preferential procurement pathways. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specification distributors possessing testing laboratory relationships and hospitality panel access. Long-term viability hinges on regulatory compliance moats deepening rather than narrowing across the analysis window. Monitor MBIE and TGA certification timeline extensions as the inflection signal indicating import friction is structurally advantaging domestic or established import distributors over new market entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Production | Godfrey Hirst's captive polypropylene supply anchors cost advantages in residential carpet segments against import competition. |
| Certification Investment with TGA and MBIE | Extended fire-rating and slip-resistance compliance timelines filter lower-tier suppliers and protect specification-grade margins. |
| Direct-to-Contractor Digital Platform Launch | B2B marketplace penetration compresses distributor layers and enables manufacturers with logistics scale to capture replacement cycle volume. |
| Biogenic-Content Credentialing Program | NZGBC and GBCA rating tool alignment creates preferential procurement pathways for low-carbon timber in government tenders. |
| Acoustic Underlayment Integration | Pre-integrated SPC systems satisfy NCC impact sound transmission mandates in Sydney and Melbourne multi-residential towers. |
Research Methodology
Cross-validation between distributor procurement data and construction pipeline disclosures anchors the qualitative findings in this study. Primary interviews with flooring specification managers, hospitality procurement directors, healthcare facilities planners, and residential contractor networks were combined with secondary validation through TGA building-product conformity registers, MBIE compliance databases, and Australian Bureau of Statistics construction activity indices. Bottom-up volume estimates from product-type shipments were triangulated against top-down construction spend allocations across residential, commercial, and institutional end-use segments.
Sensitivity analysis around input cost volatility and regulatory timeline scenarios informs the projection framework. Segmentation dimensions modeled include product type, end-use sector, material composition, and installation method across the analysis window. CAGRs were derived from trend extrapolation of specification-grade procurement growth in hospitality renovation pipelines and residential corridor expansion, calibrated against historical elasticities of substitution between vinyl, timber, and laminate categories. Rigid-core technology adoption curves and biogenic-content threshold implementation timelines served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in Australian National Construction Code and New Zealand Building Code regimes; material policy shifts in slip-resistance mandates or VOC emission thresholds would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
China Luxury Vinyl Tile (LVT) Market
Flooring, Carpets, and Rugs
Europe Carpet and Rugs Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
United Arab Emirates Floor Covering Market
Flooring, Carpets, and Rugs
Canada Terrazzo Flooring Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Rugs Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
Europe Vinyl Flooring Market
Flooring, Carpets, and Rugs
Bamboo Flooring Market
Flooring, Carpets, and Rugs
Foam Flooring Products Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
India Laminate Flooring Market
Flooring, Carpets, and Rugs
Laminate Flooring Market
Flooring, Carpets, and Rugs
Flooring Wood Panels Market