
 Flooring for Tile and Stone Market | 2026-2036
Flooring for Tile and Stone Market Size, Share, and Industry Trends Forecast 2026-2036
Flooring for Tile and Stone Market Foresight
The capital-intensity divergence between integrated quarry-to-retail operators and asset-light distributors is unwinding traditional margin structures in tile and stone supply. Mohawk Industries leverages captive ceramic production across North American manufacturing bases to sustain cost advantages in porcelain tile. Shaw Industries Group anchors its competitive position through controlled distribution networks that dominate commercial contractor channels. Tarkett SA navigates European regulatory complexity with specialized compliance capabilities that differentiate its natural stone sourcing.
Flooring for tile and stone encompasses rigid surfacing materials installed over subfloors or wall structures, with porcelain tile achieving water absorption below 0.5 percent through vitrification at temperatures exceeding 1200°C, serving primarily to provide durable, hygienic, and aesthetically specified interior and exterior surfaces. Ceramic tile occupies mature volume pools in residential replacement cycles, while porcelain tile captures expanding share in commercial lobby applications where traffic density demands superior abrasion resistance. Natural stone concentrates margin in luxury property developer segments where quarry provenance and slab consistency command pricing premiums.
The EPA administers lead-safe certification requirements under RRP that shape contractor training and product specification in US renovation markets, while ISO 13006 and EN 14411 define dimensional and mechanical performance thresholds that govern cross-border tile trade. India's BIS certification mandate for ceramic tiles and China's GB/T 4100 national standards create parallel compliance tracks that influence manufacturing location decisions. Stakeholders must monitor regulatory divergence between North American and Asian certification regimes when allocating capital across quarry investments, kiln capacity, and distribution infrastructure.
Market Dynamics
The capital-intensity divergence between integrated quarry-to-retail operators and asset-light distributors is unwinding traditional margin structures in tile and stone supply. EPA lead-safe certification requirements under RRP and tightening ISO 13006 ceramic standards are forcing contractor training investments and manufacturing location decisions simultaneously.
Growth Catalysts
- Urban renovation corridors:China's municipal infrastructure renewal programs are concentrating demand in high-density residential replacement cycles. Shanghai and Guangzhou renovation zones absorb premium porcelain volumes.
- Smart city infrastructure zones:India's Ministry of Housing and Urban Affairs mandates ceramic surfacing in public transit terminals and municipal buildings under the Smart Cities Mission.
- Multi-family housing specifications:Residential builders across North America are expanding porcelain tile adoption in rental unit developments where durability requirements exceed ceramic performance thresholds.
Market Restraints
- Natural gas price volatility:Kiln operations in Italy and Spain face input cost pressure from European energy market fluctuations, compressing margins for vitrified tile producers.
- Quarry concentration risk:Premium marble and granite slab supply concentrates in Carrara, Italy and Minas Gerais, Brazil, creating single-source vulnerability for luxury property developers.
- Water absorption technical floor:Ceramic tile cannot achieve porcelain's sub-0.5% absorption rate, limiting its specification in commercial lobby and exterior cladding applications.
Strategic Opportunities
- India's BIS certification mandate:The Bureau of Indian Standards compulsory marking scheme for ceramic tiles creates compliance-based differentiation for certified importers.
- Digital printing convergence:Inkjet decoration technology combined with through-body porcelain is enabling realistic stone replication at lower quarry-dependent cost structures.
- Direct-to-contractor platforms:Specialized procurement channels are emerging to serve commercial installer networks, bypassing traditional distributor markups.
Industry Challenges
- Lead-safe installer certification:The EPA's RRP rule demands trained contractors for pre-1978 housing renovation, creating workforce pipeline constraints.
- Dual carbon compliance:China's MEE emission standards and EU CBAM carbon border adjustments require simultaneous kiln efficiency upgrades and emissions documentation.
- ISO 13006 testing timelines:Cross-border tile trade faces extended certification delays from dimensional and mechanical performance verification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flooring for Tile and Stone Market |
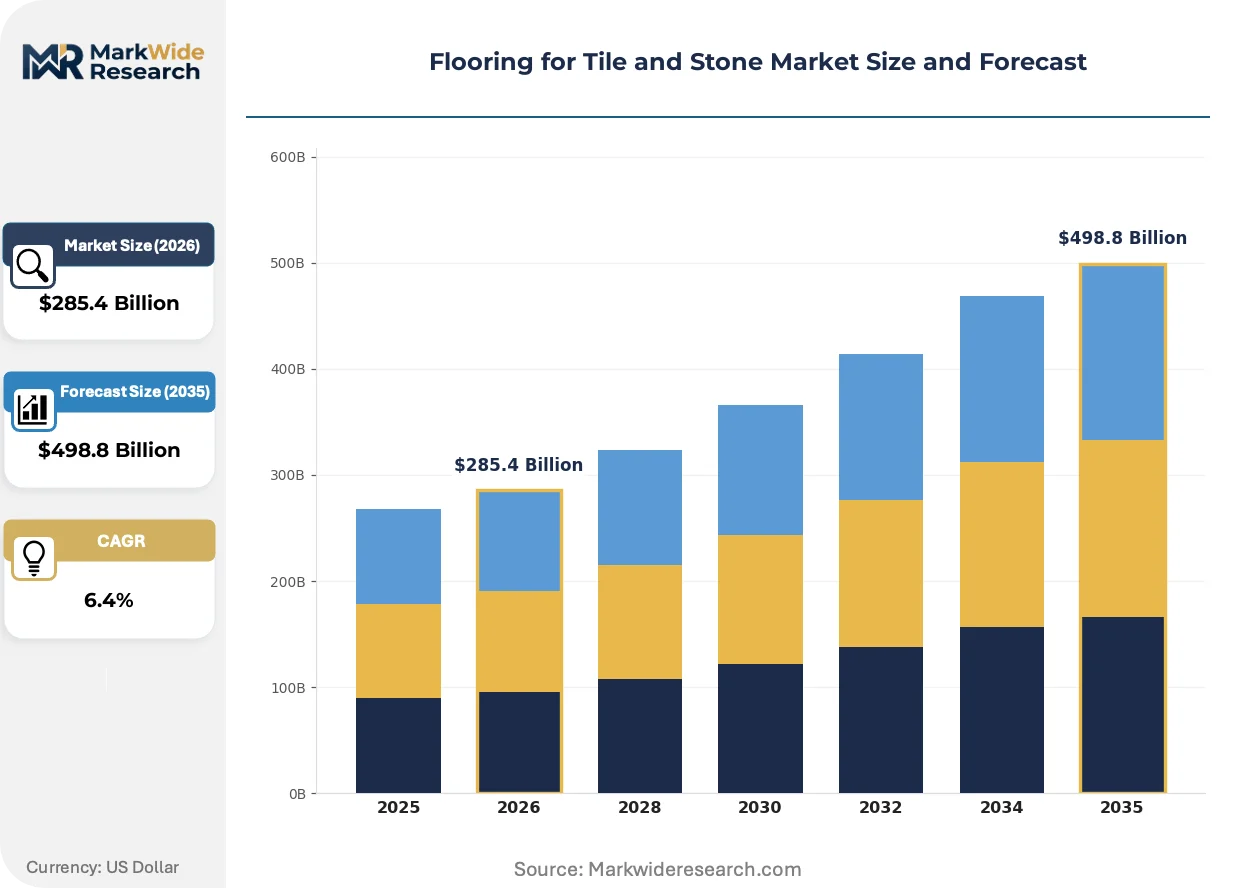
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $498.8 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Tile, Porcelain Tile, Natural Stone, Glass Tile, Composite Tile, Mosaic Tile Installation Method: Thinset Mortar, Dry-Set Mortar, Self-Adhesive, Loose Lay, Floating Floor, Cement Backer Board End User: Residential Builders, Commercial Contractors, Interior Designers, Facility Managers, Property Developers Application: Indoor Flooring, Outdoor Patios, Wall Cladding, Countertops, Bathrooms, Commercial Lobbies |
| Companies Covered | Mohawk Industries, Inc., Shaw Industries Group, Inc., Tarkett SA, Forbo Holding AG, Daltile Corporation, Polycor Inc., Emser Tile, Bedrosians Tile and Stone, MSI International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flooring for Tile and Stone Market Shifts & Advancements
Digital manufacturing and regulatory compliance automation are actively reshaping competitive positioning in tile and stone. Three developments merit specific attention.
Large-format thin porcelain slabs are decomposing traditional natural stone specification in commercial facade and interior wall applications. Hospitality developers in Dubai and Singapore are specifying 3mm-thick gauged porcelain for high-rise cladding where weight reduction drives structural cost savings. This material is decomposing marble and granite volume in luxury hotel lobbies by delivering equivalent aesthetic impact at reduced installation labor and substrate reinforcement expense.
REACH chemical restrictions and the EU Green Deal's embodied carbon disclosure requirements are tightening raw material traceability obligations for European tile importers. Manufacturers must now document talc, feldspar, and pigment supply chains to satisfy Substance of Very High Concern screening. Italian ceramic districts are responding by consolidating supplier audits and investing in closed-loop water recycling to demonstrate compliance.
Commercial contractor buying collectives are aggregating procurement volumes to extract direct pricing from manufacturer sales teams. These groups bypass traditional distributor networks in Florida, Texas, and California commercial construction markets. The shift concentrates specification influence with project management firms rather than independent flooring dealers, compressing channel margins and rewarding suppliers with captive manufacturing scale.
Flooring for Tile and Stone Market Segmentation
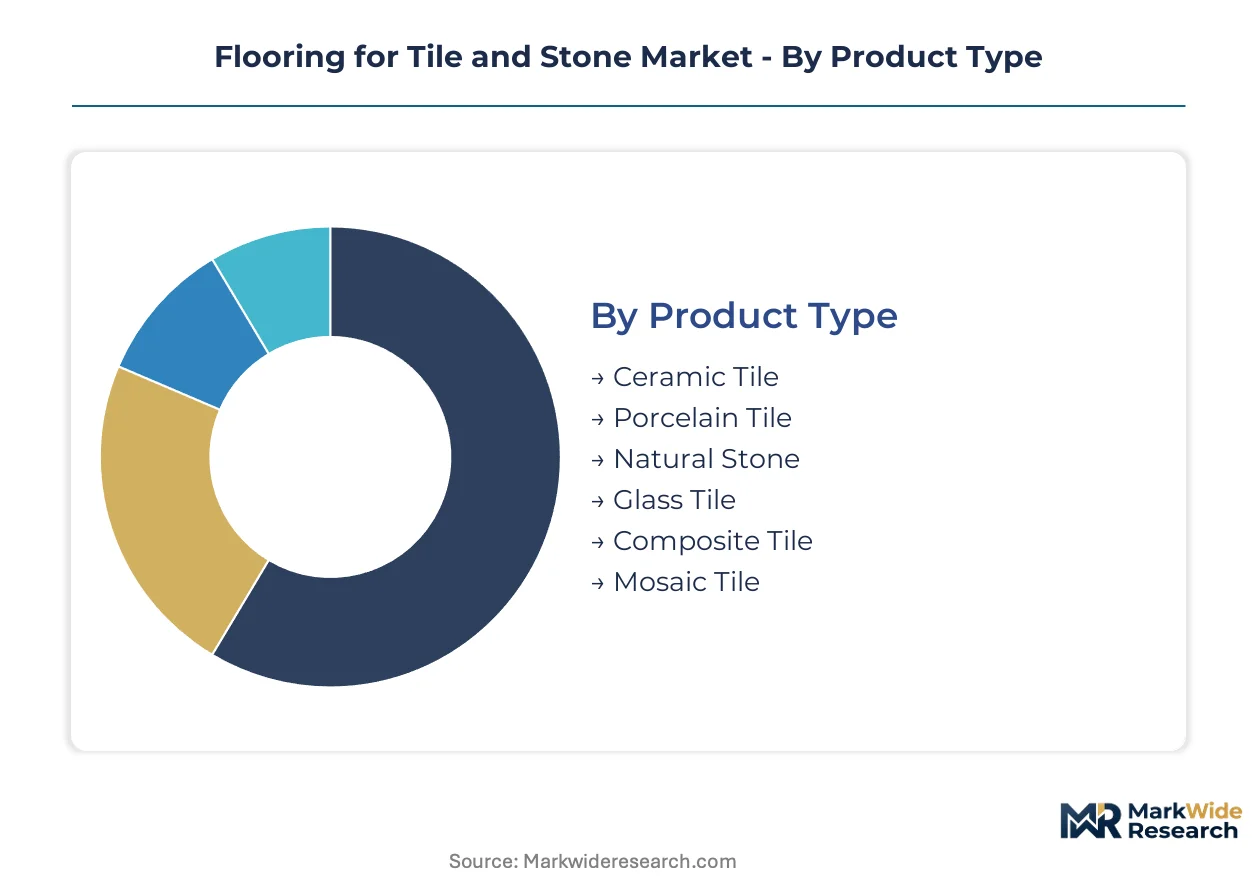
Segmentation in tile and stone flooring exposes where capital efficiency and specification influence diverge across product physics, installation labor intensity, and end-user procurement power. Understanding these fault lines clarifies where margin accumulates and where volume concentrates.
Product Type:
Porcelain tile commands the widest margin spread between commodity-grade production and premium specification, while natural stone extracts scarcity rents from quarry-controlled supply.
- Ceramic Tile:Fired at lower temperatures than porcelain, ceramic achieves 3-10% water absorption through porous body composition. Residential replacement cycles in China's urban renovation corridors absorb volume where cost sensitivity dominates specification decisions.
- Porcelain Tile:Vitrification above 1200°C drives sub-0.5% water absorption through full body density. Commercial lobby applications in India's smart city infrastructure zones specify porcelain where abrasion resistance thresholds exceed ceramic performance limits.
- Natural Stone:Quarry-sourced marble and granite command luxury developer premiums through provenance documentation and slab consistency grading.
- Glass Tile:Recycled content formulations serve backsplash and accent wall niches where translucency drives aesthetic specification.
- Composite Tile:Engineered stone blends compress manufacturing variation while mimicking natural material appearance at controlled cost structures.
- Mosaic Tile:Small-format pieces concentrate artisan labor in decorative pool and spa applications where pattern complexity justifies premium pricing.
Ceramic tile holds installed capacity across residential renovation markets. Porcelain tile is rotating up the share rankings in commercial specification channels.
Installation Method:
Labor productivity and substrate preparation requirements create cost tier separation between bonded systems and floating alternatives.
- Thinset Mortar:Portland cement-based adhesive bonds tile directly to prepared substrates with polymer-modified flexibility. Commercial contractors in Florida and Texas specify thinset for large-format porcelain where dimensional stability demands superior shear resistance.
- Dry-Set Mortar:Unmodified cement-sand mixtures serve low-traffic residential applications where cost compression outweighs performance margins.
- Self-Adhesive:Pressure-sensitive backing enables rapid installation in retail refresh programs where downtime minimization drives method selection.
- Loose Lay:Interlocking or weighted systems bypass adhesive curing for temporary or renovation-overlay applications.
- Floating Floor:Click-lock porcelain tile systems expand into multi-family housing where speed-to-lease pressures compress construction schedules.
- Cement Backer Board:Underlayment panels manage moisture vapor transmission in wet-area applications where substrate integrity governs warranty compliance.
Thinset mortar dominates commercial specification. Floating floor methods are gaining traction fastest in residential builder procurement.
End User:
Procurement scale and specification authority concentrate differently across project ownership structures and professional service relationships.
- Residential Builders:Volume aggregators in North American multi-family developments standardize porcelain specifications across unit counts exceeding 500 doors.
- Commercial Contractors:Project management firms in California and Texas commercial markets consolidate buying collectives that extract direct manufacturer pricing.
- Interior Designers:Specification influence concentrates in luxury residential and hospitality segments where aesthetic authority overrides cost engineering.
- Facility Managers:Institutional owners in healthcare and education verticals prioritize lifecycle cost over first-cost in maintenance-intensive environments.
- Property Developers:Mixed-use project sponsors balance material cost against LEED certification points and tenant attraction premiums.
Commercial contractors command procurement volume leverage. Interior designers are climbing fastest in specification influence rankings.
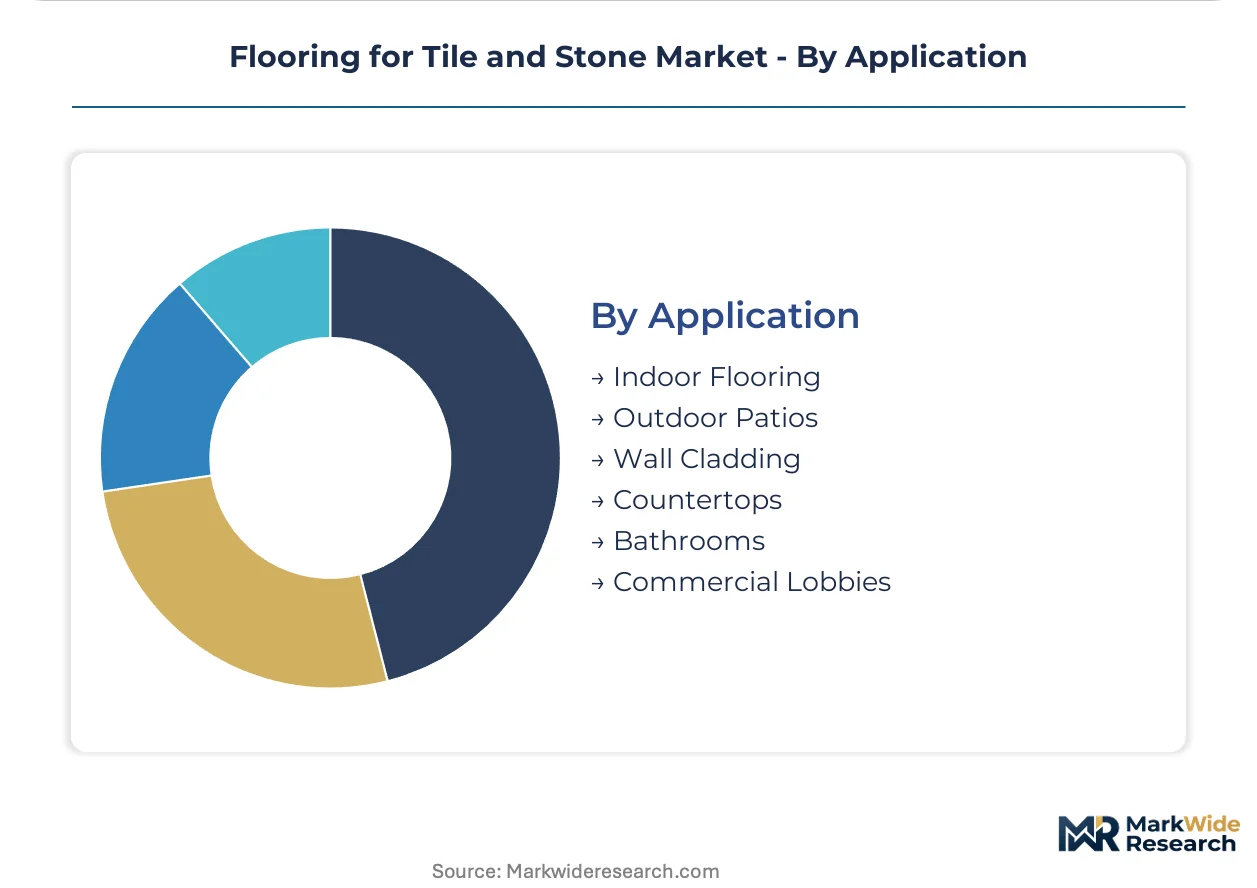
Application:
Traffic density and exposure severity determine performance thresholds that filter product eligibility.
- Indoor Flooring:Residential and light commercial spaces absorb ceramic and porcelain volumes where abrasion indices below PEI 4 suffice.
- Outdoor Patios:Freeze-thaw cycling and moisture exposure specify porcelain or natural stone with low water absorption and slip resistance ratings.
- Wall Cladding:Large-format thin porcelain slabs displace natural stone in high-rise facades where weight reduction generates structural cost savings.
- Countertops:Quartz composite and granite concentrate in kitchen and bath applications where stain resistance and heat tolerance govern selection.
- Bathrooms:Wet-area specifications demand glazed porcelain or glass tile with verified slip resistance coefficients.
- Commercial Lobbies:Traffic density exceeding 1000 pedestrians daily specifies PEI 5 porcelain or natural stone with demonstrated abrasion resistance.
Indoor flooring holds installed base volume. Wall cladding applications are expanding most quickly as gauged porcelain technology matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India's smart city infrastructure zones demonstrate the highest price elasticity, while luxury property developers in Italy's quarry districts absorb scarcity premiums with minimal volume sensitivity. This demand-elasticity contrast shapes regional investment allocation across kiln capacity and distribution infrastructure.
China
Shanghai and Guangzhou renovation corridors concentrate premium porcelain absorption as municipal infrastructure renewal programs accelerate residential replacement cycles. The GB/T 4100 national standards and MEE emission standards impose dual carbon compliance obligations on kiln operators. Foshan's ceramic manufacturing cluster is upgrading digital printing capabilities to satisfy domestic specification demand while documenting supply chain traceability for EU CBAM carbon border adjustments.
United States
Multi-family housing developers in Florida and Texas standardize porcelain specifications across rental unit portfolios exceeding 500 doors. EPA lead-safe certification requirements under the RRP rule shape contractor training investments and workforce pipeline constraints. California commercial contractor buying collectives are consolidating procurement volumes to extract direct manufacturer pricing, bypassing traditional distributor markups.
India
The Smart Cities Mission mandates ceramic surfacing in public transit terminals and municipal buildings across high-density urban zones. BIS certification compulsory marking schemes for ceramic tiles create compliance-based differentiation for certified importers. Gujarat's ceramic manufacturing belt is expanding vitrified tile capacity to serve domestic infrastructure specifications while navigating extended ISO 13006 testing timelines for export verification.
Italy
Carrara's marble quarry provenance commands luxury developer premiums through slab consistency grading and documented provenance. REACH chemical restrictions and EU Green Deal embodied carbon disclosure requirements tighten raw material traceability for talc, feldspar, and pigment supply chains. Sassuolo's ceramic district is consolidating supplier audits and investing in closed-loop water recycling to satisfy Substance of Very High Concern screening protocols.
United Arab Emirates
Hospitality developers in Dubai specify large-format thin porcelain slabs for high-rise cladding where weight reduction generates structural cost savings. The country's national building codes align with international performance standards while permitting rapid specification adoption. Jebel Ali's logistics corridor is positioning as a re-export hub for gauged porcelain serving Saudi Arabian and Qatari luxury construction markets.
Flooring for Tile and Stone Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in tile and stone supply. Quarry-to-retail operators sustain cost advantages through captive ceramic production and controlled distribution networks, while asset-light distributors compete on specification breadth and logistics speed. Three archetypes dominate: integrated manufacturers with backward kiln control, specialized natural stone sourcers with quarry relationships, and procurement platforms serving commercial contractor collectives. Competitive intensity centers on manufacturing scale expansion and direct-channel bypass strategies.
Among North American integrated operators, Mohawk Industries, Inc. and Shaw Industries Group, Inc. occupy positions exemplifying captive production advantages across manufacturing bases. Tarkett SA represents the European specialist archetype, navigating regulatory complexity with compliance capabilities that differentiate natural stone sourcing. These three companies anchor the tiered structure where scale-driven manufacturing and regulatory specialization determine margin capture.
| Leading Market Players |
|---|
| Mohawk Industries, Inc. |
| Shaw Industries Group, Inc. |
| Tarkett SA |
| Forbo Holding AG |
| Daltile Corporation |
| Polycor Inc. |
| Emser Tile |
| Bedrosians Tile and Stone |
| MSI International |
| Others |
Supply & Pricing Matrix
ISO 13006 certification gates both supply qualification and price differentiation in tile and stone flooring, creating tiered access where certified manufacturers command specification premiums while uncertified producers compete on raw material cost alone.
Pricing Analysis
After-sales service contracts and installation warranty extensions drive lifetime value capture in commercial tile procurement. Three-tier pricing structure across premium, standard, and economy levels segments the market by PEI abrasion ratings and water absorption thresholds. Price differentiation stems from ISO 13006 compliance tier and captive kiln ownership. Cost compression in standard-grade ceramic intensifies as India's BIS mandate raises import qualification barriers. Residential builders demonstrate highest price sensitivity, while luxury property developers absorb quarry-provenance premiums with minimal volume elasticity.
Supply Chain Analysis
Carrara quarry access and Minas Gerais slab grading create chokepoint vulnerability for premium marble and granite specification. Manufacturing gravity centers on China, India, and Italy for ceramic and porcelain production. Raw material dependencies span feldspar deposits, high-grade kaolin, and natural gas for kiln firing. Single-source vulnerability concentrates in Carrara's white marble extraction. Distribution runs through controlled dealer networks in North America and direct-to-contractor platforms in California and Texas commercial markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing convergence with gauged porcelain technology creates platform-economics inflection, where interoperability between inkjet decoration systems and slab handling equipment determines specification capture in hospitality and high-rise cladding.
For Market Incumbents: Consolidate captive ceramic production across North American manufacturing bases to defend margin position against distributor bypass trends. Deepen backward integration into feldspar and talc supply chains to satisfy REACH traceability requirements. Lock in commercial contractor buying collectives through direct pricing agreements that neutralize asset-light distributor competition.
For New Entrants and Emerging Players: Compliance-as-a-service for ISO 13006 and BIS certification documentation offers white-space opportunity where incumbents under-serve mid-tier importers. Target India's smart city infrastructure zones with certified porcelain offerings. Penetrate through specialized procurement platforms serving Florida and Texas commercial installer networks.
For Investors and Strategic Acquirers: EU CBAM implementation reshapes the acquisition landscape toward kiln operators with documented carbon emissions and closed-loop water recycling. Five-to-ten year viability favors integrated quarry-to-retail operators with captive ceramic production. Acquire specialists with Carrara quarry relationships or Sassuolo ceramic district positioning. Monitor CBAM carbon border adjustment enforcement as inflection signal for manufacturing location repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Supply | Feldspar and talc quarry control satisfies REACH Substance of Very High Concern screening for EU market access. |
| Digital Printing Technology Deployment | Inkjet decoration convergence enables realistic stone replication at reduced Carrara quarry dependency. |
| Direct-to-Contractor Platform Launch | Bypass of traditional distributor markups captures specification influence in California and Texas commercial markets. |
| BIS Certification Investment | Compulsory marking scheme compliance creates differentiation barrier for ceramic tile imports into India. |
| Closed-Loop Water Recycling Installation | Sassuolo ceramic district investments demonstrate EU Green Deal embodied carbon compliance. |
Research Methodology
A standing panel of commercial contractors, residential builders, ceramic plant managers, and quarry operators provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA RRP certification databases, ISO 13006 testing protocol documentation, BIS compulsory marking registries, and EU CBAM implementation guidance. Bottom-up volume modeling triangulated against top-down value estimates from customs trade flows and kiln capacity utilization surveys.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, installation method, end-user procurement authority, and application severity dimensions. CAGRs derived from annualized growth rate fitting across the analysis window. Forecast inputs included municipal infrastructure renewal program commitments, smart city mission surfacing mandates, and multi-family housing construction permit trajectories.
Forecasts assume regulatory continuity in EPA RRP enforcement, EU CBAM carbon border adjustments, and India's BIS certification mandates; material policy shifts would require re-modeling. Specific risk factors encompass natural gas price volatility affecting Italian and Spanish kiln economics, quarry concentration disruption in Carrara or Minas Gerais, and ISO 13006 testing timeline extensions. Practitioners should keep alternative scenarios live as dual carbon compliance obligations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Australia & New Zealand Flooring Market
Flooring, Carpets, and Rugs
Bath Rugs and Mats Market
Flooring, Carpets, and Rugs
China Wood Flooring Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Middle East Flooring and Carpet Market
Flooring, Carpets, and Rugs
Wood Flooring Market
Flooring, Carpets, and Rugs
US Wood Flooring Market
Flooring, Carpets, and Rugs
Brazil Floor Covering Market
Flooring, Carpets, and Rugs
Global Commercial Flooring Market
Flooring, Carpets, and Rugs
Stone Flooring Market
Flooring, Carpets, and Rugs
Turkey Floor Covering Market
Flooring, Carpets, and Rugs
China Engineered Wood Flooring Market
Flooring, Carpets, and Rugs
Carpets and Rugs Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Egypt Floor Covering Market
Flooring, Carpets, and Rugs
India Wood Flooring Market