
 ASEAN Laminate Flooring Market | 2026-2036
ASEAN Laminate Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Laminate Flooring Market Outlook
Installation service revenue is tilting toward certified contractor networks as product commoditization squeezes bare-material margins. Inovar leverages backward integration into resin-impregnated paper production to control input quality across its Southeast Asian plants. Robina Flooring anchors its position through dedicated distribution hubs in Penang and Surabaya that shorten last-mile delivery cycles. Mannington Mills competes primarily on design breadth, extending North American print-layer libraries into tropical humidity-rated formulations.
Laminate flooring comprises a fiberboard core bonded with decorative paper and aluminum oxide wear layer, typically rated AC3 to AC5 for abrasion resistance and engineered for floating installation over concrete or plywood subfloors. High-Pressure Laminate dominates commercial specifications due to superior dimensional stability under heavy foot traffic, while Waterproof Laminate captures the fastest expansion as developers specify moisture-resistant cores for tropical climates and ground-floor retail. Direct Pressure Laminate occupies the value tier in residential mass housing where cost-per-square-meter governs procurement decisions.
Indonesia's BIS-equivalent national standards body enforces SNI labeling for formaldehyde emission classes, while Thailand's TISI certification mandates slip resistance testing for commercial installations. Malaysia's SIRIM and Singapore's PSB certification create tiered market access where uncertified imports face border detention or project disqualification. Stakeholders must monitor evolving trans-ASEAN mutual recognition agreements that could collapse separate national testing requirements into unified conformity assessment pathways.
Market Dynamics
Waterproof laminate cores are displacing standard fiberboard specifications across tropical ASEAN housing developments, forcing manufacturers to reconfigure resin-impregnation lines and recertify products under stricter national marking regimes.
Growth Catalysts
- Urban household formation:Middle-class housing stock expansion in greater Jakarta, Bangkok metropolitan region, and Ho Chi Minh City corridor absorbs rising laminate volumes as residential construction accelerates.
- SNI marking requirements:Indonesia's national standards body tightens formaldehyde emission class enforcement, creating compliance-driven replacement cycles for legacy inventory in residential mass housing.
- Floating installation systems:Click-lock edge technologies reduce skilled labor dependency and shorten project timelines for concrete and plywood subfloor applications across multi-unit developments.
Market Restraints
- Melamine-formaldehyde resin volatility:Input cost swings for thermosetting adhesives compress margin predictability for fiberboard core producers serving price-sensitive procurement tiers.
- Border detention risk:Uncertified imports face SIRIM, PSB, and TISI enforcement actions that strand inventory and disqualify project bids across Malaysia, Singapore, and Thailand.
- Engineered wood substitution:SPC and WPC rigid core alternatives capture moisture-prone ground-floor retail specifications with superior dimensional stability claims.
Strategic Opportunities
- Vietnam secondary cities:Da Nang, Can Tho, and Hai Phong housing pipelines remain underpenetrated relative to Ho Chi Minh City corridor saturation.
- Trans-ASEAN mutual recognition:Unified conformity assessment pathways could collapse separate SNI, TISI, SIRIM, and PSB testing into single certification cycles.
- Direct-to-developer platforms:Digital procurement channels bypass traditional distributor markups for volume residential projects in Indonesia and Philippines.
Industry Challenges
- Certification timeline compression:SNI, TISI, and SIRIM testing cycles extend six to twelve months, delaying product launches and freezing working capital in pre-approved inventory.
- Resin-impregnated paper supply:Captive decorative paper production requires capital-intensive saturation and drying equipment that mid-scale competitors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Laminate Flooring Market |
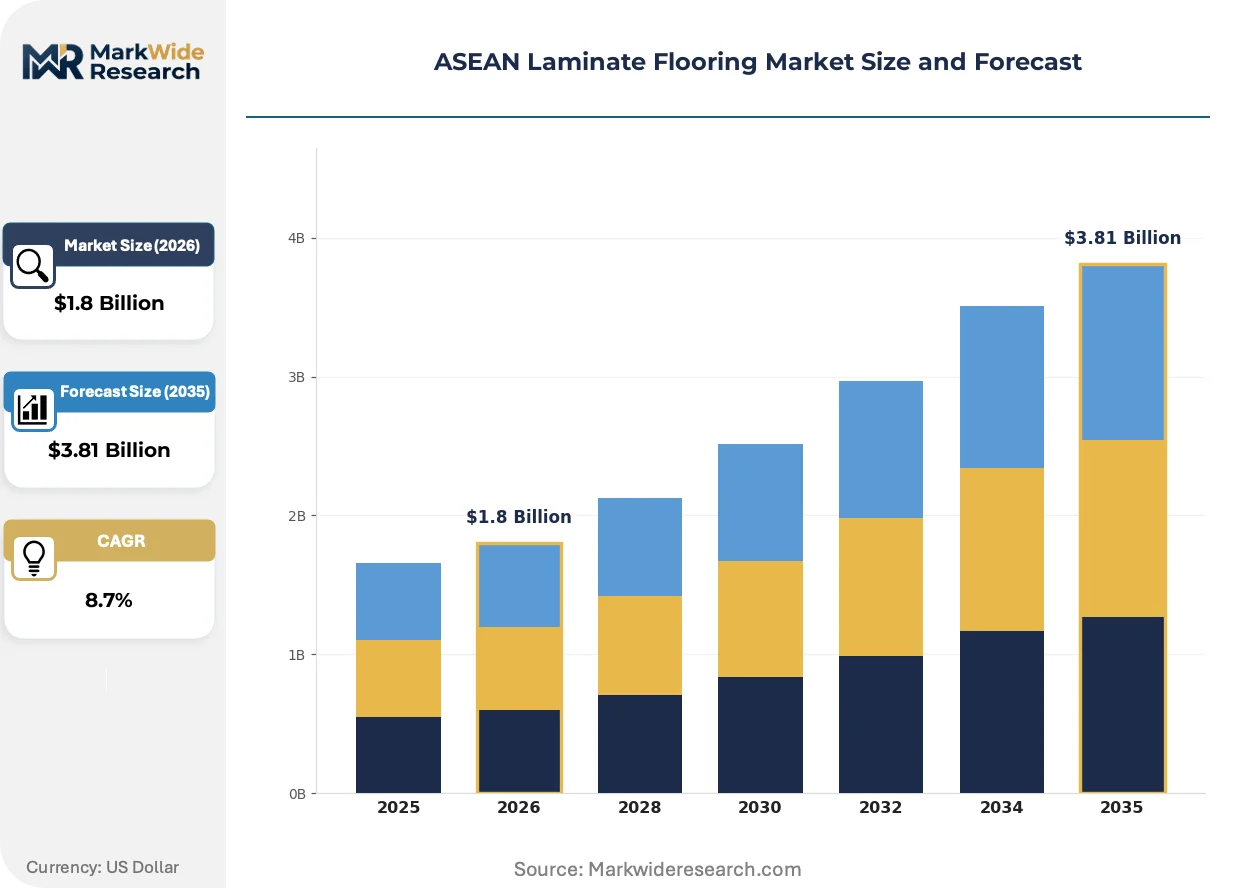
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Pressure Laminate, Direct Pressure Laminate, Waterproof Laminate, Eco-Friendly Laminate Use Case: Residential, Commercial, Industrial, Institutional Thickness: 8mm, 10mm, 12mm, 15mm Finish Type: Textured, Glossy, Matte, Embossed |
| Companies Covered | Inovar, Mannington Mills, Synchrowood, Dongwha Malaysia, Metroply Thailand, Rumah Lantai Indonesia, Power Daccor, Robina Flooring, Siam Flooring, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Laminate Flooring Market Strategic Shifts
Digital print-layer technologies and moisture-resistant core formulations are converging to redefine product differentiation, while certification-driven procurement tightens vendor qualification standards across ASEAN project channels.
Waterproof laminate incorporating hydrophobic HDF cores and wax-sealed locking systems is virtualizing the traditional moisture-barrier installation step, eliminating separate underlayment purchases. Property developers in ground-floor retail and tropical residential segments specify these systems to reduce callback liability. The technology is virtualizing the separate waterproofing trade, compressing project timelines and shifting margin capture toward core manufacturers.
Thailand's TISI certification now mandates slip resistance testing for commercial installations, extending compliance obligations beyond wear-layer abrasion ratings. Flooring contractors must source AC4-AC5 rated products with certified friction coefficients to qualify for hospitality and healthcare bids. Hotel and hospital procurement teams in Bangkok and Phuket now require TISI documentation as a gate condition for vendor shortlisting.
Developer procurement teams increasingly bundle flooring specification with installation service contracts, unbundling bare-material transactions that previously dominated mass housing tenders. Certified contractor networks capture margin that commodity distributors once held, particularly in Jakarta and Surabaya where project-scale efficiency governs award decisions. This pattern concentrates volume with vertically integrated suppliers capable of warranting both product and labor performance across multi-year build-out schedules.
ASEAN Laminate Flooring Market Segmentation
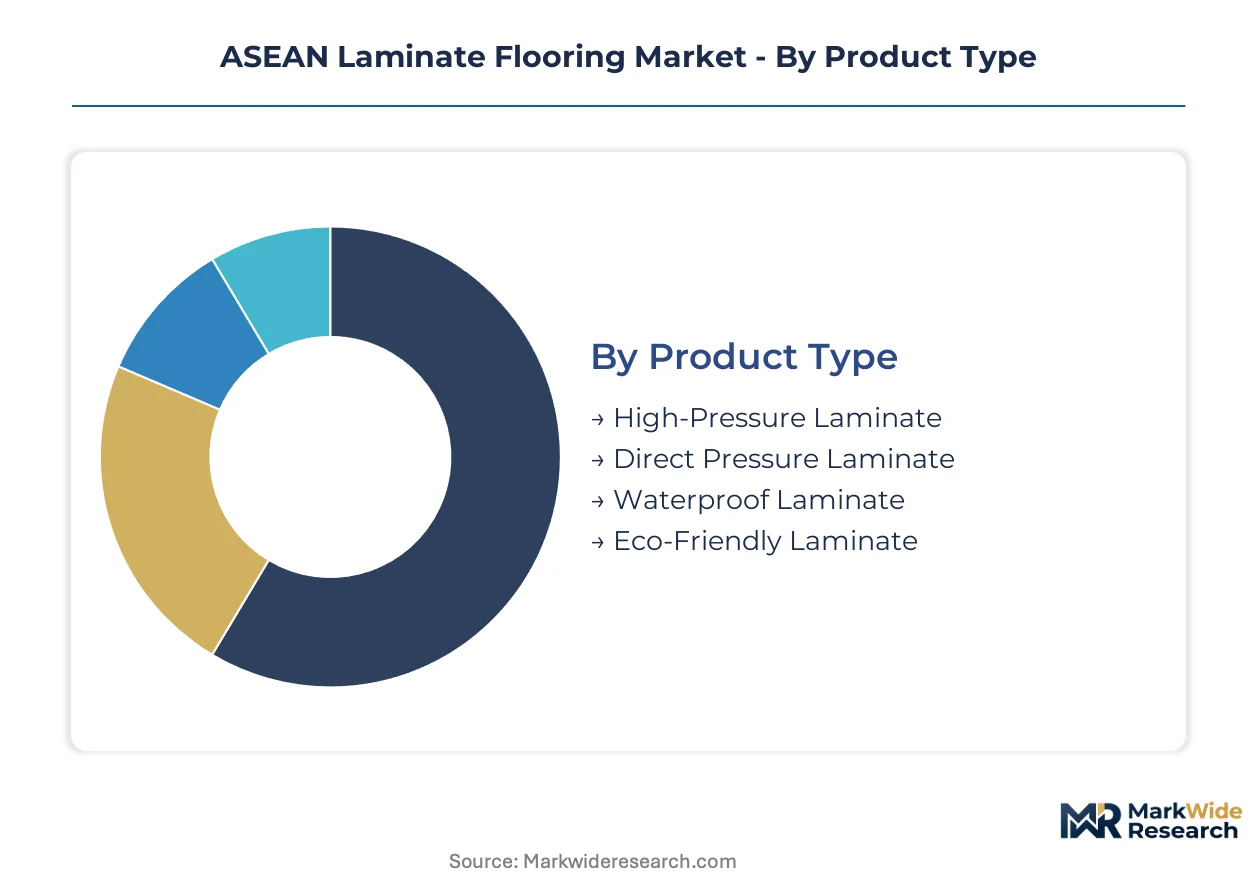
ASEAN laminate flooring segmentation reflects divergent technical requirements across tropical climates, certification regimes, and subfloor conditions. Product architecture, end-use specifications, and installation constraints create distinct procurement tiers that manufacturers must address through differentiated production lines.
Product Type:
Mature high-pressure formulations dominate commercial specifications while emerging waterproof technologies capture developer attention in moisture-prone applications.
- High-Pressure Laminate:Multi-layer construction fuses kraft paper and decorative sheets under sustained heat and pressure above 7 MPa. Bangkok hospital and hospitality procurement teams specify HPL for heavy-traffic zones where dimensional stability under load governs warranty terms.
- Waterproof Laminate:Hydrophobic HDF cores combined with wax-sealed locking systems eliminate separate underlayment requirements. Ground-floor retail developers in Jakarta and Ho Chi Minh City corridor specify these systems to reduce callback liability from concrete moisture vapor transmission.
- Direct Pressure Laminate:Single-press manufacturing bonds decorative paper directly to fiberboard cores at lower cost. Indonesia's mass housing contractors favor DPL for price-sensitive procurement tiers where SNI compliance satisfies minimum formaldehyde emission thresholds.
- Eco-Friendly Laminate:Recycled wood fiber content and low-emission melamine resins target green building certifications. Singapore PSB-marked variants serve developer sustainability scorecards in public housing tenders.
High-Pressure Laminate retains volume leadership across commercial channels; Waterproof Laminate holds the steepest expansion curve as tropical residential specifications harden against moisture damage.
Use Case:
Application-driven procurement separates floating-installation residential volumes from adhesive-fixed commercial specifications with distinct labor and warranty requirements.
- Residential:Click-lock floating systems dominate multi-unit developments across greater Jakarta and Bangkok metropolitan region. Middle-class household formation absorbs AC3-rated products through developer bundle contracts that merge material supply with certified installation networks.
- Commercial:AC4-AC5 abrasion ratings and TISI slip resistance certification gate hospitality and healthcare bids in Phuket and Bangkok. Hotel procurement teams require documented friction coefficients for lobby and corridor specifications.
- Industrial:Heavy-load tolerance and chemical resistance distinguish warehouse and light manufacturing applications. Malaysian logistics facilities near Port Klang specify thicker cores for forklift traffic zones.
- Institutional:Extended wear warranties and fire-rated cores serve school and government building tenders. Vietnam's public education infrastructure pipeline specifies 15mm thickness for classroom durability.
Residential absorbs the greatest shipment volumes; Commercial commands the highest specification premiums per square meter.
Thickness:
Structural performance requirements and subfloor condition tolerance stratify procurement across thin floating systems and thick rigid platforms.
- 8mm:Standard floating installation over level concrete or plywood subfloors. Cost-optimized mass housing in Philippines and Indonesia specifies this tier where budget constraints override acoustic performance.
- 10mm:Enhanced stability for moderate residential traffic with integrated underlayment compatibility. Bangkok condominium developers favor this specification for unit turnover efficiency.
- 12mm:Commercial-grade rigidity supporting AC4-AC5 wear layers without flex-induced joint failure. Malaysian retail fit-out contractors specify 12mm for open-plan merchandise floors.
- 15mm:Maximum dimensional stability for uneven subfloors and heavy static loads. Industrial and institutional specifications in Vietnam and Thailand absorb this premium tier.
10mm-12mm specifications capture the greatest combined volume; 15mm gains share fastest in commercial upgrade cycles.
Finish Type:
Surface aesthetic differentiation targets regional design preferences while functional texture properties influence slip resistance compliance.
- Textured:Embossed grain patterns replicate natural wood tactile response. Residential preferences across Indonesia and Malaysia favor textured finishes for living area authenticity.
- Glossy:High-sheur polyurethane topcoats reflect light for commercial showroom and retail environments. Bangkok luxury condominium lobbies specify glossy finishes for perceived premium positioning.
- Matte:Low-reflection surfaces minimize glare and conceal surface wear. Healthcare and institutional procurement in Singapore and Vietnam prioritizes matte finishes for maintenance efficiency.
- Embossed:Synchronized grain-to-pattern registration enhances visual depth. High-end residential developers in Ho Chi Minh City corridor specify embossed finishes for differentiation in competitive housing stock.
Textured finishes retain volume leadership across residential mass markets; Matte surfaces are expanding most quickly in institutional compliance-driven procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Malaysia, Thailand, and Indonesia where fiberboard mills and resin-impregnation lines serve domestic demand and re-export channels. National certification regimes fragment market access across ASEAN borders.
Indonesia
Jakarta and Surabaya absorb the greatest laminate volumes as middle-class housing stock expands. The national standards body enforces SNI labeling for formaldehyde emission classes, accelerating replacement cycles for non-compliant legacy inventory. Greater Jakarta's developer procurement teams now bundle flooring with certified installation networks.
Thailand
Bangkok metropolitan region and Phuket hospitality corridors drive commercial-grade specifications. TISI certification mandates slip resistance testing for hotel and healthcare bids, extending compliance beyond wear-layer ratings. Contractors source AC4-AC5 products with documented friction coefficients to qualify for lobby and corridor awards.
Malaysia
Penang and Port Klang anchor distribution hubs serving domestic retail fit-outs and re-export markets. SIRIM certification standards tighten product compliance thresholds, detaining uncertified imports at border checkpoints. Malaysian logistics facilities near Port Klang specify thicker cores for forklift traffic zones.
Vietnam
Ho Chi Minh City corridor concentrates residential demand while Da Nang and Hai Phong remain underpenetrated. Public education infrastructure tenders specify 15mm thickness for classroom durability. Secondary city housing pipelines offer expansion vectors as primary metro saturation intensifies.
Singapore
PSB-marked variants serve developer sustainability scorecards in public housing tenders. Green building procurement prioritizes low-emission laminates with recycled wood fiber content. The city-state's certification requirements create tiered market access where pre-approved inventory accelerates project timelines.
ASEAN Laminate Flooring Market Competitive Environment
Vertically integrated manufacturers and specialized distributors split the market across distinct value-capture models. Concentration remains moderate with regional leaders commanding procurement relationships through certification-holding advantages. Two archetypes dominate: backward-integrated producers controlling resin-impregnated paper supply, and distributor-led networks optimizing last-mile delivery cycles. Competitive moves center on captive raw material production and dedicated distribution hub expansion.
Among Malaysia and Thailand-based fabricators, Inovar and Robina Flooring exemplify the integrated-production archetype, while Mannington Mills occupies a position as a design-specialist entrant extending overseas print-layer libraries. Dongwha Malaysia and Metroply Thailand anchor the mid-scale regional tier, serving price-sensitive procurement through standardized product lines. These named entities represent the competitive spectrum from captive supply control to distribution-optimized service models.
| Leading Market Players |
|---|
| Inovar |
| Mannington Mills |
| Synchrowood |
| Dongwha Malaysia |
| Metroply Thailand |
| Rumah Lantai Indonesia |
| Power Daccor |
| Robina Flooring |
| Siam Flooring |
| Others |
Value Chain & Pricing Dynamics
Melamine-formaldehyde resin volatility determines both the pricing tier spreads across AC3-AC5 wear ratings and the geographic clustering of fiberboard core production. Input cost swings compress margin predictability for manufacturers serving price-sensitive procurement tiers, forcing supply chain reconfiguration toward captive resin-impregnation capabilities.
Pricing Analysis
SNI marking requirements dictate the pricing tier structure across Indonesia's residential mass housing segment. Three-tier pricing structure across premium, standard, and economy levels separates PSB-certified imports from SIRIM-compliant domestic production from uncertified border-detained inventory. Cost compression in the economy tier is intensifying because TISI and SIRIM testing cycles extend working capital commitments. Developer procurement teams in Jakarta demonstrate highest price sensitivity, while Bangkok hospitality buyers absorb premium tiers for slip-resistant AC5 specifications.
Supply Chain Analysis
Export-control regimes on decorative paper printing technologies limit advanced pattern-transfer equipment flows into ASEAN fiberboard mills. Manufacturing gravity centers on Malaysia, Thailand, and Indonesia where resin-impregnation lines serve domestic demand and re-export channels. Supply chains draw from melamine-formaldehyde resin suppliers in Northeast Asia, kraft paper mills in Southeast Asia, and aluminum oxide abrasive sources in South Asia. Single-source vulnerability concentrates in decorative paper saturation equipment where European and Japanese suppliers dominate. Distribution runs through certified contractor networks that displace traditional distributor markups in Jakarta and Surabaya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as developer procurement teams in greater Jakarta and Bangkok metropolitan region consolidate flooring specification with installation service contracts. This consolidation fragments the bare-material distributor tier while elevating vertically integrated suppliers.
For Market Incumbents: Insulate margin position by deepening captive supply of resin-impregnated decorative paper across Malaysian and Indonesian plants. Accelerate SNI, TISI, and SIRIM certification renewal cycles before trans-ASEAN mutual recognition collapses separate national testing requirements. SPC and WPC rigid core substitution in moisture-prone ground-floor retail represents the most pressing technology threat. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's secondary cities where Da Nang and Hai Phong housing pipelines remain underpenetrated relative to Ho Chi Minh City corridor saturation. Direct-to-developer digital procurement channels offer the most penetrable go-to-market angle for bypassing entrenched distributor relationships in Indonesia and Philippines. For Investors and Strategic Acquirers: The market sits at a certification-intensification phase that favors backward-integrated manufacturers with captive testing laboratory relationships. Long-term viability over the next decade hinges on controlling decorative paper supply rather than pure distribution scale. Watch for trans-ASEAN mutual recognition agreement announcements as the critical inflection signal that would compress compliance costs for multi-country operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin-Impregnated Paper | Inovar's captive saturation lines in Malaysia and Indonesia insulate input quality from decorative paper supply shocks. |
| Certified Contractor Network Expansion | Robina Flooring's Penang and Surabaya hubs shorten last-mile delivery cycles for developer bundle contracts. |
| Waterproof Core Formulation R&D | Hydrophobic HDF development eliminates separate underlayment purchases and captures tropical residential specifications. |
| Trans-ASEAN Certification Harmonization | Unified SNI-TISI-SIRIM-PSB pathways would collapse six-to-twelve month testing cycles into single approval windows. |
| Direct-to-Developer Platform Launch | Digital procurement channels bypass traditional distributor markups for volume residential projects in Indonesia. |
Study Parameters
A standing panel of flooring procurement managers at Jakarta and Bangkok developers, plant managers at Malaysian fiberboard mills, SIRIM and TISI certification auditors, and resin-impregnated paper technical directors provided ongoing calibration throughout the study. Primary interviews combined with secondary validation from customs trade databases, SNI and TISI regulatory filing records, and ASEAN construction permit aggregators. Bottom-up shipment estimates from manufacturer channels triangulated against top-down housing stock expansion models.
Scenario-bracketing framed low-base-high demand trajectories across the projection horizon. Segmentation dimensions modeled include product architecture, end-use specification, thickness tier, and finish type alongside climate-zone subfloor condition tolerance. CAGRs derived from housing formation rates, replacement cycle timing, and certification-driven procurement elasticity. Waterproof laminate penetration curves and SPC substitution elasticities served as key forecast inputs.
Sensitivities concentrate around trans-ASEAN mutual recognition timeline delays, melamine-formaldehyde resin price spikes, and SNI enforcement intensity variations. Forecasts reflect assumptions on middle-class household formation persistence and tropical climate moisture damage claim rates. Material shifts in waterproof core technology cost curves or engineered wood substitution acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flooring, Carpets, and Rugs
Saudi Arabia Floor Covering Market
Flooring, Carpets, and Rugs
India Floor Covering Market
Flooring, Carpets, and Rugs
Europe Flooring Market
Flooring, Carpets, and Rugs
United States Laminate Flooring Market
Flooring, Carpets, and Rugs
Global Carpet Tile Market
Flooring, Carpets, and Rugs
Global Luxury Vinyl Tile Floor Covering Market
Flooring, Carpets, and Rugs
Netherlands Floor Covering Market
Flooring, Carpets, and Rugs
Japan Floor Covering Market
Flooring, Carpets, and Rugs
Sheet Flooring Market
Flooring, Carpets, and Rugs
Carpet Floor Mats Market
Flooring, Carpets, and Rugs
Global Non-Resilient Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Carpet and Rugs Market
Flooring, Carpets, and Rugs
United States Non-Resilient Floor Covering Market
Flooring, Carpets, and Rugs
North America Wood Flooring Market
Flooring, Carpets, and Rugs
Saudi Arabia Vinyl Flooring Market
Flooring, Carpets, and Rugs
Area Rugs Market