
 Quartz Sink Market | 2026-2036
Quartz Sink Market Size, Share, and Industry Trends Forecast 2026-2036
Quartz Sink Market Intelligence
The substitution of traditional stainless steel and natural stone with engineered quartz composite is repositioning the value proposition in kitchen fixtures. Kohler Co. leverages its extensive distribution network and brand recognition to capture share in the premium residential segment. BLANCO differentiates through its proprietary Silgranit material composition, focusing on color variety and durability. Franke Holding AG competes by offering integrated kitchen systems where the quartz sink is a central component.
A quartz sink is a composite fixture typically made from around 80% quartz aggregate blended with 20% acrylic or epoxy resin. This composition creates a hard, non-porous surface resistant to scratches, stains, and heat, serving modern kitchen design and utility demands. While double-bowl configurations remain popular for their functionality, single-bowl sinks are gaining traction, especially in minimalist kitchen designs. The residential end-user segment commands the largest share, driven by renovation cycles and new home construction.
Product compliance is governed by standards such as ANSI/IAPMO Z124 in the United States, which specifies material and performance requirements for plastic plumbing fixtures. In Europe, CE marking under the Construction Products Regulation (CPR) and adherence to food contact material safety rules are mandatory for market access. Navigating these distinct regional standards for material safety and performance certification is critical for manufacturers seeking to expand their geographic footprint.
Market Dynamics
The displacement of traditional materials like stainless steel and granite by engineered quartz composites is the central force shaping the kitchen fixture market. This material substitution is driven by superior performance in scratch, stain, and heat resistance demanded by modern households.
Growth Catalysts
- Material Innovation:Advanced non-porous composite formulations, blending quartz with acrylic resins, enhance durability and hygiene, attracting homeowners in the premium residential remodeling sector seeking long-lasting, low-maintenance surfaces.
- Residential Construction:Strong demand from new home construction and renovation projects, particularly within the United States and Germany, provides a consistent volume base for quartz sink manufacturers.
- Aesthetic Versatility:The ability to produce sinks in a wide array of consistent colors and finishes allows for better integration with contemporary kitchen designs, a key purchasing factor for interior designers and homeowners.
Market Restraints
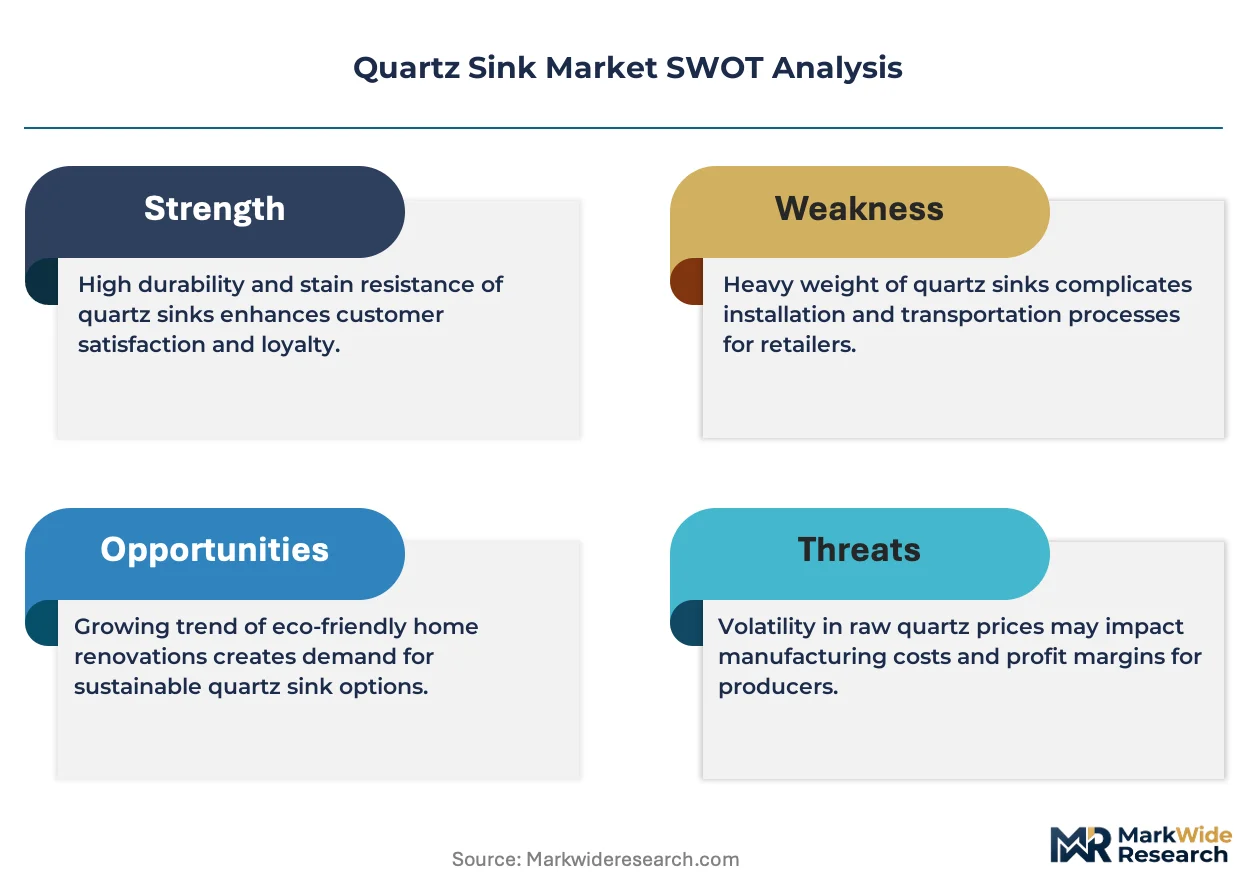
- Input Cost Volatility:The market is sensitive to price fluctuations in petroleum-derived acrylic and epoxy resins, which constitute a significant portion of the material blend and can impact final product pricing and manufacturer margins.
- Premium Material Competition:High-end natural stone, such as quarried marble and granite, along with premium-grade stainless steel, continue to present a strong substitution threat in the luxury segment where brand heritage and perceived value are high.
- Installation Complexity:Quartz sinks are heavier and more rigid than stainless steel counterparts, requiring specialized installation techniques and support structures to prevent cracking or damage, which can deter some contractors.
Strategic Opportunities
- Commercial Applications:Expanding into commercial sectors like hospitality, healthcare, and food service where the demand for hygienic, durable, and non-porous surfaces aligns directly with the core properties of quartz composites.
- Geographic Expansion:Targeting urbanizing regions in Latin America and Southeast Asia, where a growing middle class is investing in kitchen upgrades and adopting Western design trends, presents significant white-space potential.
- Integrated Smart Systems:Incorporating technology such as hands-free faucets, integrated water filtration, or responsive lighting directly into the sink design can create new value propositions and capture share in the smart home market.
Industry Challenges
- Regulatory Navigation:Manufacturers face complexity in managing divergent compliance standards, such as ANSI/IAPMO Z124 in the U.S. and Europe's CE marking under the Construction Products Regulation, for global market access.
- Capital-Intensive Production:Achieving consistent color, density, and finish quality requires significant capital investment in precision mixing, molding, and curing equipment, creating high barriers to entry for new players.
- Logistics and Handling:The weight and relative brittleness of quartz sinks compared to metal alternatives pose logistical challenges, increasing shipping costs and the risk of damage during transit and installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quartz Sink Market |
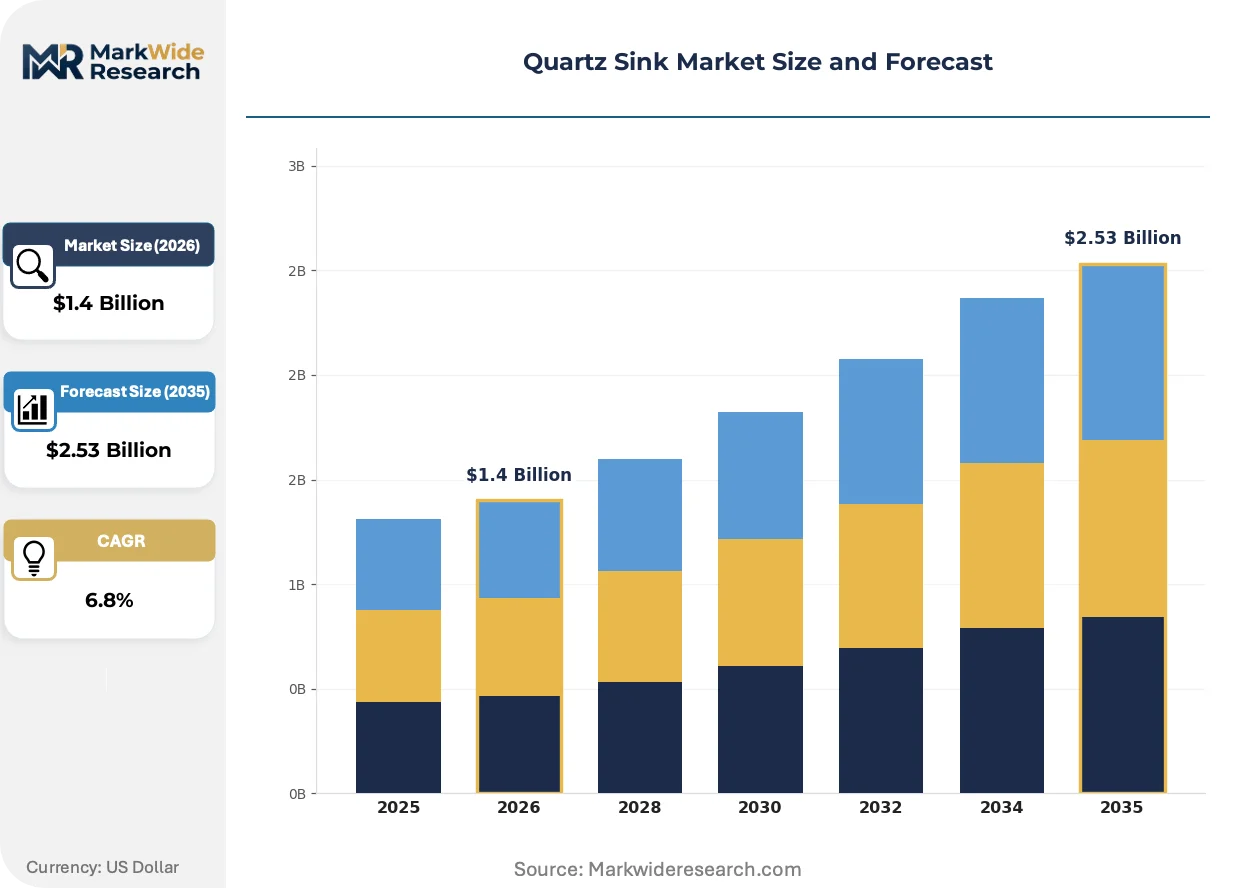
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Bowl, Double Bowl, Undermount, Drop-in Material: Engineered Quartz, Natural Quartz, Composite, Resin Installation Type: Top-Mount, Below-Mount, Integrated, Freestanding End User: Residential, Commercial, Hospitality, Industrial |
| Companies Covered | Kohler Co., BLANCO, Franke Holding AG, Elkay Manufacturing Company, Oliveri Solutions, Astracast, Moen Incorporated, Teka Group, Acrysil Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quartz Sink Market Strategic Shifts & Innovations
Material science advancements are redefining product capabilities, enabling quartz sinks to meet dual demands for high performance and sophisticated design. This evolution pushes manufacturers to innovate beyond basic functionality, focusing on features that enhance kitchen workflow and aesthetics.
Advanced resin formulations with improved antimicrobial properties and UV stability represent a key product evolution. The premium residential segment is rapidly adopting these materials for their enhanced hygiene and resistance to discoloration over time. This technology is unifying the previously separate attributes of durability and long-term aesthetic integrity, creating a superior value proposition for consumers.
European regulations, specifically the Construction Products Regulation (CPR) and rules governing food contact materials, are setting a high bar for product safety and performance. This forces manufacturers to provide extensive documentation and test results on material composition and durability, effectively raising compliance costs. The mid-tier segment is most affected, as it must balance these added costs against competitive pricing pressures.
A notable behavioral shift is the preference for minimalist kitchen designs, which directly influences sink configuration choices. The market is seeing a move away from traditional double-bowl sinks toward large, deep single-bowl models that can accommodate oversized pots and pans while maintaining a clean, uncluttered look. This trend is most prominent in new urban residential developments across North America and Europe.
Quartz Sink Market Segmentation
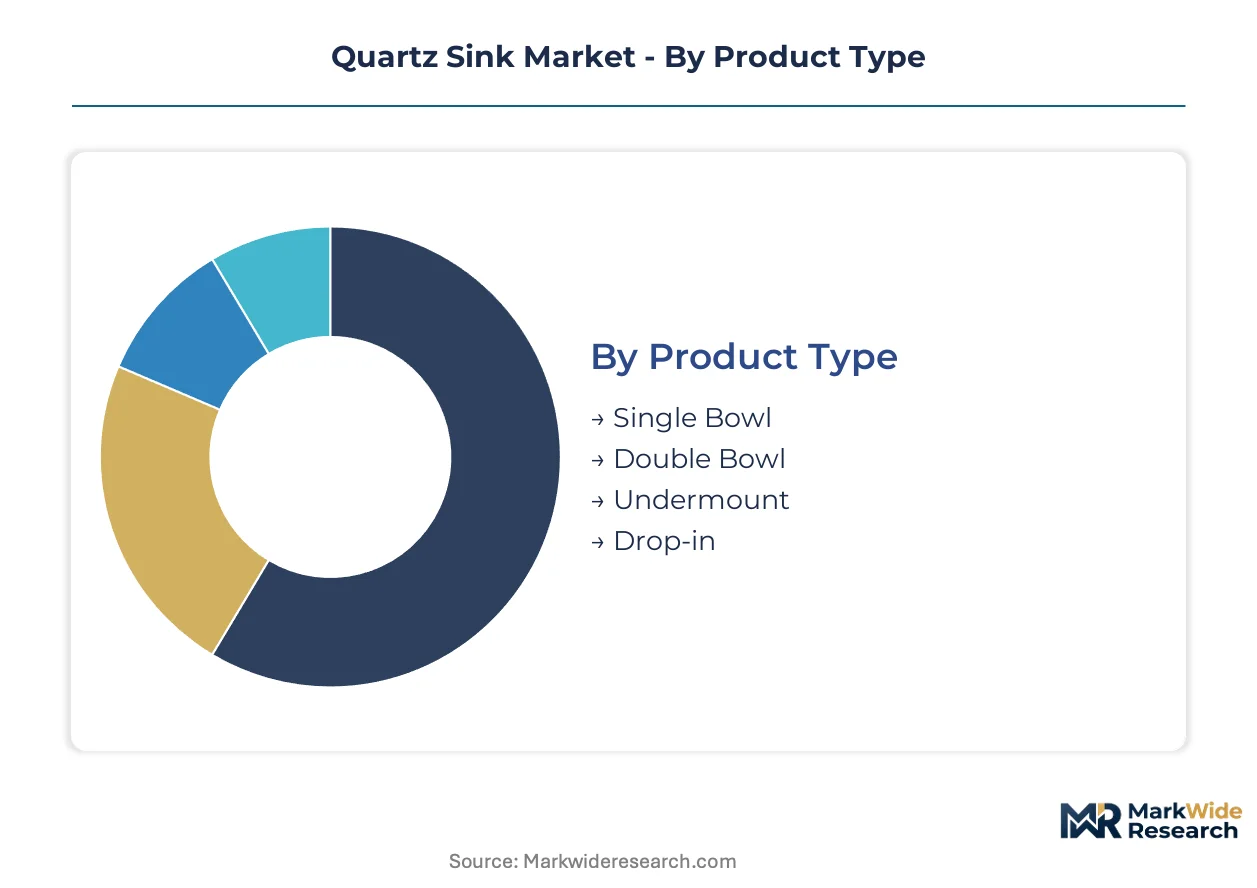
The quartz sink market's segmentation provides a detailed lens into consumer preferences and industry demand drivers. Analyzing distinct product types, materials, installation methods, and end-user applications illuminates specific growth pockets and competitive battlegrounds for manufacturers.
Product Type:
The product type segmentation highlights how consumer upgrade cycles and renovation trends influence sink choices.
- Double Bowl:These configurations offer versatile functionality for tasks like washing and rinsing simultaneously, making them a consistent choice in residential kitchen renovation projects due to their proven utility. Demand remains strong in established housing markets across the United States and Germany.
- Single Bowl:Characterized by a large, deep basin, single-bowl sinks accommodate oversized cookware and align with modern minimalist kitchen aesthetics. This design is gaining significant traction in new urban residential developments seeking uncluttered, functional spaces.
- Undermount:Undermount sinks integrate seamlessly beneath the countertop, providing a sleek appearance and simplifying countertop cleaning.
- Drop-in:Drop-in sinks feature a finished rim that rests on the countertop, offering simpler installation and often appearing in more budget-conscious renovation projects.
Double Bowl sinks sit at the top of the volume ranking, with Single Bowl configurations climbing the fastest.
Material:
Material segmentation reveals distinct cost tiers and performance expectations shaping consumer and commercial procurement decisions.
- Engineered Quartz:Composed of approximately 80% quartz aggregate and 20% resin, this material offers superior resistance to scratches, stains, and heat. Demand concentrates in the premium residential remodeling sector, driven by aesthetic appeal and long-term durability.
- Composite:These sinks blend various aggregates with resins, often including granite or other minerals, to achieve a balance of durability and cost-effectiveness. The mid-tier residential segment represents a significant end-user base for these robust, versatile options.
- Natural Quartz:Sinks crafted from natural quartz offer unique aesthetic variations and command a niche in the luxury segment for bespoke kitchen designs.
- Resin:Primarily composed of acrylic or epoxy resins, these options provide a lighter, more affordable alternative with less durability compared to quartz-rich composites.
Performance attributes often dictate material selection, with Engineered Quartz leading in overall market adoption.
Installation Type:
Installation type segmentation delineates product suitability across diverse kitchen layouts and functional requirements.
- Below-Mount:This installation method creates a seamless edge between the sink and countertop, enhancing aesthetics and simplifying cleaning. Below-mount installations are prevalent in premium residential projects and modern kitchen designs.
- Top-Mount:Also known as drop-in, these sinks have a visible rim resting on the countertop, facilitating easier installation and often chosen for renovation projects where cost and simplicity are primary considerations. This type is common in both residential and light commercial settings.
- Integrated:Integrated sinks are molded directly into the countertop material, creating a completely seamless and custom look.
- Freestanding:Freestanding sinks are self-contained units, typically found in utility rooms, laundry areas, or specialized commercial applications.
Installation method frequently aligns with aesthetic goals, influencing project timelines and labor costs.
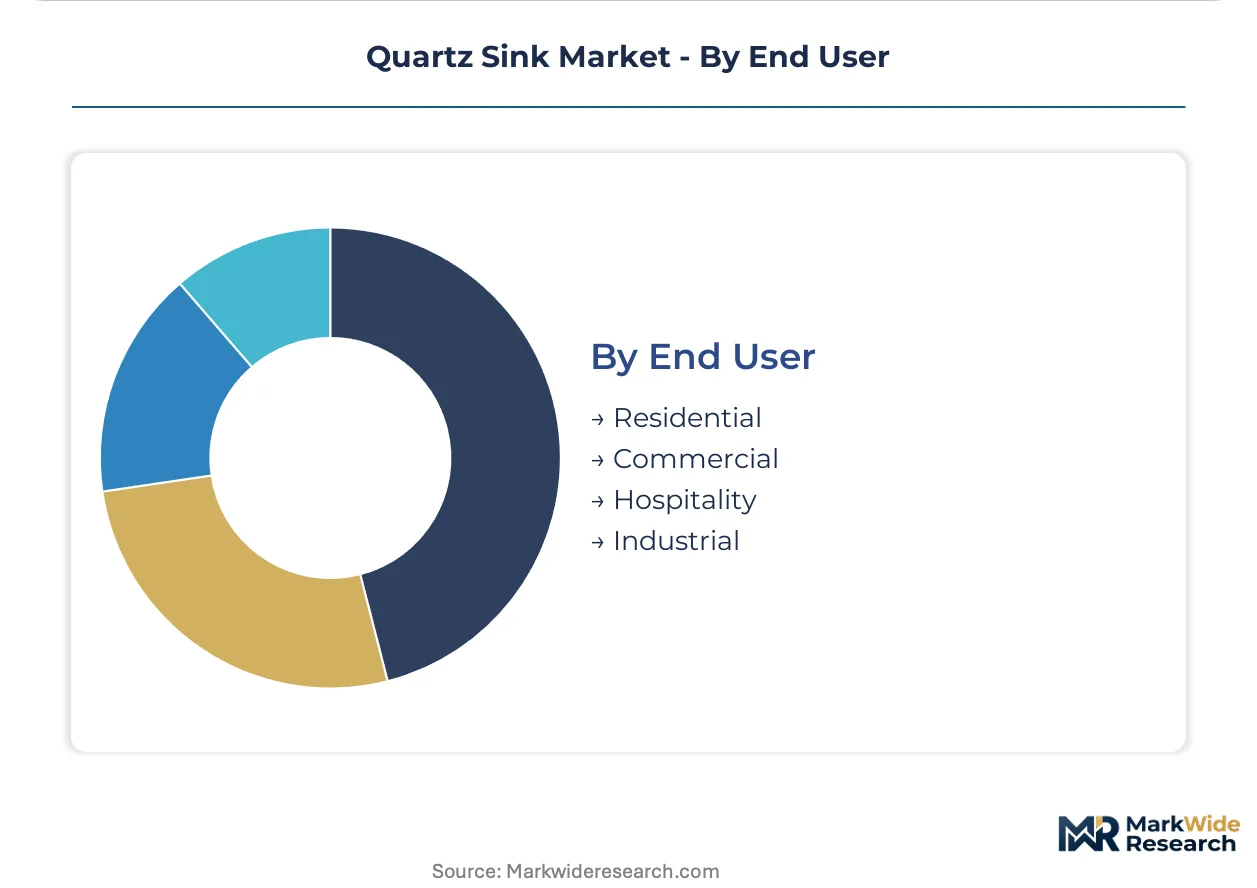
End User:
End user segmentation differentiates demand patterns based on specific functional needs and procurement scales across various customer types.
- Residential:This segment includes new home construction and renovation projects, where homeowners prioritize aesthetics, durability, and hygiene for their kitchen and utility spaces. The United States and Germany are key markets for residential quartz sink demand.
- Commercial:Commercial applications, such as office breakrooms, small businesses, and light institutional settings, require durable and easy-to-maintain sinks that can withstand moderate daily use. Hygiene and longevity are critical purchase factors.
- Hospitality:Hotels, restaurants, and catering facilities demand highly durable and hygienic sinks capable of handling intensive use and stringent cleaning protocols.
- Industrial:Industrial settings like laboratories or manufacturing facilities require specialized sinks with resistance to chemicals or extreme temperatures.
The Residential segment dominates volume, while Commercial applications present a strategic expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States residential remodeling sector, alongside Germany's robust renovation market, drives significant demand for quartz sinks. These regions exhibit high consumer preference for durable and aesthetically pleasing kitchen fixtures. Material innovation and product compliance standards further shape regional market dynamics.
United States
New home construction and renovation projects fuel quartz sink demand. Regulatory compliance under ANSI/IAPMO Z124 ensures material and performance standards. Major metropolitan areas like Dallas and Atlanta experience sustained residential development, necessitating modern kitchen installations.
Germany
Germany's strong renovation cycles and aesthetic preferences underpin consistent demand for kitchen solutions. Manufacturers must adhere to CE marking under the Construction Products Regulation (CPR). Bavaria and North Rhine-Westphalia represent significant manufacturing hubs and consumer markets for premium quartz products.
China
China's rapid urbanization and a growing middle class investing in kitchen upgrades are boosting quartz sink adoption. Adherence to national GB standards for building materials is essential. The Yangtze River Delta region, including Shanghai, exhibits both manufacturing prowess and substantial consumer demand.
India
India's expanding housing projects and increasing disposable incomes contribute to rising demand for modern kitchen amenities. The Bureau of Indian Standards (BIS) sets quality benchmarks for plumbing fixtures. Major urban centers such as Delhi-NCR and Mumbai demonstrate high construction activity.
United Kingdom
The United Kingdom's home improvement market, driven by a preference for modern kitchen designs, supports quartz sink sales. Products require UKCA marking for conformity, following previous CE marking requirements. London and the Southeast of England show concentrated renovation spending, influencing design trends.
Quartz Sink Market Key Industry Players
Global majors compete with regional champions across brand recognition and distribution network strength. The market structure exhibits a tiered consolidation, with established players leveraging extensive reach and specialized manufacturers focusing on niche segments. Strategic archetypes include premium brand innovators, material differentiation specialists, and integrated kitchen system providers. Dominant competitive moves involve geographic expansion into urbanizing regions and continuous material innovation to enhance product performance.
Among established manufacturers, Kohler Co., BLANCO, and Franke Holding AG represent different strategic approaches to the quartz sink market. Kohler Co. exemplifies a premium brand leveraging extensive distribution networks for market penetration in the residential segment. BLANCO distinguishes itself through proprietary material compositions, focusing on color variety and enhanced durability. Franke Holding AG occupies a position as an integrated kitchen systems provider, where the quartz sink is a central component. These companies collectively anchor market presence through brand heritage, product differentiation, and comprehensive offerings for diverse consumer needs.
| Leading Market Players |
|---|
| Kohler Co. |
| BLANCO |
| Franke Holding AG |
| Elkay Manufacturing Company |
| Oliveri Solutions |
| Astracast |
| Moen Incorporated |
| Teka Group |
| Acrysil Ltd. |
| Others |
Cost & Logistics Intelligence
Brent Crude Oil futures directly influence the cost of petroleum-derived resins, cascading through the quartz sink supply chain into variable pricing tiers for manufacturers.
Pricing Analysis
Input cost pass-through mechanisms largely determine final quartz sink prices across market segments. The market operates on a value-based pricing model, differentiating across premium, mid-range, and economy tiers. Brand recognition, proprietary material compositions, and compliance standards like ANSI/IAPMO Z124 drive price differentiation, while pricing softness stems from intense competition with premium natural stone. The mid-tier residential segment exhibits high price sensitivity, contrasting with luxury bespoke projects.
Supply Chain Analysis
Quartz aggregate supply primarily draws from mining operations in countries such as China and India. Production further depends on petroleum-derived acrylic and epoxy resins, with manufacturing concentrated in Germany and China. Commodity price volatility for resins presents a significant structural risk, alongside logistics challenges from product weight. Distribution runs through established networks of specialized kitchen and bath retailers, and direct partnerships with residential builders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The quartz sink market presents a geographic-arbitrage play, leveraging lower production costs in emerging manufacturing hubs against premium pricing in established Western markets with stringent compliance standards.
For Market Incumbents: Cement existing market leadership by investing in advanced material science R&D to maintain product differentiation against premium natural stone competition. Deepen channel control through exclusive partnerships with residential builders in key markets like the United States. Invest in comprehensive certification processes, such as CE marking, to streamline global market access. This strategy protects against emerging entrants offering lower-cost alternatives.
For New Entrants and Emerging Players: Direct-to-consumer e-commerce platforms offer a viable entry point for new quartz sink manufacturers to bypass established distribution networks. Target commercial sectors like hospitality and healthcare, where demand for hygienic surfaces aligns with quartz composite properties. Focus on urbanizing regions in Southeast Asia, leveraging a growing middle class investing in kitchen upgrades. Emphasizing aesthetic versatility and competitive pricing for single-bowl configurations can capture mid-tier residential share.
For Investors and Strategic Acquirers: Consolidation pressure builds where capital-intensive production and complex regulatory navigation create barriers to entry for smaller players. The market exhibits strong long-term viability due to quartz's superior performance and aesthetic appeal. Target material differentiation specialists with proprietary composite formulations or integrated kitchen system providers for strategic acquisitions. A key signal to watch is sustained volatility in petroleum-derived resin prices, directly impacting manufacturer margins.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Boosts production volume to meet growing demand from urbanizing regions in Southeast Asia. |
| Advanced Resin Formulation R&D | Enhances antimicrobial properties and UV stability, providing superior value proposition for consumers. |
| Integrated Smart System Development | Incorporates hands-free faucets and water filtration, creating new value propositions in the smart home market. |
| Geographic Expansion into Commercial Sector | Diversifies revenue streams by targeting hospitality and healthcare, aligning with hygiene demands. |
| Compliance Certification Investment | Secures market access in regulated regions like Europe by adhering to CE marking requirements. |
Research Approach
Bottom-up residential and commercial end-use modeling reconciled against top-down quartz aggregate supply tracking forms the analytical core. Primary interviews with kitchen designers, residential builders, and material science engineers informed market dynamics. Secondary validation drew from ANSI/IAPMO Z124 standards, Construction Products Regulation documents, and national housing starts data. This triangulation method enhances data accuracy.
An input-output matrix framework projects market evolution by mapping raw material consumption to finished product demand across the analysis window. Segmentation dimensions modeled include product type, material composition, installation type, end-user, and regional market maturity. Compound annual growth rates were derived through regression analysis of historical performance and projected demand. Key forecast inputs include residential renovation spending and new home construction starts.
The model assumes a particular technology adoption path for non-porous composite formulations; alternative pathways for competing materials would alter the outlook. Forecasts reflect these underlying assumptions, acknowledging potential shifts in petroleum-derived resin prices or new regulatory changes. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen and Dining
United States Kitchen Furniture Market
Kitchen and Dining
Opalware Dinnerware and Crockery Market
Kitchen and Dining
Rainbow Flatware/Cutlery Market
Kitchen and Dining
China Kitchen Products Market
Kitchen and Dining
Back Table and Cart Covers Market
Kitchen and Dining
Popover Pan Market
Kitchen and Dining
Outdoor Kitchen Market
Kitchen and Dining
Oman Kitchen Hood Market
Kitchen and Dining
US Tableware Market
Kitchen and Dining
Qatar Kitchen Hood Market
Kitchen and Dining
Saudi Arabia Modular Kitchen Market
Kitchen and Dining
Bahrain Kitchen Hoods Market
Kitchen and Dining
Banquet Carts and Heated Cabinets Market
Kitchen and Dining
Vietnam Kitchen Furniture Market
Kitchen and Dining
United Arab Emirates Kitchen Furniture Market
Kitchen and Dining
Global Wooden Tableware Market