
 Sterilization Pouches Market | 2026-2036
Sterilization Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Sterilization Pouches Market Analysis
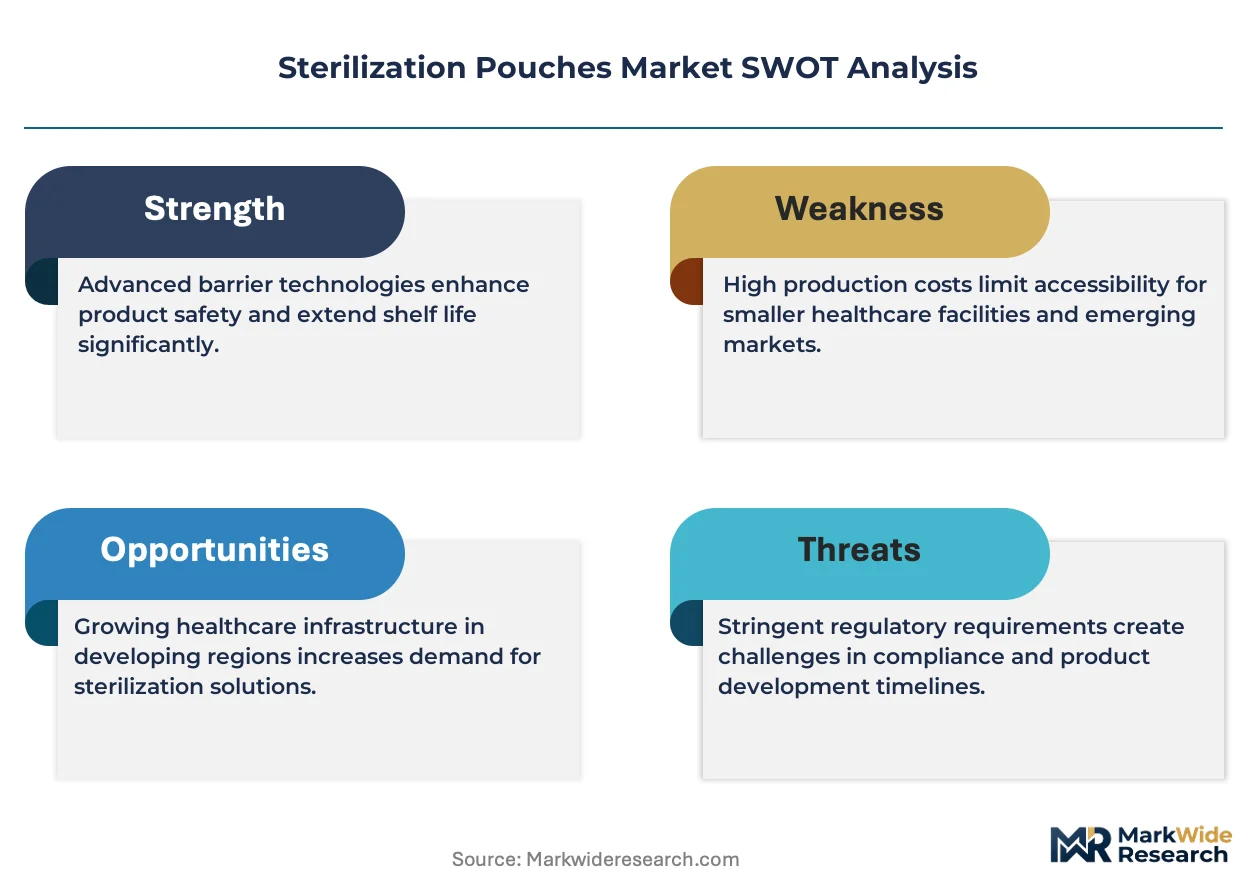
EU MDR is realigning the cost-of-entry calculus for sterile barrier suppliers by mandating enhanced clinical evidence and post-market surveillance. Amcor plc leverages its multi-layer film extrusion capabilities to sustain compliance leadership across European hospital networks. Dynarex Corporation anchors its competitive position through specialized distribution into outpatient surgical centers. 3M differentiates via adhesive seal technologies that navigate evolving validation protocols.
Sterilization pouches are multi-layer laminated enclosures, typically combining medical-grade paper with polypropylene or Tyvek films, engineered to maintain sterility of instruments after autoclave or ethylene oxide processing while permitting gas permeation and microbial exclusion. Their primary commercial purpose centers on preventing nosocomial infections during instrument storage and transport within healthcare supply chains. Flat pouches occupy the dominant volume position due to standardized dimensions compatible with high-throughput central sterile supply departments. Specialty pouches represent the fastest-expanding material category as robotic surgery instruments and elongated laparoscopic devices require customized barrier geometries. Tyvek-based configurations command premium positioning where breathable yet puncture-resistant performance determines procurement decisions.
FDA enforces sterile barrier validation under 21 CFR Part 820 quality system regulations, while ISO 11607 governs materials, design, and performance testing internationally; EMA-aligned notified bodies apply CE marking under MDR for European market access. These frameworks shape demand by elevating documentation burdens and disqualifying non-validated suppliers from hospital tender processes. Stakeholders must monitor regulatory convergence between FDA and EU notified body expectations as divergence in biocompatibility testing protocols threatens to fragment product qualification strategies.
Market Dynamics
EU MDR clinical evidence mandates are compressing the supplier base by disqualifying non-validated manufacturers from hospital tender processes, forcing sterilization pouch producers to absorb elevated post-market surveillance costs or exit European procurement channels entirely.
Growth Catalysts
- Centralized Sterilization Services:German hospital networks are consolidating instrument processing into regional hubs, generating sustained demand for standardized high-volume pouch formats compatible with automated sealing workflows.
- ISO 11607 Harmonization:International alignment of materials testing protocols is reducing qualification duplication, enabling qualified suppliers to leverage single validation packages across multiple notified body jurisdictions.
- Robotic Surgery Instrumentation:Elongated laparoscopic devices and da Vinci system accessories require customized barrier geometries, expanding the addressable market for specialty pouch configurations beyond conventional flat formats.
Market Restraints
- Medical-Grade Paper Supply Concentration:Nordic pulp suppliers control critical raw material inputs for breathable sterilization layers, exposing converters to price volatility and allocation risk during fiber harvest disruptions.
- Ethylene Oxide Emission Restrictions:EPA commercial sterilizer regulations are constraining EtO processing capacity in the United States, indirectly limiting pouch demand from instrument manufacturers dependent on gas-based sterilization cycles.
- Tyvek Duopoly Structure:DuPont and LyondellBasell dominate breathable polymer supply, limiting downstream margin negotiation leverage for independent pouch converters.
Strategic Opportunities
- Outpatient Surgical Center Expansion:Ambulatory surgery centers in Spain and Italy are building captive sterilization capabilities, creating first-mover advantages for distributors with specialized small-batch logistics.
- Sustainable Material Transition:EU Green Deal bio-based packaging targets are incentivizing development of cellulose-derived alternatives to petroleum-based polypropylene films.
- RFID-Enabled Traceability:Convergence of sterile barrier systems with wireless inventory tracking is integrating pouch-level data capture into hospital supply chain management platforms.
Industry Challenges
- Biocompatibility Testing Talent Scarcity:Qualified toxicologists capable of designing ISO 10993-compliant extractables studies command premium compensation, extending validation timelines for mid-tier manufacturers.
- Legacy Steam Sterilizer Compatibility:New pouch materials must demonstrate performance equivalence across decades-old autoclave installations prevalent in Southern European public hospitals, complicating product rollout.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sterilization Pouches Market |
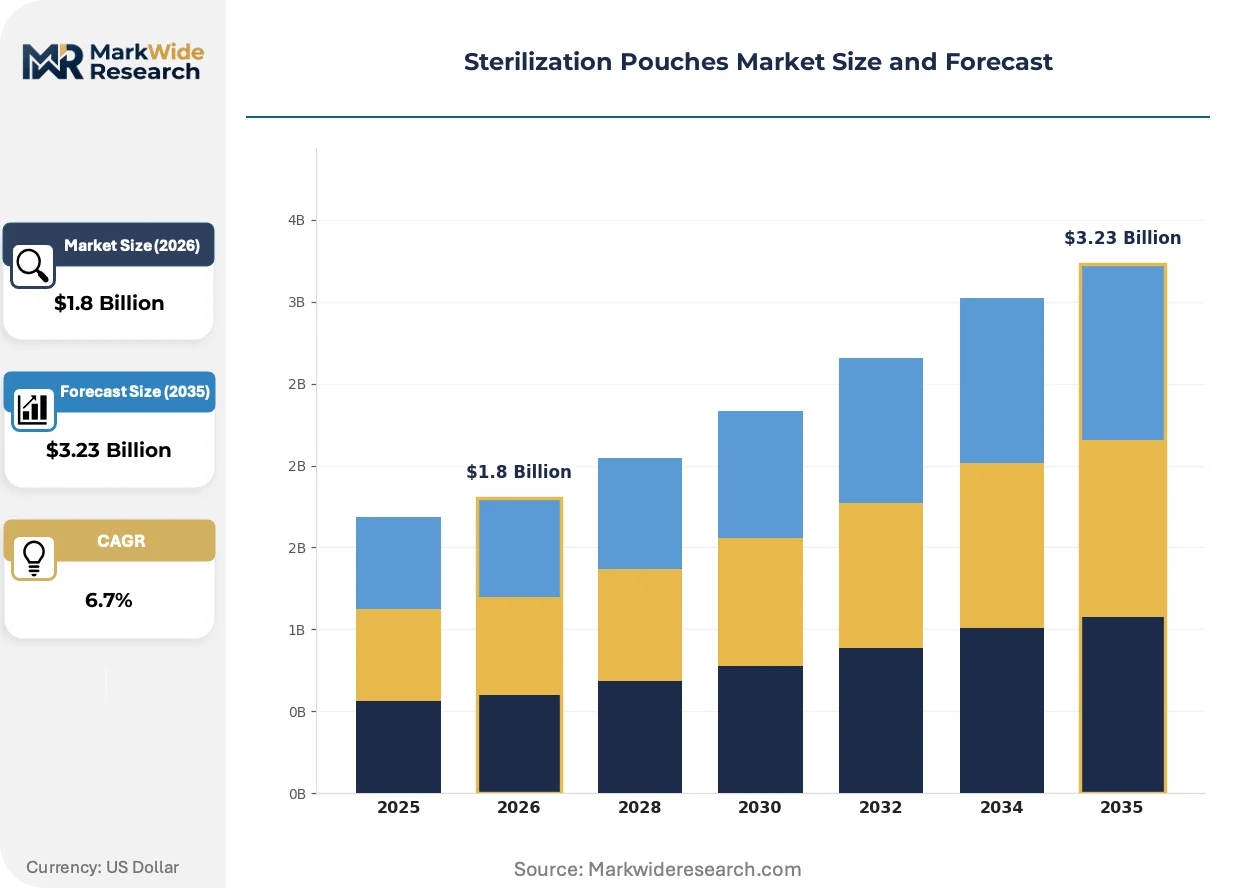
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouch Type, Roll Stock, Flat Pouches, Specialty Pouches Material: Polypropylene, Paper, Polyester, Tyvek End User: Hospitals, Dental Clinics, Laboratories, Veterinary Clinics Closure Type: Self-Seal, Heat Seal, Adhesive Seal, Zip Lock |
| Companies Covered | Amcor plc, Mondi Group, 3M, Berry Global, STERIS, Cardinal Health, Dynarex Corporation, Getinge Group, PMS Healthcare Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sterilization Pouches Market Emerging Trajectories
Active sterilization pouch development centers on breathable barrier performance enhancement, regulatory compliance automation, and supply chain digitization, with material science convergence creating differentiation vectors beyond conventional laminated paper-polypropylene constructions.
Tyvek-based multilayer films are integrating nanoscale fiber orientation controls to achieve superior microbial exclusion while maintaining gas permeation rates required for ethylene oxide sterilization cycles. University hospital networks in Switzerland and the Netherlands are piloting these configurations for orthopedic implant kits. The technology is integrating predictive sterile integrity modeling into procurement specifications, compressing qualification cycles for novel barrier designs.
EU MDR post-market surveillance requirements are mandating electronic data capture systems for sterile barrier traceability, compelling pouch manufacturers to deploy serialized production records accessible to notified bodies. Industrial consequence includes elevated IT infrastructure investment thresholds that favor larger converters with existing ERP integration capabilities. German and French hospital procurement consortia are now requiring digital device history record compatibility as a tender precondition.
Consolidated buying by European hospital group purchasing organizations is compressing supplier negotiation leverage and unbundling after-sales technical support from unit pricing. Independent distributors serving outpatient surgical centers in Belgium and Austria are responding by developing pouch-plus-validation service bundles. The shift is most visible in Benelux markets where GPO penetration exceeds seventy percent of acute care procurement volume.
Sterilization Pouches Market Segmentation
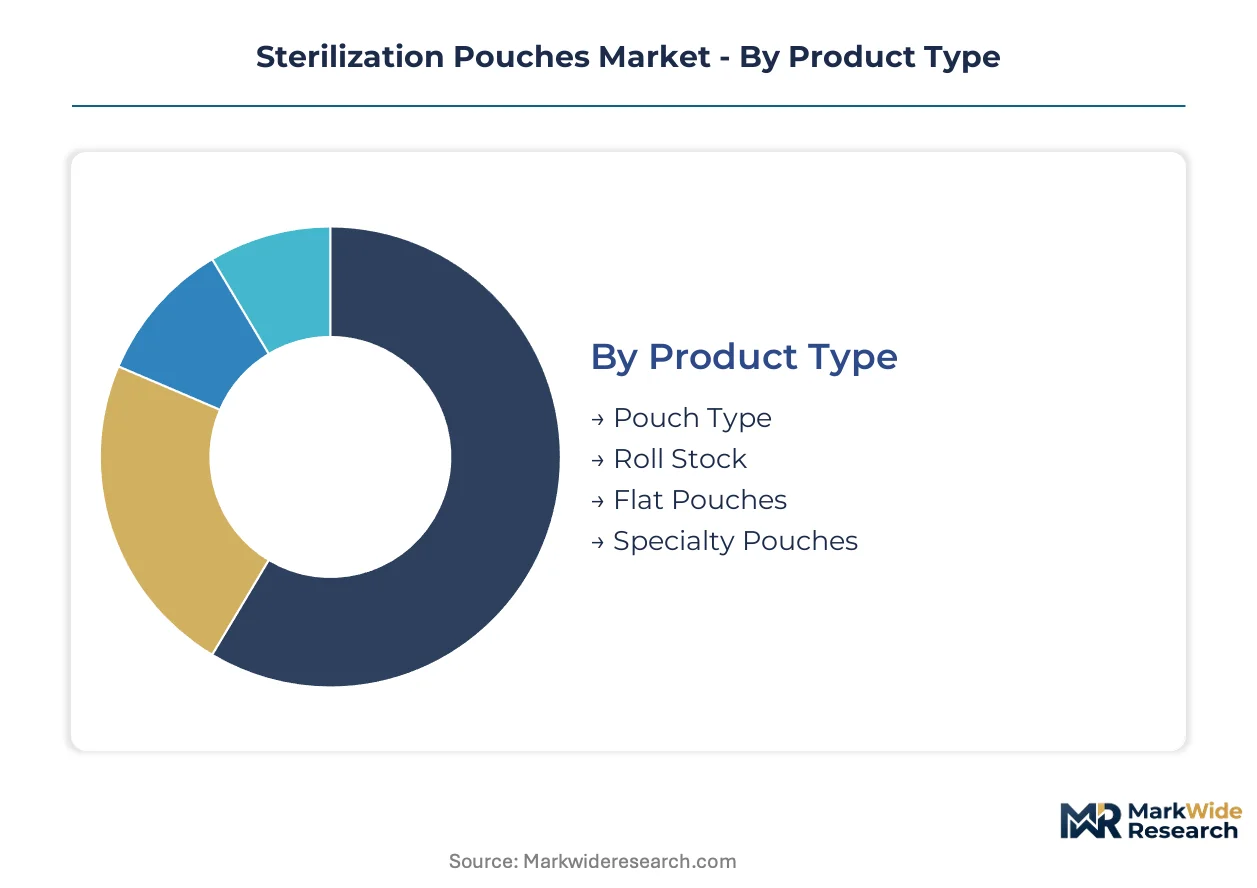
Sterilization pouch procurement patterns diverge sharply across healthcare settings, with central sterile supply departments prioritizing high-throughput formats while ambulatory surgical centers demand specialized geometries. Material selection and closure mechanisms further stratify purchasing decisions based on sterilization modality compatibility and regulatory validation requirements.
Product Type:
Hospital procurement teams segment demand by throughput velocity and instrument geometry compatibility rather than unit cost alone.
- Flat Pouches:Standardized rectangular configurations dominate central sterile supply department workflows, with German hospital networks specifying dimensions compatible with automated sealing equipment. High-volume instrument kits for orthopedic and general surgery procedures sustain procurement concentration in regional sterilization hubs.
- Specialty Pouches:Custom-engineered barrier geometries accommodate elongated robotic surgery instruments and da Vinci system accessories. Swiss and Dutch university hospital networks are qualifying these configurations for minimally invasive procedure kits where conventional flat formats fail.
- Pouch Type:Generic pre-formed enclosures serve small-batch veterinary and dental applications where standardization outweighs customization requirements.
- Roll Stock:Continuous-format material enables on-demand pouch fabrication for instrument sets with non-standard dimensions.
Flat pouches lead volumes today; specialty pouches are gaining share fastest.
Material:
Raw material selection hinges on gas permeation requirements and puncture resistance thresholds specific to sterilization modality.
- Tyvek:High-density polyethylene spunbond nonwoven delivers breathable microbial barrier performance required for ethylene oxide cycles. DuPont and LyondellBasell supply concentration limits downstream converter margin negotiation leverage.
- Polypropylene:Cast or blown film layers provide moisture barrier and heat-seal compatibility for steam sterilization applications. EU Green Deal bio-based packaging targets are incentivizing cellulose-derived alternatives.
- Paper:Medical-grade kraft pulp from Nordic suppliers forms the breathable layer in conventional laminated constructions, exposing converters to fiber harvest disruption risks.
- Polyester:High-temperature stability supports steam sterilization cycles exceeding standard polypropylene thresholds.
Polypropylene and paper laminates dominate installed base; Tyvek configurations command premium positioning.
End User:
Facility scale and accreditation intensity determine validation documentation requirements and volume procurement patterns.
- Hospitals:Acute care networks with centralized sterilization services in Germany and France mandate ISO 11607-compliant barrier systems with digital device history record compatibility. EU MDR post-market surveillance requirements are elevating supplier qualification thresholds.
- Dental Clinics:Smaller-format pouch demand concentrates in private practice settings where self-contained sterilization units process instruments between patients.
- Laboratories:Research and diagnostic facilities require validated barriers for cell culture and microbiology applications.
- Veterinary Clinics:Companion animal surgical practices generate demand for mid-volume pouch formats with simplified sealing protocols.
Hospitals anchor procurement volumes; dental clinics represent the steepest expansion trajectory as private practice consolidation accelerates.
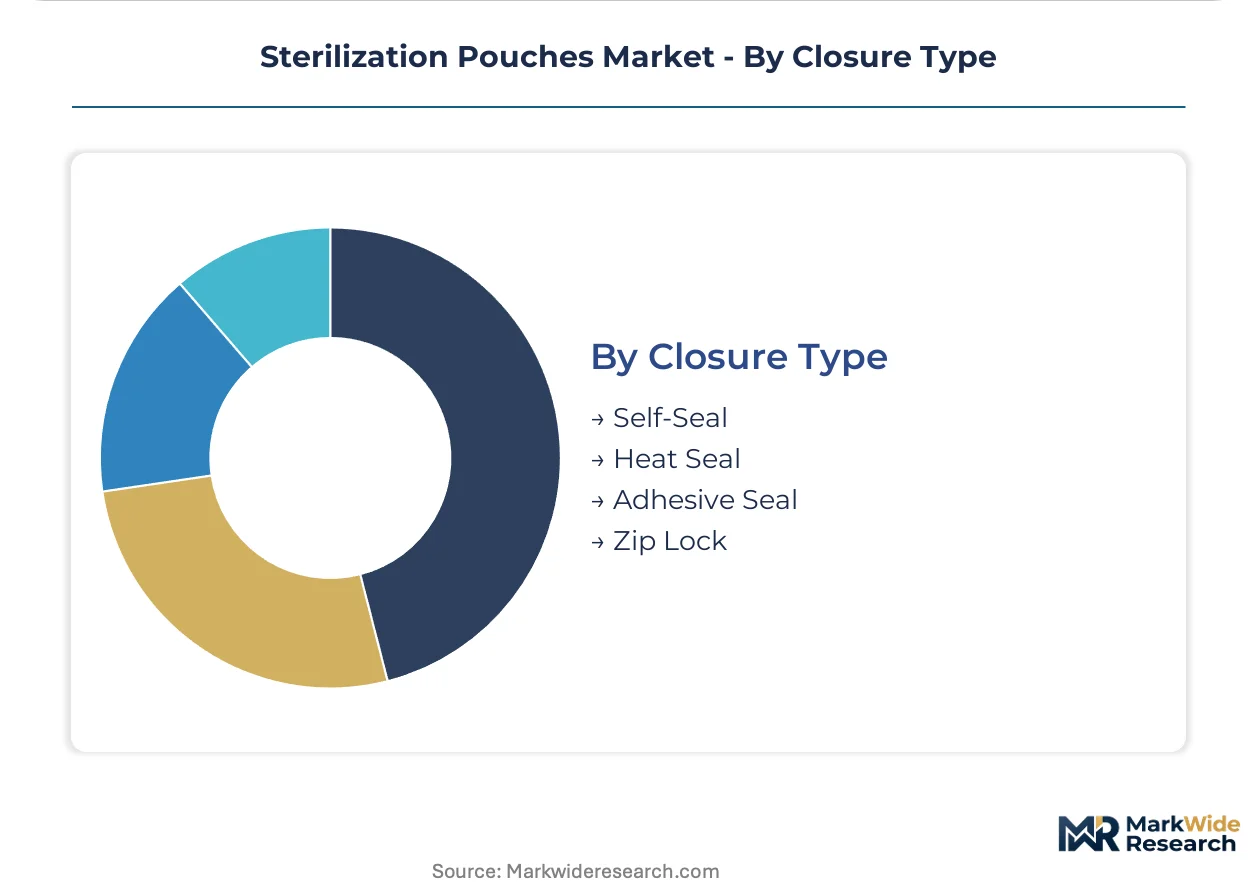
Closure Type:
Sealing mechanism selection reflects workflow automation level and sterile field opening protocol requirements.
- Self-Seal:Pressure-sensitive adhesive strips enable hand-sealing without heat equipment, suiting ambulatory surgery center workflows in Spain and Italy where captive sterilization capabilities are expanding.
- Heat Seal:Thermal fusion creates hermetic bonds compatible with high-throughput automated sealing systems in German regional sterilization hubs.
- Adhesive Seal:Specialized formulations navigate evolving FDA and EU notified body validation protocols for sterile barrier integrity.
- Zip Lock:Reclosable mechanisms serve temporary instrument storage applications where repeated access is required.
Heat seal dominates centralized processing volumes; self-seal formats are climbing fastest with outpatient surgical center expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial chemistry pioneered steam sterilization protocols during the late nineteenth century, establishing centralized instrument processing as a hospital standard. This heritage shapes contemporary procurement patterns across European healthcare networks. National regulatory frameworks now determine market access trajectories for sterile barrier suppliers.
Germany
Regional sterilization hubs in North Rhine-Westphalia and Bavaria consolidate instrument processing for multi-hospital networks, sustaining demand for high-volume flat pouch formats compatible with automated sealing workflows. EU MDR notified bodies headquartered in Berlin and Munich enforce stringent post-market surveillance documentation requirements. The Frankfurt-Rhine-Main medical technology cluster hosts validation service providers supporting pouch qualification for export markets.
United States
EPA commercial sterilizer emission regulations constrain ethylene oxide processing capacity, indirectly reshaping pouch demand from instrument manufacturers dependent on gas-based cycles. FDA 21 CFR Part 820 quality system regulations govern sterile barrier validation for domestic market access. The Minneapolis-St. Paul corridor concentrates medical device manufacturing, driving specialized pouch procurement for orthopedic and cardiovascular implant kits.
Switzerland
University hospital networks in Zurich and Geneva pilot Tyvek-based multilayer films with nanoscale fiber orientation controls for orthopedic implant applications. Swissmedic maintains alignment with EU MDR standards while preserving independent market authorization pathways. The Basel pharmaceutical-medical device nexus generates demand for validated barriers supporting cell culture and aseptic processing applications.
Netherlands
Academic medical centers in Amsterdam and Rotterdam implement RFID-enabled traceability systems integrating pouch-level data capture into supply chain management platforms. The Dutch Health and Youth Care Inspectorate enforces ISO 11607 compliance as a procurement precondition for national tender processes. The Eindhoven high-tech systems cluster fosters development of smart packaging technologies for sterile barrier applications.
France
Hospital procurement consortia in the Île-de-France region mandate digital device history record compatibility as a tender precondition, elevating IT infrastructure requirements for pouch suppliers. ANSM applies CE marking oversight under MDR alignment for European market access. The Lyon biotech corridor generates specialized demand for research-grade sterilization barriers in cell therapy and regenerative medicine applications.
Sterilization Pouches Market Vendor Landscape
The competitive structure tilts toward diversified packaging conglomerates with multi-layer film extrusion capabilities. Tiered supplier segmentation separates integrated material science leaders from regional converters serving outpatient surgical networks. Three archetypes dominate: multinational healthcare packaging specialists, medical device distributors with captive pouch lines, and independent converters focused on small-batch customization. Consolidation pressures intensify as EU MDR compliance costs compress the viable supplier base, while strategic partnerships between material suppliers and sterilization equipment manufacturers reshape channel access.
Within the multinational specialist tier, Amcor plc and 3M occupy positions anchored by adhesive seal technologies and multi-jurisdiction validation capabilities. Dynarex Corporation exemplifies the distributor-converter archetype, leveraging specialized logistics into ambulatory surgery center channels. Mondi Group represents European-based integrated paper and film suppliers navigating bio-based packaging transitions under EU Green Deal targets.
| Leading Market Players |
|---|
| Amcor plc |
| Mondi Group |
| 3M |
| Berry Global |
| STERIS |
| Cardinal Health |
| Dynarex Corporation |
| Getinge Group |
| PMS Healthcare Technologies |
| Others |
Supply Flow & Price Mechanics
Tyvek-certified premium tiers and commodity paper-polypropylene laminates diverge sharply in both procurement economics and upstream sourcing configurations. German hospital networks pay substantial premiums for DuPont-sourced breathable barriers with ISO 11607 validation packages, while outpatient surgical centers in Southern Europe prioritize unbundled per-unit pricing from regional converters.
Pricing Analysis
Bundled validation services versus unbundled commodity supply splits pricing architecture across buyer archetypes. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with EU MDR-compliant Tyvek configurations commanding substantial premiums over paper-based alternatives. Cost compression in the standard tier is intensifying because GPOs in Benelux and France are unbundling technical support from unit contracts. Dental clinics and ambulatory surgery centers exhibit highest price sensitivity; orthopedic implant kit manufacturers show lowest sensitivity due to liability exposure.
Supply Chain Analysis
Converter workforce availability constraints in Germany, Poland, and the Czech Republic limit expansion of automated sealing operations. Raw material dependencies center on Nordic medical-grade kraft pulp, DuPont and LyondellBasell Tyvek supply, and petroleum-based polypropylene resin. Single-source vulnerability in breathable polymer supply exposes downstream margins to allocation decisions by the two dominant material suppliers. Distribution runs through hospital group purchasing organizations in consolidated markets and specialized distributors in ambulatory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR compliance costs in Germany and France create structural disadvantages against notified body pathways in Switzerland and the Netherlands, compressing viable supplier bases in high-regulation jurisdictions while opening procurement windows in adjacent lower-cost validation environments.
For Market Incumbents: Anchor market position through backward integration into multi-layer film extrusion capabilities that insulate against Tyvek duopoly pricing power. Acquire ISO 10993 biocompatibility testing capabilities in-house to reduce validation timeline exposure from toxicologist talent scarcity. Prioritize ERP integration for digital device history record compatibility as French and German tender preconditions harden. For New Entrants and Emerging Players: Begin with ambulatory surgery center channels in Spain and Italy where captive sterilization buildouts outpace established distributor coverage. Target self-seal pouch formats for small-batch workflows where automated sealing infrastructure remains underdeveloped. Pursue pouch-plus-validation service bundles that differentiate against GPO-commoditized supply in Benelux markets. For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR post-market surveillance costs exceed ten million euros annually, forcing mid-tier converters toward exit. Mid-cap specialists with existing notified body relationships and digital infrastructure represent prime acquisition targets. Monitor EPA ethylene oxide emission regulation enforcement as inflection indicator for gas-sterilization dependent pouch demand.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR notified body engagement secures access to German and French hospital procurement channels. |
| Backward Integration into Film Extrusion | In-house multi-layer production reduces Tyvek duopoly exposure and protects converter margins. |
| RFID-Enabled Traceability Development | Serialized pouch data capture meets Dutch and Swiss hospital supply chain digitization requirements. |
| Hospital System Partnership | Direct relationships with German regional sterilization hubs secure high-volume flat pouch commitments. |
| Bio-Based Material Transition | Cellulose-derived alternatives align with EU Green Deal packaging targets and differentiate commodity supply. |
Methodological Framework
Multiple input streams — sterilization equipment manufacturer interviews, hospital procurement committee discussions, regulatory affairs consultations, and GPO contract analysis — were reconciled against secondary validation. Primary fieldwork engaged central sterile supply department managers, biomedical engineers, notified body auditors, and pouch converter operations directors. Secondary sources included FDA 510(k) filings for sterile barrier systems, EU MDR technical documentation databases, hospital procurement tender records, and ISO 11607 certification registries. Bottom-up demand modeling from instrument sterilization volumes was cross-referenced with top-down healthcare packaging market assessments.
Historical volume trajectories were cross-referenced against expert panel inputs to construct projection frameworks. Segmentation dimensions modeled encompass product type, material composition, sterilization modality compatibility, end-user facility scale, and regional regulatory cluster. CAGRs were derived from weighted average growth assumptions across these dimensions, with ethylene oxide processing capacity constraints and EU MDR implementation timelines as key industry-specific forecast inputs across the analysis window.
Several conditions sit outside the modeled scope, including sudden Nordic pulp supply disruptions, unilateral EPA EtO emission regulation changes, and breakthrough sterilization modalities displacing autoclave and gas-based cycles. Forecasts reflect assumptions regarding regulatory stability and material supply continuity. Material deviation in EU MDR enforcement intensity or Tyvek allocation decisions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Standcap Pouch Market
Pouch
Europe Pouch Packaging Market
Pouch
India Pouch Packaging Market
Pouch
MAP Flow Wrappers Market
Pouch
Utility Pouches Market
Pouch
Feminine Care Pouch Film Market
Pouch
Bio PE Pouches Market
Pouch
Benelux Pouch Packaging Market
Pouch
Colombia Pouch Packaging Market
Pouch
Peel Pouches Market
Pouch
Pouch-Bowl Packaging Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Asia-Pacific Pouch Packaging Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Pouch Equipment Market