
 MAP Flow Wrappers Market | 2026-2036
MAP Flow Wrappers Market Size, Share, and Industry Trends Forecast 2026-2036
MAP Flow Wrappers Market Analytics
German packaging machinery OEMs is expanding output of servo-driven flow wrap systems for protein and dairy applications. MULTIVAC leverages its vacuum-sealing heritage to dominate thermoforming-integrated lines for fresh meat. Bosch Packaging Technology sustains engineering density in high-speed horizontal configurations for bakery and confectionery. ULMA Packaging competes through modular architectures that adapt across food, healthcare, and consumer goods lines without full line reconfiguration.
MAP Flow Wrappers are automated packaging machines that enclose products in flexible films while displacing ambient atmosphere with controlled gas mixtures, typically achieving residual oxygen levels below 0.5% in sealed packs to extend shelf stability of perishables. Horizontal flow wraps occupy the largest installed base due to throughput advantages in baked goods and processed meat, while biodegradable material configurations represent the fastest-expanding segment as brand owners face EPR compliance deadlines. Vacuum packaging technology leads margin pools in premium protein applications, whereas seal technology variants serve cost-sensitive volume tiers in emerging Asian markets.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications shape material selection and recycling accountability across the value chain, with REACH chemical restrictions further constraining adhesive and coating formulations. Germany's national packaging regulator enforces stricter sorting and recovery quotas than baseline EU mandates, forcing equipment buyers to specify mono-material-compatible sealing systems. Stakeholders must weigh capital commitments against evolving extended producer responsibility frameworks before committing to platform architectures with fifteen-year depreciation horizons.
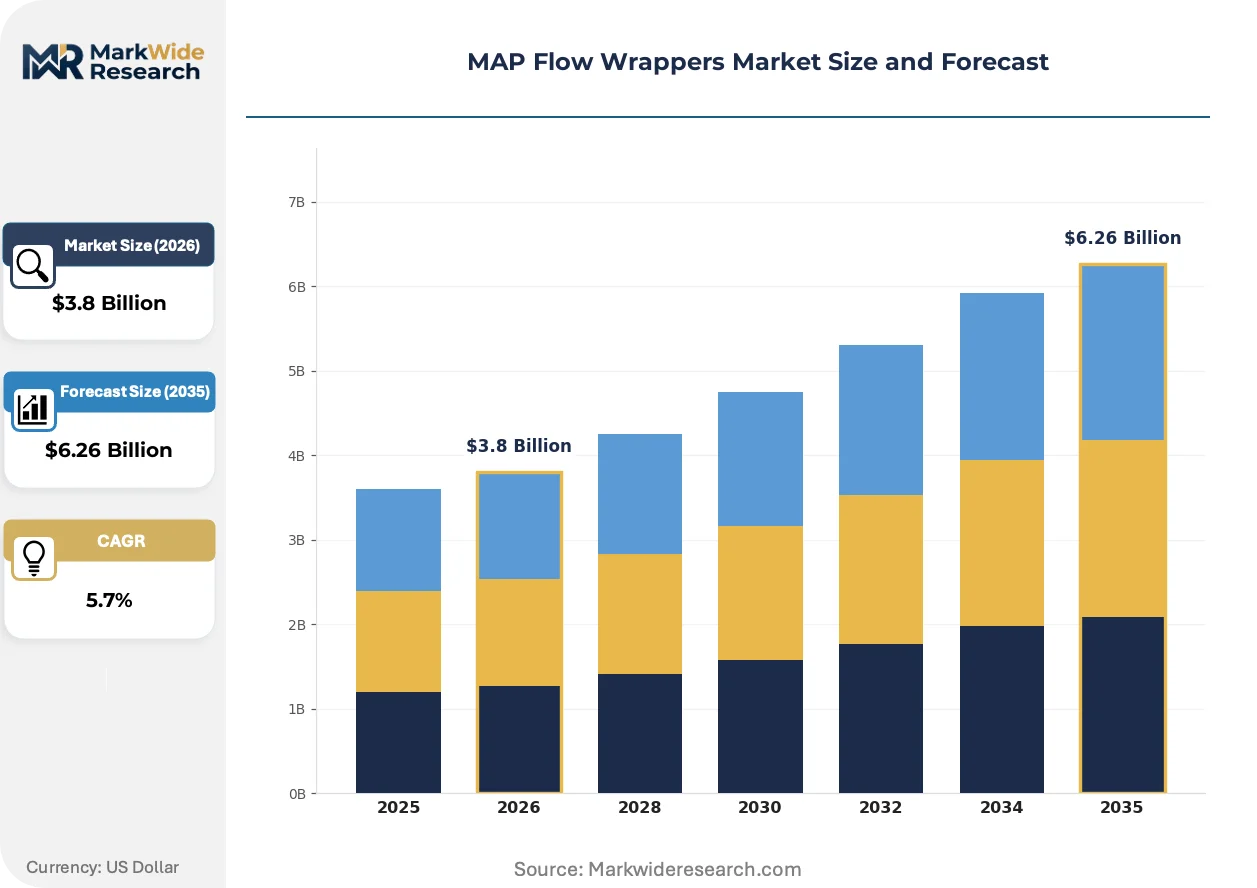
Market Dynamics
Equipment buyers across European protein processing corridors are recalibrating capital cycles around mono-material sealing architectures as EPR frameworks harden recovery accountability for flexible packaging films.
Growth Catalysts
- EPR Compliance Deadlines:Germany's national packaging regulator enforces stricter sorting quotas than baseline EU mandates, forcing automated wrapper deployment in Stuttgart and Cologne food processing clusters.
- Biodegradable Material Specifications:Brand owners in fresh produce lines are specifying sealing systems compatible with bio-based films to preempt regulatory penalties.
- Protein Sector Automation:Vacuum-integrated flow wrap lines are displacing manual packaging in premium meat operations across Bavaria and Lower Saxony.
Market Restraints
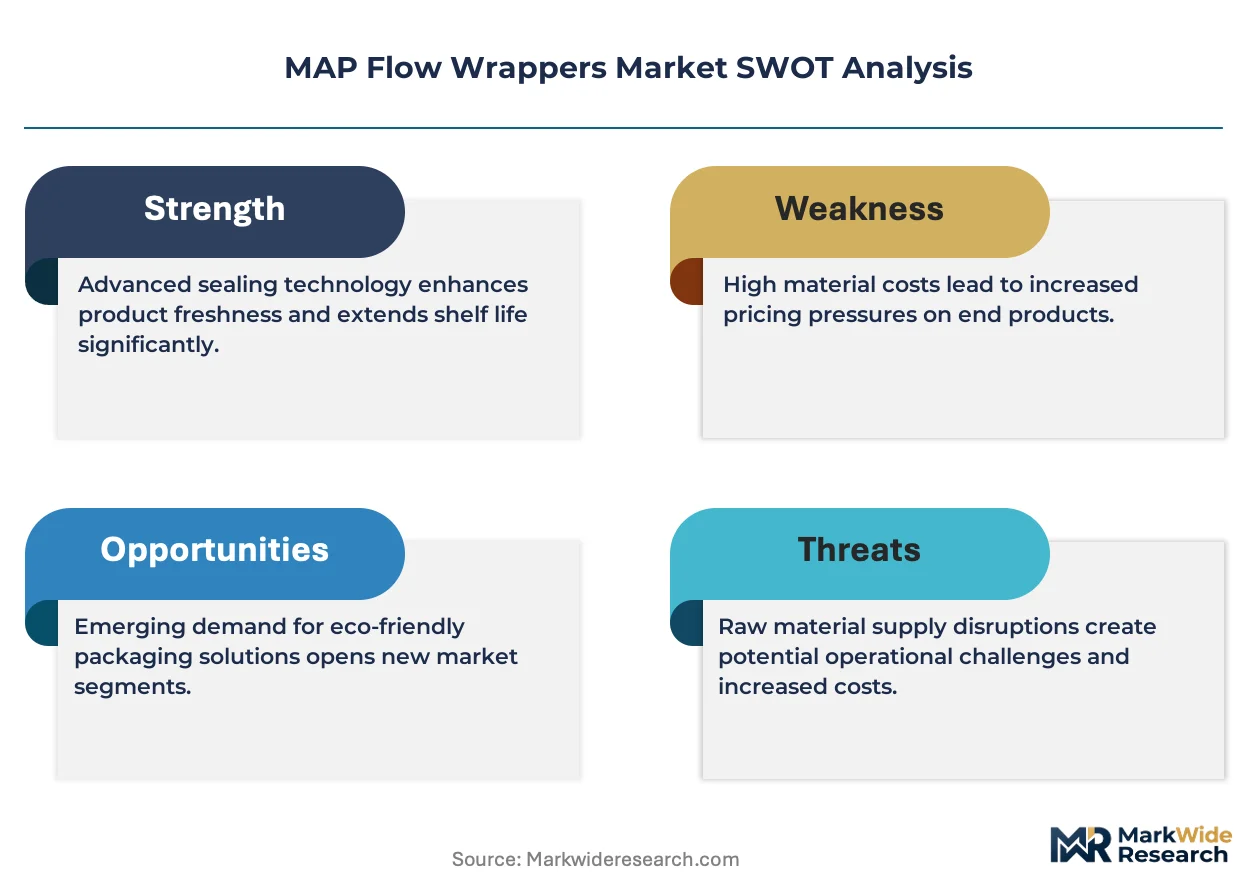
- Specialized Polymer Supply Concentration:Seal-layer resin production clusters in the Rhine-Ruhr industrial belt create input vulnerability for mono-material system builders.
- REACH Chemical Restrictions:ECHA constraints on adhesive and coating formulations extend qualification timelines for new sealing technologies.
- Thermoforming Substitution:Rigid tray-based MAP systems retain cost advantages in high-volume prepared meal segments.
Strategic Opportunities
- Healthcare Crossover Applications:Modular wrapper architectures from food lines are adapting to sterile medical device packaging under MDR compliance pathways.
- Confectionery Automation Gaps:Mid-tier bakeries in Baden-Württemberg remain underpenetrated by servo-driven horizontal systems.
- EU Green Deal Funding Windows:National innovation grants in Germany subsidize energy-efficient sealing technology retrofits.
Industry Challenges
- Mechatronics Talent Scarcity:Servo system programming expertise concentrates with aging engineering workforces in Swabian machinery districts.
- Legacy Line Integration:Brownfield bakeries face control system incompatibilities when retrofitting gas-flush capabilities onto mechanical-drive wrappers.
- CE Marking Timeline Compression:Machinery safety certification delays are extending order-to-commission cycles for export-bound equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MAP Flow Wrappers Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Flow Wraps, Vertical Flow Wraps, Automatic Flow Wraps, Manual Flow Wraps Industry Vertical: Food, Beverage, Healthcare, Consumer Goods Material: Plastic, Paper, Aluminum, Biodegradable Technology: Thermoforming, Vacuum Packaging, Modified Atmosphere Packaging, Seal Technology |
| Companies Covered | Tetra Laval, Fuji Machinery, Bosch Packaging Technology, Syntegon, ULMA Packaging, Coesia Group, MULTIVAC, IMA Group, PFM Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MAP Flow Wrappers Market Evolving Landscape
Sealing technology evolution and regulatory material mandates are compressing equipment replacement cycles while redrawing competitive boundaries between thermoforming and flexible film platforms.
Vision-guided robotic product loading is automating changeover sequences in high-mix bakery operations. Mid-tier German manufacturers are retrofitting existing horizontal flow wraps with servo-driven infeed systems to reduce format-dependent downtime. This automation is compressing labor cost differentials between established European producers and emerging equipment assemblers.
REACH chemical restrictions are constraining adhesive formulations in multi-layer seal technologies. ECHA's evolving SVHC candidate list forces continuous reformulation of coating chemistries used in gas-barrier films. Protein packagers in northern Germany are responding by accelerating qualification of solvent-free sealing alternatives ahead of regulatory phase-out dates.
After-sales service unbundling is fragmenting traditional machinery procurement relationships. Food processors in the Cologne corridor are separating hardware acquisition from maintenance contracts, pressuring OEM margins. This purchasing behavior is most pronounced among private-label meat packagers facing private-equity ownership cost targets.
MAP Flow Wrappers Market Segmentation
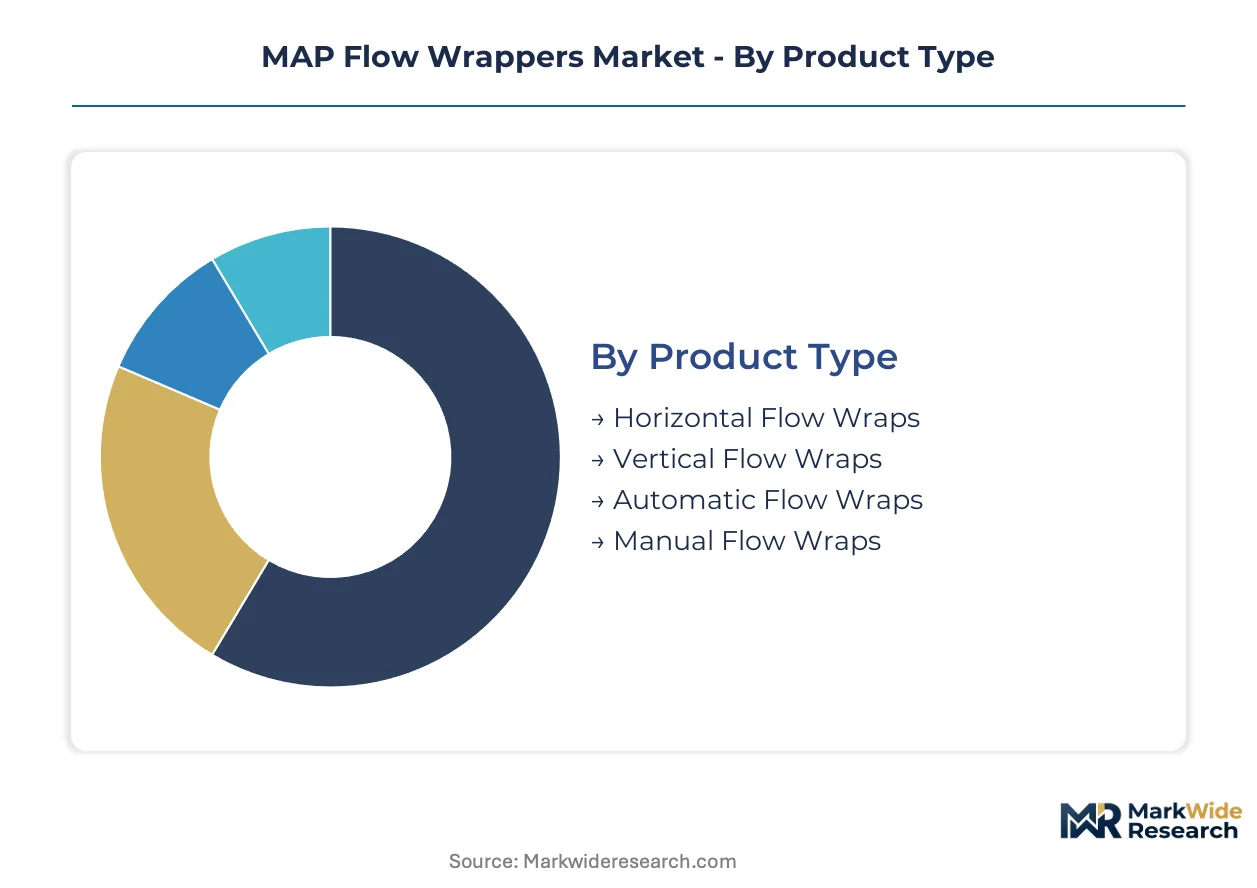
Equipment replacement cycles in MAP flow wrapping diverge sharply across product configurations, with servo-driven horizontal systems commanding premium capital allocations while legacy mechanical units face accelerated obsolescence under EPR compliance timelines. Material specification mandates and end-use shelf-life requirements create distinct technology-performance tiers that reshape procurement patterns across protein processing and fresh produce corridors.
Product Type:
Upgrade trajectories favor automated architectures with integrated gas-flush capabilities as brownfield bakeries and meat processors confront fifteen-year depreciation horizons against tightening mono-material mandates.
- Horizontal Flow Wraps:Servo-driven configurations dominate high-throughput bakery and processed meat operations, achieving residual oxygen levels below 0.5% through integrated vacuum-gas displacement sequences. German food processing clusters around Stuttgart specify these systems for automated protein packaging lines facing EU Packaging and Packaging Waste Regulation recovery targets.
- Vertical Flow Wraps:Compact footprints suit constrained production environments in mid-tier confectionery operations, though throughput limitations restrict deployment in volume-driven fresh produce applications. Bavarian private-label bakeries favor vertical configurations for single-serve portioning where floor space premiums exceed labor cost differentials.
- Automatic Flow Wraps:Vision-guided robotic loading and servo-driven infeed systems reduce format-dependent downtime in high-mix operations.
- Manual Flow Wraps:Mechanical-drive legacy units persist in artisanal cheese and specialty meat operations with sub-scale throughput requirements.
Volume placements concentrate in Horizontal Flow Wraps; the faster expansion belongs to Automatic Flow Wraps.
Industry Vertical:
End-use margin structures dictate capital intensity thresholds, with premium protein applications justifying vacuum-integrated sealing investments while cost-sensitive beverage lines prioritize standard thermoforming alternatives.
- Food:Fresh meat, bakery, and prepared meal segments drive specification of mono-material-compatible sealing systems ahead of EPR compliance deadlines. Cologne corridor meat packagers separate hardware acquisition from maintenance contracts, fragmenting traditional OEM procurement relationships.
- Beverage:Pouch-based liquid packaging favors rigid tray alternatives over flexible film flow wraps in high-volume segments.
- Healthcare:Modular architectures from food lines adapt to sterile medical device packaging under MDR compliance pathways, with ULMA Packaging configurations crossing into pharmaceutical barrier applications.
- Consumer Goods:Non-food flexible packaging demands simpler gas-barrier specifications, permitting cost-engineered seal technologies.
Capital deployment concentrates in Food; Healthcare applications are climbing the fastest.
Material:
Raw material sourcing geography and recovery infrastructure compatibility increasingly constrain specification decisions, with Rhine-Ruhr resin concentration creating supply vulnerability for specialized seal-layer formulations.
- Plastic:Multi-layer polyolefin structures dominate existing installed base but face REACH chemical restrictions on adhesive formulations. ECHA's evolving SVHC candidate list forces continuous reformulation of coating chemistries, accelerating qualification of solvent-free sealing alternatives in northern German protein operations.
- Paper:Fiber-based barriers gain traction in bakery segments with shorter shelf-life requirements and established recycling streams.
- Aluminum:Metallized films retain premium positioning in extended-shelf-life applications despite energy-intensive production profiles.
- Biodegradable:Bio-based films specified by brand owners in fresh produce lines to preempt regulatory penalties, though seal compatibility gaps persist with legacy equipment.
Installed base concentrates in Plastic; Biodegradable specifications are gaining share fastest.
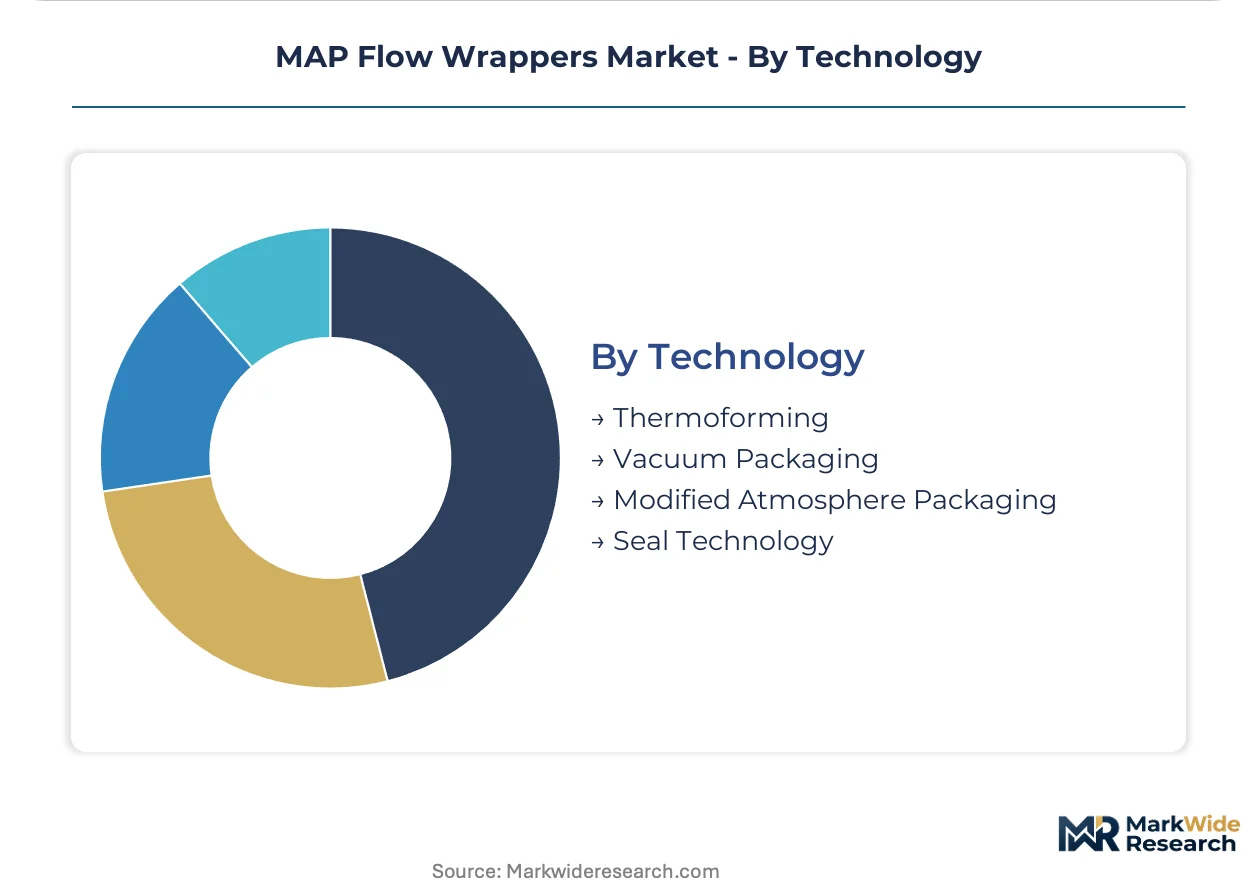
Technology:
Performance tier differentiation separates vacuum-integrated premium configurations from standard seal technologies, with qualification timelines extending for gas-barrier innovations under REACH constraints.
- Thermoforming:Rigid tray-based MAP systems retain cost advantages in high-volume prepared meal segments, constraining flexible film penetration in certain food service channels.
- Vacuum Packaging:Integrated vacuum-gas sequences command margin premiums in premium protein applications across Bavaria and Lower Saxony, with MULTIVAC heritage dominating thermoforming-integrated lines.
- Modified Atmosphere Packaging:Gas-flush capabilities with residual oxygen control extend shelf stability of perishables, specified for automated deployment in European retail chain produce lines.
- Seal Technology:Standard configurations serve cost-sensitive volume tiers with simpler barrier requirements and shorter qualification timelines.
Revenue pools concentrate in Vacuum Packaging; Modified Atmosphere Packaging applications show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized seal-layer resin production clusters in the Rhine-Ruhr industrial belt create geographic concentration for MAP flow wrapper supply chains. Equipment procurement patterns track food processing corridor density and national packaging recovery mandates.
Germany
Stuttgart and Cologne food processing clusters drive automated wrapper deployment for protein and dairy applications. Germany's national packaging regulator enforces stricter sorting quotas than baseline EU mandates, forcing mono-material sealing system specifications. Bavarian private-label meat packagers separate hardware acquisition from maintenance contracts, fragmenting traditional OEM procurement relationships.
United States
Fresh produce packaging lines across retail chains scale automated wrapper deployment for extended shelf-life applications. FDA food contact substance notifications shape material selection and recycling accountability across flexible film value chains. Protein processing corridors in the Midwest specify vacuum-integrated flow wrap lines to displace manual packaging operations.
China
Cost-sensitive volume tiers in emerging markets favor standard seal technology variants with simpler barrier requirements. SAMR and GB standards constrain adhesive and coating formulations in multi-layer structures. Yangtze River Delta food processors accelerate qualification of solvent-free sealing alternatives ahead of regulatory phase-out dates.
Japan
Premium protein applications justify vacuum-integrated sealing investments with residual oxygen control below 0.5%. METI and JIS standards govern equipment safety certification timelines for export-bound machinery. Kansai region bakeries retrofit existing horizontal flow wraps with servo-driven infeed systems to reduce format-dependent downtime.
Italy
Mid-tier confectionery operations favor vertical flow wrap configurations where floor space premiums exceed labor cost differentials. EU Packaging and Packaging Waste Regulation recovery targets accelerate equipment replacement cycles in prepared meal segments. Emilia-Romagna packaging machinery districts concentrate servo system programming expertise with aging engineering workforces.
MAP Flow Wrappers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue healthcare crossover applications and biodegradable material compatibility. The vendor base stratifies across heritage vacuum-sealing specialists, diversified packaging conglomerates, and modular architecture providers. Three archetypes dominate: thermoforming-integrated heritage players, high-speed horizontal configuration engineers, and modular system architects. Competitive moves center on M&A for sealing technology portfolios and geographic expansion into Asian protein processing corridors.
Among diversified packaging conglomerates, Tetra Laval and Coesia Group exemplify scale-driven platform strategies spanning multiple barrier technologies. Heritage vacuum-sealing specialists such as MULTIVAC occupy positions in premium protein applications, leveraging thermoforming integration expertise. Fuji Machinery represents the high-speed horizontal configuration archetype, while ULMA Packaging anchors the modular architecture tier with cross-sector adaptability. Bosch Packaging Technology and Syntegon sit within the engineered-systems tier, sustaining engineering density in servo-driven configurations. IMA Group and PFM Packaging exemplify regional specialists with concentrated presence in European food processing corridors.
| Leading Market Players |
|---|
| Tetra Laval |
| Fuji Machinery |
| Bosch Packaging Technology |
| Syntegon |
| ULMA Packaging |
| Coesia Group |
| MULTIVAC |
| IMA Group |
| PFM Packaging |
| Others |
Value Network & Pricing Analysis
Seal-layer resin procurement from Rhine-Ruhr petrochemical clusters feeds through three distinct pricing tiers as equipment buyers unbundle after-sales service contracts from hardware acquisition. This input cost concentration amplifies margin pressure for mono-material system builders while creating negotiation leverage for private-label meat packagers in Cologne and Stuttgart corridors.
Pricing Analysis
Warranty and maintenance unbundling is fragmenting traditional machinery procurement relationships. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-integrated servo systems from mechanical-drive legacy units and compact vertical configurations. Price differentiation hinges on CE marking tier and after-sales service bundling. Cost compression in standard seal technology tiers is intensifying because private-equity-owned processors demand hardware-only procurement. Mid-tier bakeries in Baden-Württemberg exhibit highest price sensitivity; premium protein processors in Bavaria show lowest.
Supply Chain Analysis
Dual-sourcing mandates from German food processing clusters require seal-layer resin qualification from at least two Rhine-Ruhr suppliers plus one Asian alternative. Component dependencies center on servo motor drives, gas-barrier film formulations, and vacuum pump assemblies. Single-source vulnerability concentrates in specialized polymer production clusters. Distribution runs through OEM direct sales for large accounts and machinery dealer networks for mid-tier installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MAP flow wrapper market sits in a servo-driven automation transition as legacy mechanical-drive systems face accelerated obsolescence under EPR compliance deadlines. Gas-flush integrated horizontal configurations are displacing manual and semi-automatic legacy lines.
For Market Incumbents: Deploy backward integration into seal-layer resin formulation to secure mono-material supply continuity against Rhine-Ruhr concentration risk. Accelerate healthcare crossover certification investments to offset margin erosion in saturated protein processing corridors. Thermoforming substitution in prepared meal segments and emerging Asian equipment assemblers represent dual threats requiring defensive positioning. For New Entrants and Emerging Players: Begin with underpenetrated mid-tier confectionery automation in Baden-Württemberg, where floor space constraints and labor cost differentials favor compact vertical configurations. Target healthcare sterile packaging applications under MDR compliance pathways as the most penetrable adjacent vertical. Pursue EU Green Deal funding qualification as the primary go-to-market mechanism for energy-efficient sealing technology introductions. For Investors and Strategic Acquirers: After-sales service contract unbundling by private-equity-owned meat packagers is the leading indicator that recurring revenue streams are decoupling from hardware margins, compressing traditional OEM valuation multiples. Five-to-ten year viability favors modular architecture specialists with cross-sector adaptability. Acquisition targets should demonstrate bio-based film sealing compatibility and healthcare certification pathways. Watch for EPR enforcement acceleration in Germany as the signal for equipment replacement cycle inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Sealing System Development | REACH-compliant architectures preempt EPR penalties in German protein processing corridors. |
| Healthcare Crossover Certification | MDR pathway expansion opens sterile medical device packaging to food-line modular systems. |
| Servo-Driven Retrofit Programs | Brownfield bakeries in Swabian districts reduce format-dependent downtime without full line replacement. |
| Solvent-Free Sealing Qualification | ECHA SVHC restrictions force adhesive reformulation in northern German protein operations. |
| After-Sales Service Unbundling Response | OEMs must restructure pricing to capture value from hardware-only procurement trends. |
Research Methodology
Multi-period observation of equipment procurement patterns, regulatory filing timelines, and resin price indices anchored the trend analysis, supplemented by interviews with packaging machinery OEM product managers, protein processing plant engineers, and EPR compliance officers at brand owners. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, ECHA SVHC candidate list updates, and machinery trade association shipment data. Bottom-up triangulation across installation base estimates and top-down cross-check against capital expenditure disclosures ensured convergence.
Input-output matrices mapped seal-layer resin costs, servo system pricing, and gas-flush technology premiums against end-use margin structures across the projection horizon. Segmentation dimensions modeled include product configuration, industry vertical, material specification, and technology tier. CAGRs were derived from equipment replacement cycle analysis against compliance deadline schedules. Forecast inputs incorporated EPR enforcement intensity scenarios and bio-based film adoption curves.
Regulatory phase-out acceleration, raw material supply disruption in Rhine-Ruhr clusters, and thermoforming technology cost breakthroughs are the dominant revision risks to modeled equipment demand. Forecasts reflect assumptions about EPR implementation timelines and mono-material compatibility qualification rates. A model refresh is warranted upon material change in EU Packaging and Packaging Waste Regulation enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Spain Pouch Packaging Market
Pouch
Portion Control Packs Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Italy Pouch Packaging Market
Pouch
Clipless Vertical Pouches Market
Pouch
2 Seal Pouches Market
Pouch
Monodose Packs Market
Pouch
Paper Pouch Market
Pouch
Global Boil-In Bags Market
Pouch
Germany Pouch Packaging Market
Pouch
Kraft Paper Pouch Market
Pouch
Retort Pouch Market
Pouch
Zipper Pouch Market
Pouch
Heat Seal Pouch Market
Pouch
Child Resistant Single Dose Pouches Market
Pouch
Stand Up Paper Pouches Market