
 Self-Seal Pouches Market | 2026-2036
Self-Seal Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Seal Pouches Market Analytics
Medical-grade validation tiers is bifurcating the competitive landscape between commodity converters and sterile-barrier specialists. Amcor leverages its pharmaceutical certification infrastructure to dominate high-barrier pouch segments in North America. Berry Global sustains cost-competitive positions across retail and food-grade applications through manufacturing scale. STERIS specializes in sterilization-compatible formats, anchoring demand from hospital central supply chains.
Self-seal pouches are flexible packaging structures incorporating integrated closure mechanisms—adhesive strips, zip locks, or heat-sealable layers—typically constructed from multi-laminate films with specified oxygen transmission rates below 0.1 cc per square meter per day for barrier applications. These configurations serve to protect contents from contamination, moisture ingress, and gas exchange while enabling repeated access without external sealing equipment. Stand-up pouches and zipper pouches capture expanding shelf-space premiums in retail environments, while flat pouches retain volume dominance in medical sterilization trays where dimensional consistency matters. Biodegradable films represent the fastest-growing material trajectory, though plastic laminates still concentrate margin pools in high-barrier pharmaceutical applications.
FDA 21 CFR Part 820 quality system regulations and EU MDR sterile barrier requirements shape validation protocols for medical-grade self-seal pouches, with ISO 11607 providing harmonized testing frameworks for seal strength and microbial barrier performance. EPA guidelines on volatile organic compound emissions from adhesive-based closures influence material selection in North American manufacturing. Stakeholders must monitor evolving biodegradability certifications and regional single-use plastic restrictions as these frameworks increasingly determine market access and product qualification pathways.
Market Dynamics
Medical sterilization packaging demands are bifurcating converter capabilities, with FDA and EU MDR validation requirements forcing capital redeployment toward barrier-certification infrastructure and away from commodity pouch production.
Growth Catalysts
- EU MDR sterile barrier mandates:Hospital central supply departments across Germany, France, and Italy are accelerating qualification of pre-sterilized pouch formats to eliminate in-house sterilization bottlenecks.
- Biodegradable film innovation:PLA and PHA laminates are capturing shelf-space premiums in European retail environments as single-use plastic restrictions tighten material specifications.
- Frankfurt-Stuttgart converter clustering:Specialized medical packaging networks in southern Germany enable rapid prototyping and validation turnaround for sterilization-compatible pouch designs.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Asian petrochemical suppliers control 70% of high-barrier EVOH feedstock, exposing European converters to input cost volatility and currency mismatch risks.
- ISO 11607 certification timelines:Seal-strength and microbial-barrier testing protocols extend product qualification cycles to 18-24 months, freezing working capital in pre-revenue inventory.
- Reusable rigid sterilization containers:Hospital systems in the Netherlands and Denmark are piloting metal tray alternatives that eliminate single-use pouch consumption in non-critical instrument sets.
Strategic Opportunities
- Polish and Romanian hospital modernization:EU structural funds are financing central sterile supply department upgrades in Eastern European markets currently served by unpackaged instrument flows.
- Home healthcare infusion therapy:Self-administered parenteral nutrition and antibiotic protocols are creating demand for patient-portable, multi-dose pouch formats with tamper-evident closures.
- EU Green Deal biodegradability incentives:Packaging converters certifying to EN 13432 compostability standards gain preferential procurement status in French and Belgian public hospital tenders.
Industry Challenges
- Adhesive formulation chemists:The intersection of high-barrier performance, heat-seal compatibility, and VOC compliance under EPA guidelines has created acute talent scarcity in European converter R&D functions.
- Legacy sterilization validation:Gamma and ethylene oxide compatibility testing for new film laminates requires capital-intensive cobalt-60 or EO chamber access, constraining mid-tier converter innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Seal Pouches Market |
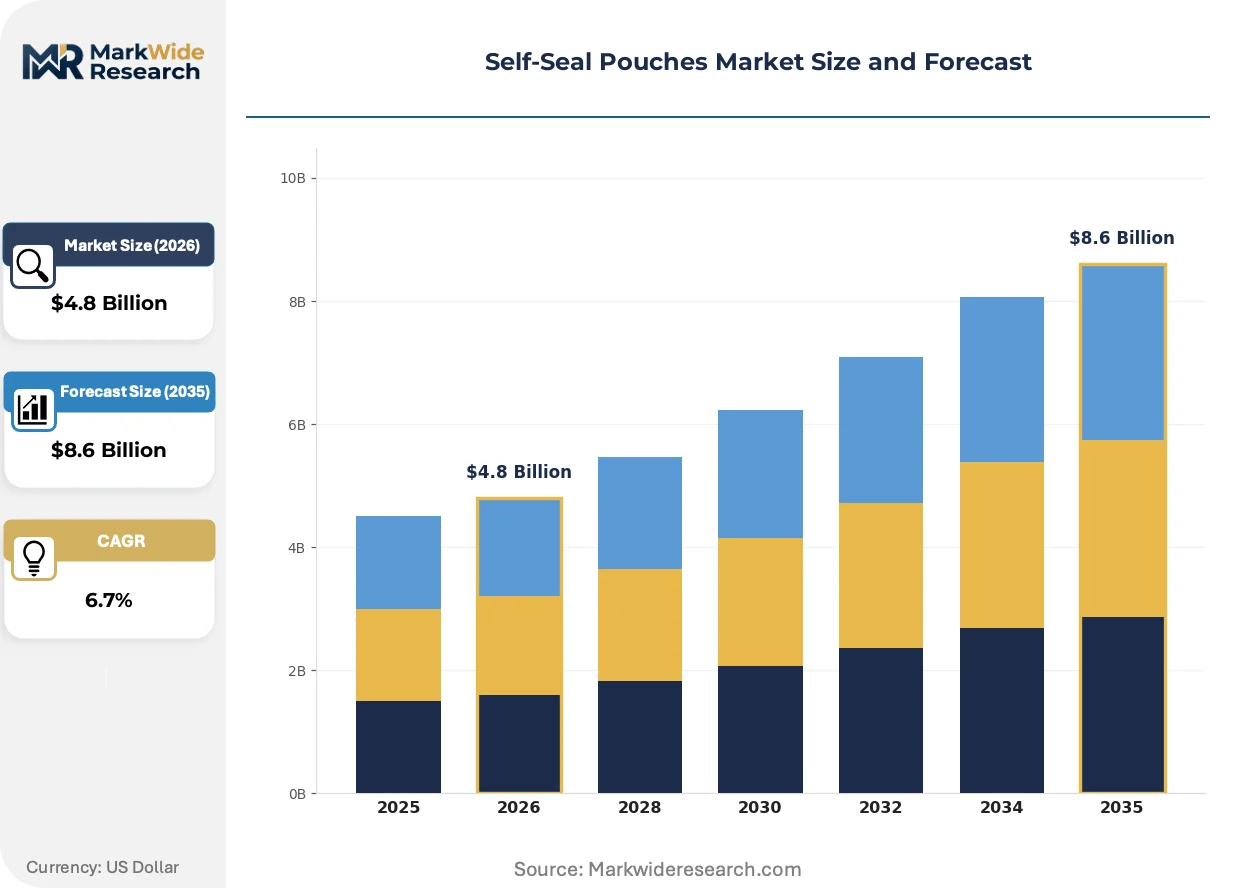
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Pouches, Gusseted Pouches, Zipper Pouches, Stand-Up Pouches Material: Plastic, Paper, Foil, Biodegradable Films Application: Food Packaging, Medical Supplies, Retail, Household Items Closure Type: Adhesive Seal, Zip Lock, Heat Seal, Velcro |
| Companies Covered | Amcor, Berry Global, Mondi, 3M, Proampac, STERIS, Cardinal Health, Getinge Group, Dynarex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Seal Pouches Market Evolving Landscape
Multi-layer coextrusion and digital printing technologies are compressing development cycles while regulatory pressure on barrier validation is elevating technical specification thresholds across medical and food-grade segments.
Water-based adhesive heat-seal layers are displacing solvent-based systems in high-barrier pharmaceutical pouches. German and Swiss contract manufacturers are adopting these formulations to preempt EPA VOC enforcement actions and secure FDA 510(k) companion device approvals. The shift is compressing margin structures for converters lacking in-house adhesive compounding capabilities.
EU MDR Annex I general safety and performance requirements are mandating quantitative microbial barrier testing for all sterile barrier systems. Pouch manufacturers serving the European market are revalidating entire product portfolios under ISO 11607-1 seal strength and dye penetration protocols. Small converters without dedicated regulatory affairs functions are outsourcing compliance to specialized testing laboratories in Frankfurt and Milan.
Hospital procurement departments are consolidating sterilization pouch suppliers to reduce qualification overhead. French and Belgian hospital groups are moving from 15-20 approved vendors to 3-4 strategic partnerships with full validation documentation. The concentration is favoring converters with integrated sterile barrier manufacturing and in-house microbiology testing capabilities in the Rhône-Alpes and Flanders regions.
Self-Seal Pouches Market Segmentation
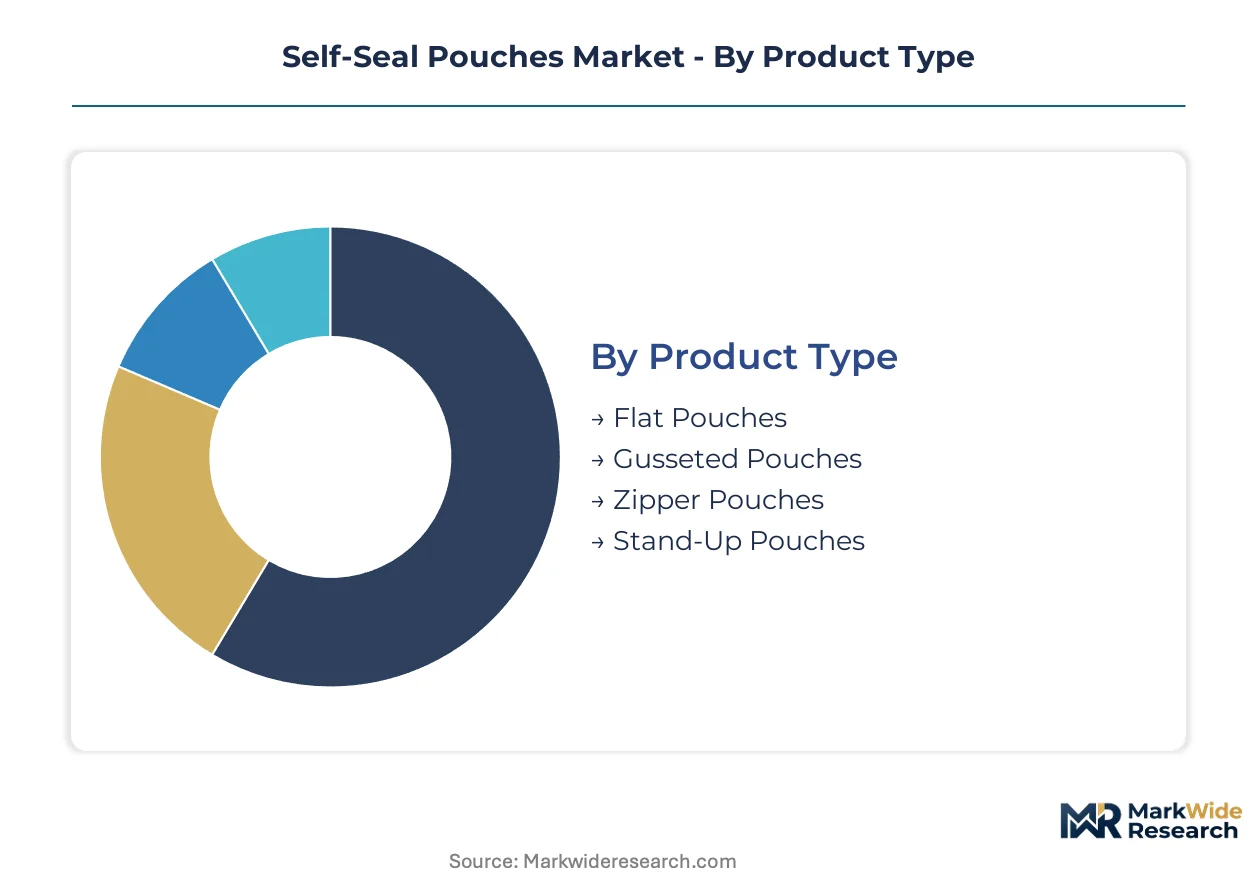
Segmentation in the self-seal pouches market reveals how validation requirements and channel access reshape competitive positioning. Converter capabilities fragment across medical-grade sterilization packaging and commodity retail formats, with certification tiers determining margin pools and customer stickiness.
Product Type:
Hospital central supply departments and retail shelf-space buyers source through entirely different channel structures, with medical procurement favoring dimensional consistency and retail prioritizing visual merchandising.
- Flat Pouches:Two-dimensional laminates with heat-sealable layers and specified oxygen transmission rates below 0.1 cc per square meter per day. German hospital systems around Frankfurt and Stuttgart standardize on flat formats for sterilization trays requiring stackable geometry and minimal dimensional variation.
- Stand-Up Pouches:Bottom-gusseted structures enabling vertical shelf display with integrated reclosure mechanisms. French and Belgian retail environments capture expanding shelf-space premiums as single-use plastic restrictions tighten specifications for consumer-facing packaging.
- Gusseted Pouches:Side-folded expansions accommodating bulk contents in industrial and food-service channels.
- Zipper Pouches:Track-and-slider reclosure systems dominating household storage and multi-dose pharmaceutical applications.
Flat pouches dominate installed base in medical sterilization. Stand-up pouches are where expansion concentrates in European retail environments.
Material:
Cost tiers separate commodity converters from sterile-barrier specialists, with certification infrastructure determining which material grades access pharmaceutical procurement channels.
- Plastic:Multi-laminate films incorporating EVOH barrier layers and polyethylene sealant webs. Asian petrochemical suppliers control upstream feedstock concentration, exposing European converters to input cost volatility and currency mismatch exposure.
- Biodegradable Films:PLA and PHA laminates certifying to EN 13432 compostability standards. French and Belgian public hospital tenders grant preferential procurement status to converters meeting EU Green Deal biodegradability incentives.
- Foil:Aluminum-laminate structures providing near-zero moisture vapor transmission for pharmaceutical stability applications.
- Paper:Fiber-based substrates with polymer barrier coatings serving limited food-service and retail segments.
Plastic laminates dominate installed base in high-barrier pharmaceutical applications. Biodegradable films are climbing the fastest as regional single-use plastic restrictions determine market access.
Application:
Volume concentration varies sharply by end-use, with medical sterilization packaging demanding eighteen-to-twenty-four-month qualification cycles that freeze working capital in pre-revenue inventory.
- Medical Supplies:Sterile barrier systems validated under FDA 21 CFR Part 820 and EU MDR Annex I requirements. Hospital central supply departments across Germany, France, and Italy accelerate qualification of pre-sterilized formats to eliminate in-house sterilization bottlenecks.
- Food Packaging:Modified-atmosphere and vacuum-compatible structures with oxygen scavenging layers. Retail shelf-space premiums in European supermarkets drive specification for stand-up and zipper formats with extended reclosure durability.
- Retail:General merchandise and apparel packaging with tamper-evident features.
- Household Items:Storage and organization applications with lower barrier requirements.
Medical supplies dominate installed base in validated barrier applications. Food packaging is where volume expansion concentrates as retail format innovation accelerates.
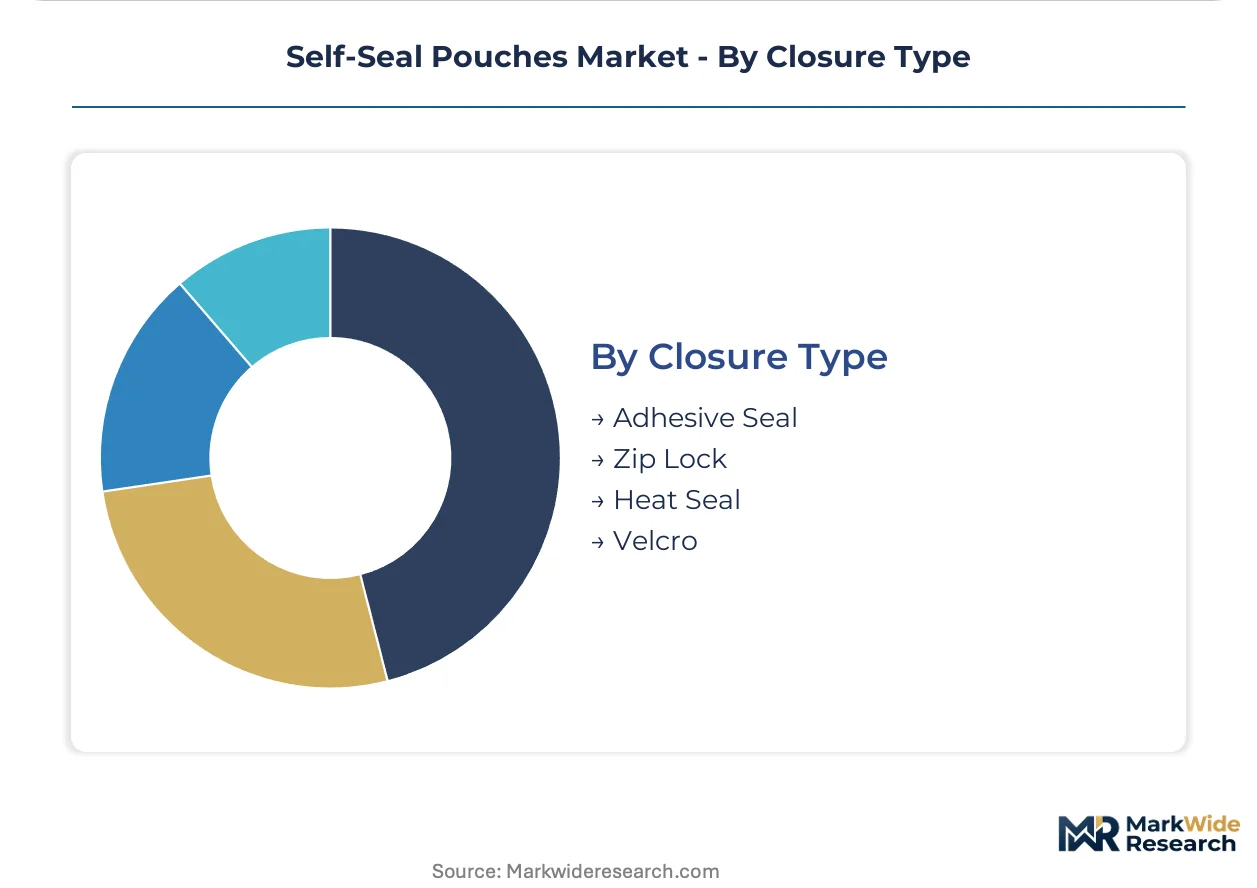
Closure Type:
Supply concentration in adhesive formulation chemistry creates capability scarcity at the intersection of high-barrier performance, heat-seal compatibility, and VOC compliance.
- Heat Seal:Thermal-activation layers requiring specified temperature and dwell time parameters. German and Swiss contract manufacturers adopt water-based adhesive formulations to preempt EPA enforcement actions and secure FDA 510(k) companion device approvals.
- Adhesive Seal:Pressure-sensitive strips enabling equipment-free closure. Home healthcare infusion therapy applications create demand for patient-portable, multi-dose formats with tamper-evident features in self-administered parenteral nutrition protocols.
- Zip Lock:Interlocking track systems for repeated access without seal degradation.
- Velcro:Hook-and-loop fasteners limited to non-barrier household and retail applications.
Heat seal dominates installed base in pharmaceutical sterilization packaging. Adhesive seal is where application expansion concentrates in patient-portable healthcare formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances reshape regional competitive positioning, with European converters importing EVOH barrier feedstock from Asian petrochemical suppliers while medical-grade pouch formats flow toward hospital systems in Germany, France, and Italy. Currency mismatch exposure concentrates margin pressure on converters lacking long-term supply contracts.
Germany
Hospital central supply departments in Frankfurt and Stuttgart drive sterilization pouch qualification volumes. EU MDR Annex I mandates quantitative microbial barrier testing for all sterile barrier systems, forcing converters toward ISO 11607-1 revalidation cycles. The Frankfurt-Stuttgart corridor anchors specialized medical packaging networks enabling rapid prototyping turnaround.
United States
FDA 21 CFR Part 820 quality system regulations govern sterile barrier validation protocols for pharmaceutical applications. Water-based adhesive heat-seal layers displace solvent-based systems as German and Swiss contract manufacturers adopt EPA-compliant formulations to preempt enforcement actions. Domestic converters face input cost volatility from EVOH resin concentration in Asian supply chains.
France
Hospital procurement consolidation reduces approved sterilization pouch vendors from 15-20 to 3-4 strategic partnerships. EU Green Deal biodegradability incentives grant preferential tender status to converters certifying to EN 13432 compostability standards. Rhône-Alpes region hosts converters with integrated sterile barrier manufacturing and in-house microbiology testing capabilities.
China
Asian petrochemical suppliers control 70% of high-barrier EVOH feedstock, positioning Chinese converters upstream of European and North American demand. NMPA regulations shape domestic medical packaging qualification frameworks. Manufacturing clusters in the Yangtze River Delta supply multi-laminate films with specified oxygen transmission rates below 0.1 cc per square meter per day.
Poland
EU structural funds finance central sterile supply department upgrades in Eastern European markets transitioning from unpackaged instrument flows. Hospital modernization programs create qualification demand for pre-sterilized pouch formats. Warsaw and Krakow medical device distribution hubs channel Western European converter products into regional healthcare procurement networks.
Self-Seal Pouches Market Competitive Landscape
Concentration sits with sterile-barrier specialists holding FDA and EU MDR validation infrastructure, while commodity converters compete on manufacturing scale in retail and food-grade segments. The market structures around three archetypes: pharmaceutical certification leaders, cost-competitive scale operators, and sterilization-compatible format specialists. M&A activity targets barrier-certification capabilities, and capacity expansion concentrates in southern Germany and the Rhône-Alpes region.
Within the pharmaceutical certification tier, Amcor leverages North American infrastructure to dominate high-barrier pouch segments, while Berry Global sustains cost-competitive positions across retail applications through manufacturing scale. STERIS occupies a specialist position anchoring demand from hospital central supply chains with sterilization-compatible formats. These three exemplify how validation tiers determine margin pools and customer stickiness in medical-grade applications.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Mondi |
| 3M |
| Proampac |
| STERIS |
| Cardinal Health |
| Getinge Group |
| Dynarex Corporation |
| Others |
Value Network & Pricing Analysis
Water-based adhesive heat-seal layers displacing solvent-based systems simultaneously shift supply geography toward German and Swiss contract manufacturers while compressing margin structures for converters lacking in-house adhesive compounding capabilities. This substitution dynamic redirects procurement flows from Asian solvent-chemical suppliers toward European water-based formulation specialists, elevating landed costs for North American buyers dependent on EPA-compliant inputs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in medical-grade self-seal pouches. Price differentiation hinges on FDA 510(k) certification tier and volume scale commitments, with hospital central supply departments showing lowest sensitivity due to eighteen-to-twenty-four-month qualification lock-in. Pricing pressure stems from EVOH resin concentration in Asian petrochemical supply chains, squeezing converters without long-term feedstock contracts. Retail and food-grade segments exhibit highest price sensitivity, driving commodity converters toward manufacturing scale defenses.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for EVOH barrier feedstock shipments. Supply concentrates in China, South Korea, and Japan for high-barrier resin feedstock, while finished pouch manufacturing clusters in Germany, France, and Poland. Raw material dependencies center on ethylene vinyl alcohol resin, polyethylene sealant webs, and water-based adhesive formulations. Single-source vulnerability from Asian petrochemical concentration exposes European converters to currency mismatch risks. Distribution runs through hospital GPO contracts in Western Europe and medical device distribution hubs in Warsaw and Krakow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR sterile barrier mandates are accelerating qualification demand for pre-sterilized pouch formats, creating a regulatory inflection that favors converters with integrated validation infrastructure over commodity manufacturers.
For Market Incumbents: Compound barrier-certification capabilities through ISO 11607-1 testing infrastructure investments in the Frankfurt-Stuttgart corridor to defend against mid-tier converters outsourcing compliance. Deepen upstream control over water-based adhesive formulation chemistry to preempt EPA enforcement actions and secure FDA 510(k) companion device approvals. Anchor hospital central supply relationships through multi-year validation documentation partnerships that freeze out competitors. For New Entrants and Emerging Players: Lead with biodegradable film innovation targeting French and Belgian public hospital tenders where EU Green Deal incentives grant preferential procurement status to EN 13432-certified converters. Exploit white-space in Polish and Romanian hospital modernization programs financed by EU structural funds, positioning for central sterile supply department upgrades transitioning from unpackaged instrument flows. Pursue home healthcare infusion therapy segments with patient-portable, multi-dose pouch formats for self-administered parenteral nutrition protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors sterile-barrier specialists with integrated microbiology testing capabilities over commodity scale operators. Long-term viability over a five-to-ten year window hinges on regulatory certification moats rather than manufacturing throughput. Target acquisition archetypes include mid-tier converters in the Rhône-Alpes and Flanders regions with EU MDR validation pipelines. Watch hospital procurement consolidation signals—vendor reduction from fifteen-to-twenty approved suppliers to three-to-four strategic partnerships—as the inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 11607-1 Certification Investment | Enables FDA 510(k) and EU MDR sterile barrier qualification for hospital central supply procurement. |
| Water-Based Adhesive Formulation Transition | Preempts EPA VOC enforcement actions while securing pharmaceutical companion device approvals. |
| Biodegradable Film Certification to EN 13432 | Unlocks preferential tender status in French and Belgian public hospital procurement frameworks. |
| Backward Integration into EVOH Compounding | Reduces Asian petrochemical feedstock exposure and currency mismatch margin volatility. |
| Hospital GPO Strategic Partnership | Captures procurement consolidation benefits as vendor panels narrow from fifteen-to-twenty to three-to-four approved suppliers. |
Research Methodology
Operator-level perspectives from hospital central supply managers, medical device packaging engineers, pharmaceutical regulatory affairs leads, and contract manufacturing procurement directors anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, SEC 10-K disclosures of listed packaging converters, and hospital GPO contract award records. Bottom-up demand modeling triangulated against top-down market sizing across sterilization pouch volumes and retail format adoption.
Sensitivity analysis tested forecast robustness across EVOH resin price volatility scenarios, EU MDR implementation timeline variations, and biodegradable film cost parity assumptions. Segmentation dimensions modeled include product type, material grade tier, application end-use, closure mechanism, and regional regulatory cluster. CAGRs derived from historical trajectory analysis and adoption curve fitting across the projection horizon. Industry-specific inputs incorporated ISO 11607-1 certification pipeline data and hospital sterilization department capital expenditure surveys.
The analysis sits within stated boundaries; outcomes outside sustained EU MDR enforcement intensity, continued EVOH supply concentration, or stable hospital procurement consolidation trends would require recalibration. Forecasts reflect documented assumptions regarding regulatory implementation pacing and feedstock supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Paper Pouch Market
Pouch
Europe Retort Pouches Market
Pouch
Portion Control Packs Market
Pouch
Rice Paper Stand Up Pouch Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Spout Pouch Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Colombia Pouch Packaging Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Automatic Pre-Made Pouch Packaging Machine Market
Pouch
Aluminum Pouches Market
Pouch
Heat Sealed Lamination Pouch Market
Pouch
Feed Pouches Market
Pouch
UAE Pouch Packaging Market
Pouch
OPP Pouches Market
Pouch
2 Seal Pouches Market