
 Utility Pouches Market | 2026-2036
Utility Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Utility Pouches Market Analytics
Specialty retail and direct-to-professional channels is fragmenting as e-commerce platforms and specialized industrial distributors compete for procurement contracts. Petzl leverages its vertical integration in climbing and vertical-access equipment to control premium positioning in European markets. DEWALT anchors its pouch lineup to power-tool ecosystems, sustaining brand loyalty among construction trades. Mystery Ranch differentiates through load-bearing ergonomics developed for military backpack systems.
Utility pouches are fabric-based enclosures, typically constructed from denier-rated nylon or ballistic polyester with reinforced stitching and hardware closures, designed to secure tools, electronics, or personal equipment during mobile work or recreational activity. Zippered pouches lead volume due to universal compatibility with existing bag systems, while clip pouches represent the fastest-expanding category as modular attachment standards proliferate across professional gear. Leather utility pouches command concentrated margin pools in artisan and heritage-positioned segments, though nylon and polyester materials dominate absolute production scale.
REACH compliance in Europe mandates disclosure of Substances of Very High Concern in textile treatments, redirecting coating chemistry toward water-based alternatives. OSHA workplace equipment standards in the United States influence load-rating specifications for professional-grade belt pouches. ISO 9001 quality management certification functions as a baseline market-access filter for contract manufacturers serving branded channels. Stakeholders must monitor evolving modular attachment standards and material traceability requirements as procurement specifications tighten across defense and industrial buyer segments.
Market Dynamics
REACH chemical disclosure mandates are restructuring coating supply chains across European textile manufacturing, forcing solvent-free formulation adoption and supplier consolidation among finish providers.
Growth Catalysts
- Military Modular Standards:NATO STANAG attachment protocols are expanding interoperability requirements for tactical load-bearing equipment across defense procurement channels.
- OSHA Belt-Load Specifications:Updated workplace fall-protection standards are mandating rated attachment points for professional-grade tool pouches in elevated construction work.
- Ballistic Nylon Innovation:Advances in denier-rated weave densities are improving abrasion resistance without weight penalties in industrial safety applications.
Market Restraints
- Petrochemical Feedstock Volatility:Nylon 6,6 resin prices fluctuate with benzene derivative markets, compressing margin predictability for woven fabric suppliers.
- Coating Chemistry Transition Costs:Water-based polyurethane alternatives require retooling of textile finishing lines, creating capital barriers for mid-tier contract manufacturers.
- Hardware Supply Concentration:YKK and ITW dominate global zipper and buckle supply, creating single-source vulnerability for pouch assembly operations.
Strategic Opportunities
- Industrial Safety in Germany:Betriebssicherheitsverordnung workplace equipment inspections are expanding certified pouch requirements in manufacturing and logistics sectors.
- RFID-Enabled Inventory Tracking:Integration of embedded identification chips is enabling tool-crib automation and loss-prevention systems in facility maintenance operations.
- Direct Professional E-Commerce:Specialized industrial distributors are bypassing traditional retail channels to capture recurring procurement contracts from trade contractors.
Industry Challenges
- ISO 9001 Certification Timelines:Branded channel access requires 12-18 month quality management system implementation, delaying market entry for emerging suppliers.
- Modular Attachment Standard Fragmentation:Competing MOLLE, PALS, and proprietary hook-loop systems create SKU proliferation and inventory complexity for multi-platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Utility Pouches Market |
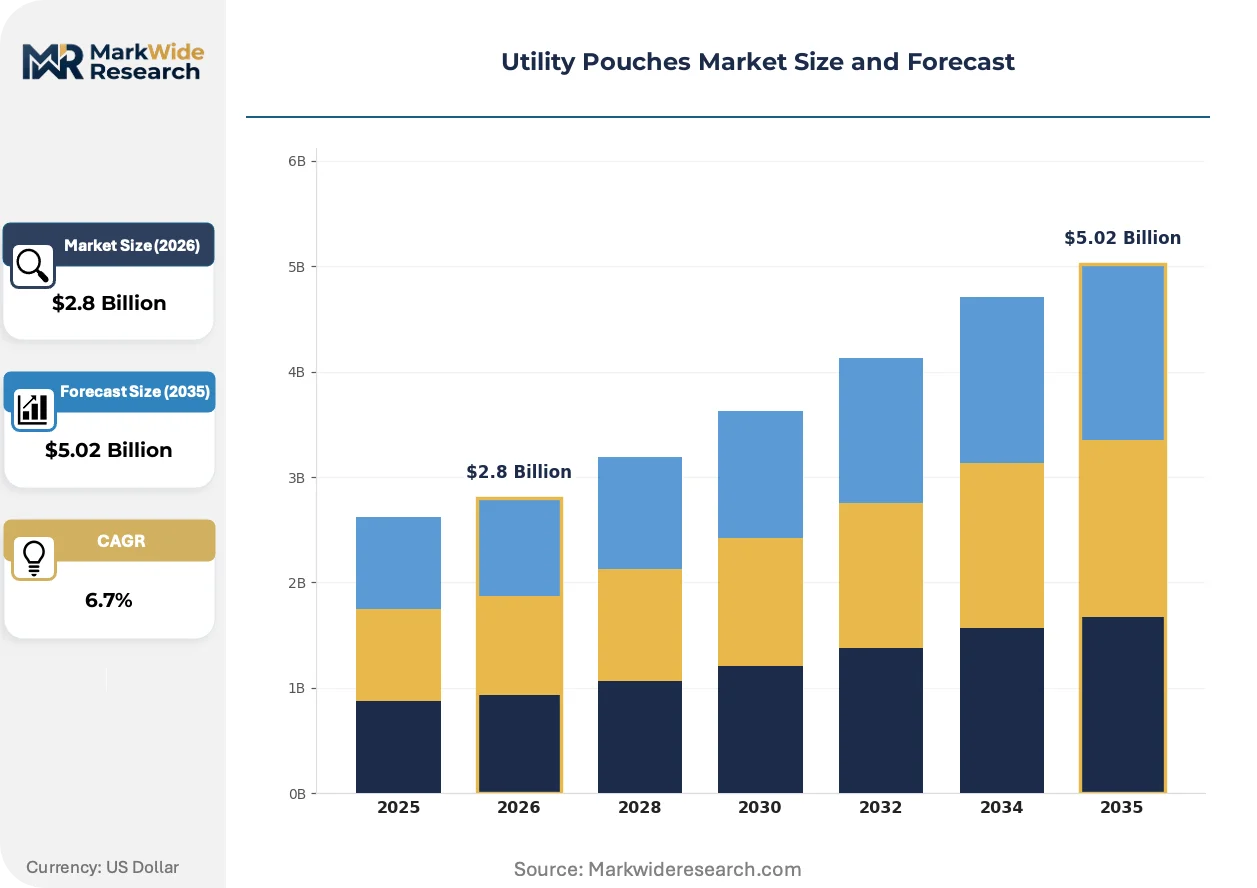
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drawstring Bags, Zippered Pouches, Clip Pouches, Belt Pouches Material: Nylon, Polyester, Canvas, Leather Application: Outdoor Activities, Travel, Storage, Organization End User: Retail Customers, Outdoor Enthusiasts, Professionals, Students |
| Companies Covered | Petzl, DEWALT, 5.11 Tactical, Mystery Ranch, Maxpedition, Condor Outdoor, Greenlee, TUMI, Elite Safety Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Utility Pouches Market Evolving Landscape
Digital identification and solvent-free chemistry are converging to reshape material specification and procurement verification across professional-grade pouch manufacturing.
Embedded RFID tagging is digitizing asset tracking for high-value tool inventories in aviation maintenance and power-generation facilities. MRO departments at Delta Airlines and Siemens Energy are mandating chip-readable pouches for calibrated equipment containment. This technology is digitizing supply chain transparency from fabrication through end-of-life disposal compliance.
REACH Substances of Very High Concern disclosure thresholds are eliminating perfluorinated water-repellent chemistries from European-sourced textiles. ECHA enforcement actions against non-compliant importers are redirecting coating R&D toward bio-based fluorine alternatives. German industrial safety distributors are now requiring full material declaration documentation for catalog inclusion.
Specialized procurement platforms are displacing traditional two-step distribution for trade contractor pouch purchases. Grainger and Fastenal digital storefronts now capture specification-driven bulk orders previously routed through independent safety equipment dealers. This channel migration is most pronounced in North American construction verticals where project-based purchasing favors direct vendor relationships over retail intermediaries.
Utility Pouches Market Segmentation
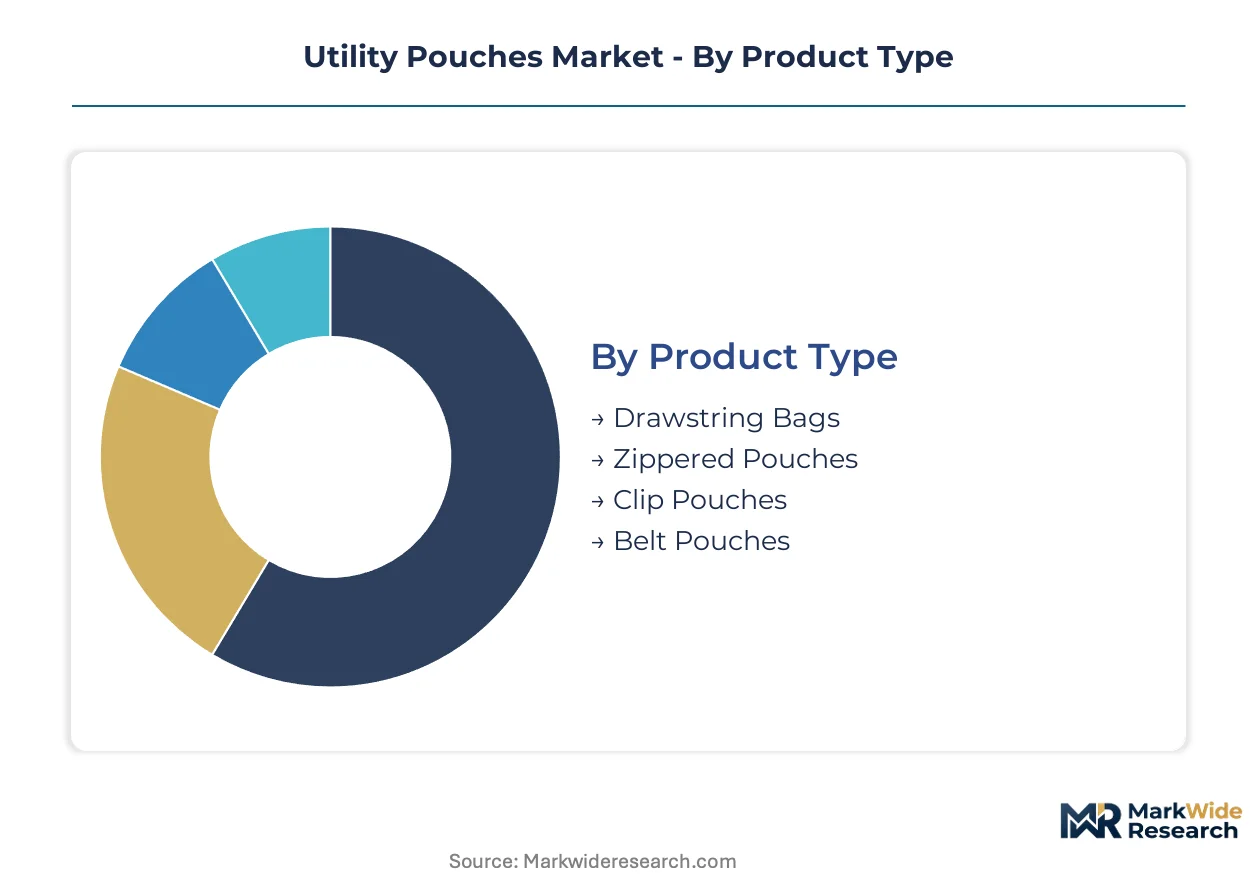
Utility pouch manufacturers configure product lines around attachment mechanics, material durability, and professional certification requirements. Procurement specifications from defense contractors and industrial safety distributors fragment demand across incompatible modular standards and coating chemistries.
Product Type:
Mature closure formats dominate current procurement volumes while emerging attachment systems capture specification-driven replacement cycles.
- Zippered Pouches:These enclosures employ coil or vislon zipper chains with taped seams for dust and moisture exclusion. Demand concentrates in aviation maintenance and power-generation facilities where OSHA mandates tool containment for elevated work; Delta Airlines and Siemens Energy now require chip-readable variants for MRO tracking.
- Clip Pouches:Molded polymer or aluminum gate clips enable rapid attachment to harness systems and bag loops. German industrial safety distributors under Betriebssicherheitsverordnung inspection protocols are expanding certified clip pouch requirements in manufacturing and logistics sectors.
- Drawstring Bags:Cord-lock closures with reinforced eyelets serve bulk storage and recreational applications where rapid access outweighs environmental sealing.
- Belt Pouches:Rated attachment points and load-distribution panels address professional-grade tool carriage for construction trades.
Zippered pouches handle the majority of throughput; clip pouches are the fastest mover on share.
Material:
Cost tier differentiation separates specification-grade synthetics from heritage-positioned natural materials.
- Nylon:Denier-rated ballistic weaves provide abrasion resistance for tactical and industrial applications. REACH Substances of Very High Concern disclosure thresholds are eliminating perfluorinated water-repellent chemistries from European-sourced nylon textiles.
- Polyester:Solution-dyed PET fabrics offer UV stability and solvent-free coating compatibility at lower unit costs than nylon. Water-based polyurethane finishing lines require capital retooling that creates barriers for mid-tier contract manufacturers.
- Canvas:Cotton duck weaves with waxed or oil-treated finishes occupy artisan and heritage market positions.
- Leather:Full-grain and top-grain hides command concentrated margin pools where brand positioning emphasizes durability craftsmanship over synthetic performance metrics.
Nylon absorbs the largest share of professional procurement; polyester is climbing the fastest as coating chemistry transitions accelerate.
Application:
Volume concentrates in mobility-driven use cases while stationary storage applications anchor replacement demand.
- Outdoor Activities:Climbing, hiking, and vertical-access equipment require load-bearing ergonomics and modular attachment compatibility. Petzl leverages in-house production of harness systems to control premium positioning in European markets.
- Travel:Compression and organizational pouches for luggage systems prioritize weight reduction and TSA-accessible closures.
- Storage:Long-term containment applications emphasize archival-grade materials and pest-resistant sealing.
- Organization:Desktop and vehicle interior systems favor compartmentalization and rapid visual identification.
Outdoor activities drive the highest absolute volume; travel applications are expanding most quickly as specialized distributor e-commerce displaces traditional retail channels.
End User:
Customer type stratification separates recurring institutional procurement from discretionary individual purchases.
- Professionals:Trade contractors, military personnel, and industrial maintenance crews require ISO 9001-certified products with rated load specifications. DEWALT anchors pouch lineups to power-tool ecosystems to sustain brand loyalty among construction trades.
- Outdoor Enthusiasts:Climbers, hikers, and recreational users prioritize weight-to-durability ratios and compatibility with existing gear systems. Mystery Ranch differentiates through load-bearing ergonomics developed for military backpack systems.
- Retail Customers:General consumers purchase through mass-market channels with lower specification requirements and price sensitivity.
- Students:Educational supply procurement favors basic organizational pouches with institutional branding and volume pricing.
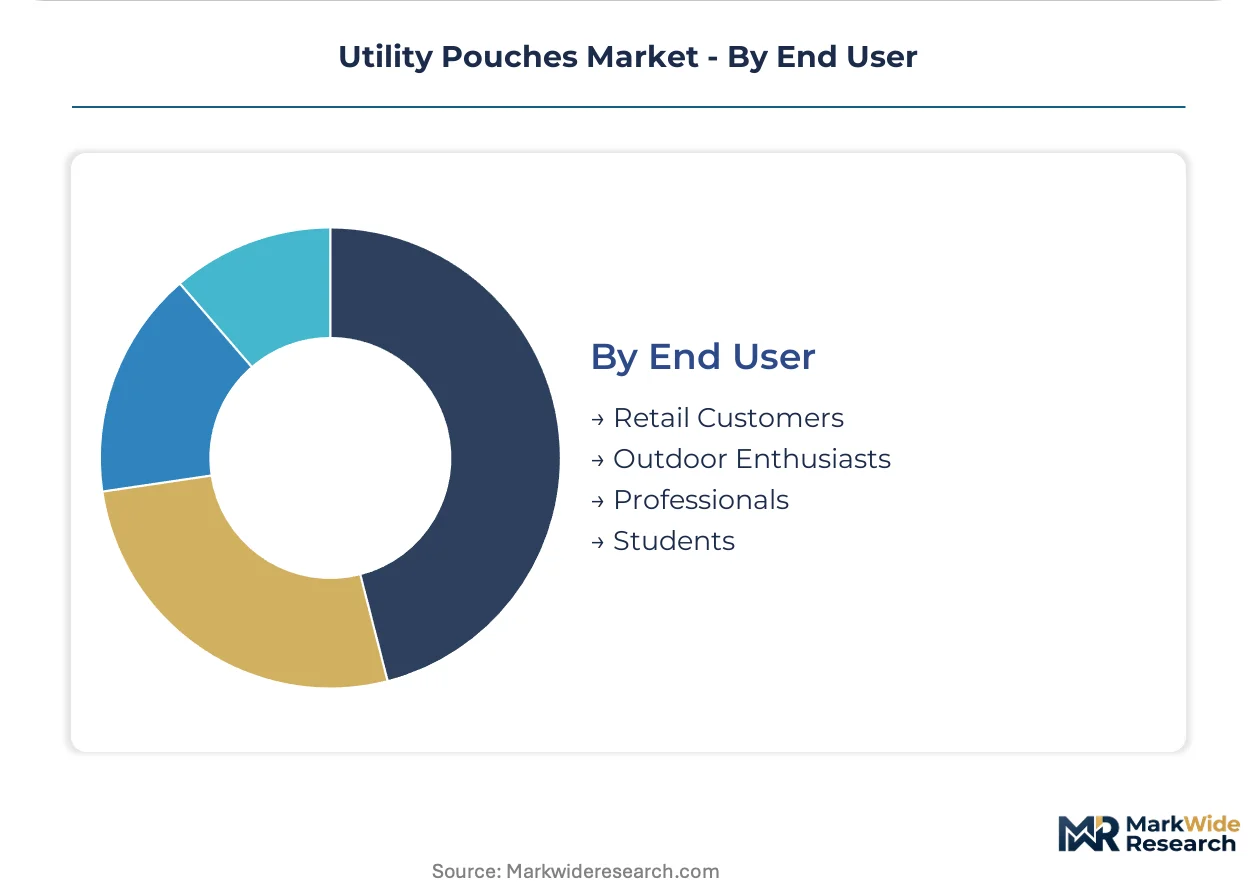
Professionals generate the highest revenue per unit; outdoor enthusiasts are gaining share fastest as direct-to-consumer specialized platforms expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA workplace equipment standards in the United States anchor the regulatory framework shaping professional-grade pouch specifications across major procurement channels. REACH chemical disclosure mandates in Europe are restructuring coating supply chains and redirecting manufacturing investments. Military modular standards from NATO STANAG protocols are expanding interoperability requirements across defense procurement networks.
United States
Construction trades and aviation maintenance crews drive specification-grade demand for rated belt pouches with load-bearing attachment points. OSHA updated fall-protection standards now mandate certified attachment hardware for elevated work environments. Dallas-Fort Worth and Atlanta industrial corridors concentrate distribution infrastructure for trade contractor procurement through specialized e-commerce platforms.
Germany
Betriebssicherheitsverordnung workplace equipment inspections are expanding certified pouch requirements across manufacturing and logistics operations. REACH Substances of Very High Concern disclosure thresholds eliminate perfluorinated chemistries from textile treatments, forcing water-based coating adoption. Stuttgart and Munich industrial safety equipment distributors now require full material declaration documentation for catalog inclusion.
China
Contract manufacturers serving branded channels dominate synthetic fabric production at scale for global export markets. GB standards for textile quality and chemical content create baseline compliance filters for international buyers. Guangdong and Zhejiang province manufacturing clusters concentrate finishing line capacity for denier-rated nylon and ballistic polyester weaves.
Japan
Vertical-access equipment specialists leverage load-bearing ergonomics developed for climbing and industrial rope-access applications. METI industrial safety guidelines influence specification requirements for professional-grade harness-compatible pouches. Tokyo and Osaka metropolitan areas anchor premium positioning for technical outdoor and professional-use segments.
United Kingdom
Heritage-positioned leather craft workshops command concentrated margin pools in artisan market segments. CE marking requirements for personal protective equipment create regulatory alignment with European procurement standards. Birmingham and Manchester manufacturing districts sustain specialized stitching and hardware assembly operations for premium positioning.
Utility Pouches Market Competitive Landscape
Equipment-anchored tool brands and technical outdoor specialists split the market between ecosystem-integrated positioning and modular performance differentiation. The vendor base concentrates around three strategic archetypes: power-tool ecosystem anchors, vertical-access equipment integrators, and tactical load-bearing system developers. Capacity expansion in solvent-free coating lines and strategic partnerships with industrial safety distributors represent the dominant competitive moves reshaping procurement channel access.
Among power-tool ecosystem anchors, DEWALT exemplifies brand loyalty sustainment through hardware compatibility integration. Within the vertical-access tier, Petzl occupies a position reflecting in-house harness system production control. On the tactical load-bearing vector, Mystery Ranch represents ergonomic transfer from military backpack development. These three companies anchor distinct strategic positions without overlapping core competency claims.
| Leading Market Players |
|---|
| Petzl |
| DEWALT |
| 5.11 Tactical |
| Mystery Ranch |
| Maxpedition |
| Condor Outdoor |
| Greenlee |
| TUMI |
| Elite Safety Products |
| Others |
Value Network & Pricing Analysis
Petrochemical feedstock volatility in benzene derivative markets compresses margin predictability for woven fabric suppliers while simultaneously widening spreads between specification-grade and commodity-tier pouch offerings. This input cost instability forces manufacturers to index raw material surcharges into long-term procurement contracts, reshaping how defense and industrial buyers negotiate volume commitments.
Pricing Analysis
Configured-to-order pricing for NATO STANAG-compatible pouches with embedded RFID tracking commands substantial premiums over standard zippered variants stocked through industrial distributors. Three-tier pricing structure across premium, standard, and economy levels separates ISO 9001-certified professional-grade products with rated load specifications from basic organizational pouches sold through mass retail channels. Price differentiation hinges on certification grade and customization level, with military and aviation maintenance buyers exhibiting lowest price sensitivity due to specification mandates. Cost compression in mid-tier polyester pouches is intensifying because water-based coating retooling expenses are being amortized across smaller production runs.
Supply Chain Analysis
Contract manufacturing concentration in Guangdong and Zhejiang provinces anchors global synthetic fabric finishing capacity for denier-rated nylon and ballistic polyester weaves. Raw material sourcing draws from petroleum-based resin suppliers in China, South Korea, and Taiwan, while hardware components rest on YKK zipper and ITW buckle supply from Japan and the United States. Single-source vulnerability in zipper and buckle procurement creates inventory risk for pouch assembly operations during logistics disruptions. Distribution runs through specialized industrial e-commerce platforms including Grainger and Fastenal digital storefronts that displace traditional two-step distribution for trade contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH chemical disclosure mandates are restructuring European textile manufacturing, creating a high-growth disruption as solvent-free coating adoption forces supplier consolidation and opens acquisition opportunities for compliant finish providers.
For Market Incumbents: Entrench specification-grade positioning by securing ISO 9001 certification for additional production lines and locking in multi-year procurement contracts with Delta Airlines and Siemens Energy for RFID-enabled pouch variants. Backward integration into water-based polyurethane coating capacity insulates margin structures from ECHA enforcement actions while denying compliant supply to emerging competitors. For New Entrants and Emerging Players: Pursue white-space opportunities in German industrial safety distribution under Betriebssicherheitsverordnung inspection protocols, where certified clip pouch requirements are expanding fastest among manufacturing and logistics sectors. Target direct-to-professional e-commerce channels with modular attachment systems compatible with existing Petzl harness ecosystems, bypassing traditional retail intermediaries that demand prohibitive slotting fees. For Investors and Strategic Acquirers: REACH Substances of Very High Concern disclosure thresholds reshape the acquisition landscape by rendering non-compliant coating facilities stranded assets while elevating the strategic value of water-based formulation R&D capabilities. Mid-tier contract manufacturers with solvent-free finishing lines and existing German distributor relationships represent priority acquisition targets. Monitor ECHA enforcement action announcements as the critical signal for accelerated supplier consolidation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Solvent-free coating line additions in Guangdong province capture REACH-compliant export demand from European defense contractors. |
| Backward Integration | In-house denier-rated nylon weaving reduces exposure to YKK zipper supply concentration and petrochemical resin volatility. |
| Green Manufacturing Transition | Water-based polyurethane adoption satisfies ECHA disclosure mandates while qualifying for German industrial safety distributor catalogs. |
| Long-term Supply Agreement | Multi-year RFID-enabled pouch contracts with aviation MRO departments lock in recurring revenue and specification-driven replacement cycles. |
| Joint Venture | Partnerships with specialized industrial e-commerce platforms bypass traditional retail channels and capture project-based contractor procurement. |
Research Methodology
Cross-validation between primary interviews with procurement officers at industrial safety distributors and secondary validation through customs trade data anchors the qualitative findings in this study. Plant managers at Guangdong and Zhejiang contract manufacturers, technical R&D directors at coating formulation suppliers, and channel sales heads at specialized e-commerce platforms provided operational perspective. Secondary sources include SEC 10-K filings from publicly traded tool and equipment manufacturers, REACH Substances of Very High Concern disclosure databases maintained by ECHA, and industrial safety equipment import records. Bottom-up production capacity estimates triangulate against top-down procurement volume data from aviation maintenance and power-generation facility operators.
Calibration against historical adoption curves for modular attachment standards and solvent-free coating transitions informs the projection framework across the analysis window. Segmentation dimensions modeled include closure mechanism type, material chemistry tier, professional certification level, and end-use application intensity. CAGRs derive from elasticity-adjusted demand curves incorporating NATO STANAG protocol adoption timelines and OSHA fall-protection standard enforcement phases. RFID integration penetration rates and water-based coating capacity expansion schedules serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in benzene derivative pricing and euro-dollar exchange rates would shift the trajectory for European export competitiveness and raw material sourcing economics. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and defense procurement cycle timing. Quarterly review of ECHA compliance action announcements and NATO equipment standard revision schedules is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
North America Pouch Packaging Market
Pouch
Standcap Pouch Market
Pouch
Sterilization Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market
Pouch
Egypt Pouch Packaging Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Dual-Chamber Pouches Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Pouch Equipment Market
Pouch
Inflatable Pouches Market
Pouch
Poland Pouch Packaging Market
Pouch
Inverted Pouch Market
Pouch
Flexible Plastic Pouches Market
Pouch
Mexico Pouch Packaging Market