
 Pouch-Bowl Packaging Market | 2026-2036
Pouch-Bowl Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Pouch-Bowl Packaging Market Analytics
A capital-intensity divergence between integrated film producers and converters is unwinding competitive stability in flexible food packaging. Amcor leverages captive resin and film extrusion to sustain margin structures that pure-play converters struggle to match. Huhtamaki Group anchors its position through geographic density in emerging-market quick-service restaurant supply chains. ProAmpac differentiates via specialized retort pouch capabilities for shelf-stable prepared meals.
Pouch-bowl packaging denotes flexible-to-semi-rigid containers combining barrier films with thermoformed or injection-molded bases, typically achieving oxygen transmission rates below 0.5 cc/m²/day through coextruded EVOH or metallized layers to preserve product integrity across ambient distribution. The hybrid segment leads value contribution as brands seek format differentiation between pure flexible pouches and rigid bowls. Plastic material configurations still dominate volume, though biodegradable substrate development is accelerating fastest among sustainability-focused European food brands. Food end users command the largest absolute demand pool, while cosmetics applications concentrate margin in premium airless pouch-bowl systems.
FDA food-contact substance notifications govern barrier layer approvals in the United States, while EU REACH and the Packaging and Packaging Waste Regulation impose extended producer responsibility and recyclability design mandates across European markets. Japan's METI has issued voluntary guidelines for mono-material flexible packaging that Japanese converters now treat as de facto compliance benchmarks. Stakeholders must monitor regulatory divergence between single-material mandates in Europe and multi-material performance standards still prevalent in North American retail supply chains.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are forcing converters to redesign multi-material laminates into mono-material or recyclable configurations, compressing legacy barrier film architectures and redistributing competitive advantage toward integrated resin producers with in-house recycling streams.
Growth Catalysts
- Ready-to-eat meal proliferation:Food service operators in Germany and France are standardizing pouch-bowl formats for portion-controlled distribution through centralized retail networks.
- Extended Producer Responsibility frameworks:EU REACH and national implementations in Italy and Spain impose design-for-recycling obligations that reward early format standardization.
- Barrier film coextrusion advances:EVOH and metallized layer integration now achieves sub-0.5 cc/m²/day oxygen transmission without aluminum foil dependence.
Market Restraints
- Resin cost volatility:Ethylene and propylene feedstock fluctuations directly compress converter margins on EVOH and polypropylene barrier substrates.
- Recyclability-performance tradeoff:Mono-material polyethylene structures sacrifice shelf stability versus legacy multi-material laminates, limiting adoption in ambient distribution chains.
- Retort processing limitations:Biodegradable substrates lack thermal resistance above 121°C, excluding them from shelf-stable prepared meal applications.
Strategic Opportunities
- Japanese regulatory alignment:METI voluntary mono-material guidelines create export pathways for European converters achieving compliant barrier structures.
- Cosmetics airless systems:Premium skincare brands in South Korea are adopting pouch-bowl formats for preservative-free dispensing with extended shelf claims.
- Quick-service restaurant supply chain density:Emerging-market QSR expansion in Brazil and Mexico favors standardized pouch-bowl portioning for cold-chain efficiency.
Industry Challenges
- Multi-material separation infrastructure:Existing municipal recycling streams lack capacity to process metallized flexible laminates, creating compliance gaps with EU design mandates.
- Thermoforming-tooling capex cycles:Converters face 18-24 month lead times for custom mold development, constraining format innovation velocity against rigid container alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pouch-Bowl Packaging Market |
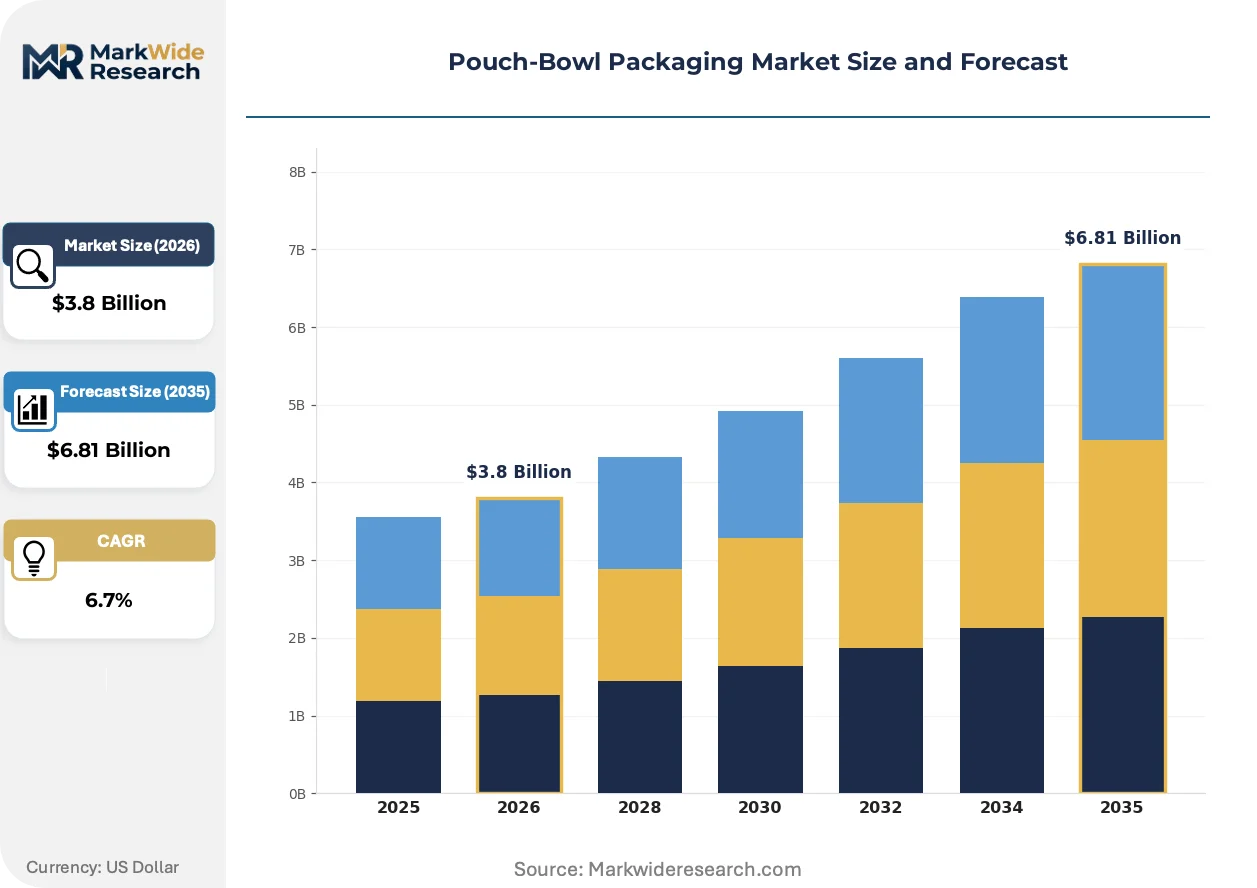
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouch, Bowl, Hybrid, Rigid Material: Plastic, Paper, Aluminum, Biodegradable End User: Food, Beverage, Cosmetics, Healthcare Sales Channel: Online, Retail, Distributors, Wholesalers |
| Companies Covered | Ampac Holding, Kapak Corporation, Cryovac, Exopack, Huhtamaki Group, Bemis Company, Sucat Packaging, ProAmpac, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pouch-Bowl Packaging Market Evolving Landscape
Barrier technology convergence and regulatory design mandates are compressing the viable solution set for flexible food packaging, privileging formats that satisfy both performance specifications and post-consumer recovery requirements without structural compromise.
Mono-material polypropylene barrier structures with vacuum-deposited silicon oxide coatings are displacing metallized polyester laminates in ambient shelf-stable applications. German and Dutch retail chains are specifying these formats for private-label ready meals. The shift is compressing demand for aluminum oxide metallization equipment and redirecting capital toward plasma-enhanced chemical vapor deposition lines.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin adoption in foamed polypropylene tray production for insulated pouch-bowl applications. The industrial consequence is retooling of thermoforming lines across converter networks in Belgium and Poland. Ambient distribution chains for prepared meals are most affected, with brands reformulating around reduced thermal protection requirements.
Centralized procurement by pan-European retail buying groups is consolidating supplier panels and compressing switching costs between converter networks. French and Italian supermarket cooperatives are unbundling format design from manufacturing execution, awarding separate contracts to design studios and toll converters. The shift is most visible in standardized portion-control formats for single-serve prepared proteins.
Pouch-Bowl Packaging Market Segmentation
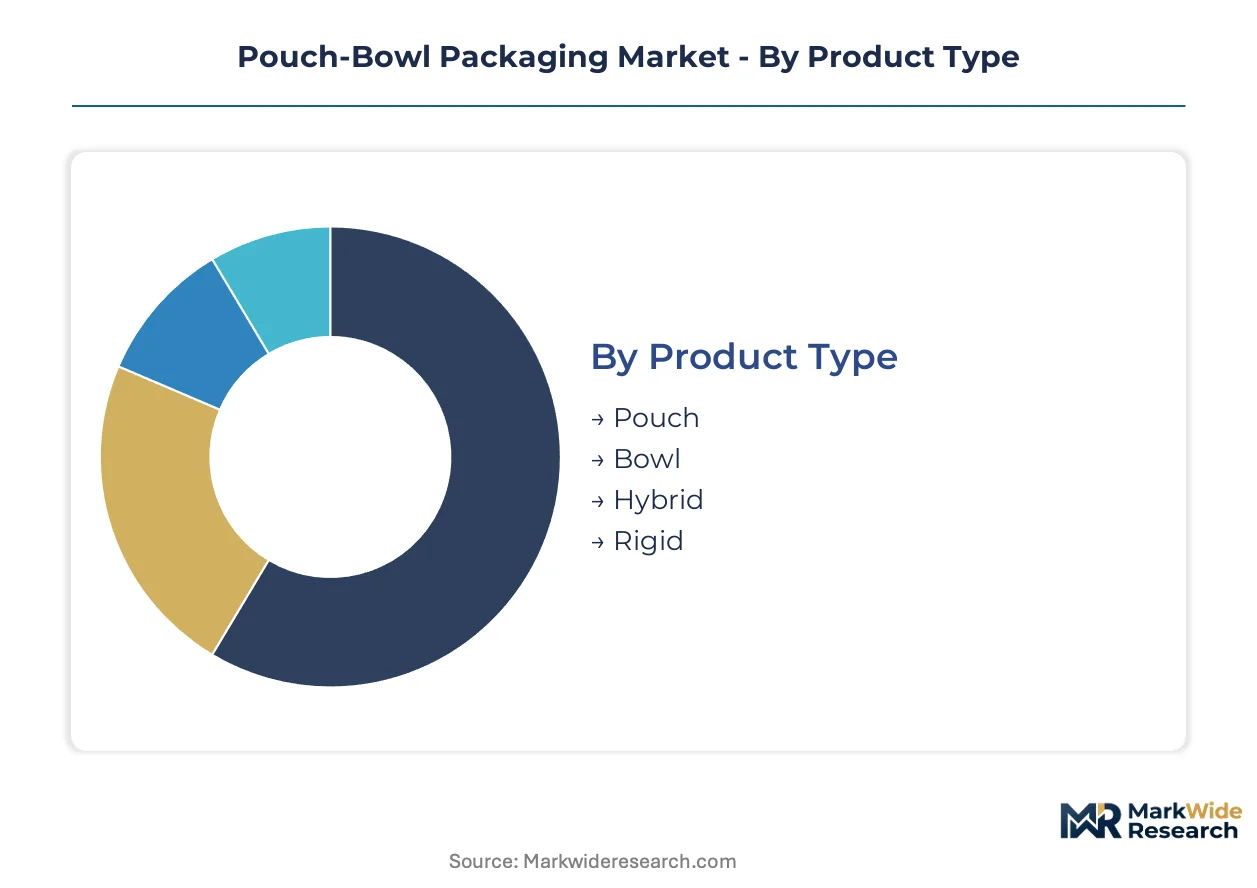
Pouch-bowl packaging segmentation reveals divergent margin structures across format hybridization and material complexity. Each category carries distinct regulatory exposure and capital intensity profiles that reshape supplier competitive positioning.
Product Type:
Margin pools concentrate in hybrid formats that command premium pricing for barrier performance without full rigid container costs.
- Hybrid:Combines flexible film lids with thermoformed or injection-molded bases, achieving sub-0.5 cc/m²/day oxygen transmission through coextruded EVOH or metallized layers. German retail chains specify these for private-label ready meals as they bridge shelf appeal and logistics efficiency.
- Pouch:Pure flexible formats with spouted or fitmented closures dominate ambient distribution for shelf-stable prepared proteins. French supermarket cooperatives are unbundling pouch design from manufacturing execution, compressing converter margins through competitive tolling.
- Bowl:Semi-rigid containers with heat-sealed lidding films serve portion-controlled food service distribution. Demand concentrates in centralized European retail networks where standardization reduces switching costs.
- Rigid:Injection-molded or thermoformed bases with snap-fit or welded closures sacrifice format flexibility for maximum product protection. Cosmetics airless applications in South Korea sustain premium positioning here.
The dominant share belongs to Hybrid, while Pouch is closing the gap fastest.
Material:
Cost tier stratification separates commodity resin converters from specialty substrate developers racing regulatory compliance deadlines.
- Plastic:Polypropylene and polyethylene configurations still dominate absolute volume, with EVOH coextrusion achieving barrier performance without aluminum foil dependence. EU Packaging and Packaging Waste Regulation mandates are forcing redesign into mono-material or recyclable configurations.
- Biodegradable:PLA and starch-based substrates lack thermal resistance above 121°C, excluding them from retort applications. Accelerating development among sustainability-focused European food brands targets cold-chain ready meals instead.
- Aluminum:Metallized films and foil laminates face municipal recycling infrastructure gaps that create compliance vulnerabilities under extended producer responsibility frameworks.
- Paper:Fiber-based barriers with polymer coatings serve limited moisture-sensitive applications where grease resistance outweighs oxygen protection requirements.
Plastic retains volume leadership, though Biodegradable substrates are climbing the fastest as design-for-recycling obligations tighten.
End User:
Application-driven demand concentration creates divergent specification intensity across food service, consumer retail, and premium dispensing systems.
- Food:Ready-to-eat meal proliferation in Germany and France drives standardization for portion-controlled distribution through centralized retail networks. Ambient shelf-stable applications command the largest absolute demand pool.
- Cosmetics:Premium skincare brands in South Korea adopt pouch-bowl formats for preservative-free dispensing with extended shelf claims. Airless systems concentrate margin in this segment through specialized barrier engineering.
- Beverage:Fitmented pouch-bowl formats for concentrates and functional drinks face competition from conventional bottle and carton alternatives in established markets.
- Healthcare:Sterile barrier requirements and validation protocols limit supplier qualification to converters with medical device manufacturing certifications.
Food commands the dominant share, while Cosmetics is gaining share fastest on premium pricing power.
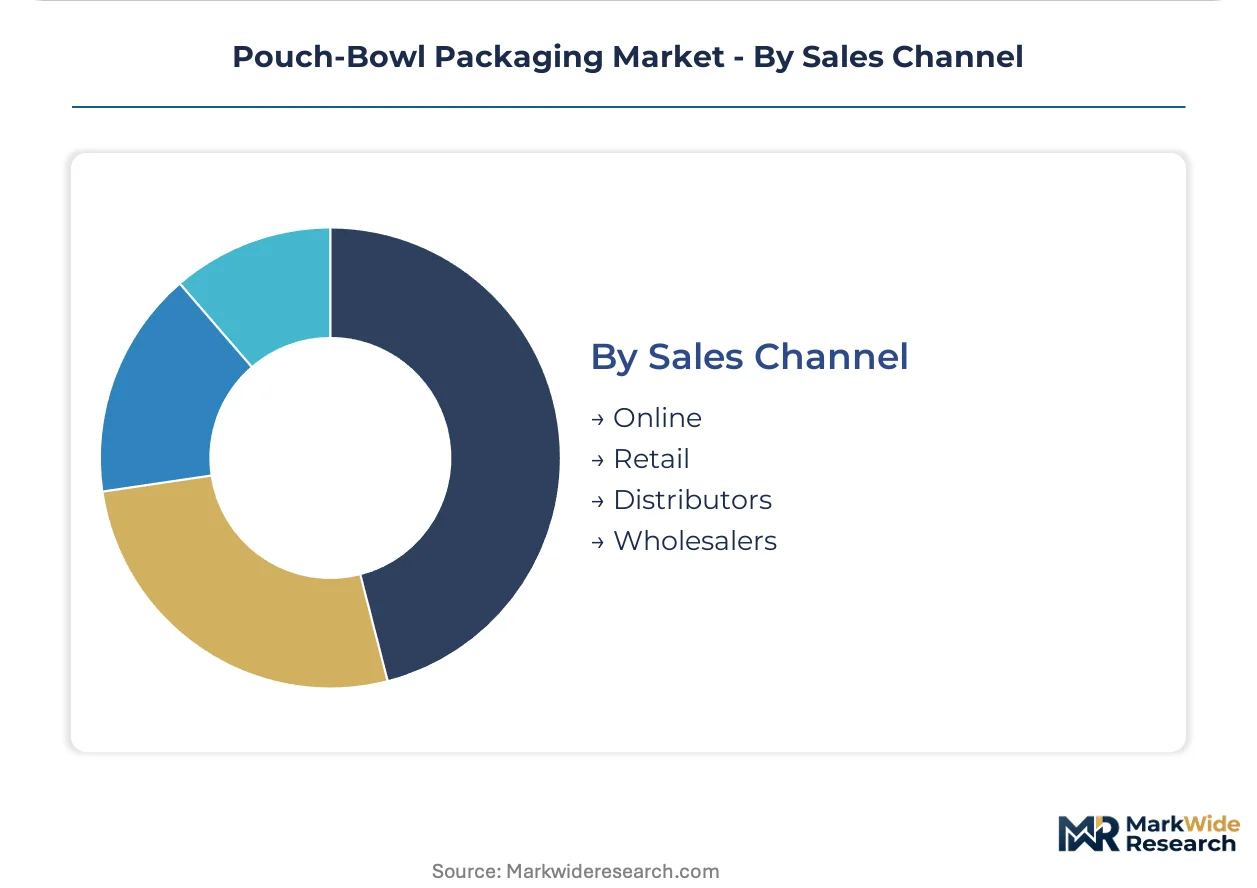
Sales Channel:
Customer type fragmentation separates direct procurement by retail buying groups from fragmented distributor networks serving smaller converters.
- Retail:Pan-European supermarket cooperatives consolidate supplier panels and compress switching costs between converter networks. Centralized procurement unbundles format design from manufacturing execution.
- Distributors:Regional stock-and-resell operations serve mid-tier converters lacking direct resin or film supply relationships. Geographic density in emerging-market QSR supply chains favors this channel in Brazil and Mexico.
- Online:Digital procurement platforms are capturing specification-intensive buyers seeking rapid sample validation and short-run customization.
- Wholesalers:Volume aggregation for commodity pouch-bowl formats serves price-sensitive food service operators with limited technical specification requirements.
Retail holds the dominant share, while Online is expanding most quickly as specification workflows digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity as centralized retail procurement prioritizes format standardization, while converters in Poland face acute margin pressure from resin cost volatility and rapid regulatory compliance deadlines.
Germany
Centralized retail distribution networks in North Rhine-Westphalia and Bavaria drive standardization for portion-controlled ready meals. The EU Packaging and Packaging Waste Regulation imposes strict design-for-recycling obligations that favor mono-material polypropylene structures. Converter clusters around Düsseldorf and Munich are retooling thermoforming lines to meet private-label specifications from pan-European supermarket cooperatives.
France
Supermarket cooperatives in Île-de-France and Auvergne-Rhône-Alpes are unbundling pouch design from manufacturing execution, compressing converter margins through competitive tolling arrangements. REACH compliance deadlines force rapid substrate redesign for ambient shelf-stable applications. Lyon-based converters specialize in retort pouch capabilities for prepared protein distribution through centralized procurement networks.
Japan
METI voluntary mono-material guidelines create export pathways for compliant European converters targeting premium ready-meal segments in Tokyo and Osaka. The Kanto region concentrates demand for barrier-engineered formats in convenience store distribution chains. Japanese converters treat these guidelines as de facto compliance benchmarks, reshaping import qualification protocols for foreign suppliers.
United States
FDA food-contact substance notifications govern barrier layer approvals for flexible-to-semi-rigid containers distributed through Midwest retail networks. Chicago and Minneapolis anchor converter activity for ambient shelf-stable prepared meals. Multi-material performance standards still prevail in North American retail supply chains, creating regulatory divergence with European mono-material mandates.
South Korea
Premium skincare brands in Seoul are adopting pouch-bowl formats for preservative-free dispensing with extended shelf claims. The Seoul Capital Area concentrates demand for airless barrier systems that command margin premiums through specialized engineering. MFDS cosmetic safety regulations shape validation requirements for imported packaging components.
Pouch-Bowl Packaging Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin producers leveraging captive film extrusion to sustain margin structures that pure-play converters struggle to match. The market structure compresses competitive stability as capital-intensity divergence accelerates. Three archetypes dominate: integrated resin-to-film producers, geographic-density specialists in emerging-market QSR supply chains, and retort-capability differentiators for shelf-stable applications. Dominant competitive moves include backward integration into resin supply and geographic expansion through toll manufacturing partnerships.
Among the integrated leaders, Amcor leverages captive resin and film extrusion to anchor the premium tier, while Huhtamaki Group exemplifies geographic-density positioning through emerging-market quick-service restaurant supply chains. ProAmpac occupies a specialized position representing retort pouch capability differentiation for shelf-stable prepared meals. These three companies illustrate how competitive advantage redistributes toward integrated production control and format-specific engineering expertise.
| Leading Market Players |
|---|
| Ampac Holding |
| Kapak Corporation |
| Cryovac |
| Exopack |
| Huhtamaki Group |
| Bemis Company |
| Sucat Packaging |
| ProAmpac |
| Amcor |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German converter clusters around Düsseldorf and Munich shapes both supply concentration and price floors for mono-material polypropylene structures. Scale economies in captive resin extrusion allow integrated producers to defend margin structures that toll-dependent converters cannot match, compressing competitive stability across the European supply base.
Pricing Analysis
After-sales revenue from technical service contracts and format redesign consulting drives lifetime value for converter relationships with pan-European retail buying groups. Three-tier pricing structure across premium, standard, and economy levels stratifies by barrier performance tier and EVOH layer complexity, with German supermarket cooperatives showing lowest price sensitivity due to procurement centralization. Pricing pressure stems from resin cost volatility in ethylene and propylene feedstocks, eroding margins on multi-material laminate redesigns. Small-format food service operators in France exhibit highest price sensitivity as they lack volume scale to negotiate contract-based offtake terms.
Supply Chain Analysis
Germany and Belgium anchor thermoforming line retooling for mono-material polypropylene barrier structures, while Poland hosts emerging converter capacity serving Central European retail networks. Raw material dependencies center on ethylene-vinyl alcohol copolymers, metallized polyester films, and vacuum-deposited silicon oxide coating equipment. Single-source vulnerability in plasma-enhanced chemical vapor deposition line supply creates bottlenecks for converters racing EU Packaging and Packaging Waste Regulation compliance deadlines. Distribution runs through pan-European supermarket cooperative procurement hubs that consolidate supplier panels and compress switching costs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pouch-bowl packaging sits in early-cycle expansion as ready-to-eat meal proliferation in Germany and France accelerates format standardization through centralized retail procurement networks.
For Market Incumbents: Consolidate backward integration into captive resin supply and EVOH coextrusion capacity to defend margin structures against pure-play converter competition. Expand thermoforming tooling partnerships in Poland and Belgium to secure capacity for EU regulatory compliance deadlines. Threat substitution from rigid container alternatives intensifies as mono-material mandates sacrifice shelf stability. For New Entrants and Emerging Players: Lead with biodegradable substrate development for cold-chain ready meals, bypassing retort processing limitations that exclude PLA and starch-based materials from ambient applications. Target South Korean cosmetics airless systems where premium pricing power concentrates margin for specialized barrier engineering. Go-to-market angle: digital procurement platforms for rapid sample validation and short-run customization. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated resin-to-film producers with in-house recycling streams and geographic density in emerging-market QSR supply chains. Long-term viability over a 5-10 year window hinges on regulatory alignment between European mono-material mandates and Japanese METI voluntary guidelines. Signal to watch: Japanese import qualification protocol shifts for compliant European barrier structures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive EVOH extrusion capacity defends margins against feedstock volatility in German converter networks. |
| Mono-Material Format Redesign | EU Packaging and Packaging Waste Regulation compliance unlocks access to pan-European retail procurement panels. |
| Geographic Expansion through Toll Manufacturing | Polish and Belgian tolling partnerships accelerate thermoforming line retooling for private-label ready meals. |
| Specialized Retort Pouch Capability Investment | Shelf-stable prepared protein applications in French supermarket cooperatives sustain premium positioning. |
| Digital Procurement Platform Development | Rapid sample validation workflows capture specification-intensive buyers shifting from distributor networks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across converter networks, resin producers, and retail procurement functions. Primary interviews with thermoforming line operators, barrier film R&D directors, supermarket cooperative category buyers, and quick-service restaurant supply chain managers combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance registrations, METI guideline publications, and customs trade data for EVOH and polypropylene substrates. Bottom-up capacity estimates triangulated against top-down demand modeling from food service operator procurement disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions including format hybridization tier, material complexity grade, end-use application intensity, and regional regulatory cluster. CAGRs were derived from trend extrapolation of adoption curves for mono-material structures and substitution elasticities between flexible and rigid alternatives. Forecast inputs incorporated EU F-Gas Regulation phase-down schedules for foamed polypropylene tray production and centralized procurement consolidation patterns among French and Italian supermarket cooperatives.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or Japanese import qualification alignment would require recalibration. Forecasts reflect documented assumptions about resin cost volatility trajectories and municipal recycling infrastructure development for metallized laminate separation. Recalibration cycles align with material shifts in EU Packaging and Packaging Waste Regulation implementation timelines and METI guideline adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Pouches Market
Pouch
Four Side Flat Pouch Market
Pouch
Inflatable Pouches Market
Pouch
Utility Pouches Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
United States Retort Pouches Market
Pouch
Feminine Care Pouch Film Market
Pouch
Stick Pouches Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Global Pouches Packaging Market
Pouch
Poland Pouch Packaging Market
Pouch
UAE Pouch Packaging Market
Pouch
Box Pouch Market
Pouch
Aluminum Foil Zipper Pouch Market