
 Breathable Bags Market | 2026-2036
Breathable Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Breathable Bags Market Analytics
Asset-light leasing models for extrusion and converting equipment is reconfiguring capital barriers for mid-tier converters entering the breathable films segment. Mondi plc leverages its integrated pulp-to-paperboard network to sustain cost-advantaged supply of fiber-based breathable substrates. Berry Global anchors North American supply through blown film capacity concentrated in the Midwest. Sealed Air differentiates via active packaging technologies that integrate moisture control with breathability.
Breathable bags are engineered films or fabric laminates with controlled porosity, typically achieving moisture vapor transmission rates between 5,000 and 15,000 g/m²/day, designed to balance gas exchange with contamination protection for respiring products. The primary commercial purpose centers on extending post-harvest life of fresh produce and maintaining viability of agricultural inputs through regulated humidity environments. Biodegradable bags now occupy the fastest-expanding margin pool as compostability certifications become mandatory across EU retail channels. Polyethylene still dominates tonnage in industrial and heavy-duty gardening applications where UV resistance and load strength outweigh disposal premiums. Food packaging applications lead value generation, driven by centralized produce distribution networks requiring standardized shelf-life protocols.
The EU Packaging and Packaging Waste Regulation and REACH compliance frameworks are reshaping material substitution timelines, with EFSA migration limits now governing direct food-contact breathable layers. FDA food contact substance notifications govern US market entry for novel coextruded structures, while BIS certification requirements in India are localizing test protocols for imported film substrates. Stakeholders must monitor divergence between regional compostability standards and industrial composting infrastructure availability before committing capital to next-generation biodegradable resin formulations.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is collapsing traditional single-use plastic film supply chains, forcing converters to requalify entire substrate portfolios under EFSA migration limits and industrial compostability standards within compressed timelines.
Growth Catalysts
- EFSA Migration Limits:Direct food-contact breathable layers meeting EFSA thresholds command shelf space in centralized European produce distribution networks, locking in specification-compliant suppliers.
- Supermarket Retrofit Programs:German supermarket chains are retrofitting fresh produce sections with ventilated packaging systems, creating pull-through demand for standardized MVTR-rated films.
- Blown Film Capacity Expansion:Concentrated Midwest extrusion assets in North America are reducing lead times for heavy-duty gardening applications requiring UV-stabilized polyethylene structures.
Market Restraints
- Resin Price Volatility:Polyethylene and biodegradable resin feedstocks face input cost swings tied to naphtha and agricultural commodity markets, compressing converter margins on fixed-price contracts.
- Composting Infrastructure Gaps:Industrial composting facility availability lags behind EU compostability certification mandates, creating stranded asset risk for biodegradable film investments in Eastern European markets.
- Technical MVTR Ceiling:Current coextrusion technologies struggle to push moisture vapor transmission rates consistently above 15,000 g/m²/day without sacrificing puncture resistance in automated packing lines.
Strategic Opportunities
- Indian BIS Localization:BIS certification requirements for imported film substrates are creating captive demand for domestic extrusion and converting capacity serving fresh produce export corridors.
- Active Packaging Convergence:Integration of moisture control chemistries with breathable microperforation is opening specification slots in premium berry and mushroom supply chains.
- Asset-Light Leasing Models:Equipment leasing for extrusion and converting lines is lowering capital barriers for mid-tier converters entering the breathable films segment.
Industry Challenges
- Multilayer Coextrusion Expertise Gap:Qualified process engineers capable of tuning layer ratios for controlled porosity remain concentrated among legacy film producers, constraining new entrant scale-up.
- REACH Registration Timelines:Novel biodegradable additives face 18-24 month ECHA dossier preparation cycles, delaying commercial launch windows relative to product development completion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breathable Bags Market |
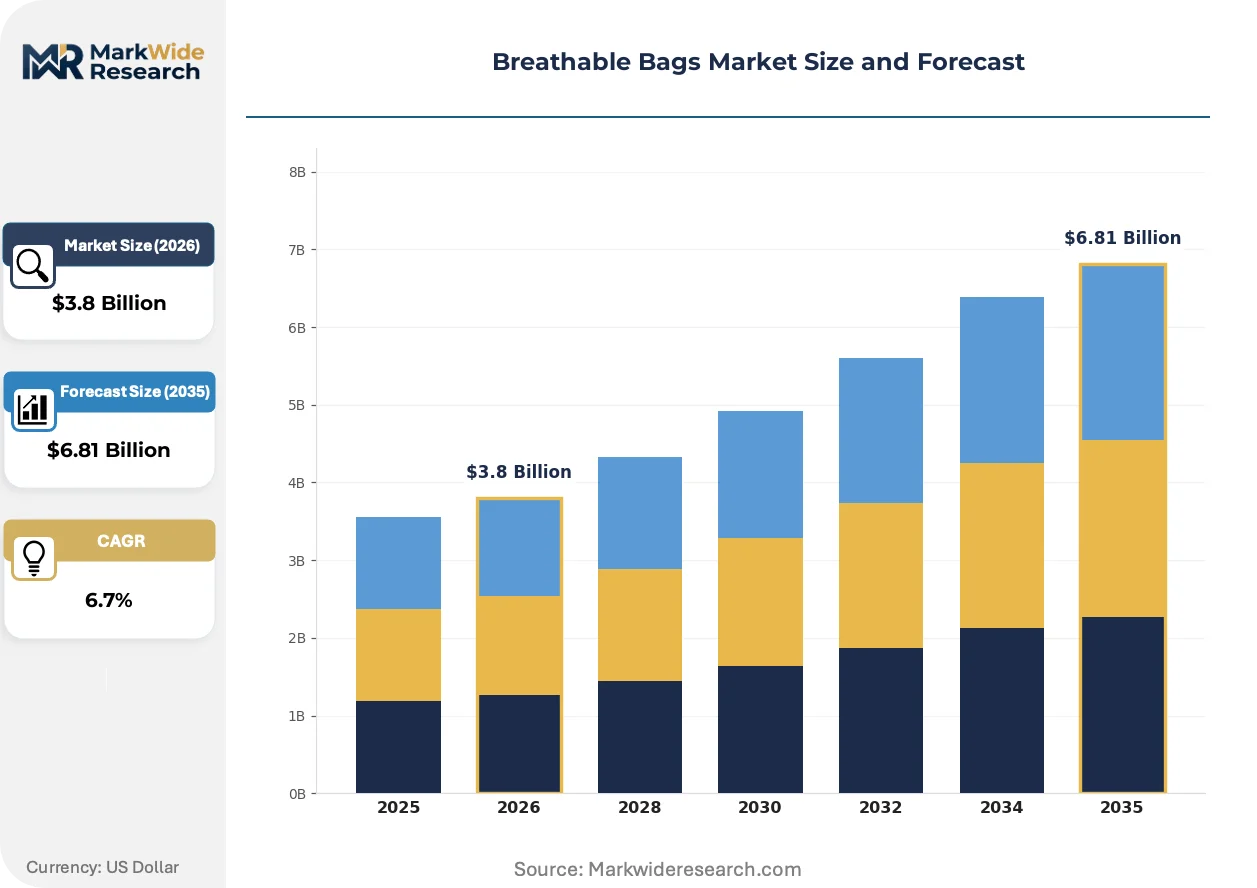
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Bags, Mesh Bags, Woven Bags, Non-Woven Bags Material: Polyethylene, Cotton, Jute, Polyester Application: Food Packaging, Gardening, Retail, Industrial Use End User: Grocers, Farmers, Retailers, Manufacturers |
| Companies Covered | Amcor plc, Huhtamäki Oyj, Mondi plc, DuPont de Nemours, Inc., Printpack, Berry Global, Sealed Air, Smurfit Kappa, PAXXUS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breathable Bags Market Evolving Landscape
Material science advances and regulatory compliance architectures are rewriting specification criteria across fresh produce and agricultural input packaging, with breathability metrics now bundled with compostability claims and active functional layers.
Microperforation laser systems paired with real-time optical gauging are collapsing the defect tolerance thresholds that previously required thicker film gauges to compensate for pinhole variability. Berry packers in California's Central Valley are adopting these systems at line speeds exceeding 400 feet per minute. The technology is collapsing the traditional trade-off between optical clarity and mechanical reliability in high-humidity cold chain environments.
REACH compliance frameworks are mandating full substance disclosure across multilayer film structures, with ECHA SVHC candidate list expansions triggering reformulation cycles for slip agents and anti-fog coatings. Converters serving EU retail channels must now maintain substance volume tracking from resin pellet through finished bag. Fresh herb packaging lines in the Netherlands and Belgium face the most acute compliance pressure due to direct food-contact surface area ratios.
Centralized produce distribution networks are consolidating supplier qualification lists around integrated shelf-life protocol providers, displacing fragmented regional bag converters. Retail procurement teams in Germany and France now specify MVTR ranges, compostability certification, and traceability documentation as bundled requirements. This concentration is most visible in pre-cut salad and ready-to-eat vegetable segments where shelf-life variance directly impacts markdown rates.
Breathable Bags Market Segmentation
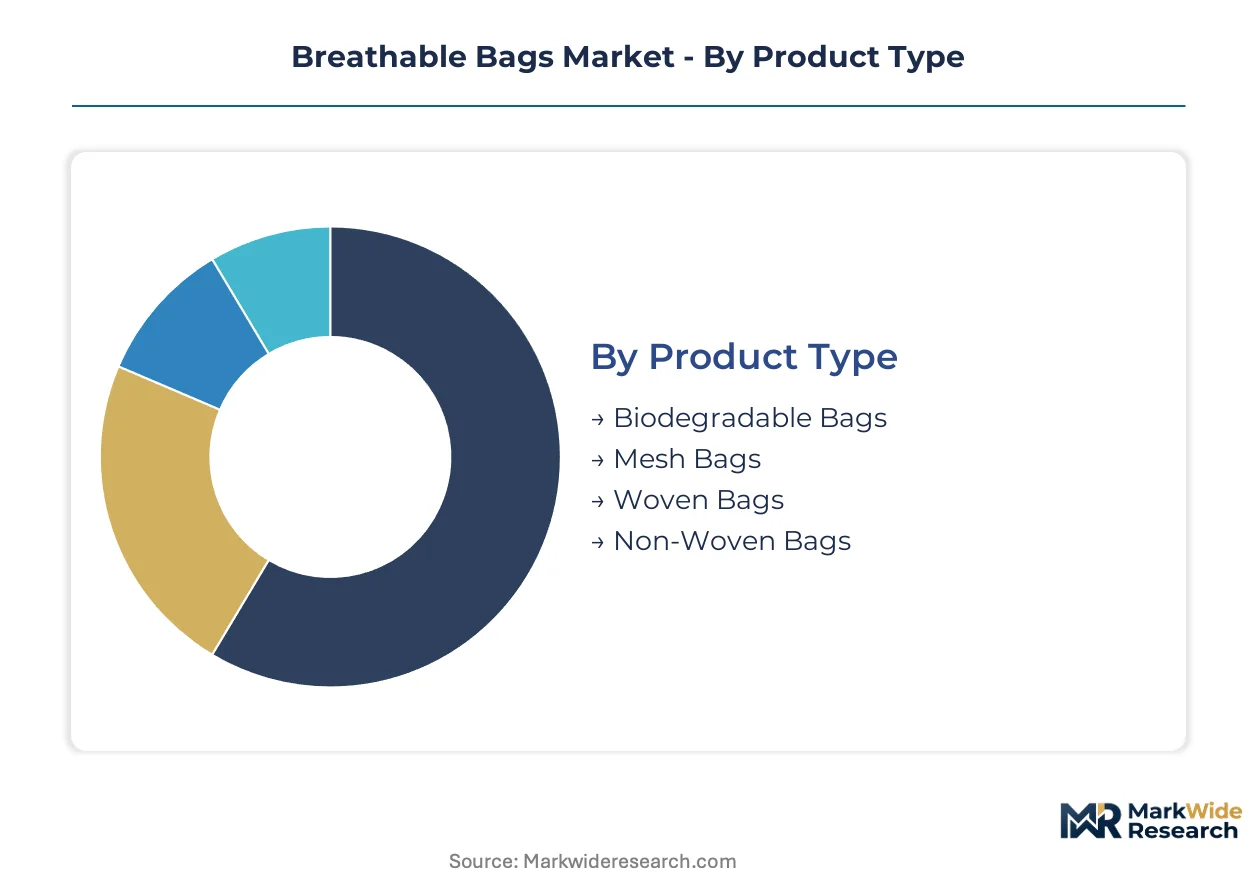
Breathable bag specifications diverge sharply across use cases, with MVTR requirements, compostability mandates, and load-bearing needs forcing distinct formulation strategies. Segmentation clarity enables converters to align extrusion assets with margin pools rather than commoditized volume.
Product Type:
Cost tier stratification separates premium certified compostables from commodity polyethylene alternatives, with equipment intensity and resin pricing driving margin architecture.
- Biodegradable Bags:PLA and PBAT blends with industrial compostability certification per EN 13432 dominate EU fresh produce aisles. German supermarket chains mandate these specifications for pre-cut salad and herb packaging to comply with single-use plastic reduction targets.
- Mesh Bags:Extruded polyethylene netting with 5-15mm aperture control provides ventilation for root vegetables and citrus in automated packing lines. California Central Valley berry packers favor laser-perforated mesh for hydro-cooled strawberry distribution.
- Woven Bags:Circular looms produce polypropylene tape fabric for 25-50kg agricultural input loads requiring UV stabilization and tear resistance.
- Non-Woven Bags:Spunbond polypropylene with thermal point bonding serves lightweight retail produce with printed branding surfaces.
Mesh bags command the established base. The steepest expansion runs through biodegradable bags.
Material:
Application heat maps reveal where resin selection trades off mechanical performance against end-of-life compliance requirements.
- Polyethylene:Linear low-density and metallocene grades deliver 5,000-15,000 g/m²/day MVTR tunability through coextrusion. Midwest blown film capacity serves North American heavy-duty gardening applications where UV resistance outweighs disposal premiums.
- Cotton:Natural fiber woven substrates with 200-400 GSM weight specifications appeal to organic produce branding in French and Italian retail channels.
- Jute:Bast fiber construction provides 50kg load capacity for coffee and cocoa bean export packaging from Indian and Bangladeshi origins.
- Polyester:PET monofilament weaving creates rigid mesh structures for industrial filtration and agricultural drying applications.
Polyethylene anchors volume leadership. Cotton gains share fastest in premium retail positioning.
Application:
Customer type concentration shapes specification bundling, with centralized procurement teams demanding integrated shelf-life protocols versus fragmented spot purchasing.
- Food Packaging:MVTR-rated films with active moisture control layers extend post-harvest life for centralized distribution networks. Dutch fresh herb packers face acute EFSA compliance pressure due to high food-contact surface area ratios.
- Gardening:UV-stabilized polyethylene withstands 12-18 month outdoor exposure for soil and mulch containment in North American home improvement retail.
- Retail:Printed non-woven and cotton bags serve branded produce merchandising with shorter use cycles.
- Industrial Use:Heavy-duty woven construction handles mineral and chemical bulk transport where breathability prevents condensation damage.
Food packaging dominates value capture. Gardening provides the most stable volume base.
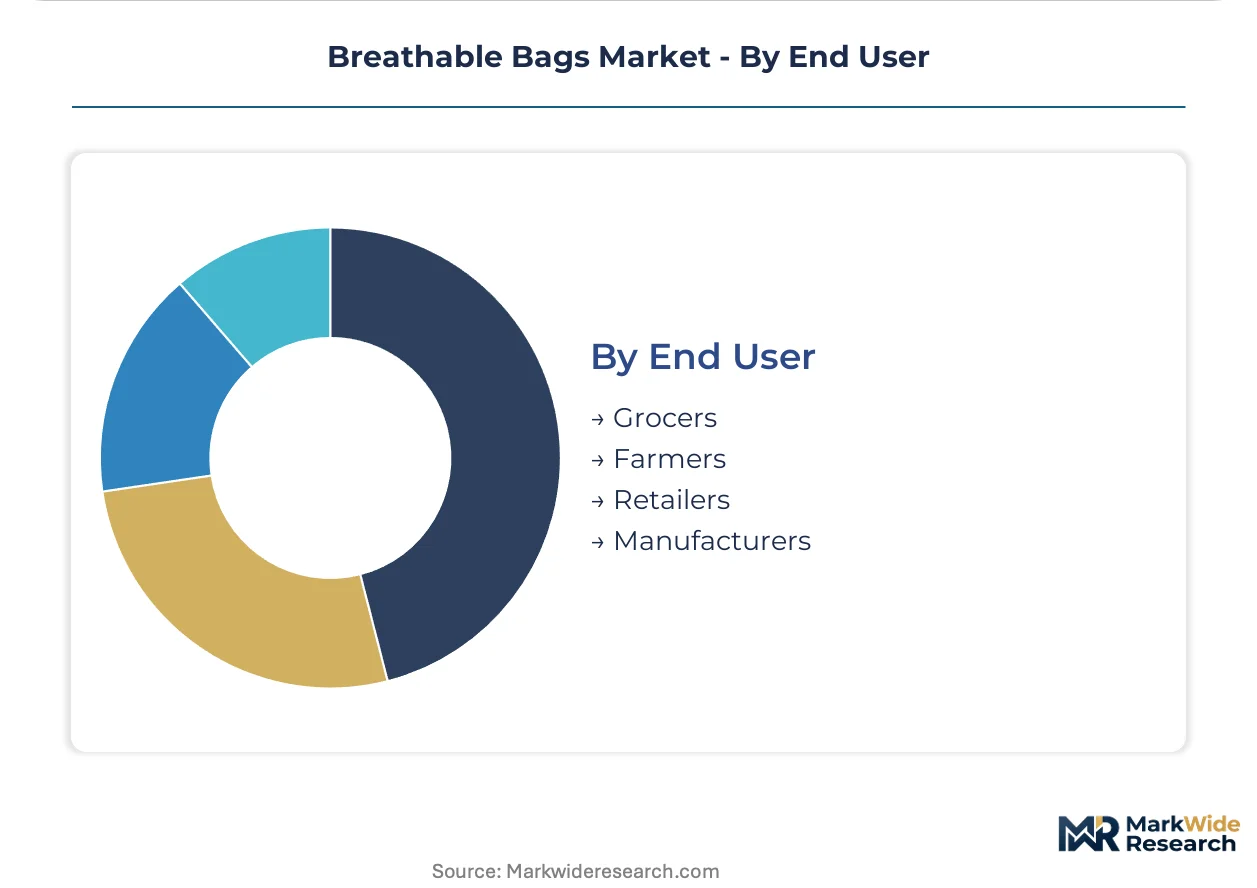
End User:
Volume scale and specification sophistication separate enterprise procurement from fragmented agricultural purchasing patterns.
- Grocers:German supermarket chains retrofit produce sections with ventilated packaging systems, creating pull-through demand for standardized MVTR-rated films bundled with compostability certification.
- Farmers:Direct field packing operations prioritize unit cost over specification complexity, favoring mesh and woven formats for bulk harvest handling.
- Retailers:Mid-tier chains balance branded presentation with logistics standardization across distributed store networks.
- Manufacturers:Industrial processors specify custom dimensions and load ratings for automated filling equipment integration.
Grocers drive specification convergence. Farmers represent the deepest volume pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Packaging and Packaging Waste Regulation mandates are accelerating substrate requalification timelines across major economies. Germany's supermarket retrofit programs and India's BIS localization requirements are reshaping regional supply chain configurations.
Germany
Supermarket chains in Bavaria and North Rhine-Westphalia are retrofitting fresh produce sections with ventilated packaging systems. EFSA migration limits govern direct food-contact breathable layers, locking in specification-compliant suppliers. The Rhine-Main cluster around Frankfurt anchors converter capacity serving centralized European distribution networks.
United States
California Central Valley berry packers are adopting laser-perforated mesh systems at line speeds exceeding 400 feet per minute. FDA food contact substance notifications govern market entry for novel coextruded structures. Midwest blown film capacity in Illinois and Ohio reduces lead times for heavy-duty gardening applications requiring UV stabilization.
India
BIS certification requirements for imported film substrates are localizing test protocols and creating captive demand for domestic extrusion capacity. Maharashtra and Gujarat house fresh produce export corridors driving specification convergence. The Delhi-NCR region concentrates converter operations serving agricultural input packaging for Punjab and Haryana farming belts.
Netherlands
Fresh herb packaging lines in the Randstad face acute REACH compliance pressure due to high food-contact surface area ratios. ECHA SVHC candidate list expansions trigger reformulation cycles for slip agents and anti-fog coatings. The Eindhoven region hosts optical gauging technology providers supplying microperforation laser systems.
China
Yangtze River Delta converters are scaling biodegradable resin formulations to meet EU compostability certification requirements for export-bound fresh produce packaging. GB standards and SAMR regulations govern domestic food-contact film specifications. The Pearl River Delta concentrates woven bag capacity serving agricultural commodity export markets.
Breathable Bags Market Competitive Landscape
Channel-controlling players compete with product-specialist players across specification tiers. The vendor base clusters around three strategic archetypes: integrated pulp-to-film conglomerates with captive fiber supply, Midwest-anchored blown film specialists with UV stabilization expertise, and active packaging innovators integrating moisture control chemistries. Dominant competitive moves include asset-light equipment leasing partnerships and multilayer coextrusion technology licensing.
Within the integrated substrate tier, Mondi plc and Smurfit Kappa occupy positions leveraging fiber-based supply networks. Among North American film specialists, Berry Global anchors blown film capacity concentration. At the active packaging convergence point, Sealed Air exemplifies integration of moisture control with breathable microperforation architectures.
| Leading Market Players |
|---|
| Amcor plc |
| Huhtamäki Oyj |
| Mondi plc |
| DuPont de Nemours, Inc. |
| Printpack |
| Berry Global |
| Sealed Air |
| Smurfit Kappa |
| PAXXUS |
| Others |
Value Network & Pricing Analysis
Midwest blown film overcapacity in Illinois and Ohio is compressing converter margins while simultaneously extending payment terms to resin distributors, forcing suppliers to absorb working capital strain in exchange for volume commitments from centralized produce buyers.
Pricing Analysis
Certification level creates the primary spread, with EN 13432 compostability and EFSA migration compliance adding substantial premiums over commodity polyethylene grades. Three-tier pricing structure separates certified biodegradable films from standard MVTR-rated polyethylene and uncoated mesh alternatives. Pricing pressure stems from naphtha-linked resin volatility that converters cannot fully pass through on annual produce supply contracts. Farmers and direct field packers exhibit the highest price sensitivity, while German supermarket procurement teams prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for converters supplying EU retail channels, stretching balance sheets for mid-tier extrusion operations. Raw material sourcing draws from Saudi Arabian and US Gulf Coast polyethylene supply, Chinese spunbond polypropylene capacity, and Thai PLA resin production. Single-source vulnerability concentrates in laser-perforation equipment and optical gauging systems sourced from Dutch and German technology providers. Distribution runs through centralized produce distribution networks in Germany and the Netherlands, with secondary channels serving fragmented agricultural input markets in India and the American Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breathable bags market represents a high-growth disruption driven by EU Packaging and Packaging Waste Regulation mandates collapsing single-use plastic supply chains and forcing substrate requalification at scale.
For Market Incumbents: Pre-empt specification consolidation by locking in multiyear retrofit contracts with German supermarket chains before biodegradable capacity floods the market. Secure backward integration into PLA and PBAT resin supply through offtake agreements with Thai and European biopolymer producers. Anchor Midwest blown film assets with UV stabilization expertise against commodity import pressure. For New Entrants and Emerging Players: Build out microperforation-as-a-service offerings for California Central Valley berry packers seeking to upgrade legacy mesh lines without capital outlay. Target Indian fresh produce export corridors where BIS certification requirements are localizing demand for domestic extrusion capacity. Lead with laser-perforation technology licensing rather than asset-heavy manufacturing scale-up. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier converters with established EFSA-compliant film portfolios and underutilized extrusion assets in the Rhine-Main cluster. The long-term viability window favors players capable of bridging industrial compostability certification with active packaging functional layers. Monitor divergence between EU compostability mandates and actual industrial composting facility buildout as the critical inflection signal for biodegradable film asset valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Resin | Captive PLA/PBAT supply locks in margin capture as EU compostability mandates harden. |
| Microperforation Technology Licensing | Dutch optical gauging providers extend reach without capital-intensive manufacturing scale-up. |
| EFSA Compliance Certification Investment | Migration limit documentation becomes table stakes for German supermarket supplier qualification. |
| Asset-Light Equipment Leasing Partnerships | Mid-tier converters enter breathable films segment without balance sheet strain. |
| Active Packaging Convergence R&D | Moisture control chemistry integration opens premium berry and mushroom supply chain slots. |
Research Methodology
Desk research of trade association filings, customs records, and ECHA substance databases preceded structured interviews with blown film plant managers, supermarket produce category buyers, regulatory affairs leads at packaging converters, and agricultural input distributors. Primary fieldwork across the Rhine-Main cluster, California Central Valley, and Maharashtra export corridors was cross-checked against secondary data from EU Packaging and Packaging Waste Regulation implementation reports, FDA food contact substance notifications, and BIS certification requirement circulars. Bottom-up capacity estimates and top-down demand segmentation were triangulated to anchor volume and value outputs.
The analytical framework held regulatory implementation timelines and resin price volatility assumptions constant across the projection horizon, varying only penetration rates by application segment. Segmentation dimensions modeled include product type tier, material resin family, end-use application, and geographic regulatory cluster. CAGRs were derived from fitted trend extrapolation validated against converter capacity expansion announcements and supermarket retrofit program disclosures. Industry-specific forecast inputs incorporated MVTR specification convergence trends and compostability certification adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese Yangtze River Delta converters or unexpected EFSA migration limit tightening would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Counter Bags Market
Bags and Containers
Global PP Jumbo Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Vacuum Sealer Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Liner Bags Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Hanging Bags Market
Bags and Containers
Side Weld Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Middle East & Africa Paper Bags Market
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
FIBC Market