
 Heat Sealed Lamination Pouch Market | 2026-2036
Heat Sealed Lamination Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Sealed Lamination Pouch Market Analytics
Food-grade barrier specifications is unwinding commodity-grade oversupply as buyers prioritize oxygen transmission rates below 0.1 cc/m²/day. Fellowes leverages thermal-lamination R&D intensity to command premium office-segment positioning. Amcor anchors pharmaceutical pouch volumes through in-house extrusion of multilayer coextruded films. USI specializes in narrow-format pouch equipment that serves contract packaging houses across North America.
Heat sealed lamination pouches are multilayer flexible structures bonded through thermal pressure activation of adhesive or coextruded sealant layers, typically achieving peel strengths of 3-8 N/15mm for hermetic closure in moisture-sensitive applications. Their primary purpose is to extend shelf stability of oxygen- and moisture-degradable contents through engineered barrier performance. Stand-up pouches capture the largest value pool in food and beverage branding applications where shelf presence drives procurement decisions. Retort pouches represent the fastest-expanding material segment as ready-meal processors convert from metal cans to lightweight flexible formats capable of withstanding 121°C sterilization cycles. Aluminum foil laminations retain margin concentration in pharmaceutical cold-chain packaging where light and thermal protection justify premium pricing.
FDA 21 CFR Part 177 compliance governs food-contact layer composition in US-bound pouch shipments, while EU REACH Annex XVII restrictions on phthalate plasticizers reshape sealant formulation strategies for European exports. India's BIS certification for food packaging materials creates non-tariff entry barriers that favor domestic laminate converters with established testing relationships. Stakeholders must monitor evolving extended producer responsibility frameworks in the EU and state-level plastic-content thresholds in California and New York to anticipate reformulation investments and regional sourcing reallocations.
Market Dynamics
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are compressing procurement timelines and forcing laminate converters to retool for tamper-evident formats with integrated track-and-trace compatibility.
Growth Catalysts
- EU Falsified Medicines Directive:Mandates for unit-level serialization accelerate demand for tamper-evident pouch formats with integrated verification features across European pharmaceutical distribution.
- Retort pouch conversion:Ready-meal processors abandon metal cans for lightweight flexible formats capable of withstanding 121°C sterilization cycles, expanding addressable food packaging volume.
- Germany's industrial packaging corridor:Concentrated converter capacity and proximity to pharmaceutical OEMs create efficient supply clustering for high-barrier laminate demand.
Market Restraints
- Aluminum foil supply concentration:Dependence on limited primary smelter capacity creates input cost volatility and margin compression for cold-chain pharmaceutical laminates.
- REACH Annex XVII phthalate restrictions:ECHA limitations on plasticizer chemistry force sealant reformulation, extending qualification timelines for European export shipments.
- Polymer grade scarcity:Food-grade barrier resin availability lags commodity-grade oversupply, constraining oxygen transmission rate compliance below 0.1 cc/m²/day.
Strategic Opportunities
- India's pharmaceutical export zones:BIS certification barriers favor domestic converters with established testing relationships, creating captive supply advantages for EU and US-bound shipments.
- Extended producer responsibility frameworks:EU packaging waste directives incentivize mono-material recyclable laminates, rewarding early movers in polyethylene-compatible barrier design.
- California and New York plastic-content thresholds:State-level mandates drive reformulation investment toward bio-based sealants, opening premium positioning for compliant regional suppliers.
Industry Challenges
- Multilayer coextrusion technician scarcity:Specialized extrusion operators capable of 5+ layer tolerance control command wage premiums, constraining capacity expansion at mid-tier converters.
- FDA 21 CFR Part 177 compliance timelines:Food-contact layer qualification cycles extend 18-24 months, freezing formulation changes until regulatory clearance.
- Legacy thermal-lamination equipment integration:Narrow-format pouch houses face capex burdens retooling for serialization-ready formats with inline printing and verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Sealed Lamination Pouch Market |
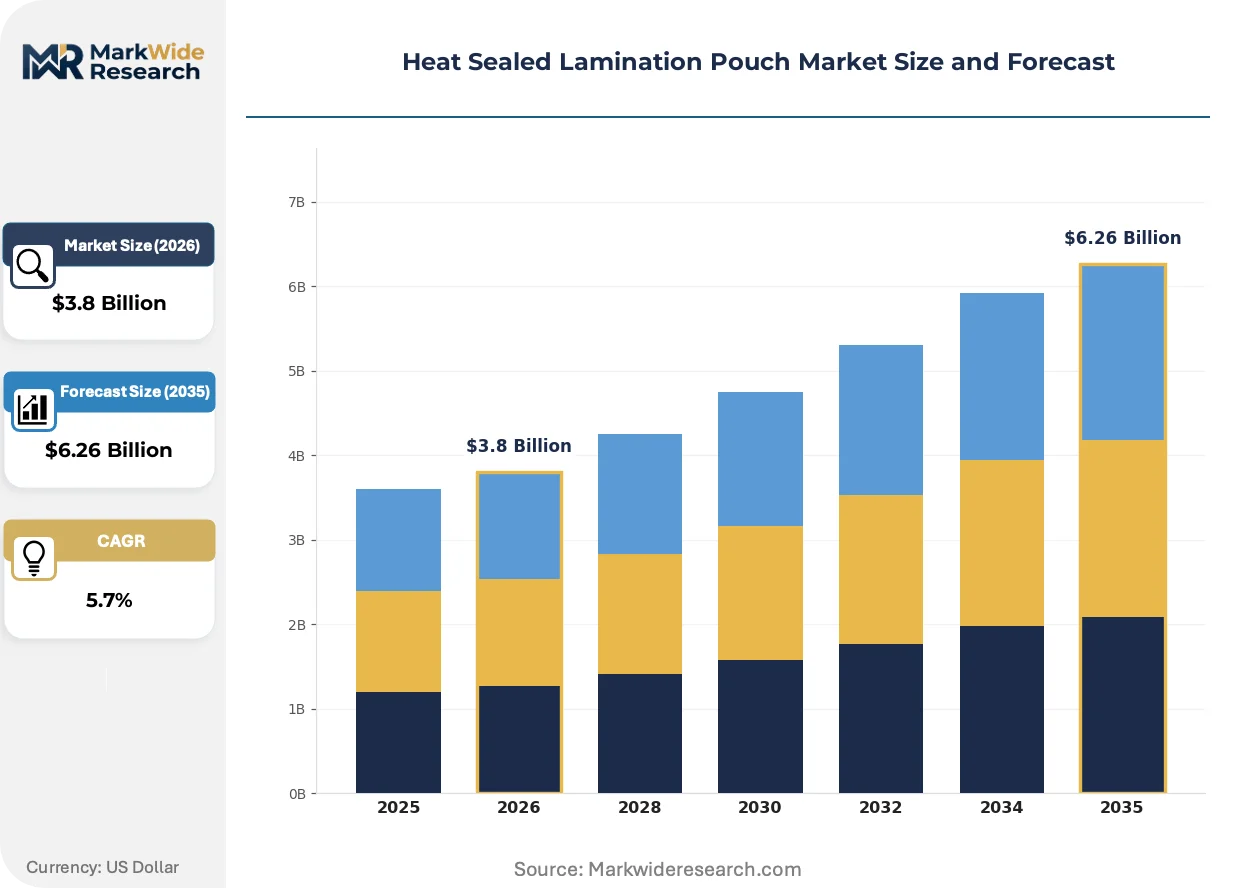
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zip Lock Pouches, Retort Pouches Material: PET, BOPP, Aluminum Foil, PE End User: Food & Beverage, Personal Care, Pharmaceuticals, Electronics Application: Packaging, Storage, Shipping, Branding |
| Companies Covered | Fellowes, ACCO Brands, USI, 3M, GBC, Royal Sovereign, Amcor, Fuji Seal International, Bobst Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Sealed Lamination Pouch Market Evolving Landscape
Barrier engineering and regulatory compliance are converging to reshape material specifications, with oxygen transmission rate thresholds becoming the decisive procurement filter across pharmaceutical and food-grade segments.
High-barrier ethylene vinyl alcohol coextrusions are displacing conventional metallized polyester in pharmaceutical cold-chain applications, achieving equivalent moisture and oxygen protection at reduced aluminum dependency. Vaccine distributors in Germany and Switzerland are specifying these laminates for temperature-sensitive biologics. The shift is compressing demand for foil-heavy structures while rewarding converters with in-house multilayer extrusion capability.
EU REACH Annex XVII restrictions on phthalate plasticizers are forcing sealant chemistry redesigns for European-bound pharmaceutical pouches. ECHA compliance deadlines have triggered reformulation sprints among adhesive suppliers, with migration-tested alternatives now qualifying for food-contact and medical-device overlapping applications. German laminate converters with established ECHA notification relationships are securing preferred-supplier status during this transition.
Serialization-ready pouch procurement is consolidating buyer relationships around converters with integrated track-and-trace printing. Pharmaceutical contract packagers in India and Germany are awarding multi-year agreements to suppliers offering inline variable-data printing and aggregation capability. This behavioral shift favors capital-intensive players over equipment-light trading houses, restructuring competitive positioning toward integrated manufacturing.
Heat Sealed Lamination Pouch Market Segmentation
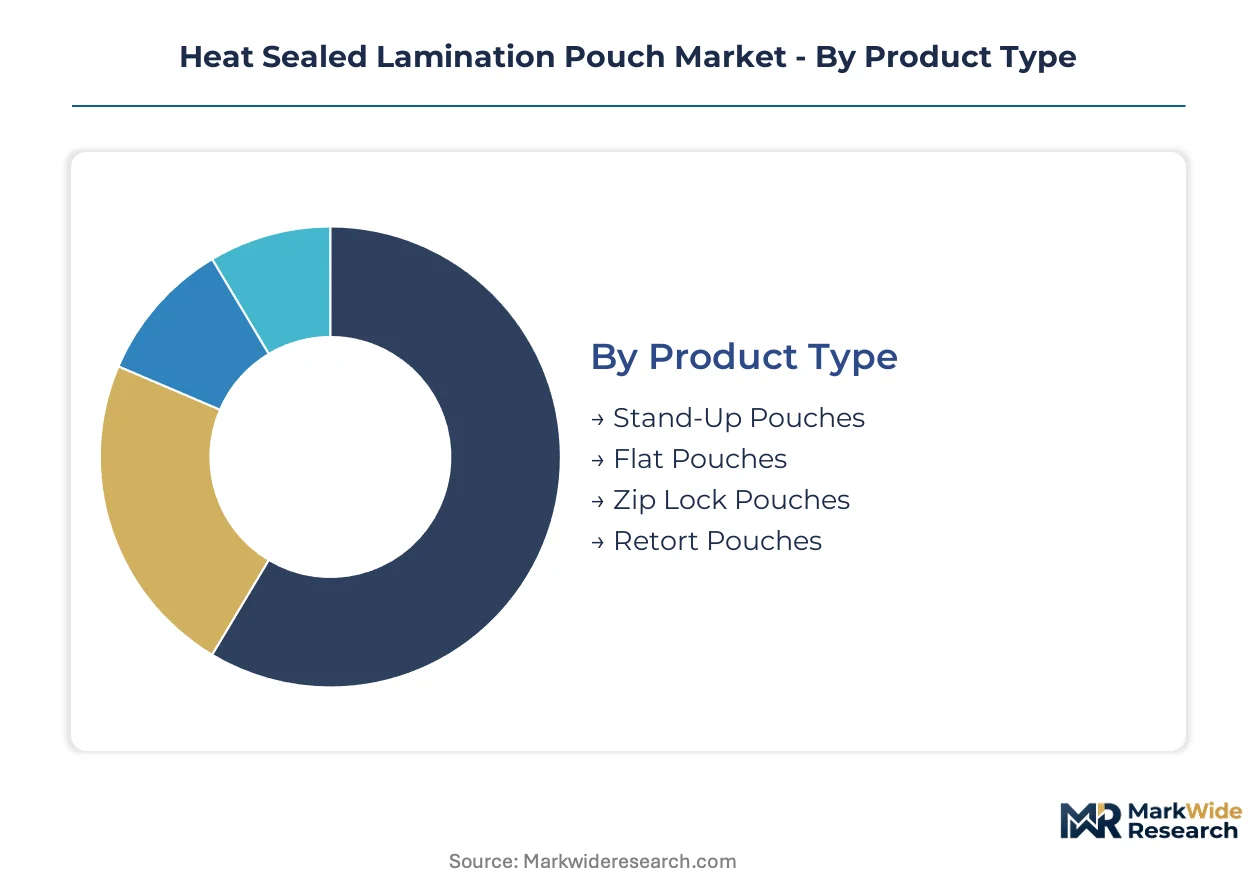
Segmentation in heat sealed lamination pouches reveals how regulatory pressure and application-specific barrier demands split procurement budgets across incompatible material specifications. Buyers now segment suppliers by compliance capability rather than commodity pricing.
Product Type:
FDA 21 CFR Part 177 food-contact certification and EU REACH Annex XVII phthalate restrictions create divergent qualification burdens across pouch formats, with retort-capable structures facing the longest approval timelines.
- Stand-Up Pouches:Gusseted bottom structures with 3-5 layer coextrusion achieve shelf stability for oxygen-sensitive snacks and beverages. German retail chains and US club stores specify these for private-label coffee and dried fruit where vertical shelf presence drives turnover. Doyen-style bottoms require precise seal-bar temperature control to prevent stress cracking during distribution.
- Retort Pouches:Multilayer laminates withstand 121°C sterilization cycles with aluminum foil or high-barrier EVOH cores replacing metal cans for ready-meals. Indian and Thai processors are converting retort lines from cans to flexible formats for export to European retailers demanding lightweight packaging. Seal integrity testing under pressure cooking conditions extends qualification cycles.
- Flat Pouches:Two- or three-layer structures serve commodity pharmaceutical and sample packaging with lower barrier requirements.
- Zip Lock Pouches:Reclosable interlocking profiles add mechanical complexity to sealant layer design for snacks and personal care sachets.
Stand-up pouches handle the majority of throughput; retort pouches are the fastest mover on share.
Material:
Input cost volatility and recycling mandates are concentrating procurement toward converters with backward integration into resin extrusion and metallization capacity.
- Aluminum Foil:6-9 micron foil laminations deliver near-zero oxygen and moisture transmission for pharmaceutical cold-chain and retort applications. Swiss and German vaccine distributors specify foil-heavy structures for temperature-sensitive biologics despite primary smelter concentration creating price volatility. Foil supply from limited European and Gulf smelters constrains margin flexibility.
- PET:Biaxially oriented polyester provides dimensional stability and print clarity for branding-intensive food and personal care segments. Indian converters with in-house PET film extrusion capture pharmaceutical export contracts requiring BIS certification compliance. Metallized PET variants displace foil in mid-barrier snack applications.
- BOPP:Balanced orientation yields high clarity and moisture resistance for confectionery and bakery overwraps at lower cost than PET.
- PE:Polyethylene sealant layers dominate food-contact applications with migration-tested formulations replacing phthalate plasticizers for EU-bound shipments.
Aluminum foil commands premium positioning; PET is expanding most quickly as metallization technology improves.
End User:
Serialization mandates and barrier specifications fragment demand across incompatible converter capabilities, with pharmaceutical and food-grade operations rarely overlapping.
- Pharmaceuticals:EU Falsified Medicines Directive unit-level tracking forces tamper-evident formats with inline variable-data printing and aggregation. German contract packagers award multi-year agreements to converters offering integrated serialization, excluding equipment-light trading houses. Oxygen transmission rates below 0.1 cc/m²/day are non-negotiable for moisture-sensitive APIs.
- Food & Beverage:Retort conversion and stand-up pouch adoption drive volume, with ready-meal processors abandoning cans for flexible sterilizable formats. California and New York plastic-content thresholds push reformulation toward bio-based sealants for regional suppliers. Shelf-life extension requirements vary dramatically by product category.
- Personal Care:Sample sachets and travel formats prioritize print quality and reclosability over extreme barrier performance.
- Electronics:Static-dissipative laminates protect moisture-sensitive components during Asian manufacturing and global distribution.
Food and beverage handles the majority of throughput; pharmaceuticals is gaining share fastest on regulatory-driven specification upgrades.
Application:
Functional requirements diverge sharply between protective shipping formats and retail-facing branded structures, with converter equipment choices locking in capability boundaries.
- Packaging:Primary containment functions span hermetic seals for sterile pharmaceuticals to reclosable convenience features for snacks. FDA and EFSA compliance timelines freeze formulation changes for 18-24 months.
- Branding:Shelf impact drives specification of metallized films, holographic effects, and high-definition flexographic printing for retail environments.
- Storage:Long-term oxygen exclusion requires high-barrier EVOH or foil laminations for emergency rations and military specifications.
- Shipping:Durable outer pouches with abrasion-resistant surfaces protect inner contents through distribution networks.
Packaging handles the majority of throughput; branding is climbing the fastest as retail differentiation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters near pharmaceutical OEMs and food processing hubs, with regulatory stringency varying sharply across jurisdictions. Germany and India anchor high-barrier laminate supply chains through distinct certification ecosystems. Aluminum foil access and EVOH extrusion capability determine regional competitive positioning.
Germany
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive compress procurement timelines for tamper-evident pouches. ECHA REACH Annex XVII phthalate restrictions force sealant reformulation, extending qualification cycles. The industrial packaging corridor in North Rhine-Westphalia concentrates multilayer coextrusion capacity serving vaccine distributors.
India
Pharmaceutical export zones drive demand for BIS-certified laminates bound for EU and US markets. CDSCO alignment with international standards accelerates track-and-trace format adoption. Gujarat and Maharashtra host captive converter operations with established testing relationships for cold-chain biologics.
United States
FDA 21 CFR Part 177 compliance governs food-contact layer composition, freezing formulation changes for 18-24 months. California and New York plastic-content thresholds push bio-based sealant development. Contract packaging houses across the Midwest and Southeast specify narrow-format pouch equipment for serialization-ready output.
Switzerland
Swissmedic regulations for temperature-sensitive biologics mandate near-zero oxygen transmission rates. Vaccine distributors specify high-barrier EVOH laminates displacing foil-heavy structures. Basel and Zurich clusters concentrate pharmaceutical cold-chain packaging expertise with integrated track-and-trace printing.
China
SAMR food-contact material standards and GB certification requirements create entry barriers for imported laminates. Domestic converters with in-house metallization capture mid-barrier snack and personal care segments. Yangtze River Delta packaging hubs supply ready-meal processors converting retort lines from metal cans.
Heat Sealed Lamination Pouch Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated multilayer extruders commanding premium positioning while equipment specialists serve contract packaging houses. The vendor base spans three tiers: capital-intensive converters with serialization capability, regional laminate specialists, and narrow-format equipment fabricators. Dominant competitive moves include backward integration into resin extrusion and strategic partnerships for track-and-trace printing systems.
Among diversified packaging conglomerates, Amcor anchors pharmaceutical pouch volumes through captive multilayer film production. Fellowes occupies a position in thermal-lamination R&D intensity for office-segment applications. USI represents the narrow-format equipment specialist archetype serving North American contract packagers. These three exemplify how scale, technology focus, and equipment specialization carve distinct competitive spaces.
| Leading Market Players |
|---|
| Fellowes |
| ACCO Brands |
| USI |
| 3M |
| GBC |
| Royal Sovereign |
| Amcor |
| Fuji Seal International |
| Bobst Group |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with primary aluminum smelters lock in foil laminate supply for German pharmaceutical converters while capping price volatility exposure across the sterilization-grade segment. These arrangements tether margin stability to Gulf and European smelter capacity, forcing mid-tier players into spot resin markets where food-grade barrier polymer scarcity amplifies cost unpredictability.
Pricing Analysis
FDA 21 CFR Part 177 dictates the pricing tier structure across food-contact laminates, with migration-tested sealant formulations commanding premiums over commodity-grade alternatives. Three-tier pricing structure across premium, standard, and economy levels separates serialization-ready pharmaceutical pouches with inline printing from basic flat pouch formats for generic drug samples. Price differentiation hinges on oxygen transmission rate certification below 0.1 cc/m²/day and EU REACH Annex XVII phthalate compliance. Cost compression in standard-tier food packaging is intensifying because BOPP oversupply from Chinese extruders erodes regional converter margins. Contract packaging houses in North America exhibit highest price sensitivity, while Swiss vaccine distributors prioritize barrier performance over unit economics.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg elevates inbound logistics costs for aluminum foil sourced from Gulf smelters, compressing working capital cycles for German laminate converters. Supply concentrates in Germany, India, and China, with North Rhine-Westphalia hosting captive multilayer extrusion, Gujarat anchoring pharmaceutical export zones, and Yangtze River Delta hubs feeding retort pouch conversion. Raw material dependencies center on 6-9 micron aluminum foil, high-barrier EVOH resin, and phthalate-free PE sealant formulations. Single-source vulnerability in primary smelter concentration creates margin volatility for cold-chain pharmaceutical laminates. Distribution runs through converter-direct relationships with pharmaceutical OEMs and food processors, bypassing distributor markups for high-specification orders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Heat Sealed Lamination Pouch Market is recovering from polymer grade scarcity cyclicality as food-grade barrier resin capacity comes online and retort conversion accelerates post-pandemic. Inventory restocking by ready-meal processors and serialization mandate deadlines in the EU are restoring converter utilization rates.
For Market Incumbents: Fortify serialization capability through inline variable-data printing investments before EU Falsified Medicines Directive enforcement hardens supplier qualification. Amcor's captive multilayer extrusion model demonstrates how backward integration into EVOH film production insulates margin compression from aluminum foil volatility. Defensive patenting around bio-based sealant chemistry secures positioning against California and New York plastic-content threshold compliance requirements. For New Entrants and Emerging Players: Contract packaging service gaps in narrow-format pouch equipment represent the most penetrable entry vector, as USI's equipment specialist archetype demonstrates sustained demand from Midwest and Southeast US packagers. India's pharmaceutical export zones offer white-space opportunity for BIS-certified converters with established CDSCO testing relationships. A go-to-market angle targeting EU-bound cold-chain biologics with high-barrier EVOH laminates displacing foil-heavy structures bypasses incumbent aluminum supply dependencies. For Investors and Strategic Acquirers: Mid-scale converters with in-house multilayer coextrusion and established ECHA notification relationships offer the strongest acquisition target archetype for pharmaceutical serialization exposure. Long-term viability over a five-to-ten year window rests on regulatory compliance capability rather than commodity scale. The signal to watch is EU extended producer responsibility framework implementation pace, which will accelerate mono-material recyclable laminate qualification timelines and reward early polyethylene-compatible barrier design movers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EVOH Extrusion | German converters with captive high-barrier film production capture pharmaceutical cold-chain contracts from Swiss vaccine distributors. |
| Serialization-Ready Equipment Upgrade | Inline variable-data printing and aggregation capability secures multi-year agreements from EU contract packagers under Falsified Medicines Directive pressure. |
| Bio-Based Sealant Reformulation | California and New York plastic-content thresholds drive R&D investment toward migration-tested alternatives displacing phthalate plasticizers. |
| BIS Certification Investment | Domestic Indian converters with established testing relationships capture captive supply advantages for EU and US-bound pharmaceutical exports. |
| Mono-Material Recyclable Design | EU packaging waste directives reward polyethylene-compatible barrier laminates with preferential extended producer responsibility fee structures. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with multilayer extrusion operators, pharmaceutical contract packaging procurement leads, and ECHA regulatory affairs specialists; and secondary validation through FDA 21 CFR Part 177 filing databases, EU REACH Annex XVII substance restriction updates, and BIS certification registries. Bottom-up triangulation across converter capacity surveys and top-down cross-checks against customs trade flows for aluminum foil and EVOH resin anchored volume estimates.
Across the analysis window, the forecasting framework modeled demand trajectories by product type (stand-up, retort, flat, zip lock), material composition (aluminum foil, PET, BOPP, PE), end user vertical (pharmaceuticals, food and beverage, personal care, electronics), and application function (packaging, branding, storage, shipping). CAGRs were derived from regression analysis of historical converter shipment data against regulatory mandate timelines and sterilization-format adoption curves. Industry-specific inputs included oxygen transmission rate specification tightening and retort line conversion rates from metal cans.
Forecasts assume regulatory continuity in FDA, ECHA REACH, and BIS regimes; material policy shifts around phthalate restrictions or extended producer responsibility would require re-modeling. Specific risks include aluminum foil supply disruption from smelter concentration, multilayer coextrusion technician wage inflation, and polymer grade scarcity persistence. Recalibration cycles align with material shifts in EU serialization enforcement deadlines and state-level plastic-content threshold implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Retort Pouch Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Utility Pouches Market
Pouch
Global Pouches Packaging Market
Pouch
Italy Pouch Packaging Market
Pouch
Fin Seal Pouches Market
Pouch
Global Boil-In Bags Market
Pouch
Mexico Pouch Packaging Market
Pouch
Pouch Equipment Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Brazil Pouch Packaging Market
Pouch
Aluminum-Free Food Pouch Market
Pouch
Paper Pouch Market
Pouch
Inverted Pouch Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Pre-Made Pouch Packaging Market