
 Peel Pouches Market | 2026-2036
Peel Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Peel Pouches Market Outlook
Hospital procurement channels is narrowing as group purchasing organizations consolidate supplier lists for sterile peel pouches. Amcor Plc leverages its global film extrusion footprint to secure multi-year contracts with major health systems. Wipak Group anchors its position through specialized cleanroom manufacturing in Northern Europe. Nelipak Healthcare Packaging differentiates via vertically integrated thermoforming and pouch conversion for Class II device customers.
Peel pouches are flexible sterile barrier systems constructed from medical-grade paper, Tyvek, or coextruded films with controlled peel strength typically measured in grams per inch; they enable aseptic presentation of surgical instruments and implantable devices without compromising sterility. Flat pouches dominate volume in general surgery applications where cost sensitivity limits specification complexity, while retort pouches command margin pools in pharmaceutical sterilization where steam and radiation resistance justify premium material stacks. Composites represent the fastest-expanding material category as multi-layer coextrusions replace single-polymer constructions to meet evolving barrier requirements.
FDA enforcement of ISO 11607-1 compliance for sterile barrier validation shapes product development timelines and testing expenditure for US-focused manufacturers, while the EU Medical Device Regulation (MDR) and REACH chemical restrictions compel European suppliers to reformulate adhesives and coatings. Stakeholders must monitor regulatory divergence between FDA 510(k) sterile packaging expectations and the EU's Notified Body review intensity to avoid dual-qualification cost overruns.
Market Dynamics
Hospital sterile processing departments are consolidating supplier relationships around validated peel pouch systems as FDA 510(k) packaging requirements tighten and surgical kit complexity accelerates material specification demands.
Growth Catalysts
- EN ISO 11607-1 Validation Mandates:European healthcare systems are mandating documented sterile barrier performance, forcing hospital procurement toward pre-qualified pouch suppliers with certified testing protocols.
- Tyvek-to-Film Migration:Advanced coextruded film structures are replacing traditional medical-grade papers in implantable device packaging, driven by superior moisture vapor transmission rate control and puncture resistance.
- German Hospital Infrastructure:The country's university medical centers are expanding central sterile supply departments, creating concentrated demand for high-performance retort-compatible pouch configurations.
Market Restraints
- Medical-Grade Polymer Cost Volatility:Ethylene-vinyl alcohol and cyclic olefin copolymer resin prices fluctuate with petrochemical feedstock markets, compressing margin stability for multi-layer film converters.
- Cleanroom Manufacturing Concentration:Sterile barrier production capacity clusters in Northern European industrial corridors, creating geographic supply risk and extended logistics lead times for North American device manufacturers.
- Adhesive Reformulation Friction:REACH chemical restrictions on solvent-based coatings force European suppliers to requalify bonding chemistries, extending product development cycles by 12-18 months.
Strategic Opportunities
- Indian Contract Manufacturing Expansion:CDSCO's streamlined medical device licensing pathways are attracting global OEMs to establish sterile packaging operations serving Asian and Middle Eastern markets.
- Home Healthcare Sterile Kits:Ambulatory surgical centers and home infusion therapy providers represent underpenetrated channels requiring smaller-format, patient-friendly peel pouch designs with intuitive aseptic presentation.
- RFID-Enabled Smart Packaging:Convergence of near-field communication tags with sterile barriers creates track-and-trace capabilities for high-value implantable devices, satisfying FDA UDI compliance and hospital inventory automation needs.
Industry Challenges
- ISO 17025 Laboratory Certification Scarcity:Validated peel strength and microbial barrier testing capacity is concentrated among a limited number of accredited third-party laboratories, creating bottlenecks for new product introductions.
- Thermoforming-Pouch Integration Complexity:Device manufacturers seeking unified sterile barrier systems face technical coordination challenges between thermoformed tray suppliers and flexible pouch converters, requiring synchronized validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peel Pouches Market |
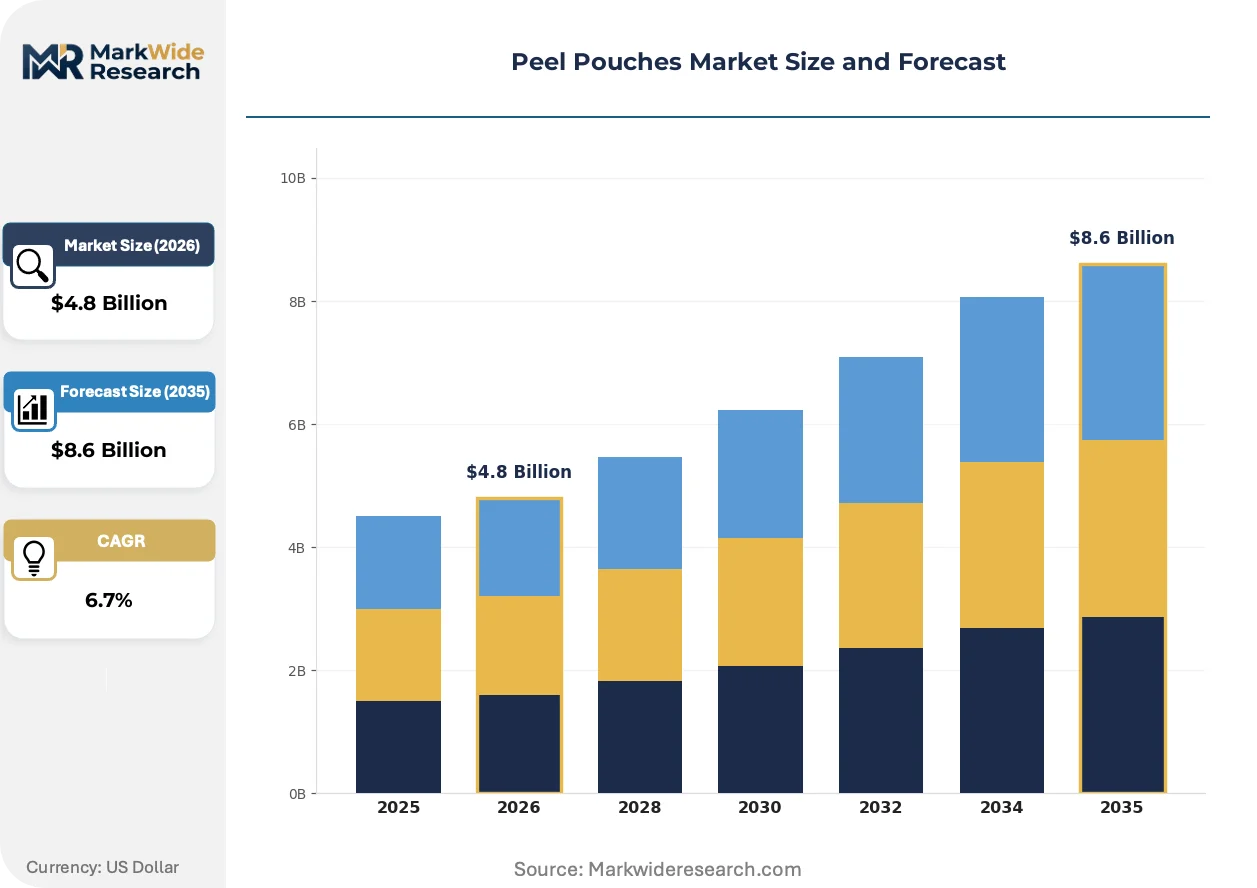
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Gusseted Pouches, Retort Pouches Material: Plastic, Aluminum, Paper, Composites End User: Food, Pharmaceuticals, Personal Care, Industrial Packaging Type: Single-Serve, Multi-Serve, Bulk Packaging, Custom Sizes |
| Companies Covered | Amcor Plc, Wipak Group, ProAmpac LLC, 3M Company, Nelipak Healthcare Packaging, Oliver Healthcare Packaging, Printpack, Berry Global Inc., SteriPack Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peel Pouches Market Strategic Shifts
Digital traceability requirements and material science advances are compressing product development cycles while elevating performance specifications for next-generation sterile barrier systems.
Radio-frequency identification inlays embedded within peel pouch substrates are digitizing supply chain visibility for orthopedic implant manufacturers. Stryker and Zimmer Biomet procurement teams now mandate serialized packaging for high-value joint replacement kits. This technology is digitizing inventory reconciliation processes that previously required manual lot-number verification, reducing surgical kit preparation errors.
The EU Medical Device Regulation's intensified Notified Body scrutiny of sterile packaging validation is elevating documentation burdens for pouch manufacturers serving European markets. Technical files must now include accelerated aging studies and transport simulation data previously considered optional. Small and mid-sized device companies are responding by consolidating supplier relationships around vertically integrated packaging partners with in-house ISO 17025 testing capabilities.
Group purchasing organizations are compressing sterile peel pouch vendor lists from twelve to four approved suppliers per health system. Premier and Vizient member hospitals now require single-source accountability for tray-and-pouch combinations, displacing fragmented procurement of separate components. This concentration is most visible in the United States, where IDN consolidation has created procurement entities representing 500+ hospital facilities with unified material specification authority.
Peel Pouches Market Segmentation
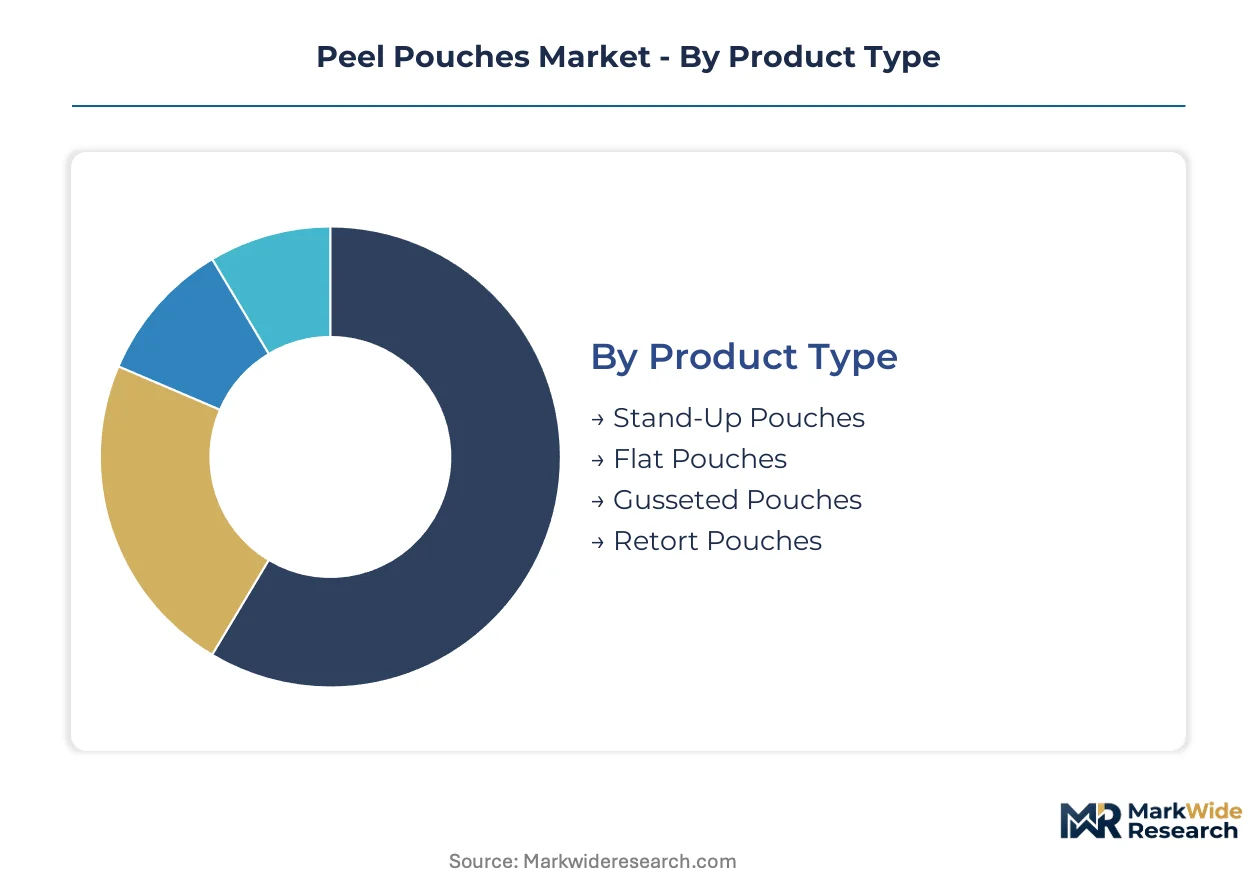
Peel pouch specification varies sharply by sterilization modality and presentation requirements. Material selection and format geometry determine barrier performance, aseptic handling characteristics, and regulatory qualification pathways.
Product Type:
Flat pouches turn inventory fastest in high-volume surgical kit operations, while retort configurations sit longer in pharmaceutical sterilization queues due to extended validation protocols.
- Flat Pouches:Two-dimensional sealed envelopes of medical-grade paper or film with linear peel seams dominate general surgery instrument packaging. German university hospitals specify these for central sterile supply departments where throughput velocity outweighs premium barrier requirements.
- Retort Pouches:Multi-layer laminates withstand steam, radiation, and ethylene oxide sterilization cycles for implantable devices. Stryker and Zimmer Biomet procurement teams mandate these for orthopedic kits where moisture vapor transmission rates below 0.1 g/m²/day are non-negotiable.
- Stand-Up Pouches:Bottom-gusseted formats with vertical presentation capability suit liquid pharmaceutical containers and diagnostic reagent bottles.
- Gusseted Pouches:Side-folded expansion panels accommodate bulky surgical instruments without compromising seal integrity.
Flat pouches dominate installed base. Retort pouches are where expansion concentrates.
Material:
Cost tiers separate commodity polymer constructions from engineered multi-layer stacks with certified barrier performance.
- Composites:Coextruded films bonded to Tyvek or aluminum foil deliver tuned moisture, oxygen, and microbial barriers. The EU MDR's intensified Notified Body scrutiny is forcing device companies toward these pre-qualified material stacks to accelerate technical file approvals.
- Plastic:Polyethylene and polypropylene monolayers serve cost-sensitive applications where sterilization cycles are gentle and shelf lives brief. Indian contract manufacturers leverage these for domestic pharmaceutical packaging under CDSCO streamlined licensing.
- Aluminum:Foil laminates provide absolute light and gas barriers for photosensitive biologics.
- Paper:Medical-grade kraft with controlled porosity remains specified for steam-permeable sterilization of metal instruments.
Plastic holds volume leadership. Composites are climbing the fastest as barrier specifications tighten.
End User:
Application risk profiles drive specification divergence between life-critical and consumer-grade packaging.
- Pharmaceuticals:Implantable devices, parenteral drugs, and biologics require ISO 11607-1 validated sterile barrier systems with documented peel strength between 500-1500 grams per inch. FDA 510(k) packaging submissions now demand accelerated aging studies that extend product development timelines.
- Food:Retort pouches for ready-to-eat meals and aseptic liquid packaging prioritize seal integrity under thermal processing. European suppliers face REACH adhesive reformulation mandates that extend qualification cycles.
- Personal Care:Sterile wipes, masks, and topical applicators use lower-specification barriers with shorter validation requirements.
- Industrial:Electronics and aerospace components utilize similar film technologies without medical-grade certification overhead.
Food commands unit volume. Pharmaceuticals concentrate margin expansion.
Packaging Type:
Customer scale and kit complexity determine format economics.
- Single-Serve:Individual instrument pouches for ambulatory surgical centers and home infusion therapy. Premier and Vizient GPOs are consolidating these specifications across 500-plus hospital facilities.
- Multi-Serve:Procedure-specific kits with 5-20 instruments arranged in sequence for surgical workflow efficiency.
- Bulk Packaging:Large-format rolls or stacks for automated sterile processing department lines.
- Custom Sizes:Device-specific dimensions for irregular orthopedic implants and robotic surgery attachments.
Multi-serve dominates hospital procurement. Single-serve is gaining share fastest in ambulatory channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German EN ISO 11607 compliance mandates are concentrating procurement toward validated suppliers, while FDA 510(k) packaging requirements in the United States and CDSCO streamlined licensing in India are reshaping regional competitive positioning. Healthcare infrastructure investments and regulatory divergence are creating distinct market architectures across major economies.
Germany
University medical centers in Heidelberg and Munich are expanding central sterile supply departments with retort-compatible pouch configurations. ECHA REACH chemical restrictions on solvent-based adhesives are forcing reformulation cycles that extend product development timelines by 12-18 months. The Northern European industrial corridor around Hamburg anchors cleanroom manufacturing concentration for flexible barrier systems.
United States
Group purchasing organizations like Premier and Vizient are consolidating vendor lists from twelve to four approved suppliers per health system. FDA enforcement of ISO 11607-1 compliance for sterile barrier validation is elevating testing expenditure and documentation burdens for domestic manufacturers. The Boston-Cambridge medical device cluster drives specification complexity for orthopedic implant packaging.
India
Contract manufacturing expansion is accelerating as CDSCO streamlined medical device licensing pathways attract global OEMs establishing sterile packaging operations. Domestic pharmaceutical packaging leverages cost-sensitive polyethylene and polypropylene monolayers under simplified regulatory frameworks. The Mumbai-Pune industrial belt hosts emerging flexible barrier conversion capacity serving Asian and Middle Eastern markets.
China
NMPA medical device registration requirements are elevating barrier validation standards for implantable device packaging serving domestic and export markets. SAMR quality system inspections are compressing supplier qualification timelines for multinational healthcare companies. The Yangtze River Delta manufacturing base integrates film extrusion and pouch conversion for Class II device customers.
Japan
PMDA pharmaceutical packaging regulations mandate documented sterile barrier performance for parenteral drug applications. METI industrial policy supports advanced coextruded film development to replace traditional medical-grade papers in high-value therapeutic packaging. The Osaka-Kobe industrial zone maintains specialized cleanroom capacity for precision barrier systems.
Peel Pouches Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated converters with in-house ISO 17025 testing capabilities and certified cleanroom manufacturing footprints. Strategic archetypes include global film extrusion specialists securing multi-year health system contracts, regional cleanroom manufacturers anchoring position through specialized Northern European production, and vertically integrated thermoforming-pouch converters serving Class II device OEMs. Dominant competitive moves encompass strategic partnerships with group purchasing organizations and geographic expansion into Indian contract manufacturing zones.
Among the named players, Amcor Plc exemplifies the global scale archetype with multinational film extrusion infrastructure, while Wipak Group represents regional specialization through Northern European cleanroom manufacturing concentration. Nelipak Healthcare Packaging occupies a position as the vertically integrated specialist, combining thermoforming and pouch conversion capabilities for device customers requiring unified sterile barrier systems. These three anchors illustrate the competitive segmentation between scale-driven global supply, regional regulatory proximity, and integrated technical service models.
| Leading Market Players |
|---|
| Amcor Plc |
| Wipak Group |
| ProAmpac LLC |
| 3M Company |
| Nelipak Healthcare Packaging |
| Oliver Healthcare Packaging |
| Printpack |
| Berry Global Inc. |
| SteriPack Group |
| Others |
Value Chain & Pricing Dynamics
The Northern European industrial corridor around Hamburg concentrates cleanroom manufacturing capacity for flexible sterile barriers, granting established converters leverage over hospital procurement teams facing extended qualification timelines for alternative suppliers.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers. FDA 510(k)-validated pouch systems command substantial premiums over CE-marked equivalents due to documentation burdens and testing expenditure. Pricing pressure stems from group purchasing organization consolidation compressing vendor lists from twelve to four approved suppliers per health system. Ambulatory surgical centers exhibit highest price sensitivity, while orthopedic implant manufacturers prioritize barrier performance over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become standard as converters absorb working capital strain from hospital procurement cycles. Raw material supply draws from Germany, the United States, and India for medical-grade polymers and coextruded films. Ethylene-vinyl alcohol and cyclic olefin copolymer resin dependencies expose converters to petrochemical feedstock volatility. Single-source vulnerability concentrates in ISO 17025-accredited testing laboratories. Distribution runs through group purchasing organization contracts directly to hospital sterile processing departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peel pouch adoption sits in early-cycle expansion as RFID-enabled smart packaging penetration accelerates surgical kit traceability mandates across health systems.
For Market Incumbents: Entrench position by securing multi-year contracts with Premier and Vizient member hospitals before GPO vendor lists finalize consolidation. Invest in backward integration into coextruded film production to offset medical-grade polymer cost volatility. Certification investment in ISO 17025 laboratory capabilities creates defensive moats against emerging regional competitors. For New Entrants and Emerging Players: Build out specialized capacity serving Indian contract manufacturing zones where CDSCO streamlined licensing attracts global OEMs establishing sterile packaging operations. Home healthcare sterile kits represent the most penetrable white-space channel, requiring smaller-format patient-friendly designs. A go-to-market angle targeting ambulatory surgical centers with simplified aseptic presentation features bypasses entrenched hospital procurement barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial packaging parents with underoptimized healthcare divisions lacking ISO 11607-1 validation capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity conversion scale. The signal to watch is FDA enforcement intensity for sterile barrier validation, which would accelerate consolidation toward pre-qualified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 17025 Laboratory Certification | In-house testing capabilities accelerate product introductions and reduce third-party bottlenecks for device manufacturers. |
| RFID-Enabled Smart Packaging Integration | Near-field communication tags satisfy FDA UDI compliance and hospital inventory automation requirements for orthopedic implants. |
| Hospital System Partnership | Single-source accountability for tray-and-pouch combinations aligns with GPO consolidation toward four approved suppliers. |
| Backward Integration into Film Extrusion | Captive supply of coextruded films insulates margin stability from ethylene-vinyl alcohol resin price volatility. |
| Geographic Expansion into India | CDSCO streamlined licensing pathways attract global OEMs establishing sterile packaging operations serving Asian markets. |
Study Parameters
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings. Stakeholder consultations encompassed sterile processing department managers, biomedical engineers, GPO contracts managers, and regulatory affairs leads at device manufacturers. Secondary validation drew from FDA 510(k) packaging submissions, EN ISO 11607 technical documentation, hospital procurement databases, and GPO contract disclosures. Bottom-up demand modeling triangulated against top-down market sizing from trade flow analysis.
Calibration against historical validation timelines and sterilization modality adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, material composition, end-user application, and packaging format. CAGRs derived from regression analysis of installed base expansion and replacement cycle dynamics. Industry-specific forecast inputs incorporated REACH adhesive reformulation timelines and FDA enforcement intensity patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Asian converters or accelerated RFID mandate implementation would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Russia Pouch Packaging Market
Pouch
Inverted Pouch Market
Pouch
Global Pouches Packaging Market
Pouch
Four Side-Sealed Pouches Market
Pouch
North America Pouch Packaging Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Ziplock Products Market
Pouch
Kraft Pouch Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Retort Pouch Market
Pouch
Foam Pouch Market
Pouch
Liquid Pouch Packaging Market
Pouch
India Pouch Packaging Market
Pouch
China Pouch Packaging Market
Pouch
Global Boil-In Bags Market