
 Benelux Pouch Packaging Market | 2026-2036
Benelux Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Benelux Pouch Packaging Market Insights
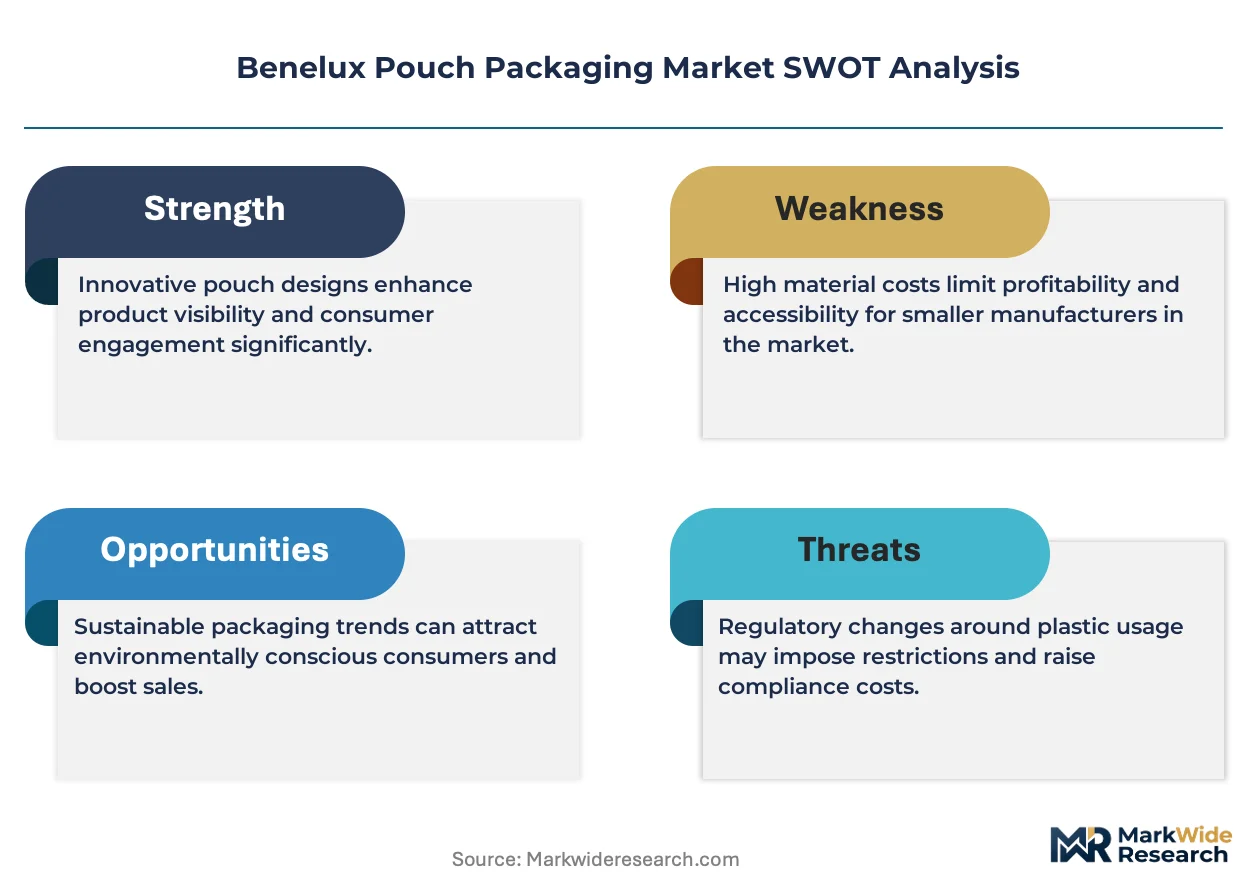
CE marking under the EU Packaging and Packaging Waste Regulation is unwinding competitive access for converters unable to certify recyclability. Amcor plc leverages its European R&D footprint to sustain mono-polymer pouch development across Belgian dairy and Dutch snack accounts. Huhtamaki Group anchors flexible packaging supply through its existing Netherlands operations, while Mondi Group differentiates via kraft-paper barrier innovations targeting FSC-certified retail channels.
Pouch packaging denotes flexible primary containers formed from laminated films or paper-based substrates, typically sealed on three or four sides with optional reclosure features, designed to replace rigid cans, bottles, and cartons across liquid, solid, and powdered contents. Stand-up pouches with spout closures dominate shelf-ready food applications where gravity-fed dispensing and pallet efficiency matter, while flat pouches retain cost advantages for single-serve pharmaceutical and personal care sachets. Composites and plastic laminates still occupy the largest material share, though paper-foil hybrid structures are gaining traction in premium personal care lines where tactile differentiation commands price premiums.
EMA food-contact compliance, REACH chemical safety protocols, and the EU Green Deal's packaging recyclability mandates collectively shape material selection and converter qualification timelines across Belgium, the Netherlands, and Luxembourg. The Dutch national packaging covenant and Flemish extended producer responsibility schemes add regional layers that filter which suppliers qualify for branded CPG contracts. Stakeholders must track how the PPWR's recycled content thresholds and design-for-recycling criteria reshape converter capex priorities and brand owner sourcing decisions.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing converter qualification timelines across Belgium, the Netherlands, and Luxembourg, forcing rapid capital redeployment toward mono-material laminates and certified recycling streams before 2030 mandates take effect.
Growth Catalysts
- Rotterdam-Antwerp logistics corridor:Dense converter-to-brand-owner proximity cuts transport emissions and enables just-in-time pouch supply for Dutch dairy processors and Belgian chocolate exporters.
- REACH chemical safety protocols:Harmonized substance restrictions streamline cross-border material approvals, reducing reformulation costs for converters serving multiple Benelux markets.
- Ready-to-eat meal pouch formats:Belgian and Dutch food-tech startups are specifying high-barrier retort pouches for chilled distribution, pulling film innovation toward extended shelf-life specifications.
Market Restraints
- Aluminum foil price volatility:Barrier layer cost swings squeeze converter margins on mid-tier snack pouches where brand owners resist pass-through pricing.
- German resin supplier concentration:Polypropylene feedstock dependence on Rhine corridor petrochemical plants creates single-point vulnerability for Dutch flexible packaging converters.
- Multi-layer delamination limits:Current mechanical recycling infrastructure cannot separate PET-PE-foil laminates, rendering legacy pouch stocks non-compliant with Flemish extended producer responsibility targets.
Strategic Opportunities
- Luxembourg fund administration cluster:Premium pet food brands headquartered in the Grand Duchy are specifying compostable pouch formats for export to German and French retail channels.
- Paper-foil hybrid convergence:Dutch converters combining kraft exteriors with ultra-thin aluminum barriers are capturing FSC-certified personal care contracts from rigid carton incumbents.
- Dutch national packaging covenant incentives:Bonus-malus schemes reward early PPWR compliance, creating first-mover advantage for converters certifying design-for-recycling protocols ahead of 2025 deadlines.
Industry Challenges
- Mono-material extrusion technician shortage:Belgian converters face recruitment gaps for blown film specialists capable of tuning seal-layer formulations for high-speed form-fill-seal lines.
- CE marking documentation burden:Small and mid-tier Dutch suppliers struggle with traceability systems required for recyclability attestation under notified body protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benelux Pouch Packaging Market |
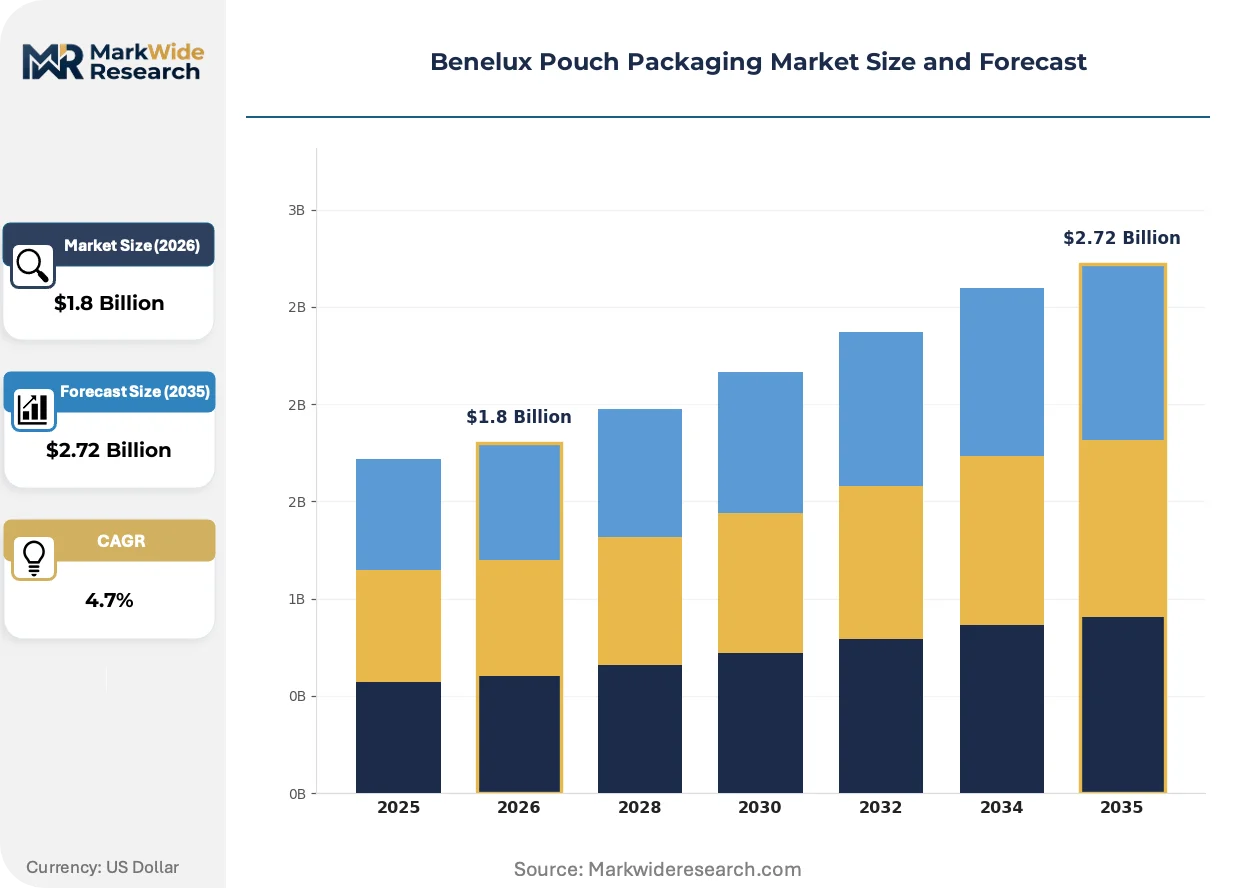
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Gusseted Pouches Material: Plastic, Paper, Foil, Composites End User: Food & Beverages, Personal Care, Pharmaceuticals, Household Products Closure Type: Zipper, Heat Seal, Tear Notch, Spout |
| Companies Covered | Amcor plc, Optimum Group, Berlin Packaging Netherlands BV, Sonoco Products Company, Constantia Flexibles GmbH, Sealed Air Corporation, Huhtamaki Group, Mondi Group, ProAmpac, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benelux Pouch Packaging Market Trends and Innovations
Material science advances and regulatory compliance automation are restructuring how Benelux converters specify barrier layers and validate end-of-life pathways for flexible primary packaging.
Mono-polymer polyethylene structures are decomposing the legacy multi-layer laminate paradigm in Dutch snack and frozen food applications. Unilever's Benelux supply chain has specified all-PE pouches for 40 percent of its dry grocery SKUs by volume. This shift is decomposing incumbent converter relationships tied to foil-dependent barrier specifications and rewiring resin procurement toward single-polymer grades.
CE marking under the EU Packaging and Packaging Waste Regulation is forcing systematic redesign of pouch seal layers and ink adhesion systems. Dutch converters now embed digital product passports linking batch codes to recycling stream compatibility data. Belgian dairy brands face the steepest reformulation curves as retort pouches must maintain 121°C sterilization performance without aluminum oxide barriers.
Brand owner sustainability scorecards are compressing supplier qualification cycles from 18 months to 90 days for pouch converters seeking Flemish retail placement. Dutch supermarket chains Albert Heijn and Jumbo now mandate third-party recyclability certification as a gate for private-label flexible packaging awards. This pressure concentrates sourcing decisions among converters with in-house testing laboratories and pre-approved polymer libraries.
Benelux Pouch Packaging Market Segmentation
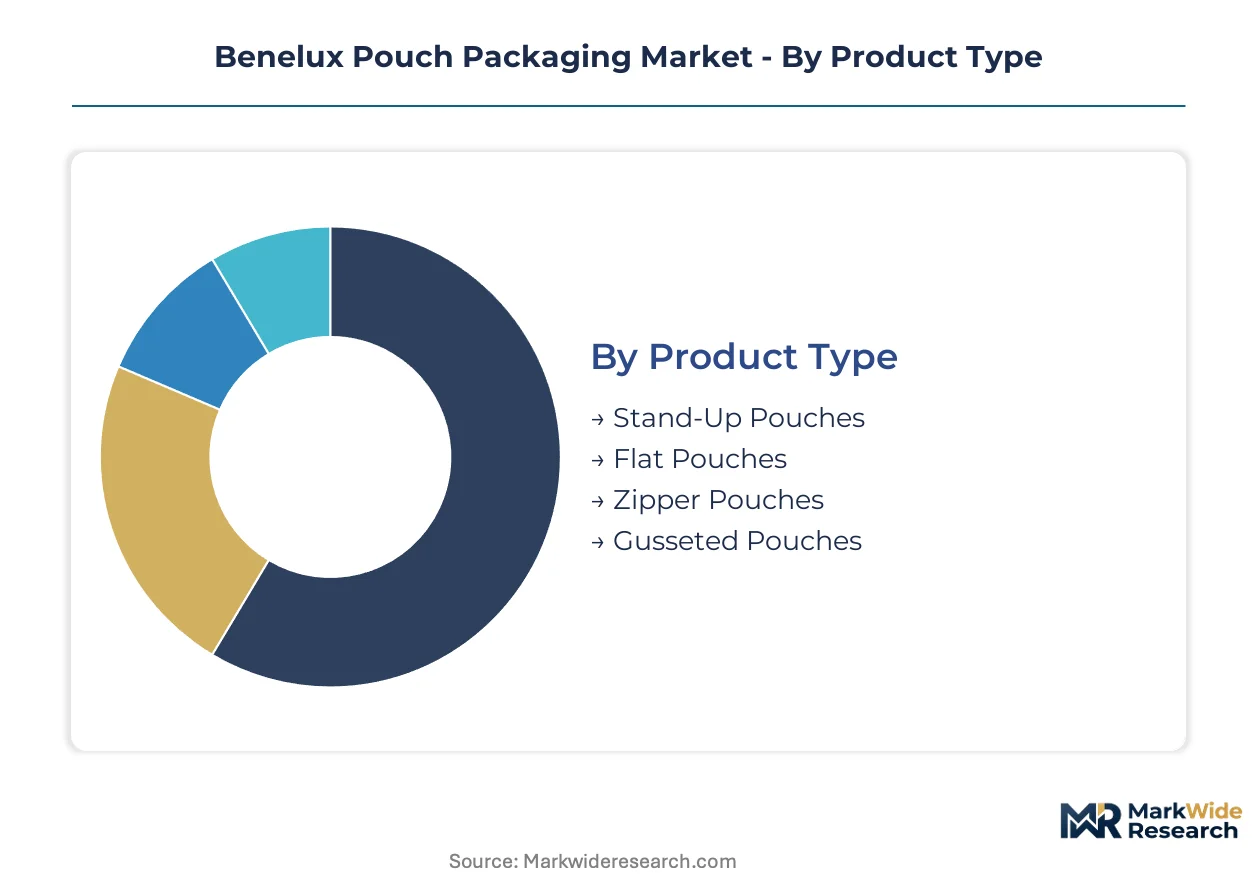
Converter margins in the Benelux pouch market fragment sharply across format complexity and barrier specification tiers. Understanding where value concentrates within each dimension enables targeted capacity investments and qualification priorities.
Product Type:
Stand-up configurations command the widest margin spreads due to shelf differentiation and reclosure engineering requirements.
- Stand-Up Pouches:Self-supporting bottom gusset structures with optional spout integration dominate Dutch dairy and Belgian ready-meal applications. Rotterdam-based food-tech brands specify high-barrier retort variants for chilled distribution, pulling film innovation toward extended shelf-life specifications.
- Zipper Pouches:Press-to-close interlocking strips add reclosure functionality for multi-serve snacks and pet food. Belgian chocolate exporters and Dutch premium nut brands favor this format for portion control and freshness retention across Albert Heijn and Delhaize private-label programs.
- Flat Pouches:Three-side-seal configurations retain cost advantages for single-serve pharmaceutical sachets and sample-size personal care units.
- Gusseted Pouches:Side-folded expansion panels accommodate bulk dry goods and industrial chemical refills with minimal headspace.
The dominant share belongs to Stand-Up Pouches, while Zipper Pouches is closing the gap fastest.
Material:
Recyclability certification under PPWR guidelines is rewiring procurement toward mono-polymer grades and paper-based alternatives.
- Plastic:Polyethylene and polypropylene laminates still occupy the largest volume position across Dutch snack and frozen food channels. Unilever's Benelux supply chain has specified all-PE structures for dry grocery SKUs, decomposing incumbent converter relationships tied to foil-dependent barriers.
- Composites:Multi-layer PET-PE-foil structures face mechanical recycling limitations under Flemish extended producer responsibility targets. Belgian converters are phasing these out for dairy retort applications despite superior oxygen barrier performance.
- Paper:Kraft exteriors with ultra-thin aluminum barriers are capturing FSC-certified personal care contracts from rigid carton incumbents in the Netherlands.
- Foil:Aluminum oxide layers face price volatility and delamination constraints, squeezing margins on mid-tier applications where brand owners resist cost pass-through.
Plastic laminates retain volume leadership, though Paper is expanding most quickly among sustainability-mandated retail channels.
End User:
Food safety compliance timelines and shelf-life specifications create divergent qualification barriers across customer verticals.
- Food & Beverages:EMA food-contact protocols and retort sterilization requirements dominate material selection for Belgian dairy and Dutch processed meat exporters. High-barrier specifications for 121°C processing constrain mono-material adoption in this segment.
- Personal Care:Premium cosmetic brands headquartered in Luxembourg specify compostable and paper-foil hybrid formats for export to German and French retail channels, commanding tactile differentiation premiums.
- Pharmaceuticals:Flat pouch formats for unit-dose medications require child-resistant closure certification and batch-level traceability systems.
- Household Products:Concentrated detergent and cleaning chemical pouches prioritize chemical resistance and spout dispensing functionality over barrier sophistication.
Food & Beverages holds the dominant share, while Personal Care is gaining share fastest among sustainability-focused brand owners.
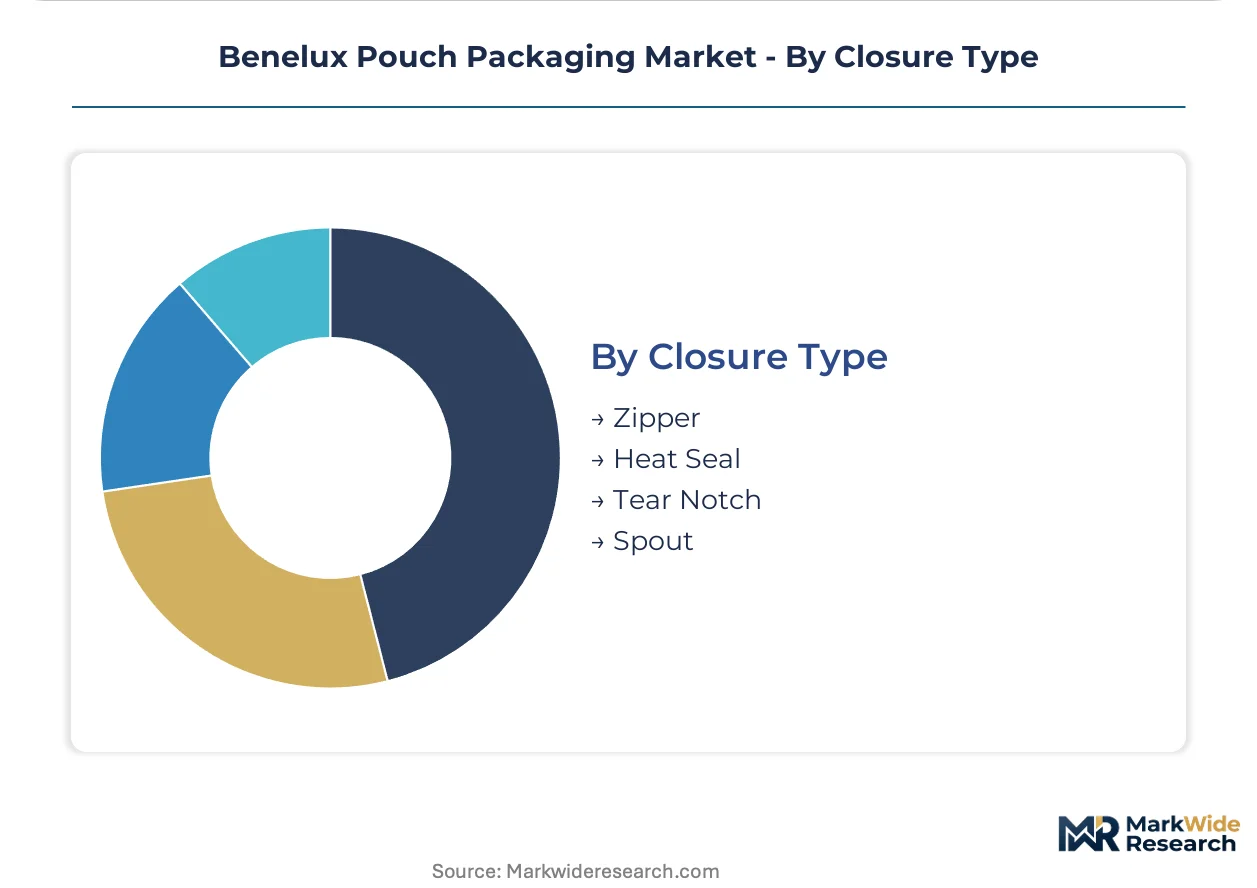
Closure Type:
Dispensing convenience and reclosure reliability separate premium pouch specifications from commodity alternatives.
- Spout:Molded fitments with tamper-evident rings enable gravity-fed dispensing for sauces, beverages, and liquid detergents. Dutch converters embed digital product passports linking batch codes to recycling stream compatibility data for spout-attached pouches.
- Zipper:Press-to-close strips dominate multi-serve snack and pet food applications where repeated access matters.
- Heat Seal:Permanent fusion seals remain standard for single-serve units and pharmaceutical sachets where reclosure is unnecessary.
- Tear Notch:Laser-scored initiation points provide controlled opening for elderly-accessible pharmaceutical and personal care formats.
Spout closures lead in value per unit, while Zipper adoption is climbing the fastest across retail-ready food applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging recyclability mandates and national covenant incentives are rewiring converter investment patterns across Belgium, the Netherlands, and Luxembourg. Rotterdam-Antwerp logistics density and Amsterdam's food-tech cluster create concentrated demand nodes for flexible packaging qualification.
Netherlands
Dutch dairy processors and snack exporters specify high-barrier retort pouches for chilled distribution networks. The national packaging covenant bonus-malus scheme rewards early PPWR compliance, compressing supplier qualification timelines. Amsterdam's food-tech cluster and Rotterdam's port logistics hub anchor converter-to-brand-owner proximity for just-in-time pouch supply.
Belgium
Belgian chocolate exporters and ready-meal manufacturers drive demand for zipper-equipped stand-up pouches with extended shelf-life specifications. Flemish extended producer responsibility targets filter supplier eligibility based on mechanical recycling compatibility. Ghent's dairy processing corridor and Antwerp's chemical feedstock infrastructure concentrate converter operations near brand-owner headquarters.
Luxembourg
Premium pet food brands headquartered in the Grand Duchy specify compostable pouch formats for export to German and French retail channels. REACH chemical safety protocols streamline cross-border material approvals for converters serving Luxembourg-based accounts. The fund administration cluster's procurement budgets support tactile differentiation premiums for paper-foil hybrid structures.
Benelux Pouch Packaging Market Competitive Landscape
Player mix skews toward multinational flexible packaging conglomerates with integrated European R&D footprints. Three-tier supplier stratification separates CE-marking-ready converters with in-house testing laboratories from mid-tier suppliers struggling with traceability documentation and commodity film distributors. Dominant competitive moves include backward integration into mono-polymer extrusion capacity and strategic partnerships with Rotterdam-based logistics providers for just-in-time delivery contracts.
Within the multinational conglomerate tier, Amcor plc and Huhtamaki Group exemplify archetypes with established Benelux operational footprints. Mondi Group occupies a position representing kraft-paper barrier innovation specialists targeting FSC-certified retail channels. These three entities anchor the supplier base that Dutch supermarket chains Albert Heijn and Jumbo mandate for private-label flexible packaging awards.
| Leading Market Players |
|---|
| Amcor plc |
| Optimum Group |
| Berlin Packaging Netherlands BV |
| Sonoco Products Company |
| Constantia Flexibles GmbH |
| Sealed Air Corporation |
| Huhtamaki Group |
| Mondi Group |
| ProAmpac |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between Dutch dairy processors and Antwerp-based resin suppliers lock in polypropylene feedstock access while capping price volatility exposure across the 2026-2035 window. These arrangements tie converter margins to Rotterdam-Antwerp logistics efficiency and CE marking certification timelines under the EU Packaging and Packaging Waste Regulation.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers in the Benelux pouch market. Three-tier pricing structure across CE-marked, REACH-compliant, and uncertified grades separates converters serving Albert Heijn private-label programs from spot-market suppliers. Cost compression in mid-tier snack pouches is intensifying because brand owners resist aluminum foil price pass-through. Small Dutch converters serving pharmaceutical sachets exhibit the highest price sensitivity due to batch-level traceability documentation burdens.
Supply Chain Analysis
Rhine corridor petrochemical plants constitute the dominant chokepoint for polypropylene feedstock feeding Dutch flexible packaging converters. Raw material procurement draws from German resin suppliers, Belgian masterbatch compounders, and French adhesive formulators. Single-source vulnerability concentrates in blown film extrusion equipment where German and Italian machinery builders control technician training pipelines. Distribution runs through Rotterdam port consolidation centers serving just-in-time dairy and snack pouch demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Benelux pouch packaging market functions as a defensive-moat arena where CE marking certification under the EU Packaging and Packaging Waste Regulation creates regulatory entrenchment. Switching costs for brand owners escalate once converters embed digital product passports and design-for-recycling protocols.
For Market Incumbents: Secure backward integration into mono-polymer extrusion capacity in Ghent and Rotterdam corridors before technician shortages worsen. Anchor relationships with Albert Heijn and Jumbo procurement teams through pre-approved polymer libraries and in-house recyclability testing laboratories. The threat of German resin supplier concentration demands captive feedstock arrangements. For New Entrants and Emerging Players: CE marking fast-track services for small Dutch converters struggling with notified body documentation offer immediate white-space access. Target Luxembourg-based premium pet food brands specifying compostable formats for German and French export channels. A paper-foil hybrid specialization targeting FSC-certified personal care contracts bypasses incumbent foil-dependent barrier relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with multi-year supply agreements to Unilever's Benelux dry grocery operations and Belgian dairy retort pouch accounts. Acquisition candidates with Rotterdam port-adjacent facilities and existing CE marking dossiers present superior five-to-ten-year viability. Watch for inflection when Flemish extended producer responsibility targets trigger forced consolidation among non-compliant mid-tier suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Polymer Extrusion Capacity Expansion | Amcor plc and Huhtamaki Group deployments in Belgium and Netherlands address PPWR recyclability mandates ahead of regulatory deadlines. |
| Design-for-Recycling Certification Program | Dutch converters embedding digital product passports capture Albert Heijn and Jumbo private-label awards through third-party recyclability attestation. |
| Backward Integration into Resin Compounding | Antwerp chemical infrastructure proximity enables captive polypropylene supply shielding against Rhine corridor feedstock volatility. |
| Paper-Foil Hybrid Format Development | Mondi Group kraft-barrier innovations target FSC-certified personal care contracts displacing rigid carton incumbents in Dutch retail channels. |
| Rotterdam Logistics Hub Partnership | Just-in-time delivery contracts with port-based consolidators cut transport emissions for Belgian chocolate and Dutch snack exporters. |
Research Methodology
Operator-level perspectives from flexible packaging plant managers, brand owner procurement leads at Dutch supermarket chains, resin procurement directors, and notified body certification specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EU Packaging and Packaging Waste Regulation implementation documents, REACH substance restriction databases, and Flemish extended producer responsibility reporting. Customs data on polyethylene and polypropylene film imports, alongside converter capacity disclosures from Antwerp and Rotterdam industrial registers, supported bottom-up and top-down triangulation.
Sensitivity analysis around aluminum foil price volatility, CE marking timeline compression, and mono-material adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include pouch format complexity, barrier specification tier, end-use vertical, closure type, and regional covenant compliance status. CAGRs derived from resin demand elasticity, brand owner sustainability scorecard penetration, and mechanical recycling infrastructure deployment curves. Industry-specific inputs incorporated retort sterilization performance requirements and digital product passport adoption rates.
Decision-makers should treat outputs as directional under assumptions of PPWR enforcement consistency and Rhine corridor petrochemical supply stability; material deviation would warrant model refresh. Forecasts embed assumptions regarding Flemish EPR target stringency and Dutch national packaging covenant incentive continuity. Practitioners should keep alternative scenarios live as EU Green Deal packaging recyclability mandates and aluminum oxide barrier substitution economics evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Morocco Pouch Packaging Market
Pouch
Squeeze Pouch Market
Pouch
Ziplock Products Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Aluminum Pouches Market
Pouch
Foam Pouch Market
Pouch
Egypt Pouch Packaging Market
Pouch
Asia-Pacific Retort Pouch Market
Pouch
Clipless Vertical Pouches Market
Pouch
Indonesia Pouch Packaging Market
Pouch
Argentina Pouch Packaging Market
Pouch
Bio PE Pouches Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Germany Pouch Packaging Market
Pouch
Feminine Care Pouch Film Market
Pouch
Digital Printed Pouch Market