
 Center Sealed Pouch Packaging Market | 2026-2036
Center Sealed Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Center Sealed Pouch Packaging Market Outlook
Aftermarket technical service revenue is narrowing as equipment makers bundle retrofit kits with original pouch lines. Amcor leverages backward integration into film extrusion to capture margin that previously flowed to resin converters. Berry Global Group anchors its position through geographic manufacturing density across the Midwest and Southeast United States. Mondi Group specializes in kraft-paper hybrid structures that reduce plastic dependency while preserving seal integrity.
Center sealed pouch packaging consists of flexible bags where the longitudinal seal runs along the geometric center of the pouch face, typically formed from coextruded polyethylene, oriented polypropylene, or aluminum-laminated films through vertical form-fill-seal processes, creating a gusseted or flat configuration for product containment and display. Plastic laminates still dominate material type due to cost-performance ratios in high-speed filling operations, though biodegradable alternatives are gaining traction in European private-label contracts where retailers face extended producer responsibility obligations. Food packaging leads application demand, driven by retortable and aseptic formats for sauces, pet foods, and ready meals, while pharmaceutical packaging commands premium positioning through barrier specifications against moisture and oxygen ingress.
The FDA regulates direct food-contact layers under 21 CFR 177 for polymer safety, while the EPA monitors volatile organic compound emissions from solvent-based adhesive lamination processes that remain prevalent in domestic production. REACH compliance in Europe restricts certain phthalate plasticizers and mandates substance-of-very-high-concern disclosure across multilayer supply chains, effectively filtering non-compliant Asian converters from premium tender pools. Stakeholders must monitor how state-level extended producer responsibility legislation in California and Maine reshapes collection infrastructure economics for flexible packaging recovery.
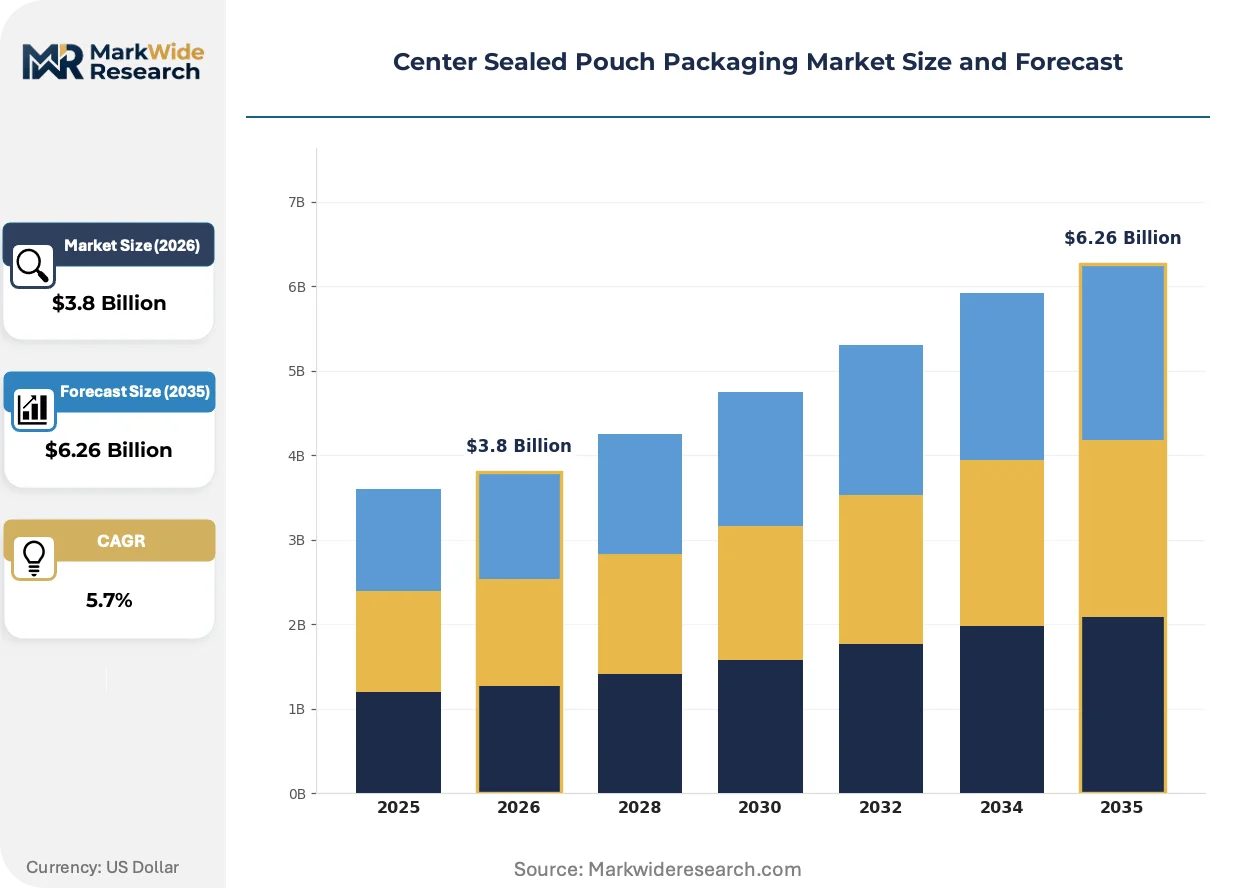
Market Dynamics
EU Packaging and Packaging Waste Regulation recyclability mandates are compressing multilayer film architectures, forcing converters to strip aluminum barriers and reengineer seal layers without sacrificing oxygen transmission performance. This regulatory compression is redrawing material hierarchies across European supply chains.
Growth Catalysts
- Retortable pouch demand:Ready-meal producers in the United States are replacing rigid trays with gusseted center-sealed formats to cut logistics cube and microwave-ready convenience.
- REACH SVHC disclosure:European chemical transparency rules are filtering non-compliant Asian converters from premium tender pools, consolidating qualified supplier bases.
- Barrier coextrusion advances:Five-layer nylon-EVOH structures are displacing metalized films in aseptic soup applications while maintaining 12-month shelf life.
Market Restraints
- Ethylene-vinyl alcohol resin concentration:Japanese and Korean suppliers control 70% of high-barrier EVOH feedstock, exposing converters to freight and currency volatility.
- Mechanical recycling incompatibility:Current multilayer pouch constructions fail near-infrared sortation at materials recovery facilities, blocking circular economy claims.
- Solvent adhesive emissions:EPA volatile organic compound rules are raising compliance costs for domestic lamination plants still using toluene-based systems.
Strategic Opportunities
- German extended producer responsibility:Retailer-led collection infrastructure investments are creating closed-loop feedstock streams for post-consumer recycled content mandates.
- Pharmaceutical unit-dose formats:Moisture-barrier center-sealed pouches for oral dissolving films are penetrating Indian and Brazilian generic drug packaging.
- Kraft-paper hybrid structures:Fiber-based sealant webs combined with thin polymer barriers are capturing European private-label coffee and dried fruit contracts.
Industry Challenges
- High-speed seal integrity:Converters lack technicians trained in ultrasonic and impulse sealing parameter optimization for novel biodegradable substrates.
- Legacy VFFS retrofit costs:Existing vertical form-fill-seal lines require $200,000-$400,000 mechanical upgrades to handle paper-based web tensions without creasing.
- Multilayer delamination testing:No harmonized ISO method exists for quantifying interlayer adhesion after retort sterilization, delaying customer qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Center Sealed Pouch Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Biodegradable, Aluminum, Paper Application: Food Packaging, Pharmaceutical Packaging, Personal Care, Industrial Products Closure Type: Zipper, Resealable, Heat Seal, Adhesive End User: Manufacturers, Retailers, Distributors, Online Sellers |
| Companies Covered | Amcor, Berry Global Group, Mondi Group, Sealed Air Corporation, Smurfit Kappa Group, Winpak Ltd., Constantia Flexibles Group, ProAmpac, Coveris Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Center Sealed Pouch Packaging Market Strategic Shifts
Material science convergence with regulatory chemistry is collapsing traditional barrier-seal tradeoffs, enabling structures that previously required aluminum or metallized polyester to function with polymer-only architectures.
Barrier film technology is hybridizing oxygen scavenger integration directly into sealant layers, eliminating separate sachet inserts. Pet food manufacturers in Germany and the Netherlands are piloting these active packaging formats for omega-3 oil preservation. The technology is hybridizing supply chains by merging converter and additive masterbatch supplier competencies into single-source specifications.
EU F-Gas Regulation phase-down schedules are pressuring cold-chain pouch users to demonstrate reduced refrigeration dependency through improved ambient stability. This industrial consequence is accelerating high-barrier coextrusion investment in Poland and the Czech Republic. Pharmaceutical and probiotic applications are most affected, with manufacturers reformulating moisture specifications to qualify for reduced refrigeration labeling.
Retailers are consolidating flexible packaging procurement through sustainability scorecards that weight recyclability above unit cost. European grocery chains are disintermediating traditional distributor networks to contract directly with film converters holding third-party recycling certifications. This pattern is most visible in France and the United Kingdom, where Tesco and Carrefour have established preferred supplier lists tied to mechanical recycling compatibility testing.
Center Sealed Pouch Packaging Market Segmentation
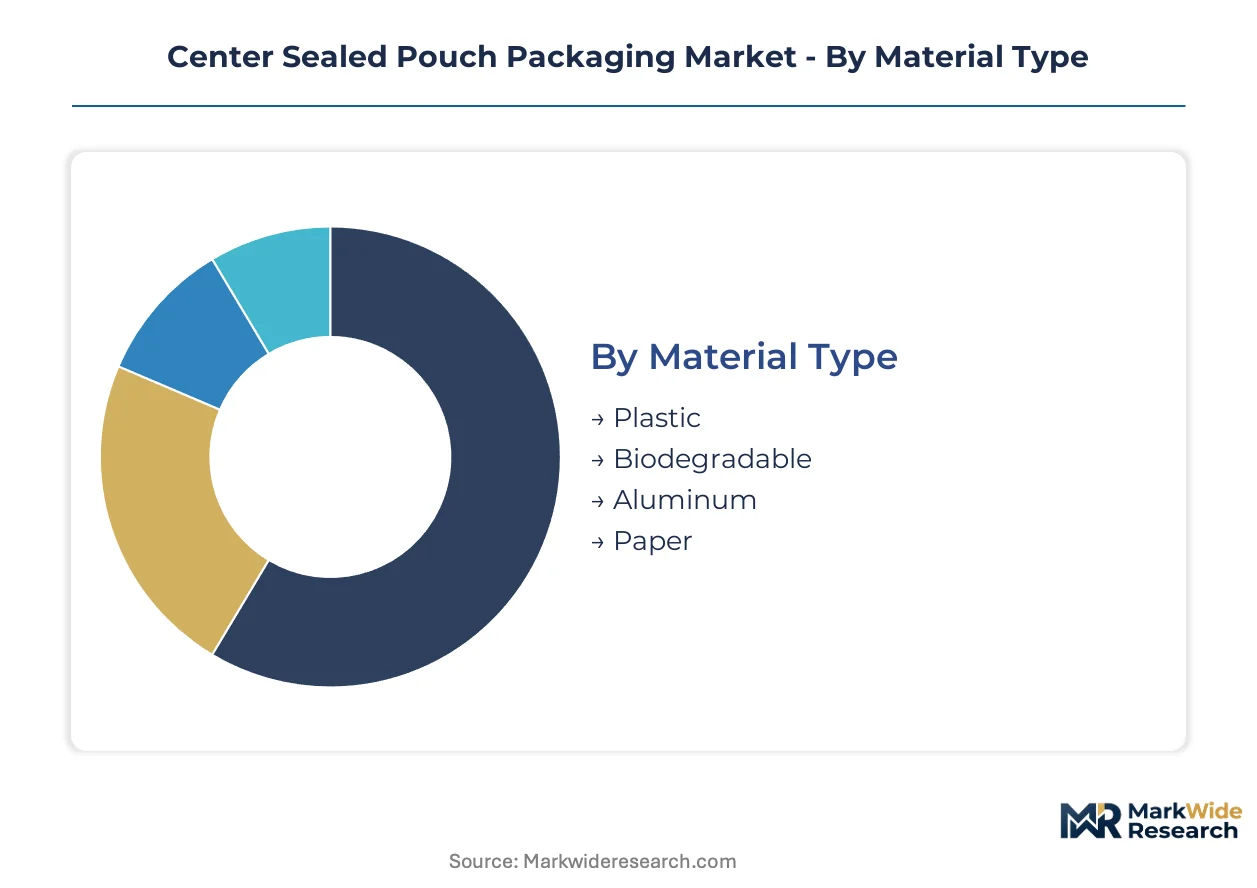
Center sealed pouch packaging exhibits sharp performance divergences across material architectures and end-use specifications. Regulatory chemistry and filling-line speeds create rigid selection criteria that segment purchasing behavior into technically distinct tiers.
Material Type:
Cost-performance ratios across barrier technologies drive procurement stratification from commodity laminates to engineered biodegradables.
- Plastic:Coextruded polyethylene and oriented polypropylene dominate high-speed vertical form-fill-seal operations through seal consistency and optical clarity. North American ready-meal producers favor five-layer nylon-EVOH structures for retortable formats that survive 121°C sterilization cycles.
- Biodegradable:PLA-PBAT blends and starch-based films are penetrating European private-label contracts where extended producer responsibility obligations penalize conventional plastics. German retailers now mandate certified compostable structures for fresh produce and bakery applications.
- Aluminum:Metallized and foil-laminated constructions retain pharmaceutical and premium coffee positioning through near-zero oxygen transmission rates.
- Paper:Kraft-paper hybrid webs with thin polymer sealant layers reduce plastic dependency while preserving machinability on legacy equipment.
Plastic commands the established base. The steepest expansion runs through biodegradable alternatives.
Application:
Functional requirements across containment scenarios create divergent barrier specifications and certification burdens.
- Food Packaging:Retortable and aseptic formats for sauces, pet foods, and ready meals require metalized or coextruded oxygen barriers combined with puncture-resistant sealant webs. US processors are converting rigid tray lines to gusseted pouches to cut logistics cube.
- Pharmaceutical Packaging:Unit-dose moisture barriers for oral dissolving films and probiotic sachets command premium positioning through USP <661> and EP 3.2.2 compliance testing.
- Personal Care:Single-use sample sachets and refill pouches prioritize aesthetic print surfaces and easy-tear notches over extended shelf-life engineering.
- Industrial Products:Chemical-resistant constructions for adhesives, lubricants, and agricultural formulations emphasize seal integrity under stacking load rather than oxygen exclusion.
Food packaging anchors volume throughput. Pharmaceutical applications deliver the highest margin per square meter.
Closure Type:
Consumer convenience expectations and re-use frequency determine mechanical complexity and unit economics.
- Zipper:Press-to-close interlocking profiles add material cost but enable multi-serve consumption patterns in snack and frozen food segments.
- Resealable:Hook-and-loop and adhesive strip systems balance reclosure performance with line speed compatibility for mid-volume converters.
- Heat Seal:Peelable and permanent seal options dominate single-serve pharmaceutical and food portions where tamper evidence outweighs re-use.
- Adhesive:Pressure-sensitive tape closures serve industrial and bulk formats where hermetic integrity is secondary to dispensing control.
Heat seal retains the widest equipment compatibility. Zipper integration is climbing fastest as portion-control marketing intensifies.
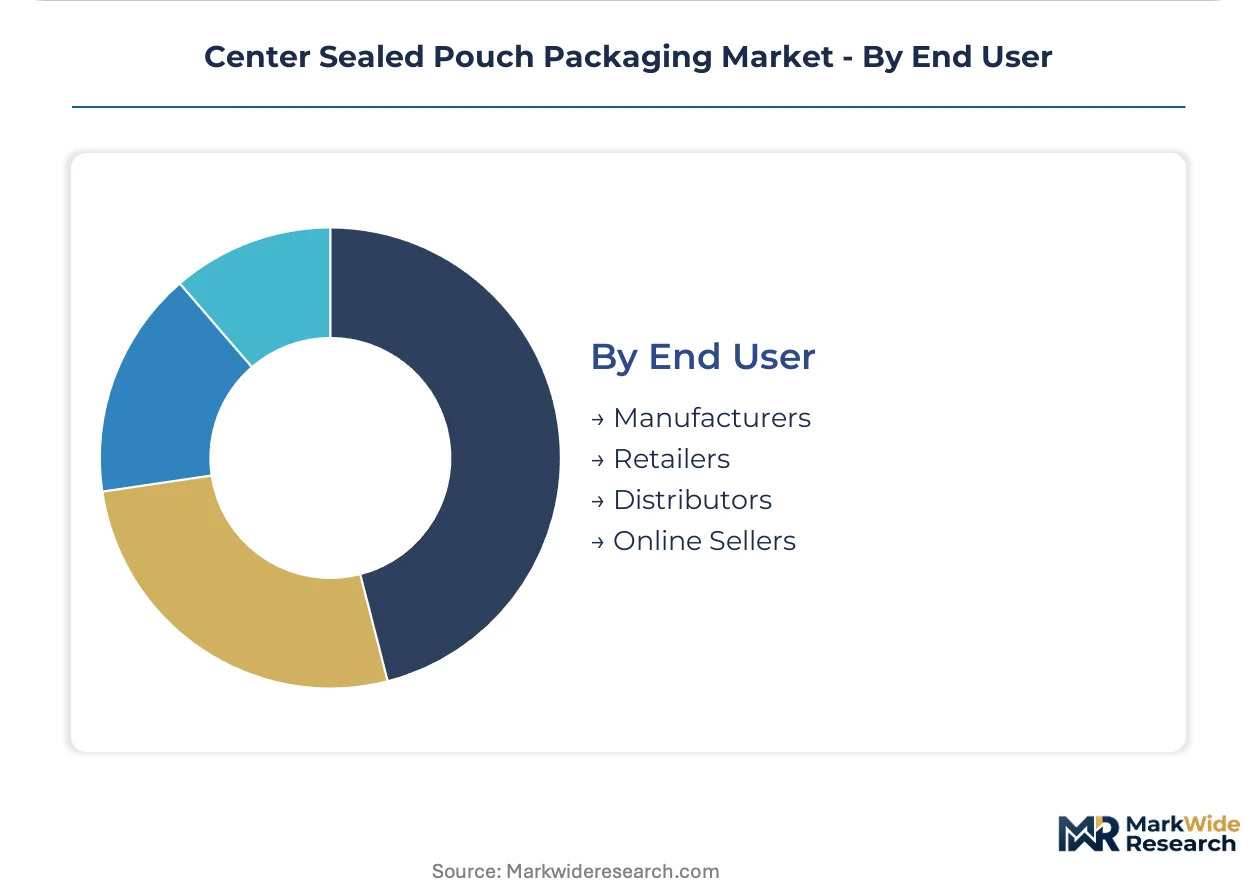
End User:
Purchasing scale and technical specification authority separate direct manufacturers from intermediated channels.
- Manufacturers:CPG and pharmaceutical producers with captive filling operations specify film structures directly, qualifying converters through 12-18 month validation protocols.
- Retailers:European grocery chains are disintermediating distributors to contract film converters holding third-party recycling certifications.
- Distributors:Regional packaging wholesalers stock standard pouch formats for small and mid-sized food processors lacking technical specification staff.
- Online Sellers:E-commerce fulfillment operations prioritize lightweight, damage-resistant formats that minimize dimensional weight shipping penalties.
Manufacturers drive technical innovation requirements. Retailer direct contracting is expanding most quickly in sustainability-mandated procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany tolerate premium pricing for high-barrier certification, while converters in India compete on unit economics for commodity pouch contracts. Demand elasticity varies sharply by end-use sophistication and regulatory compliance burden.
United States
Retortable pouch demand from ready-meal producers is displacing rigid tray formats across Midwest food processing corridors. FDA 21 CFR 177 compliance requirements for direct food-contact polymers filter supplier pools to domestic and qualified foreign converters. Chicago and Minneapolis anchor contract manufacturing clusters where Berry Global Group maintains geographic density advantages.
Germany
Extended producer responsibility legislation is mandating post-consumer recycled content thresholds for flexible packaging tender eligibility. ECHA REACH SVHC disclosure rules exclude non-compliant Asian converters from premium pharmaceutical and organic food supply chains. The Rhine-Ruhr industrial belt concentrates film extrusion and lamination capacity serving pan-European distribution.
China
Domestic pet food brands are adopting center-sealed formats for export-grade packaging to Southeast Asian markets. SAMR food-contact material safety standards are tightening migration testing protocols for multilayer adhesive laminations. The Yangtze River Delta manufacturing corridor hosts vertical form-fill-seal equipment production integrated with local film supply.
India
Generic pharmaceutical exporters are qualifying moisture-barrier pouches for oral dissolving film unit-dose formats to regulated markets. CDSCO packaging material licensing requirements delay converter qualification timelines by 8-14 months. Mumbai-Pune and Ahmedabad industrial zones concentrate domestic flexible packaging conversion for both local and export demand.
Brazil
Processed food manufacturers are converting from rigid to flexible formats to reduce logistics costs in expansive domestic distribution networks. ANVISA pharmaceutical packaging regulations mandate stability testing documentation that favors established converter relationships over price-based procurement. São Paulo state anchors national flexible packaging capacity with integrated resin-to-pouch supply chain configurations.
Center Sealed Pouch Packaging Market Competitive Environment
Capability concentration sits with specialized barrier film developers; scale advantage sits with diversified packaging conglomerates. The market structures around three tiers: integrated resin-to-pouch operators, regional conversion specialists, and equipment-integrated solution providers. Dominant competitive moves include backward integration into film extrusion and geographic manufacturing density expansion to capture logistics-sensitive food processing contracts.
Among Australia-based multinationals, Amcor exemplifies the integrated archetype through captive resin conversion capabilities. Mondi Group anchors the fiber-hybrid specialist tier with kraft-paper barrier structures reducing plastic dependency. Berry Global Group occupies the scale-driven position through Midwest and Southeast United States manufacturing density.
| Leading Market Players |
|---|
| Amcor |
| Berry Global Group |
| Mondi Group |
| Sealed Air Corporation |
| Smurfit Kappa Group |
| Winpak Ltd. |
| Constantia Flexibles Group |
| ProAmpac |
| Coveris Holdings |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Ruhr industrial belt concentrates European film extrusion capacity, and this geographic density grants German converters pricing leverage over buyers seeking REACH-compliant multilayer structures. Downstream food manufacturers absorb premium positioning for high-barrier certification, while Asian competitors face margin compression from extended producer responsibility compliance costs.
Pricing Analysis
Aftermarket technical service revenue drives lifetime value as equipment makers bundle retrofit kits with original pouch lines. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade barrier certification from commodity food-contact laminates. Cost compression in the biodegradable segment is intensifying because German retailers mandate certified compostable structures without volume scale economies. Small and mid-sized food processors lacking technical specification staff exhibit highest price sensitivity, while pharmaceutical manufacturers with captive filling operations prioritize barrier performance over unit cost.
Supply Chain Analysis
Upstream EVOH resin feedstock draws from Japanese and Korean suppliers controlling the majority of high-barrier polymer production. Raw material dependencies center on ethylene-vinyl alcohol copolymers, oriented polypropylene films, and solvent-based adhesive systems. Single-source vulnerability in Asian EVOH supply exposes converters to freight and currency volatility. Distribution runs through vertically integrated resin-to-pouch operators and regional conversion specialists serving logistics-sensitive food processing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Center sealed pouch packaging operates as a substitution defense against rigid container formats, with incumbent flexible film producers navigating displacement pressure from tray-to-pouch conversion trends in ready-meal segments.
For Market Incumbents: Insulate market position through backward integration into film extrusion to capture margin previously flowing to resin converters. Expand geographic manufacturing density across Midwest and Southeast United States to anchor logistics-sensitive food processing contracts. Defend against Asian price competition by leveraging REACH SVHC disclosure compliance as a qualification barrier.
For New Entrants and Emerging Players: Pursue white-space opportunities in pharmaceutical unit-dose moisture barriers for oral dissolving films, where CDSCO and ANVISA documentation requirements delay incumbent qualification timelines. Target Indian and Brazilian generic drug packaging markets with barrier coextrusion capabilities. Lead with certification investment as the go-to-market angle to bypass distributor intermediation.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized barrier film developers with active packaging integration capabilities over commodity laminate converters. Long-term viability hinges on recyclability-compatible material architectures that satisfy EU Packaging and Packaging Waste Regulation mandates. Acquisition target archetype: fiber-hybrid specialists with kraft-paper barrier structures reducing plastic dependency. The signal to monitor is retailer-led sustainability scorecard implementation disintermediating traditional distributor networks.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Amcor captures resin converter margin through captive polyethylene and polypropylene production. |
| Kraft-Paper Hybrid Structure Development | Mondi Group reduces plastic dependency while preserving seal integrity on legacy VFFS equipment. |
| Geographic Manufacturing Density Expansion | Berry Global Group anchors Midwest ready-meal contracts through Chicago and Minneapolis proximity. |
| Active Packaging Integration | Oxygen scavenger sealant layers eliminate sachet inserts for German pet food omega-3 preservation. |
| Third-Party Recycling Certification | European grocery chains contract directly with certified converters bypassing traditional distributors. |
Study Parameters
The analysis maps material type architectures, application specifications, closure type configurations, and end-user procurement channels, each validated through film extrusion plant managers, flexible packaging procurement leads at CPG manufacturers, vertical form-fill-seal equipment engineers, and retail category buyers. Primary interview intelligence triangulates against secondary sources including FDA 21 CFR 177 filings, ECHA REACH SVHC registries, EU Packaging and Packaging Waste Regulation drafts, and customs trade data for multilayer film imports. Bottom-up volume modeling from converter capacity and top-down demand estimation from end-use consumption patterns reconcile through iterative validation.
The forecast framework holds regulatory implementation schedules and resin supply concentration patterns as fixed boundary conditions while varying adoption rates for biodegradable alternatives and pharmaceutical unit-dose formats across the projection horizon. Segmentation dimensions include material barrier technology, end-use certification tier, closure mechanical complexity, and buyer specification authority. CAGRs derive from logistic curve fitting to observed substitution patterns between rigid and flexible formats. Industry-specific inputs encompass retort sterilization cycle requirements and moisture vapor transmission rate specifications for probiotic applications.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Asian converters circumventing REACH compliance would shift outcomes beyond modeled ranges. Cross-checking against EVOH resin import volumes and VFFS equipment order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Twin Pouch Packaging Market
Pouch
Compostable Pouches Market
Pouch
Italy Pouch Packaging Market
Pouch
Kraft Block Bottom Pouch Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Pouch Equipment Market
Pouch
Sterilization Pouches Market
Pouch
Flexible Pouch Market
Pouch
Foam Pouch Market
Pouch
Pillow Pouch Packaging Market
Pouch
Horizontal Premade Pouch Packing Machine Market
Pouch
UAE Pouch Packaging Market
Pouch
Anti-Static Foam Pouch Market
Pouch
Vietnam Pouch Packaging Market
Pouch
Monodose Packs Market
Pouch
Spouted Pouches Market