
 Pouch Equipment Market | 2026-2036
Pouch Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Pouch Equipment Market Analytics
Asset-light leasing and equipment-as-a-service models is rewriting competitive access in pouch equipment, allowing mid-sized converters to deploy high-speed lines without capital-intensive balance sheets. Coesia SpA leverages its integrated automation portfolio to anchor premium positioning across pharmaceutical and food-grade installations. Duravant LLC competes through specialized downstream handling systems that extend line efficiency beyond the forming-sealing station. MULTIVAC Sepp Haggenmüller SE & Co. KG dominates thermoforming-to-pouch hybrid configurations, particularly in vacuum and modified-atmosphere applications.
Pouch equipment encompasses machinery for forming, filling, and sealing flexible pouches from rollstock or pre-made bags, typically operating at speeds from 60 to 400 cycles per minute with seal-bar temperatures calibrated to substrate melting points for hermetic closure. These systems serve food preservation, unit-dose pharmaceuticals, and consumer convenience formats where lightweight packaging reduces logistics cost and shelf-ready presentation drives retail preference. Stand-up pouches and retort pouches lead value contribution due to premium positioning in ready-meal and baby-food segments, while vacuum pouch equipment sustains above-average margins in protein packaging where barrier integrity commands specification rigor. Flat pouches remain the volume base for commodity snacks and single-serve condiments, though margin compression from Asian OEM competition limits profitability for European and North American incumbents in this tier.
FDA validation protocols for pharmaceutical contact materials and EU MDR traceability requirements shape equipment specification in regulated end-uses, compelling OEMs to integrate vision inspection and serialization modules as standard rather than optional configurations. EFSA migration limits and REACH substance restrictions on adhesives and coatings filter through to equipment design, particularly seal-bar surface treatments and ink-circulation systems in printed pouch lines. Stakeholders must monitor how ECHA proposals on intentionally added microplastics and emerging state-level extended producer responsibility laws in the United States recalibrate substrate roadmaps and therefore equipment compatibility requirements.
Market Dynamics
Extended producer responsibility mandates across the European Union and Southeast Asia are forcing pouch equipment buyers to reconfigure substrate roadmaps, compelling capital deployment toward mono-material polyethylene-compatible lines before legacy assets fully depreciate.
Growth Catalysts
- EMA Serialization Mandates:European pharmaceutical contract manufacturers are retrofitting pouch lines with integrated vision inspection and track-and-trace modules to comply with unit-dose authentication requirements.
- India CDSCO Traceability Rules:Domestic pharma packagers are replacing aging form-fill-seal assets with flexible equipment capable of handling serialization-ready substrates at commercial speeds.
- Mono-Material Polyethylene Transition:Recyclable substrate formats are gaining equipment specification priority as ECHA proposals on intentionally added microplastics tighten material compliance windows.
Market Restraints
- Stainless Steel Input Volatility:Seal-bar assemblies and frame construction face margin pressure from nickel and chromium price swings, compressing OEM profitability on mid-tier equipment.
- Asian OEM Supply Concentration:Flat pouch equipment sourcing clusters in Chinese and Taiwanese manufacturing bases, exposing European and North American buyers to extended lead times and tariff exposure.
- Hermetic Seal Integrity Limits:High-barrier retort applications remain technically constrained by polyethylene's oxygen transmission rates versus legacy multi-layer structures.
Strategic Opportunities
- Vietnam Food Processing Expansion:Export-oriented seafood and ready-meal processors are installing vacuum and modified-atmosphere pouch capacity to serve EU and US retail channels.
- Equipment-as-a-Service Models:Asset-light leasing structures are unlocking mid-sized converter access to high-speed lines without capital-intensive balance sheet deployment.
- EU Green Deal Packaging Revisions:Pending recyclability quotas and recycled content mandates are creating specification pull for thermoforming-to-pouch hybrid configurations.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:OEMs lack sufficient computational fluid dynamics and heat-transfer specialists to optimize seal-bar profiles for novel mono-material substrates.
- FDA Validation Timeline Compression:Pharmaceutical contact material qualification protocols are extending from 18 to 30 months as FDA intensifies documentation requirements for thermal processing equipment.
- Legacy Line Integration Friction:Brownfield sites struggle to synchronize new recyclable-substrate pouch equipment with existing downstream cartoning and case-packing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pouch Equipment Market |
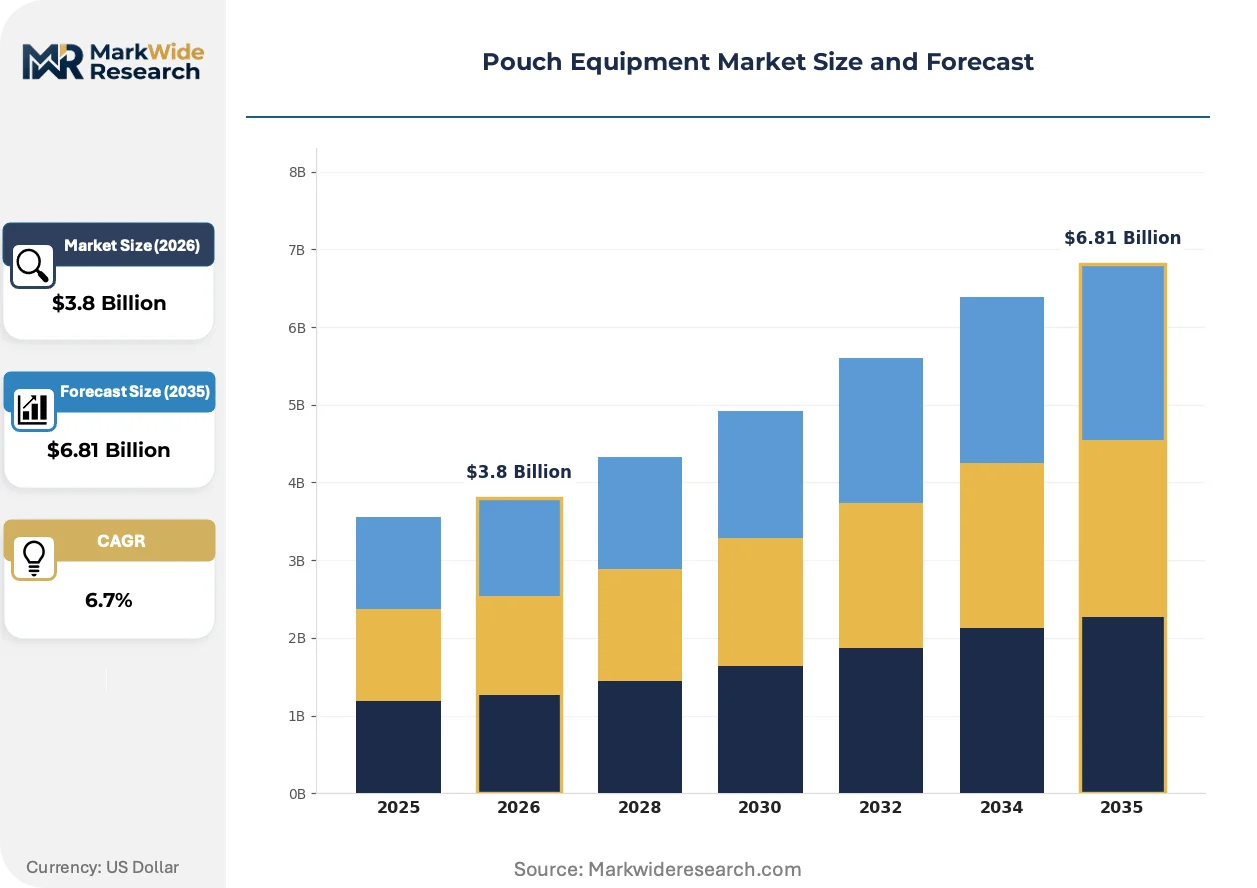
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Pouches, Retort Pouches, Vacuum Pouches Material: Plastic, Paper, Foil, Composites Application: Food Packaging, Medical Packaging, Consumer Goods, Industrial Products End User: Food & Beverage, Healthcare, Personal Care, Home Care |
| Companies Covered | Coesia SpA, Massman Automation Design, LLC, PFM Packaging Machinery, Volpak, VELTEKO CZ sro, Barry-Wehmiller Group Inc., Duravant LLC, GEA Group Aktiengesellschaft, MULTIVAC Sepp Haggenmüller SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pouch Equipment Market Evolving Landscape
Digital thread integration across design, production, and aftermarket service is compressing equipment development cycles and reshaping how OEMs capture lifetime value from installed base relationships.
Machine learning-based predictive maintenance is digitizing service revenue models for pouch equipment OEMs. Food processors in Germany and pharmaceutical packagers in Switzerland are piloting sensor-integrated lines that transmit seal-bar temperature variance and vibration signatures to cloud analytics platforms. This capability is digitizing the traditional break-fix aftermarket into continuous uptime contracts that lock in multi-year customer relationships.
REACH substance restrictions on adhesives and coatings are filtering through to equipment design specifications. ECHA migration limits now govern seal-bar surface treatments and ink-circulation systems in printed pouch lines, compelling OEMs to qualify alternative plasma coatings and ceramic barrier layers. Protein packaging applications in vacuum pouch formats face the tightest compliance windows, driving accelerated qualification timelines for barrier-integrity testing protocols.
Buyer preference is consolidating around single-source accountability for full-line performance. Mid-sized converters in India and Vietnam are rejecting fragmented procurement of forming, filling, and downstream handling equipment, instead favoring integrated system suppliers who guarantee overall equipment effectiveness metrics. This behavioral shift favors OEMs with captive automation portfolios and compresses margins for specialized component vendors who lack system-level validation capabilities.
Pouch Equipment Market Segmentation
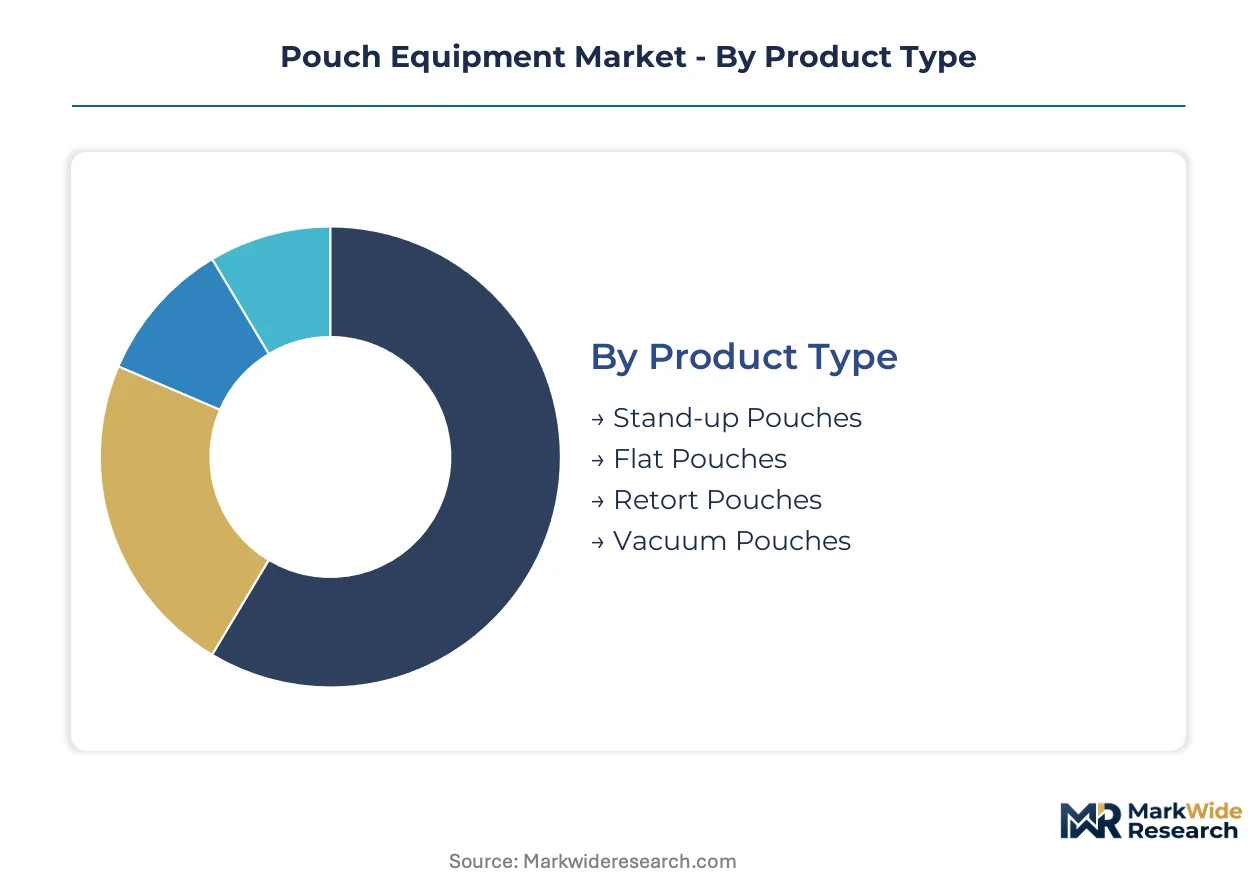
Pouch equipment purchasing cycles vary dramatically across substrate formats and end-use rigor. Pharmaceutical serialization mandates in Germany and India accelerate replacement timelines for medical-grade lines, while commodity snack packaging in Vietnam operates on extended depreciation schedules.
Product Type:
Cycle times diverge sharply: vacuum and retort equipment turn over every 7-9 years due to barrier-integrity degradation, while flat pouch lines often exceed 12-year lifespans in cost-sensitive Asian markets.
- Stand-up Pouches:These formats integrate gusseted bottom structures enabling shelf-stable vertical display. German ready-meal processors and U.S. baby-food manufacturers specify these lines for premium retail positioning, though seal-bar calibration for multi-layer substrates extends commissioning timelines.
- Flat Pouches:Horizontal form-fill-seal configurations dominate high-volume snack and condiment production. Indian spice packagers and Vietnamese instant-noodle manufacturers favor these assets for throughput economics, though margin compression from Chinese OEM competition limits supplier profitability in this tier.
- Retort Pouches:Thermal processing compatibility requires specialized seal-bar alloys and pressure-rated chamber designs. Thai seafood exporters and Italian ready-meal producers invest here for extended shelf-life applications.
- Vacuum Pouches:Modified-atmosphere capabilities sustain above-average equipment margins. Brazilian beef processors and Dutch cheese packagers prioritize barrier-integrity specifications.
Flat pouches dominate installed base. Stand-up pouch configurations are where expansion concentrates.
Material:
Cost tiers stratify sharply: foil and composite substrates command 40-60% equipment price premiums over standard polyethylene configurations, reflecting seal-bar precision and contamination-control requirements.
- Plastic:Mono-material polyethylene formats are capturing specification priority as ECHA microplastic proposals and EU extended producer responsibility frameworks tighten compliance windows. German pharmaceutical contract manufacturers and Vietnamese food exporters are retrofitting lines for recyclable substrate handling.
- Paper:Fiber-based barrier coatings require specialized moisture-control modules and modified seal-bar surface treatments. Swedish confectionery packagers and French dry-goods manufacturers pilot these formats for fiber-transition commitments.
- Foil:Aluminum-laminate structures sustain demand in pharmaceutical unit-dose and high-barrier food applications. Swissmedic validation protocols and FDA contact-material requirements govern equipment qualification timelines.
- Composites:Multi-layer structures face regulatory headwinds as recyclability mandates intensify. Legacy installed base in Italian coffee packaging and Japanese retort applications resists premature replacement despite substrate compliance pressures.
Plastic equipment commands the broadest installed base. Paper-compatible lines are gaining share fastest among sustainability-committed converters.
Application:
Volume concentration versus margin extraction varies: food packaging generates equipment throughput but compresses pricing power, while medical applications sustain premium positioning through validation-intensive procurement.
- Food Packaging:Modified-atmosphere and vacuum configurations serve protein, produce, and ready-meal segments. EFSA migration limits and national food safety authorities in Germany, India, and Brazil shape seal-bar material specifications.
- Medical Packaging:Unit-dose pharmaceutical pouches require integrated vision inspection and serialization modules. EMA mandates in Europe and CDSCO traceability rules in India are accelerating line replacement cycles.
- Consumer Goods:Convenience formats for cosmetics and household products prioritize shelf-ready presentation. Southeast Asian personal care manufacturers favor compact footprint equipment for urban production constraints.
- Industrial Products:Chemical and agricultural chemical pouches emphasize containment integrity over speed. Brazilian fertilizer packagers and Indian pesticide manufacturers specify heavy-duty seal-bar configurations.
Food packaging anchors equipment volume. Medical packaging is where specification premiums concentrate most intensely.
End User:
Customer type determines financing structure: multinational food and beverage corporations favor equipment-as-a-service arrangements, while mid-sized healthcare packagers prefer traditional capital purchase with extended validation support.
- Food & Beverage:Category-spanning demand from dairy, beverage, and prepared foods segments. German dairy cooperatives and Indian spice conglomerates represent distinct procurement profiles—automation integration versus cost-optimized standalone lines.
- Healthcare:Pharmaceutical and medical device packaging demands FDA-validated thermal processing equipment. Swiss and German contract manufacturers lead specification stringency for aseptic pouch formats.
- Personal Care:Cosmetic and hygiene product packagers prioritize format flexibility for SKU proliferation. Vietnamese and Indonesian manufacturers emphasize rapid changeover capabilities.
- Home Care:Detergent and cleaning product applications favor chemical-resistant seal-bar coatings. Brazilian and Mexican converters specify corrosion-protected equipment for alkaline product contact.
Food & beverage holds the deepest installed base. Healthcare represents the steepest expansion trajectory for premium-configured equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented food processors in Vietnam and Thailand are importing European-built vacuum pouch lines to serve EU retail channels, while German pharmaceutical contract manufacturers supply serialization-ready equipment to Indian packagers under technology transfer arrangements.
Germany
EMA serialization mandates are accelerating replacement cycles for pharmaceutical pouch lines. The country's national pharmaceutical regulator enforces unit-dose authentication requirements that demand integrated vision inspection modules. Bavarian automation clusters around Augsburg and Munich host OEMs developing thermoforming-to-pouch hybrid configurations for medical-grade applications.
India
CDSCO traceability rules are compelling domestic pharma packagers to retire aging form-fill-seal assets. The national pharmaceutical regulator mandates serialization-ready substrate handling at commercial speeds. Maharashtra's pharmaceutical manufacturing belt around Mumbai and Pune is retrofitting flexible equipment lines to meet export compliance windows.
Vietnam
Seafood and ready-meal processors are installing vacuum and modified-atmosphere capacity for EU and US retail channels. The country's food safety authority enforces migration limits aligned with EFSA standards for export eligibility. Ho Chi Minh City industrial zones concentrate new pouch-line deployments serving European supermarket private-label contracts.
United States
FDA validation protocols for pharmaceutical contact materials are extending equipment qualification timelines. The national pharmaceutical regulator intensifies documentation requirements for thermal processing equipment. Wisconsin and Illinois dairy cooperatives are adopting stand-up pouch formats for premium retail positioning in ready-meal segments.
Switzerland
Swissmedic validation protocols sustain premium equipment specification for aseptic pouch formats. The national pharmaceutical regulator governs barrier-integrity testing with stringent compliance windows. Basel-area contract manufacturers anchor demand for thermoforming lines serving unit-dose pharmaceutical exports.
Pouch Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around integrated automation portfolios that span forming, filling, and downstream handling functions. Three strategic archetypes dominate: European precision-engineering specialists with pharmaceutical validation capabilities, North American diversified machinery conglomerates with food-grade scale positions, and Asian cost-optimized fabricators serving commodity flat-pouch demand. M&A activity concentrates on acquiring downstream handling expertise, while capacity expansion focuses on mono-material polyethylene-compatible seal-bar configurations.
Among European precision-engineering specialists, Coesia SpA and MULTIVAC Sepp Haggenmüller SE & Co. KG occupy positions anchored in pharmaceutical and food-grade validation capabilities. Duravant LLC represents the North American diversified machinery archetype with specialized downstream handling systems. These three exemplify how supply-side concentration is shifting toward single-source accountability for full-line performance metrics.
| Leading Market Players |
|---|
| Coesia SpA |
| Massman Automation Design, LLC |
| PFM Packaging Machinery |
| Volpak |
| VELTEKO CZ sro |
| Barry-Wehmiller Group Inc. |
| Duravant LLC |
| GEA Group Aktiengesellschaft |
| MULTIVAC Sepp Haggenmüller SE & Co. KG |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese flat-pouch equipment fabrication is compressing margin realization for European and North American OEMs, forcing tier-1 suppliers toward subscription-based service models and away from transactional hardware sales. German pharmaceutical contract manufacturers and Vietnamese seafood processors now wield procurement leverage that reshapes how seal-bar assemblies and control systems are priced and delivered.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Pharmaceutical validation tiers and FDA contact-material certification drive 40-60% price premiums for medical-grade configurations versus food-grade equivalents. Cost compression in flat-pouch commodity equipment is intensifying because Chinese fabricators absorb margin to maintain utilization. Mid-sized Asian converters exhibit highest price sensitivity; Swiss and German pharma packagers prioritize barrier-integrity specifications over unit economics.
Supply Chain Analysis
Contract-manufacturing concentration for seal-bar assemblies and servo-drive modules clusters in Germany, China, and Taiwan. Stainless steel feedstock draws from nickel and chromium suppliers facing ECHA substance scrutiny. Single-source vulnerability persists in high-precision thermoforming dies sourced from Bavarian toolmakers. Distribution runs through OEM direct-sales organizations in regulated end-uses and third-party machinery distributors in commodity segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Computational fluid dynamics specialists capable of optimizing seal-bar thermal profiles for novel mono-material substrates remain scarce across the supplier base, constraining how quickly OEMs can respond to ECHA microplastic compliance windows.
For Market Incumbents: Entrench pharmaceutical validation capabilities through captive qualification protocols that extend FDA timeline support to customer sites. Deepen upstream control over ceramic barrier coating formulations to offset REACH substance restrictions on legacy seal-bar treatments. Asian cost-optimized entrants threaten margin position in flat-pouch tiers; defend through equipment-as-a-service bundling that locks in multi-year aftermarket relationships. For New Entrants and Emerging Players: Pursue paper-compatible pouch equipment for Swedish and French fiber-transition commitments where incumbent qualification lags substrate innovation. Vietnam's seafood export sector offers penetrable white-space for vacuum-line specialists lacking pharmaceutical validation overhead. Lead with rapid commissioning capabilities and localized spare-part warehousing rather than premium positioning. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-as-a-service sub-segments as leasing structures displace balance-sheet purchases. Long-term viability favors OEMs with installed-base density sufficient to sustain recurring revenue streams. Target acquisition archetypes: downstream handling specialists with cartoning and case-packing integration expertise. Monitor CDSCO traceability enforcement intensity in Maharashtra as inflection indicator for Indian pharma capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Model Expansion | Asset-light structures unlock mid-sized converter access to high-speed lines without capital deployment. |
| Mono-Material Polyethylene Line Retrofit | EMA and CDSCO serialization mandates accelerate replacement cycles for recyclable-substrate handling. |
| Downstream Handling Integration | Cartoning and case-packing synchronization addresses brownfield legacy-line friction in European dairy. |
| Predictive Maintenance Platform Deployment | Cloud analytics digitize break-fix aftermarket into continuous uptime contracts for German food processors. |
| Thermoforming-to-Pouch Hybrid Configuration | EU Green Deal recyclability quotas create specification pull for medical-grade barrier applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers at German dairy cooperatives, procurement leads at Indian pharmaceutical contract manufacturers, aftermarket service heads at European OEMs, and technical directors at Vietnamese seafood processors. Secondary validation drew from FDA 483 inspection observations, EMA serialization guidance documents, CDSCO traceability circulars, and customs records of pouch-line imports into Ho Chi Minh City industrial zones. Bottom-up equipment shipment tallies were cross-referenced against top-down pharmaceutical and food packaging capex disclosures to establish triangulated baseline estimates.
Calibration against historical replacement cycles for vacuum, retort, and flat-pouch configurations informed annual progression assumptions across the analysis window. Segmentation dimensions modeled include pouch format type, substrate material compatibility, end-use application rigor, and customer financing preference. CAGRs were derived from slope-intercept regression on normalized shipment values, with specific adjustment for EMA mandate acceleration effects and Chinese OEM penetration trajectories in commodity tiers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by private-equity-backed consolidation platforms or state-subsidized Chinese fabricators would shift outcomes beyond modeled ranges. Quarterly review of CDSCO enforcement intensity, ECHA microplastic proposal advancement, and nickel futures volatility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
UAE Pouch Packaging Market
Pouch
Bio PE Pouches Market
Pouch
Morocco Pouch Packaging Market
Pouch
Aluminium Bags and Pouches Market
Pouch
Argentina Pouch Packaging Market
Pouch
High-Barrier Pouches Market
Pouch
Global Pre Zippered Pouches Market
Pouch
Vented Stretch Wrap Market
Pouch
Flat Bottom Pouch Market
Pouch
Global Anti Static Bubble Pouch Market
Pouch
Open Mouth Sacks Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market
Pouch
Spain Pouch Packaging Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Slider Zipper Pouch Market
Pouch
Compostable Pouches Market