
 Feminine Care Pouch Film Market | 2026-2036
Feminine Care Pouch Film Market Size, Share, and Industry Trends Forecast 2026-2036
Feminine Care Pouch Film Market Foresight
Indonesia is narrowing the supply gap for feminine care pouch films through new blown-film extrusion lines serving regional hygiene product makers. Amcor PLC leverages its multi-layer coextrusion expertise to supply barrier-grade films across Southeast Asian converting operations. Mondi sustains a competitive edge through integrated kraft paper and film laminates tailored for sustainable pouch formats. Berry Global Inc. anchors North American supply with in-house resin compounding and pouch converting capabilities.
Feminine care pouch film denotes a multi-layer flexible packaging substrate, typically 60–150 microns in thickness, combining polyethylene sealant layers with oriented polypropylene or PET outer plies to achieve moisture vapor transmission rates below 1 g/m²/day. This engineered structure preserves product integrity for sanitary napkins and panty liners throughout distribution cycles. Flat pouches dominate unit volume due to their compatibility with high-speed form-fill-seal lines and minimal material usage per unit. Biodegradable plastics represent the fastest-expanding material category as converters respond to retailer sustainability mandates, though polyethylene retains margin concentration through scale economies and established recycling streams.
The EU Packaging and Packaging Waste Regulation and REACH compliance requirements are reshaping material specifications, restricting certain phthalate plasticizers and mandating recyclability assessments for hygiene packaging placed on European markets. The US FDA maintains indirect food-contact standards that extend to fragrance and lotion-infused feminine care products, influencing adhesive and ink selections for pouch films. Stakeholders must monitor evolving extended producer responsibility frameworks and bio-based content thresholds to align procurement strategies with compliance trajectories.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing lead times for material qualification, forcing converters to pre-validate alternative substrates before existing stocks deplete. Southeast Asian hygiene brands are scaling local pouch film orders faster than regional extrusion capacity expands, tightening supply responsiveness.
Growth Catalysts
- REACH compliance mandates:European ECHA restrictions on phthalate plasticizers are accelerating migration to bio-based sealant formulations across hygiene packaging supply chains.
- Indonesia domestic production scaling:Local feminine hygiene brands in Jakarta and Surabaya are tripling blown-film orders to replace imported pouch substrates.
- High-barrier coextrusion advances:Five-layer film structures achieving sub-1 g/m²/day moisture transmission rates are displacing conventional laminated formats in premium sanitary pad lines.
Market Restraints
- Ethylene feedstock volatility:Polyethylene resin costs swing with naphtha-cracker margins in Singapore and South Korea, squeezing converter profitability on fixed-price annual contracts.
- Monopolized masterbatch supply:Colorant and additive concentrates for hygiene-grade films concentrate among three German and Japanese chemical suppliers, creating single-source vulnerability.
- Mechanical recycling incompatibility:Multi-layer barrier films containing EVOH or metallized layers resist conventional reprocessing, limiting circular economy claims under EU Green Deal packaging rules.
Strategic Opportunities
- Vietnam central coast manufacturing:Underpenetrated converting capacity around Da Nang offers lower labor and logistics costs versus Ho Chi Minh City for export-oriented hygiene brands.
- Extended producer responsibility frameworks:France's Citeo and Germany's Der Grüne Punkt systems are creating funded collection infrastructure that rewards recyclable mono-material pouch designs.
- Digital printing convergence:UV-inkjet systems paired with corona-treated PE films enable lot-size-one customization for direct-to-consumer feminine care subscription channels.
Industry Challenges
- Multi-layer extrusion technician scarcity:Operating blown-film lines with seven or more layers requires specialized rheology knowledge that training programs in Indonesia and Vietnam have not yet scaled.
- Migration testing timelines:FDA indirect food-contact validation for fragrance-infused pouch films extends 18-24 months, delaying product launches for lotion-embedded sanitary pad formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feminine Care Pouch Film Market |
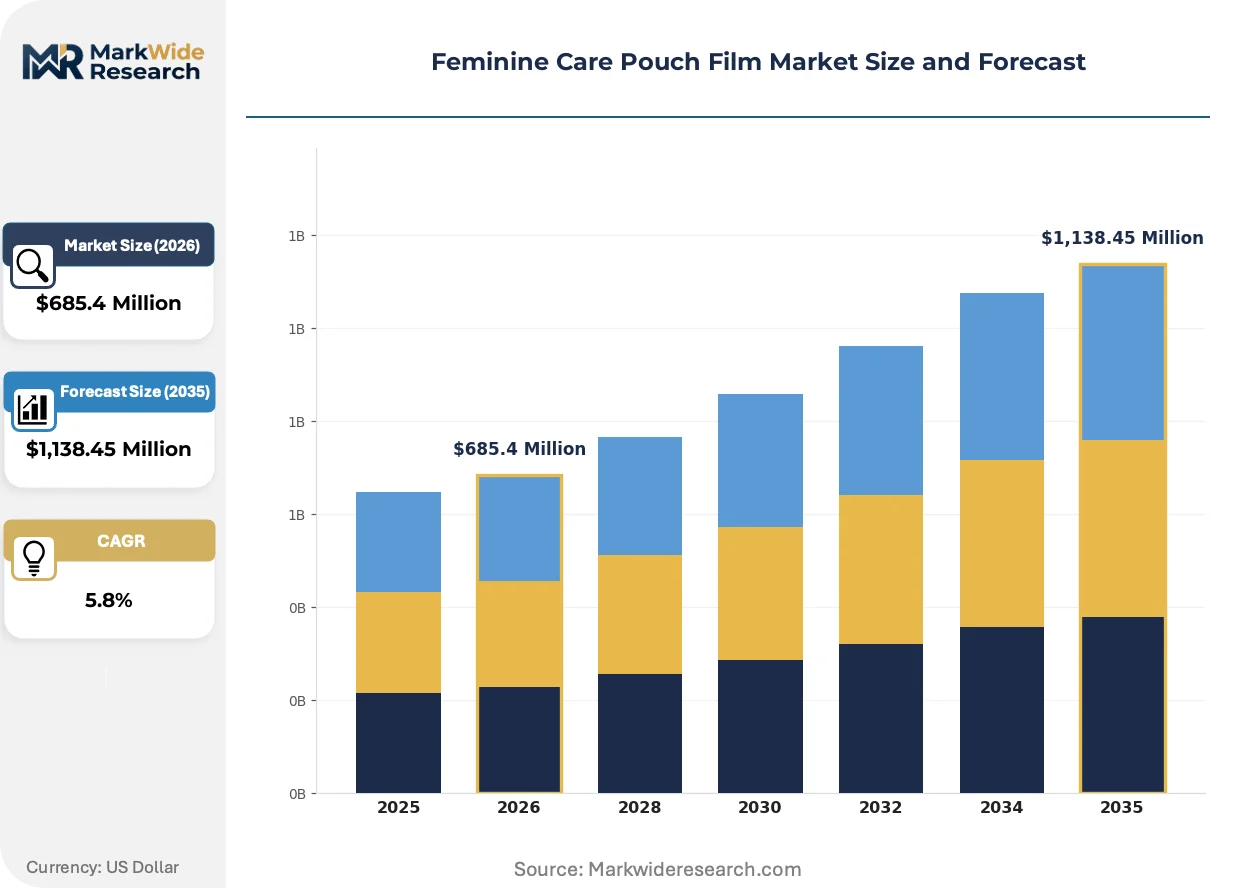
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Zipper Pouches, Resealable Pouches Material: Polyethylene, Polypropylene, PET, Biodegradable Plastics End User: Retail Stores, Online Retailers, Supermarkets, Pharmacies Packaging Type: Single-Use, Multi-Pack, Bulk Packaging, Recyclable Packaging |
| Companies Covered | Amcor PLC, Mondi, WestRock Company, Tetra Pak International S.A., Smurfit Kappa, Berry Global Inc., Huhtamaki, Bemis Manufacturing Company, ProAmpac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feminine Care Pouch Film Market Shifts & Advancements
Material science advances and regulatory compression are converging to redefine performance specifications for feminine care packaging. Converters must now engineer barrier properties using substrates that satisfy both functional requirements and emerging sustainability protocols.
Barrier-grade bio-polyethylene derived from sugarcane ethanol is hybridizing with conventional fossil-based PE in coextrusion lines, allowing brands to claim renewable content without sacrificing heat-seal integrity. Premium hygiene manufacturers in Brazil and Thailand are adopting these hybrid structures at pilot scale. The technology is hybridizing cost structures, creating tiered material specifications that separate mass-market from certified-sustainable product lines.
REACH Annex XVII restrictions on intentionally added microplastics are compelling ink reformulation across European converting operations. Industrial consequence includes accelerated qualification of water-based flexographic systems that previously failed abrasion-resistance benchmarks for high-speed filling lines. Sanitary pad pouch films with direct food-contact claims face the steepest compliance burden, with German converters leading migration-testing protocol development.
Brand procurement teams are consolidating supplier panels from twelve-plus vendors to four preferred extrusion partners capable of integrated film-to-pouch conversion. Direct material sourcing from resin producers is displacing distributor intermediaries for volume accounts above ten million annual units. This concentration is most visible in Indonesia, where domestic hygiene brands now negotiate masterbatch and film specifications in unified tenders rather than sequential purchasing stages.
Feminine Care Pouch Film Market Segmentation
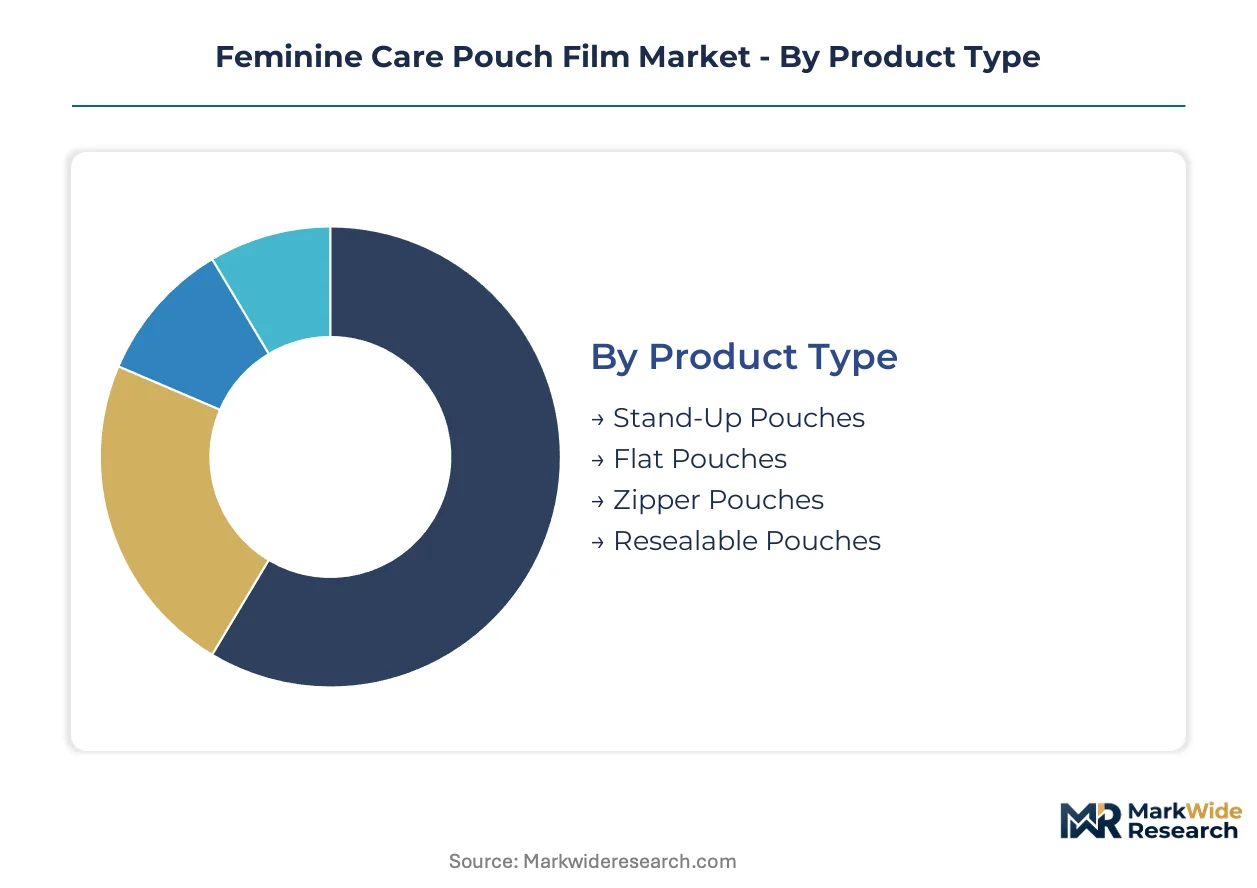
Feminine care pouch film segmentation reveals how converters balance barrier performance with sustainability mandates across distinct supply chain tiers. Each dimension—product format, substrate chemistry, distribution channel, and pack configuration—carries different technical service requirements and qualification timelines.
Product Type:
After-sales service intensity varies sharply by pouch architecture, with complex formats demanding dedicated technical support for line integration and seal optimization.
- Flat Pouches:These two-dimensional structures with heat-sealed edges dominate high-speed form-fill-seal operations due to minimal material usage and rapid cycle times. Indonesian and Vietnamese converters prioritize flat pouch films for domestic sanitary pad lines where equipment automation rates lag European benchmarks. Demand concentrates among mass-market hygiene brands optimizing per-unit packaging economics.
- Stand-Up Pouches:Gusseted bottom configurations with enhanced shelf presence require stiffer outer plies and precise crease engineering to maintain vertical stability. Premium feminine care brands in Thailand and Brazil specify stand-up formats for retail differentiation, though the segment demands longer lead times for die-cut tooling and seal-strength validation.
- Zipper Pouches:Integral slider or press-to-close mechanisms add 15-25 microns to overall film thickness and require compatible sealant layer chemistry. Pharmacy channels in Germany and France favor zipper formats for panty liner multi-packs where reclosure preserves product hygiene.
- Resealable Pouches:Adhesive strip or hook-and-loop closure systems balance convenience with material efficiency for mid-tier product positioning. Korean hygiene manufacturers specify resealable films for subscription-box formats targeting direct-to-consumer channels.
Flat pouches hold the largest share; momentum sits with stand-up configurations as premium positioning gains traction in Southeast Asian retail.
Material:
Cost tier stratification separates commodity resin formulations from certified-sustainable substrates commanding technical qualification premiums.
- Polyethylene:Linear low-density and metallocene catalyzed PE sealant layers provide heat-seal initiation temperatures below 110°C for high-speed converting. Indonesian blown-film extruders scale LLDPE capacity fastest to serve domestic hygiene brand procurement consolidation. The resin category benefits from established mechanical recycling streams under EU Packaging and Packaging Waste Regulation frameworks.
- Biodegradable Plastics:PLA and PBAT blends certified to EN 13432 industrial composting standards are displacing conventional films in European pharmacy channels where ECHA REACH restrictions on persistent microplastics apply. Brazilian sugarcane-derived bio-PE hybrid structures allow renewable content claims without seal-strength degradation. Converters face 18-24 month qualification timelines for fragrance-infused variants under FDA indirect food-contact protocols.
- Polypropylene:Oriented PP outer plies deliver stiffness and moisture barrier performance in multi-layer laminates. Japanese hygiene manufacturers specify biaxially oriented PP for premium panty liner formats requiring crinkle resistance.
- PET:Metallized or clear PET layers provide ultra-high barrier for lotion-embedded products in climates with extreme humidity variation. Thai converters source PET films primarily for export-oriented brands targeting Middle Eastern markets.
Polyethylene dominates volume; biodegradable alternatives are climbing the fastest as retailer sustainability mandates harden.
End User:
Customer type dictates order fragmentation, with modern trade channels consolidating specifications while digital channels demand lot-size-one flexibility.
- Supermarkets:High-volume accounts with centralized procurement and standardized film specifications across private-label and branded portfolios. Indonesian supermarket chains now negotiate direct film supply bypassing distributor intermediaries.
- Online Retailers:E-commerce platforms require pouch films optimized for individual ship-unit durability and printed variable data for subscription personalization. UV-inkjet compatible corona-treated PE films enable lot-size-one customization.
- Retail Stores:Traditional trade channels in Vietnam and Philippines prioritize lowest unit cost over technical sophistication, sourcing standard flat pouch films through regional converters.
- Pharmacies:Regulated channels in Germany and France demand full migration testing documentation and EMA-aligned material safety data for fragrance-infused products.
Supermarkets anchor volume concentration; online retailers are expanding most quickly as direct-to-consumer feminine care subscriptions scale.
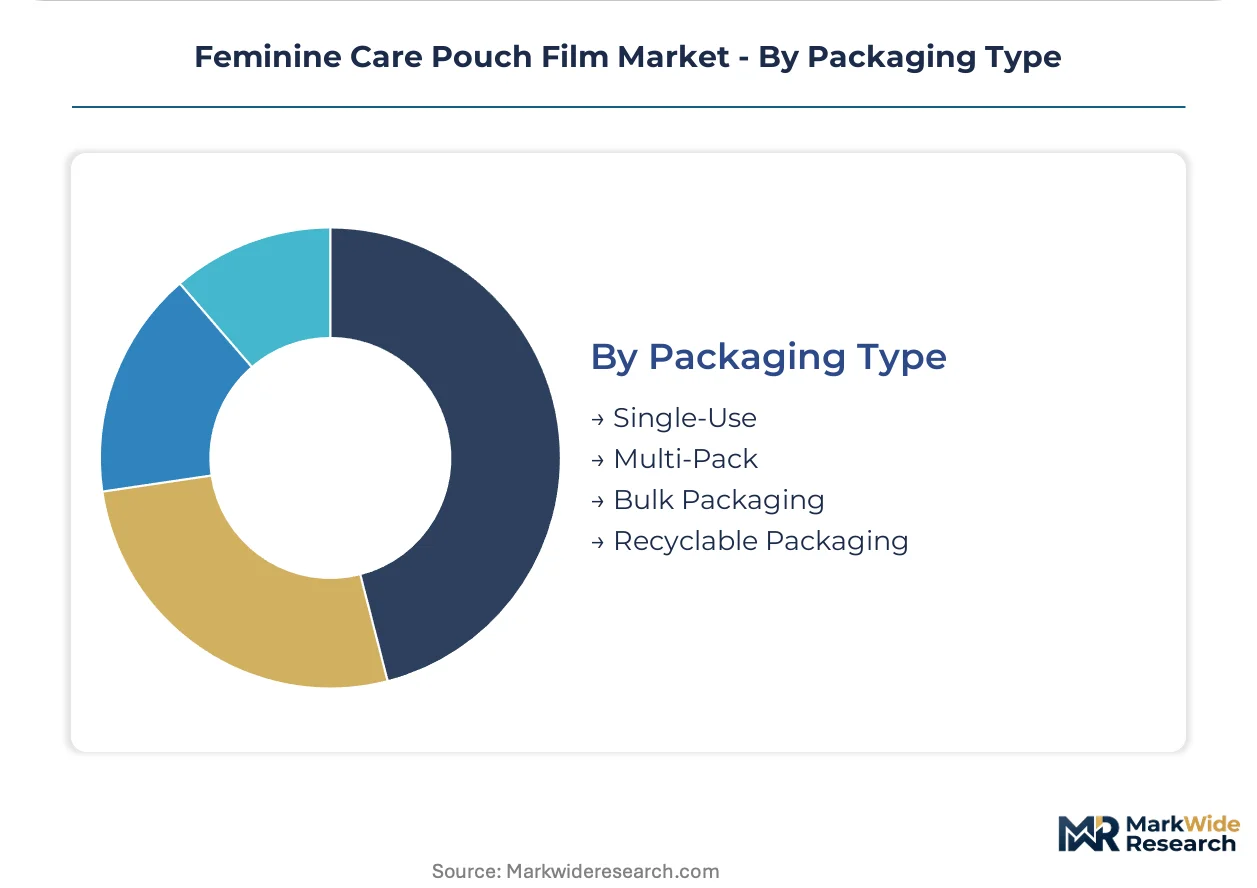
Packaging Type:
Volume scale separates mass-market configurations from specialty formats, with recyclability certification emerging as a procurement gate.
- Single-Use:Individual sanitary pad pouches for away-from-home consumption require ultra-thin film structures below 80 microns. Mass-market brands in Indonesia specify single-use formats for sachet-priced accessibility tiers.
- Multi-Pack:Ten to twenty-unit configurations balance material efficiency with retail shelf presence. Vietnamese domestic brands scale multi-pack orders fastest as local blown-film capacity expands.
- Bulk Packaging:Institutional and subscription channels specify fifty-plus unit formats with reinforced seals for logistics handling. Brazilian converters develop bulk formats for Latin American retail club channels.
- Recyclable Packaging:Mono-material PE structures designed for mechanical reprocessing under France's Citeo and Germany's Der Grüne Punkt extended producer responsibility systems. Premium European brands specify recyclable formats to satisfy EU Green Deal packaging rules.
Multi-pack configurations hold the largest share; recyclable packaging shows the steepest expansion trajectory as compliance deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Packaging and Packaging Waste Regulation anchors European compliance trajectories, while Southeast Asian production clusters absorb accelerating demand from domestic hygiene brand expansion. Regional differentiation sharpens between mature regulatory environments and capacity-constrained emerging markets.
Indonesia
Domestic feminine hygiene brands in Jakarta and Surabaya triple blown-film orders to replace imported pouch substrates. The national industrial ministry promotes local packaging material self-sufficiency through import substitution incentives. New extrusion lines in Bekasi and Cikarang industrial corridors narrow the supply gap for regional hygiene product makers.
Germany
EMA-aligned material safety documentation requirements concentrate demand among qualified converters serving pharmacy channels. REACH Annex XVII restrictions on intentionally added microplastics compel ink reformulation across converting operations. The Rhine-Ruhr industrial basin hosts migration-testing protocol development for fragrance-infused pouch films.
Vietnam
Central coast manufacturing around Da Nang offers underpenetrated converting capacity with lower labor and logistics costs versus Ho Chi Minh City. Domestic hygiene brands scale local pouch film orders faster than regional extrusion capacity expands. Binh Duong and Dong Nai provinces attract blown-film investment serving export-oriented hygiene brands.
United States
FDA indirect food-contact standards extend to fragrance and lotion-infused feminine care products, influencing adhesive and ink selections. Berry Global anchors North American supply with in-house resin compounding capabilities. Midwest converting clusters around Chicago and Minneapolis serve mass-market hygiene brands with standardized film specifications.
Brazil
Sugarcane-derived bio-PE hybrid structures allow renewable content claims without seal-strength degradation. Premium hygiene manufacturers adopt these hybrid structures at pilot scale. São Paulo state converters develop bulk formats for Latin American retail club channels while scaling barrier-grade film production.
Feminine Care Pouch Film Market Competitive Landscape
Integrated multinationals and regional specialists split the market between compliance-heavy European contracts and volume-driven Southeast Asian supply. Consolidation concentrates among extrusion-to-pouch converters capable of unified tender response. Three archetypes dominate: resin-integrated global suppliers, film-to-pouch regional converters, and sustainability-certified niche players. Competitive moves center on backward integration into resin compounding and geographic expansion into underpenetrated converting clusters.
Within the integrated multinational tier, Amcor PLC and Mondi occupy positions defined by multi-layer coextrusion expertise and integrated kraft-film laminate capabilities respectively. Berry Global Inc. anchors the resin-integrated archetype through captive supply chain control. These three exemplify how scale and vertical scope separate preferred suppliers from distributor-dependent competitors in procurement consolidation environments.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi |
| WestRock Company |
| Tetra Pak International S.A. |
| Smurfit Kappa |
| Berry Global Inc. |
| Huhtamaki |
| Bemis Manufacturing Company |
| ProAmpac |
| Others |
Supply & Pricing Matrix
Bekasi and Cikarang industrial corridors in Indonesia are expanding blown-film extrusion capacity faster than domestic demand absorbs output, compressing regional pricing power for imported substrates and forcing converters toward longer-term contract structures. This supply-side expansion in Southeast Asia interacts with European REACH compliance costs to create divergent pricing trajectories across procurement zones.
Pricing Analysis
Geographic price spreads between Indonesian domestic production and European imports have widened as local extrusion scales. Three-tier pricing structure across certified-sustainable, standard barrier-grade, and economy flat-pouch tiers separates procurement contracts. Pricing pressure stems from ethylene feedstock volatility tied to Singapore and South Korean naphtha-cracker margins. Mass-market hygiene brands in Vietnam and Philippines exhibit highest price sensitivity; premium European pharmacy channels prioritize compliance documentation over unit cost.
Supply Chain Analysis
Extended payment terms from Indonesian supermarket chains are reshaping supplier financing requirements for regional converters. Supply concentrates in Indonesia, Vietnam, and Germany, with raw material dependencies on polyethylene resin, masterbatch colorants, and EVOH barrier layers. Single-source vulnerability in German and Japanese masterbatch supply creates structural risk. Distribution runs through direct film-to-pouch converters consolidating procurement panels from distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as post-pandemic hygiene brand localization accelerates capital deployment into Southeast Asian extrusion capacity. The recovery phase favors integrated converters with captive resin supply over distributor-dependent competitors.
For Market Incumbents: Entrench barrier-grade coextrusion expertise through backward integration into masterbatch compounding, reducing single-source exposure to German and Japanese chemical suppliers. Expand technical training programs in Indonesia and Vietnam to address seven-layer blown-film technician scarcity before regional capacity constraints harden.
For New Entrants and Emerging Players: Pursue underpenetrated converting capacity around Da Nang in Vietnam's central coast, where labor and logistics costs trail Ho Chi Minh City benchmarks. Target pharmacy channels in Germany and France with EMA-aligned migration testing documentation as a differentiated entry wedge. Lead with mono-material PE recyclable formats to capture extended producer responsibility funding flows.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement panel consolidation from twelve-plus vendors to four preferred partners concentrates volume among extrusion-to-pouch converters. Target regional specialists with captive blown-film lines serving domestic hygiene brands in Jakarta and Surabaya. Watch Indonesia's import substitution policy enforcement as an inflection signal for local capacity utilization rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Masterbatch Compounding | Reduces single-source dependency on German and Japanese chemical suppliers for hygiene-grade colorants. |
| Seven-Layer Blown-Film Capacity Expansion | Captures high-barrier sub-1 g/m²/day moisture transmission specifications from premium sanitary pad lines. |
| Mono-Material PE Recyclable Format Development | Qualifies for France's Citeo and Germany's Der Grüne Punkt extended producer responsibility funding systems. |
| Migration Testing Protocol Investment | Accelerates FDA indirect food-contact validation for fragrance-infused pouch films targeting lotion-embedded formats. |
| Central Vietnam Converting Footprint Establishment | Exploits Da Nang labor cost advantages versus Ho Chi Minh City for export-oriented hygiene brand supply. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating procurement managers at Indonesian supermarket chains, technical directors at blown-film extrusion lines, regulatory affairs specialists navigating REACH Annex XVII, and hygiene brand supply chain heads. Secondary validation drew from ECHA restriction updates, EU Packaging and Packaging Waste Regulation documentation, customs trade data for polyethylene resin flows, and SEC filings from integrated packaging multinationals. Bottom-up capacity assessments triangulated against top-down demand modeling from sanitary pad production volumes.
Calibration against historical blown-film extrusion capacity utilization and hygiene product shipment data anchored projections across the analysis window. Segmentation dimensions spanned pouch architecture, substrate chemistry tiers, distribution channel type, and pack configuration scale. CAGRs derived from regression analysis of material intensity per sanitary pad unit and regional production growth trajectories. Industry-specific inputs included moisture vapor transmission rate specifications and migration testing timeline distributions for fragrance-infused variants.
The forecast holds incumbent behavior within observed patterns; aggressive moves by resin-integrated global suppliers or state-backed Indonesian converters would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Telemetry Pouch Market
Pouch
United States Pouch Packaging Market
Pouch
Slider Zipper Pouch Market
Pouch
Squeeze Pouch Market
Pouch
Center Seal Pouch Making Machine Market
Pouch
Monodose Packs Market
Pouch
GCC Retort Pouches Market
Pouch
Recyclable PE Pouch Market
Pouch
Spout Pouch Market
Pouch
Europe Retort Pouches Market
Pouch
Fin Seal Pouches Market
Pouch
Brazil Pouch Packaging Market
Pouch
Morocco Pouch Packaging Market
Pouch
Clipless Vertical Pouches Market
Pouch
Clear Pouches Market
Pouch
PPWR-Compliant Recyclable PE/PP Stand-Up Pouch Recycling Systems Market