
 India Pouch Packaging Market | 2026-2036
India Pouch Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
India Pouch Packaging Market Insights
Maharashtra's industrial corridor around Mumbai and Pune is fragmenting as new flexible packaging converters enter to serve pharmaceutical and food processing clients. Uflex Limited leverages its integrated film manufacturing and printing capabilities to anchor supply for FMCG brands across western India. Amcor Plc competes through technology leadership in high-barrier laminates for sensitive pharmaceutical applications. Paras Printpack specializes in gravure-printed stand-up pouches for regional snack food companies.
India pouch packaging comprises flexible laminated or monolayer containers formed from plastic films, paper, or aluminum foil composites, typically sealed by heat or pressure to create barrier-protected enclosures ranging from 10 milliliters to 20 liters in volume. These structures protect contents from moisture, oxygen, and light while minimizing material weight versus rigid alternatives. Stand-up pouches with spout fitments command premium positioning in liquid detergent and edible oil segments where consumer convenience drives repeat purchase. Retort pouches represent the fastest-growing material configuration as ready-to-eat curry and rice brands expand shelf-stable offerings without cold chain dependency. Plastic laminates still dominate total volume but bio-based material trials are intensifying among export-oriented food processors facing EU packaging sustainability directives.
FSSAI notification requirements for food-contact substances and BIS certification for plastic packaging standards shape material selection and supplier qualification timelines across the value chain. The Plastic Waste Management Rules enforced by the Central Pollution Control Board mandate extended producer responsibility disclosures that increase compliance costs for unorganized converters. CDSCO's pharmaceutical packaging guidelines for primary barrier materials add testing layers for drug-contact pouch formats. Stakeholders must monitor how state-level plastic ban enforcement in Karnataka, Tamil Nadu, and Maharashtra creates divergent operating environments that favor multi-material expertise over single-substrate dependence.
Market Dynamics
The FSSAI's tightening food-contact substance notifications and BIS certification mandates are forcing converters to requalify material suppliers, compressing procurement timelines and elevating compliance costs across Maharashtra and Gujarat manufacturing clusters.
Growth Catalysts
- Retort pouch technology:Ready-to-eat curry and rice brands are eliminating cold chain dependency through shelf-stable barrier formats. Adoption concentrates among western India food processors serving export markets.
- FSSAI packaging safety norms:Evolving notification requirements for food-contact substances are accelerating formal sector consolidation as unorganized converters exit.
- Maharashtra pharmaceutical corridor:Mumbai-Pune drug manufacturing clusters are generating specialized demand for high-barrier primary packaging with CDSCO-compliant testing documentation.
Market Restraints
- Aluminum foil price volatility:High-barrier laminate converters face margin compression from raw material cost swings in multi-layer structures.
- Single-substrate dependence:Converters lacking multi-material expertise face operational disruption from state-level plastic ban enforcement in Karnataka, Tamil Nadu, and Maharashtra.
- Extended producer responsibility:Central Pollution Control Board disclosure mandates under Plastic Waste Management Rules impose compliance burdens on small-scale converters.
Strategic Opportunities
- Bio-based material trials:Export-oriented food processors are piloting compostable laminates to meet EU packaging sustainability directives.
- Stand-up pouches with spout fitments:Liquid detergent and edible oil segments in Gujarat offer premium positioning for convenience-driven formats.
- PLI scheme for specialty chemicals:Domestic resin production incentives are reducing import dependence for film-grade polymers used in barrier structures.
Industry Challenges
- Gravure printing skill scarcity:Regional snack food suppliers struggle to source qualified operators for high-definition rotogravure cylinder management.
- BIS certification timelines:Plastic packaging standard approvals create 4-6 month supplier qualification delays for new material qualifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Pouch Packaging Market |
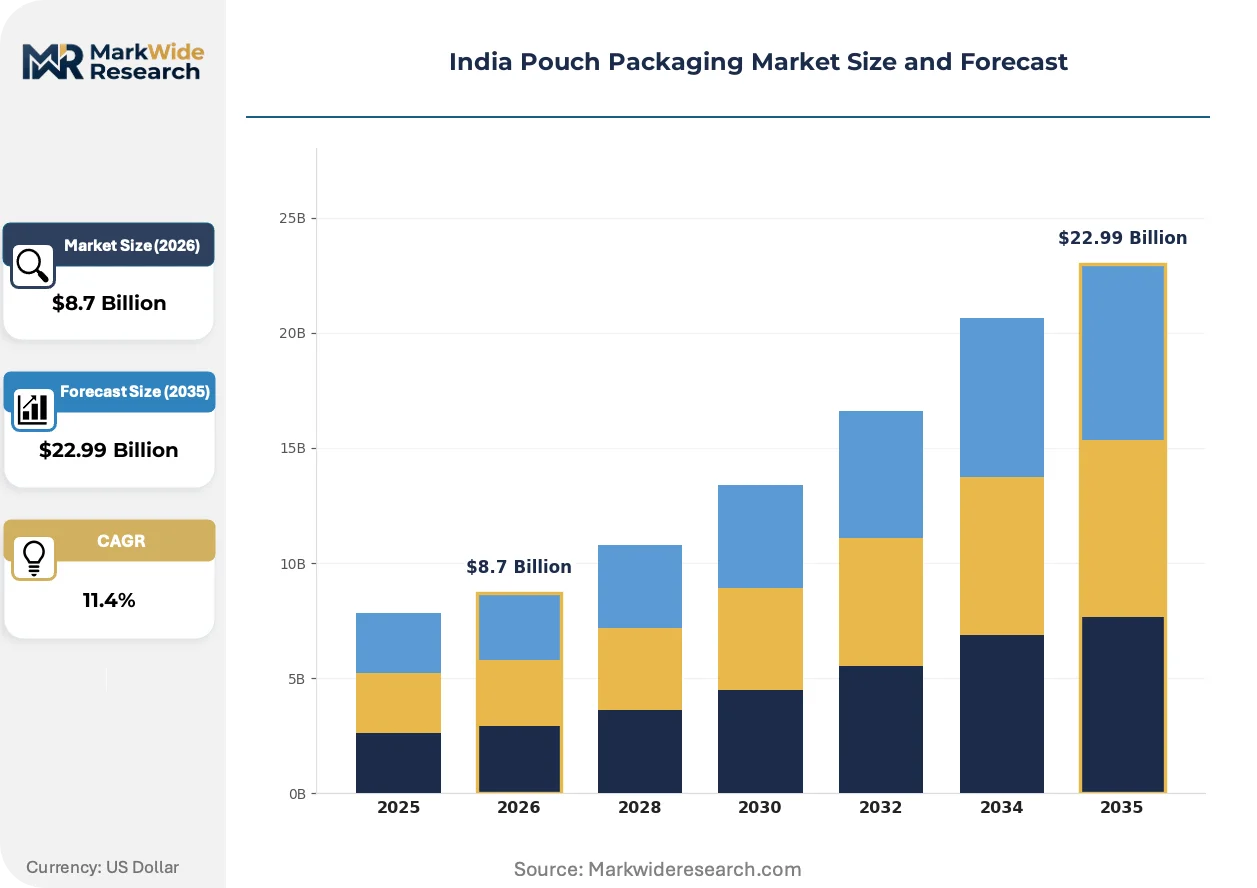
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-Up Pouches, Flat Pouches, Vacuum Pouches, Retort Pouches Material: Plastic, Paper, Aluminum Foil, Bio-based Materials Application: Food & Beverage, Personal Care, Pharmaceuticals, Household Products End User: Manufacturers, Retailers, Distributors, E-commerce Platforms |
| Companies Covered | Uflex Limited, Amcor Plc, Sonoco Products Company, Paras Printpack, Sky Flexi Pack, Aashirwad Poly Print, Tilak Polypack Pvt. Ltd., Wellworth Packers Pvt. Ltd., Paharpur 3P Pvt Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Pouch Packaging Market Trends and Innovations
Material science advances and regulatory pressure are converging to reshape converter capabilities across India's flexible packaging value chain. Three distinct shifts are altering competitive requirements.
Barrier coating technology is migrating from solvent-based adhesives to water-based and solvent-free lamination systems. Food processors in Maharashtra are demanding these formats to meet FSSAI volatile organic compound thresholds. The transition is compressing margins for converters lacking in-house adhesive compounding expertise.
CDSCO pharmaceutical packaging guidelines for primary barrier materials are mandating enhanced extractables and leachables testing documentation. Drug manufacturers in the Mumbai-Pune corridor now require batch-level compliance certificates. This regulatory layer favors converters with captive analytical laboratories over toll-testing dependencies.
Brand procurement teams are consolidating supplier panels to reduce audit burden from divergent state plastic regulations. FMCG companies are favoring multi-material capable converters who can pivot between substrate types. This concentration is most visible among western India snack food and dairy processors navigating Maharashtra's enforcement variability.
India Pouch Packaging Market Segmentation
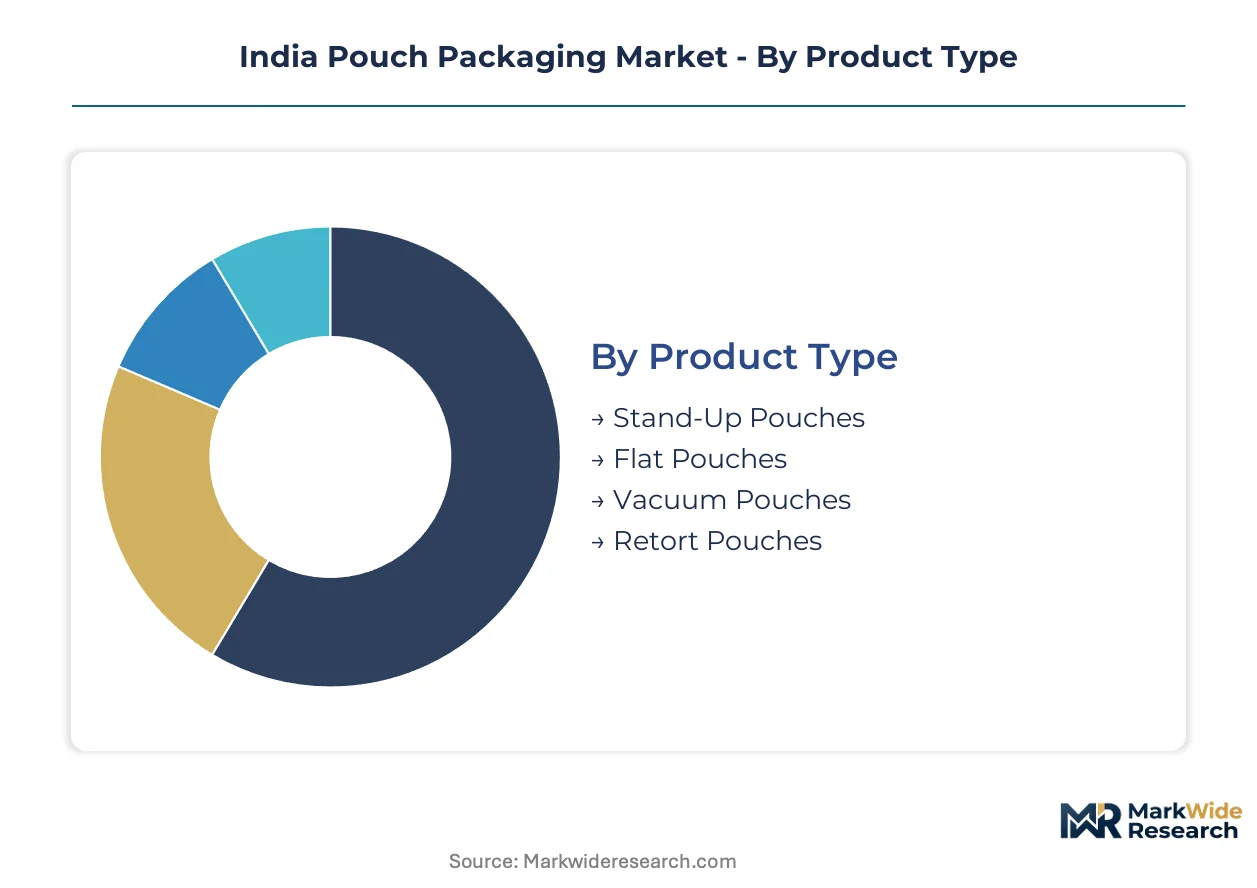
Segmentation in India's pouch packaging market reveals how substrate choices, format configurations, and end-use requirements create distinct procurement clusters. Each dimension shapes converter capabilities and regulatory compliance burdens differently across Maharashtra and Gujarat manufacturing zones.
Product Type:
Use-case spectrum spans single-serve convenience formats to industrial-scale barrier protection for shelf-stable distribution.
- Stand-Up Pouches:Three-dimensional structures with bottom gussets enable vertical shelf display and enhanced brand visibility. Gujarat's edible oil and liquid detergent processors in Ahmedabad-Surat corridor are converting from rigid bottles to spout-fitted stand-up formats for e-commerce compatibility.
- Retort Pouches:Multi-layer laminates withstand 121°C sterilization temperatures to deliver ambient shelf stability. Ready-to-eat curry and rice brands across Mumbai-Pune food processing clusters are eliminating cold chain dependency through retort adoption for export markets.
- Flat Pouches:Two-dimensional sealed envelopes serve cost-sensitive single-serve applications in regional snack distribution.
- Vacuum Pouches:Gas-barrier structures remove headspace oxygen to extend protein shelf life in Maharashtra's processed meat and seafood supply chains.
The dominant share belongs to Stand-Up Pouches, while Retort Pouches are expanding most quickly as food processors target export-ready shelf-stable formats.
Material:
Cost tier stratification separates commodity volume plays from premium barrier performance and emerging sustainability positioning.
- Plastic:Polyethylene and polypropylene laminates dominate tonnage through cost efficiency and heat-seal reliability. Maharashtra's unorganized converter base relies heavily on monolayer PE structures, though FSSAI notification requirements are forcing migration toward co-extruded multi-layer formats with enhanced food-contact compliance.
- Aluminum Foil:Ultra-thin metal layers provide complete light and oxygen barrier for pharmaceutical and sensitive food applications. Mumbai-Pune drug manufacturers require foil-containing laminates with CDSCO-mandated extractables documentation, though raw material price volatility compresses converter margins.
- Paper:Fiber-based substrates with polymer coatings serve premium positioning in organic and artisanal food segments where tactile differentiation commands shelf attention.
- Bio-based Materials:Compostable films derived from polylactic acid and starch blends are piloting among export-oriented processors facing EU packaging sustainability directives.
Plastic retains volume leadership by a wide margin, though Aluminum Foil commands the steepest premium trajectory as pharmaceutical compliance layers intensify.
Application:
Customer type concentration varies sharply between high-volume FMCG procurement and specialized batch requirements for regulated products.
- Food & Beverage:Spans ready-to-eat meals, dairy, snacks, and edible oils requiring FSSAI-compliant food-contact materials. Western India clusters generate specialized demand for retort and high-barrier formats.
- Pharmaceuticals:Primary packaging for solid dose and liquid formulations demands CDSCO-compliant testing documentation with batch-level certificates.
- Personal Care:Cosmetic and hygiene products utilize stand-up pouches with dispensing fitments for travel-size and refill applications.
- Household Products:Detergent and cleaning chemical processors in Gujarat favor large-format spout pouches for concentrated refill economics.
Food & Beverage anchors procurement volume, while Pharmaceuticals is gaining share fastest on compliance-driven supplier consolidation.
End User:
Supply concentration maps to manufacturing geography, with procurement authority fragmenting across direct converter relationships and intermediated distribution channels.
- Manufacturers:Brand owners with captive packaging specifications drive material innovation and quality certification requirements.
- Retailers:Private label programs at organized grocery chains are consolidating supplier panels to reduce audit burden from state plastic regulations.
- Distributors:Regional intermediaries serve unorganized food processors with standardized pouch formats and shorter lead times.
- E-commerce Platforms:Quick-commerce and online grocery fulfillment is driving demand for damage-resistant stand-up formats with optimized cube utilization.
Manufacturers control specification authority, though E-commerce Platforms are climbing the fastest as last-mile delivery requirements reshape format priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converter capacity clusters around western India's industrial corridors, with Maharashtra and Gujarat hosting the densest concentrations of flexible packaging fabrication serving pharmaceutical and food processing demand.
Maharashtra
Mumbai-Pune pharmaceutical manufacturers generate specialized procurement for high-barrier primary packaging with CDSCO-mandated extractables documentation. FSSAI notification requirements for food-contact substances are accelerating formal sector consolidation as unorganized converters exit. The Thane-Ambernath belt anchors retort pouch fabrication for ready-to-eat meal exporters targeting Middle Eastern markets.
Gujarat
Ahmedabad-Surat processors are converting edible oil and liquid detergent lines from rigid bottles to spout-fitted stand-up formats for e-commerce compatibility. BIS certification timelines for plastic packaging standards create supplier qualification delays that favor established multi-material converters. The Vadodara-Ankleshwar corridor specializes in gravure-printed formats for regional snack food brands.
Karnataka
State-level plastic ban enforcement is disrupting single-substrate converters lacking multi-material pivot capabilities. Bengaluru's food tech startups are piloting bio-based laminates for export-oriented organic product lines facing EU packaging sustainability directives. The Peenya industrial zone hosts emerging flexible packaging capacity serving South Indian dairy cooperatives.
Tamil Nadu
Chennai-Coimbatore manufacturing clusters generate demand for vacuum barrier structures in processed seafood and spice export supply chains. Extended producer responsibility disclosures under Central Pollution Control Board mandates impose compliance burdens on small-scale converters. The Sriperumbudur-Oragadam belt is attracting film extrusion investments from national flexible packaging groups.
Telangana
Hyderabad's pharmaceutical formulation sector is sourcing primary barrier pouches with batch-level compliance certificates for regulated drug exports. PLI scheme incentives for specialty chemicals are reducing import dependence for film-grade polymers used in barrier structures. The Jeedimetla-Patancheru industrial corridor is emerging as a secondary hub for converted flexible packaging serving central Indian markets.
India Pouch Packaging Market Competitive Landscape
Integrated film manufacturers and specialized converters split the market along capability depth lines. Tier-one players control captive resin production and multi-layer lamination expertise, while mid-scale operators compete on regional logistics and shorter lead times. Two archetypes dominate: vertically integrated material-science leaders with in-house polymer compounding, and gravure-specialist converters with cylinder management capabilities. Competitive intensity manifests through capacity expansion in western India corridors and strategic partnerships between film producers and brand owners seeking supply security.
Among India-based integrated players, Uflex Limited anchors the material-science archetype with captive film manufacturing and printing capabilities across western India. Amcor Plc represents the multinational technology-leadership position in high-barrier pharmaceutical applications. Paras Printpack exemplifies the regional specialist model focused on gravure-printed formats for snack food and dairy segments. These three occupy distinct competitive spaces without direct overlap in customer specifications or regulatory compliance tiers.
| Leading Market Players |
|---|
| Uflex Limited |
| Amcor Plc |
| Sonoco Products Company |
| Paras Printpack |
| Sky Flexi Pack |
| Aashirwad Poly Print |
| Tilak Polypack Pvt. Ltd. |
| Wellworth Packers Pvt. Ltd. |
| Paharpur 3P Pvt Ltd |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-JNPT logistics corridor channels raw material freight costs directly into converter margin structures across western India, amplifying price differentiation between multi-material specialists and single-substrate operators while concentrating procurement leverage among pharmaceutical and food processing buyers in Maharashtra and Gujarat.
Pricing Analysis
BIS certification mandates for plastic packaging standards dictate the pricing tier structure across the India pouch packaging landscape. Three-tier pricing structure across premium, standard, and economy levels separates CDSCO-compliant pharmaceutical laminates with batch-level documentation from FSSAI-grade food-contact formats and commodity monolayer structures. Price differentiation hinges on certification grade and vertical integration depth, with captive film producers commanding 15-20% premiums over toll-dependent converters. Cost compression in standard-tier food packaging is intensifying because unorganized converters face Plastic Waste Management Rules compliance burdens. Regional snack food distributors exhibit highest price sensitivity, while Mumbai-Pune drug manufacturers prioritize barrier performance over unit economics.
Supply Chain Analysis
Aluminum foil price volatility between domestic smelters and Middle Eastern suppliers dominates supply chain risk exposure for high-barrier laminate producers. Raw material sourcing draws from Saudi Arabian petrochemical feedstocks, South Korean film-grade resin, and domestic BIS-certified polymer compounding. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade foil specifications with CDSCO-mandated extractables documentation. Distribution runs through converter-direct relationships with FMCG brand owners, supplemented by regional distributor networks serving unorganized food processors in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across state-level plastic enforcement regimes creates niche opportunities for converters with multi-material pivot capabilities, as Maharashtra, Karnataka, and Tamil Nadu impose divergent substrate restrictions that punish single-format dependence.
For Market Incumbents: Harden barrier coating technology capabilities through water-based and solvent-free lamination system investments to meet FSSAI volatile organic compound thresholds. Anchor supply security via backward integration into film-grade polymer compounding under PLI scheme incentives, reducing import exposure to Saudi Arabian and South Korean resin suppliers. Defensive positioning against emerging bio-based material specialists requires captive analytical laboratory capacity for extractables and leachables testing documentation. For New Entrants and Emerging Players: Pursue white-space opportunities in Karnataka and Tamil Nadu where state-level plastic bans have displaced single-substrate incumbents lacking multi-material expertise. Target bio-based laminate trials among Bengaluru food tech startups facing EU packaging sustainability directives for export-oriented organic product lines. Go-to-market leverage rests on compostable film partnerships with regional dairy cooperatives seeking premium sustainability positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned flexible packaging groups in the Vadodara-Ankleshwar corridor lacking succession planning and CDSCO compliance infrastructure. Long-term viability favors converters with gravure cylinder management capabilities and pharmaceutical certification tiers that sustain margin premiums over commodity food packaging. Watch for inflection signals in PLI scheme disbursement velocity for specialty chemicals, indicating domestic resin self-sufficiency trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Film Extrusion | Captive resin production under PLI incentives reduces import dependence for barrier structures. |
| Bio-Based Material Certification | Compostable laminate credentials unlock EU export channels for organic food processors. |
| Analytical Laboratory Investment | In-house extractables testing eliminates toll-dependent delays for CDSCO pharmaceutical documentation. |
| Multi-Material Format Diversification | Paper and aluminum foil pivot capabilities hedge against state-level plastic enforcement variability. |
| Gravure Printing Capability Expansion | High-definition cylinder management addresses skill scarcity constraining regional snack food suppliers. |
Research Methodology
Desk research of BIS certification databases, FSSAI notification records, and CDSCO pharmaceutical packaging guidelines preceded structured interviews with converter operations managers, FMCG procurement directors, pharmaceutical packaging specialists, and flexible printing equipment distributors. Secondary validation drew from Central Pollution Control Board enforcement disclosures, state-level plastic ban implementation records, and PLI scheme beneficiary lists. Bottom-up demand modeling across substrate types, format configurations, and end-use applications was triangulated against top-down value chain estimates from resin import data and converter capacity surveys.
Assumptions held FSSAI notification timelines, BIS certification approval durations, and state-level plastic enforcement intensity within observed historical patterns while varying PLI scheme disbursement rates, EU sustainability directive stringency, and aluminum foil import cost trajectories across the projection horizon. Segmentation modeling incorporated material substrate tiers, product format types, application end-uses, and geographic manufacturing clusters. CAGRs were derived from regression analysis of historical converter revenue trajectories and forward projection of regulatory compliance cost burdens.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Middle Eastern film producers or accelerated domestic resin self-sufficiency would shift pricing power dynamics materially. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Wrap-Around Packers Market
Pouch
Four Side-Sealed Pouches Market
Pouch
Flexible Plastic Drinking Pouch Market
Pouch
Clipless Vertical Pouches Market
Pouch
Canada Pouch Packaging Market
Pouch
Standcap Pouch Market
Pouch
Center Sealed Pouch Packaging Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
Monodose Packs Market
Pouch
Kraft Pouch Market
Pouch
Slider Pouches Market
Pouch
Sterilization Pouches Market
Pouch
Kraft Paper Pouch Market
Pouch
Child Resistant Pouches Market
Pouch
Spout and Non-Spout Liquid Pouch Packaging Market
Pouch
Pillow Pouch Packaging Market