
 Bio PE Pouches Market | 2026-2036
Bio PE Pouches Market Size, Share, and Industry Trends Forecast 2026-2036
Bio PE Pouches Market Intelligence
A shift from single-source contracts to multi-source procurement for bio-based resins is realigning the competitive landscape. Amcor Plc leverages its global manufacturing footprint to secure contracts with multinational consumer goods firms. Meanwhile, Braskem differentiates through its leadership in bio-based polyethylene production, controlling a key upstream material supply. Mondi Group competes on the basis of its flexible packaging innovation and integrated operations.
Bio PE pouches are flexible packaging containers made from polyethylene derived from renewable biomass sources like sugarcane. These materials offer a reduced carbon footprint compared to fossil-fuel-based PE while maintaining key functional properties. Stand-up pouches represent the fastest-growing product type, valued for their shelf-presence and consumer convenience in the dominant food packaging application. Material composition choices, particularly between biodegradable PE and other bio-based polymers, define cost and end-of-life options for brand owners.
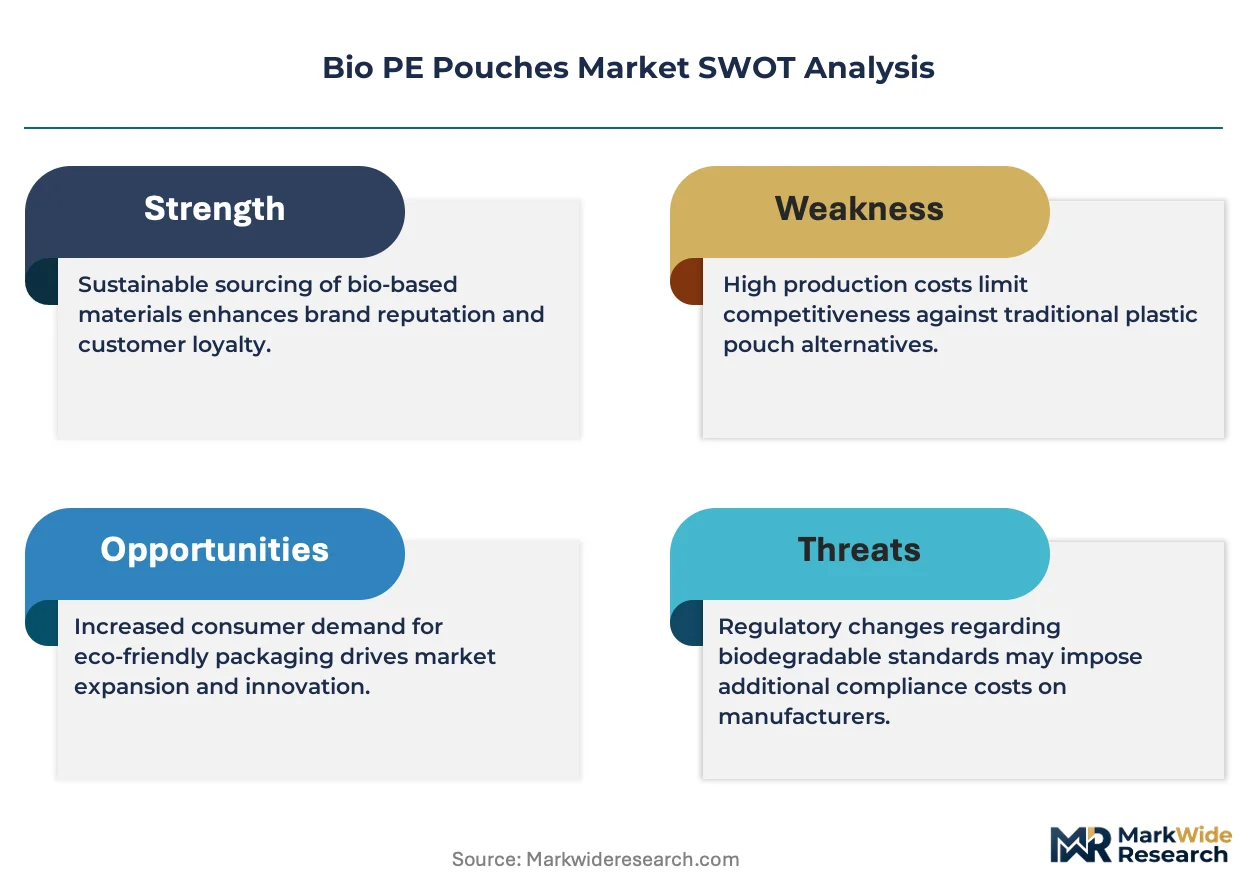
Regulatory frameworks like the EU's Packaging and Packaging Waste Regulation and the US FDA's food contact substance notifications govern market entry. These rules mandate material safety, dictate acceptable end-of-life claims, and are increasingly pushing for circularity. Key strategic decisions for manufacturers and brands now depend on balancing the higher cost of bio-based feedstocks against the tangible brand benefits derived from clear sustainability messaging.
Market Dynamics
The central dynamic in the Bio PE Pouches market is the tension between regulatory mandates for sustainability, exemplified by the EU Green Deal, and the agricultural and logistical constraints of sourcing sugarcane-based feedstocks from a concentrated supply base.
Growth Catalysts
- Regulatory Mandates:The EU's Packaging and Packaging Waste Regulation (PPWR) creates strong incentives for brands to adopt packaging with a lower carbon footprint, directly benefiting bio-based materials like bio-PE.
- Consumer Preferences:Demand for clean-label and organic food products is extending to packaging, with consumers increasingly preferring materials that reflect a brand's commitment to natural and sustainable sourcing.
- Drop-in Functionality:Bio-PE is chemically identical to fossil-based PE, allowing converters to use it on existing film extrusion and pouch-making machinery without significant capital investment or process changes.
Market Restraints
- Feedstock Cost Volatility:The price of bio-PE is tied to sugarcane prices, which are subject to agricultural yields, weather events, and global commodity market fluctuations, creating cost instability for converters.
- Supply Chain Concentration:A significant portion of the world's bio-ethylene production is geographically concentrated in Brazil, posing potential supply chain risks related to logistics, trade policy, and regional stability.
- Substitution from PLA:Polylactic acid (PLA) and other compostable bioplastics present a competitive alternative, offering a different end-of-life disposal pathway (industrial composting) that appeals to certain consumer segments and brands.
Strategic Opportunities
- Non-Food Application Expansion:There is significant opportunity in the cosmetics and personal care sectors, where the premium branding associated with sustainable packaging can justify the higher material cost of bio-PE pouches.
- Alternative Feedstock Development:Research into second-generation bio-PE derived from non-food sources like cellulosic biomass or agricultural waste can mitigate land-use concerns and diversify the raw material supply chain.
- Circular Economy Integration:Developing closed-loop systems that combine bio-PE with chemically recycled PE content can create a hybrid material that satisfies both renewable-source and recycled-content mandates.
Industry Challenges
- End-of-Life Infrastructure Gaps:A lack of dedicated sorting and recycling streams for bio-PE means it often enters the conventional PE recycling process, which it does not technically contaminate but fails to capture its unique value.
- Complex Sustainability Messaging:Communicating the specific environmental benefits of bio-PE (carbon footprint reduction) versus other bioplastics (compostability) to consumers without causing confusion or greenwashing accusations is a persistent challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio PE Pouches Market |
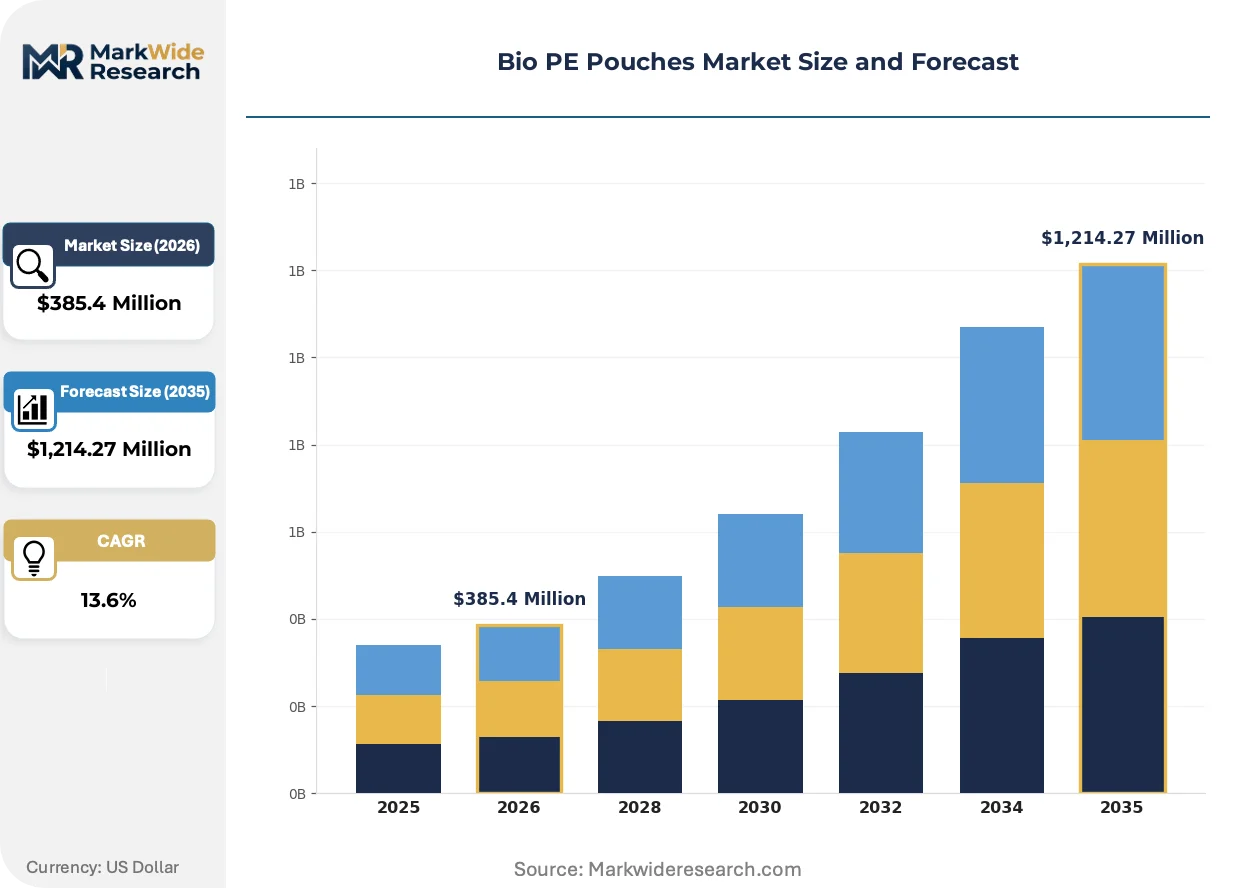
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,214.27 Million |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Flat Pouches, Gusseted Pouches, Spouted Pouches Material Composition: Biodegradable PE, Compostable Films, Recyclable Coatings, Bio-based Polymers Application: Food Packaging, Personal Care Products, Agricultural Supplies, Household Chemicals End User Industry: Consumer Goods Manufacturers, Specialty Packaging Suppliers, Contract Packers, Eco-Friendly Brands |
| Companies Covered | Amcor Plc, Mondi Group, Sealed Air Corporation, Coveris Holdings S.A., Berry Global Inc., Braskem, Huhtamaki, UFlex, Novamont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio PE Pouches Market Strategic Shifts & Innovations
The market is being reshaped by the drive to enhance the functional performance of bio-based materials beyond simple substitution. This shifts focus from merely replacing fossil plastics to engineering advanced bio-based structures that meet specific end-use demands for barrier properties and circularity.
High-barrier coextruded films are a key area of product evolution, integrating thin layers of materials like EVOH within a majority bio-PE structure. Food manufacturers are adopting these advanced pouches for oxygen-sensitive products, such as coffee and baby food, to ensure product integrity and extend shelf life. This development is absorbing R&D investment that previously targeted mono-material solutions, steering innovation toward high-performance, multi-layer bio-based packaging.
Regulatory frameworks, particularly the EU's Packaging and Packaging Waste Regulation, are setting stringent targets for circularity that go beyond renewable sourcing. The legislation's emphasis on design-for-recycling and minimum recycled content levels is compelling a strategic pivot. Flexible packaging converters, especially in Germany and the Netherlands, are now reformulating films to incorporate chemically recycled content alongside bio-PE to meet future compliance obligations.
Brand owners are altering their supply chain strategies, moving from exclusive reliance on a single bio-resin supplier to a more diversified, multi-source model. This change de-risks supply chains that were previously vulnerable to disruptions from a single producer or region and fosters greater price competition among resin manufacturers. This procurement shift is most evident among multinational CPG firms based in the US and Europe who require robust supply assurance for their global brands.
Bio PE Pouches Market Segmentation
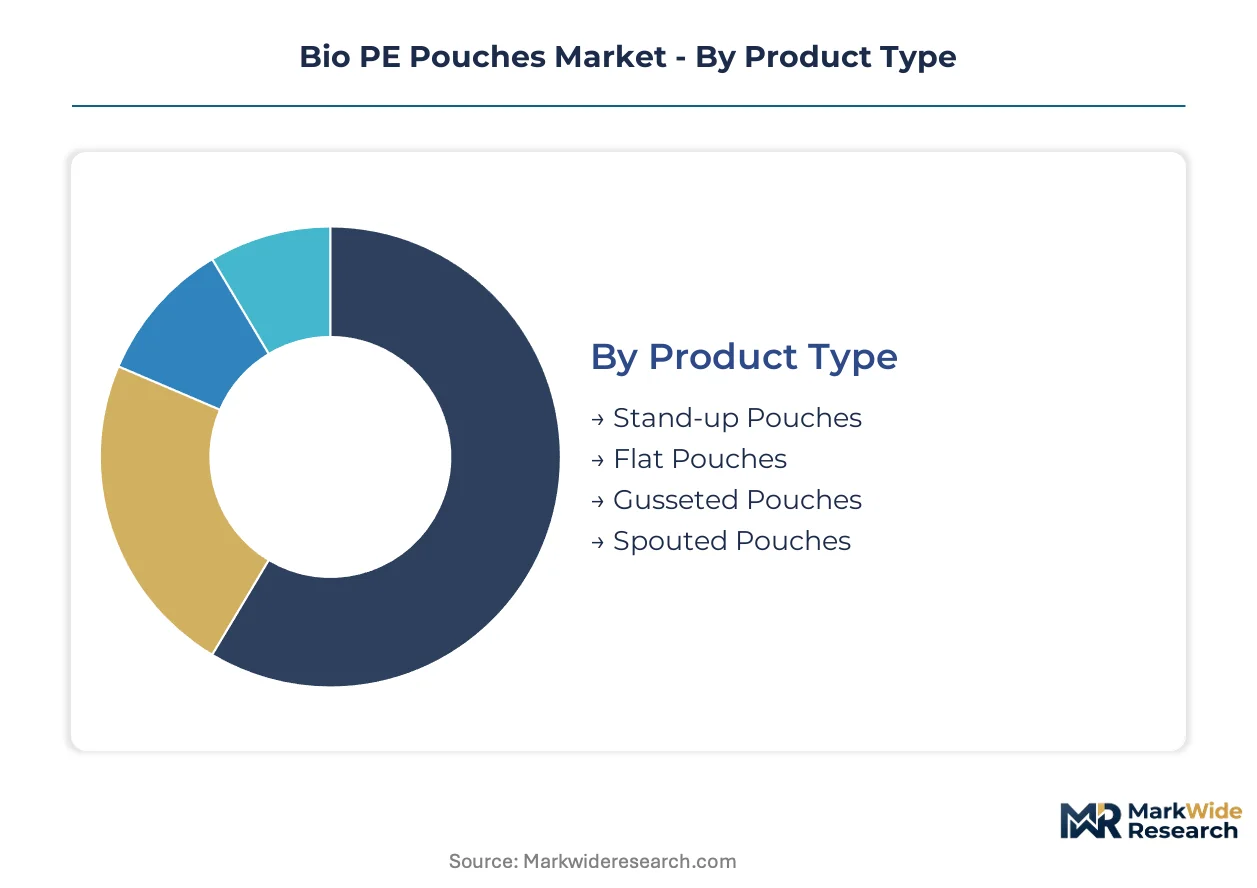
The Bio PE Pouches market structure reflects diverse product forms and material innovations addressing specific end-use requirements. This segmentation highlights the various functional attributes and strategic choices available to brand owners and converters. Understanding these distinct segments provides clarity on market dynamics and competitive positioning.
Product Type:
The product type category delineates the spectrum from highly standardized pouch formats to more specialized, custom-engineered solutions.
- Stand-up Pouches:These flexible containers feature a flat bottom or gusset that allows them to stand upright on shelves, maximizing visibility. Demand concentrates in the food packaging sector, particularly for organic and natural products, driven by consumer convenience and strong shelf presence.
- Flat Pouches:Flat pouches are simple, two-dimensional flexible bags sealed on all sides, offering a cost-effective and versatile packaging solution. Their widespread adoption in snack foods and single-serve portions reflects efficient material use and straightforward filling processes for high-volume consumer goods.
- Gusseted Pouches:Gusseted pouches incorporate folds on the sides or bottom, expanding to accommodate larger volumes, common in bulk dry goods packaging.
- Spouted Pouches:These pouches integrate a fitment and cap, providing controlled dispensing for liquid or semi-liquid products like baby food and detergents.
Leading the category by volume: Flat Pouches. Growing fastest: Stand-up Pouches.
Material Composition:
Material composition choices define the cost tiering and end-of-life options available for bio-PE pouches.
- Bio-based Polymers:These materials are derived from renewable biomass sources like sugarcane, offering a reduced carbon footprint compared to fossil-fuel plastics. Their chemical identity with conventional PE allows for drop-in functionality in existing conversion machinery, simplifying adoption for manufacturers.
- Biodegradable PE:This specific type of bio-based polyethylene is engineered to degrade naturally under certain environmental conditions, though infrastructure for its industrial composting remains limited. Its appeal lies in addressing plastic accumulation concerns, particularly for single-use applications.
- Compostable Films:These films are designed to break down into organic matter in industrial composting facilities, offering an alternative end-of-life pathway to traditional recycling.
- Recyclable Coatings:Applied to bio-PE substrates, these coatings enhance barrier properties while maintaining the pouch's overall recyclability in conventional PE streams.
This segment's evolution is driven by regulatory pressure for circularity and brand owner commitment to sustainable material sourcing.
Application:
End-use diversity within the Bio PE Pouches market showcases the material's adaptability across various consumer and industrial sectors.
- Food Packaging:This application represents the primary demand driver for bio-PE pouches, especially for organic, natural, and clean-label food products. High-barrier coextruded films protect oxygen-sensitive items like coffee and baby food, extending shelf life and maintaining product integrity.
- Personal Care Products:The cosmetics and personal care sectors leverage bio-PE pouches for premium branding and sustainability messaging, justifying higher material costs. Brands adopt these pouches for products such as lotions, shampoos, and liquid soaps, aligning with eco-conscious consumer preferences.
- Agricultural Supplies:Bio-PE pouches offer durable and moisture-resistant packaging for seeds, fertilizers, and pest control products, supporting sustainable farming practices.
- Household Chemicals:This segment uses bio-PE pouches for concentrated cleaning solutions and refills, reducing plastic waste and improving consumer convenience.
The broadest adoption is seen in food packaging, while personal care products are expanding most quickly.
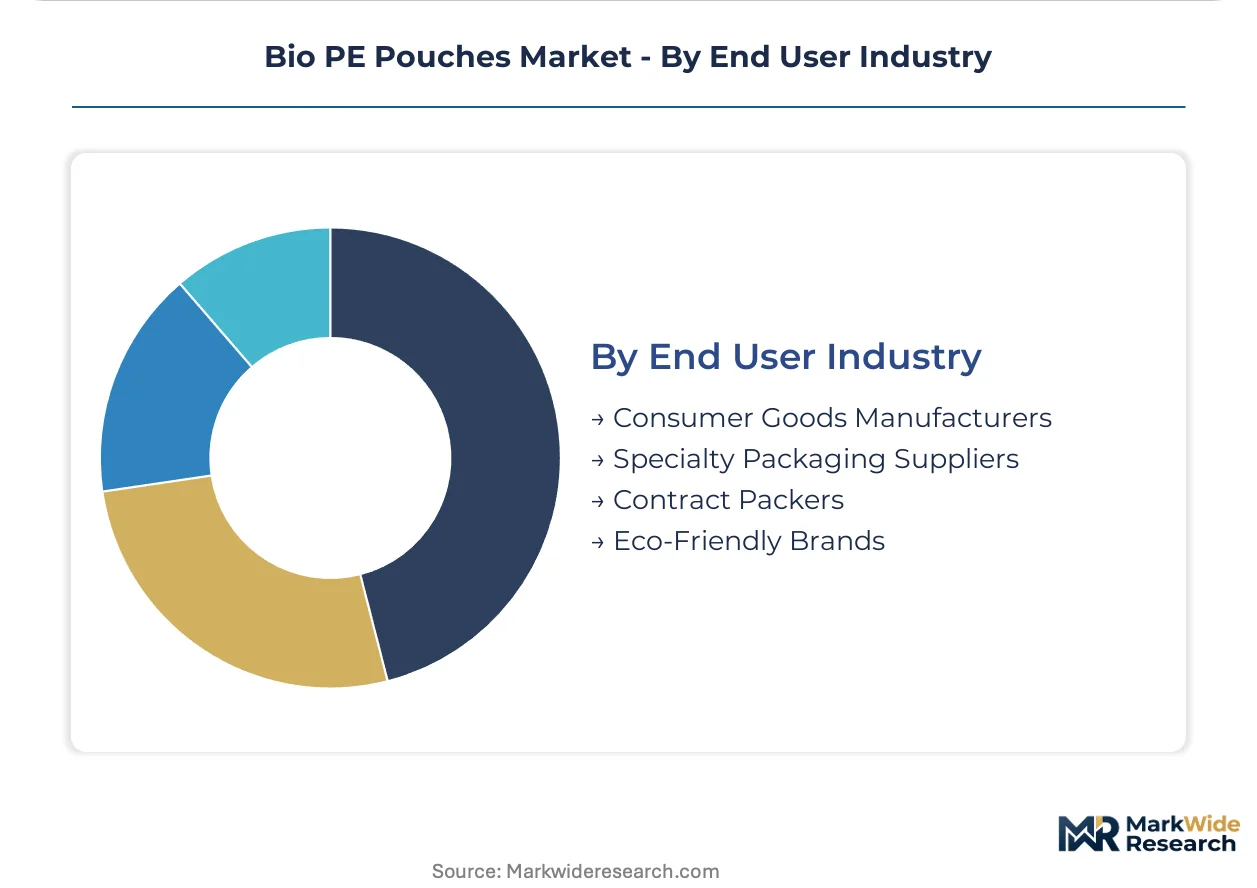
End User Industry:
The end user industry segmentation reflects the varying procurement strategies and sustainability mandates of different customer types.
- Consumer Goods Manufacturers:Multinational CPG firms represent significant volume purchasers, often shifting to multi-source procurement models for bio-based resins to ensure supply security. These manufacturers integrate bio-PE pouches into their product lines to meet sustainability targets and regulatory compliance.
- Eco-Friendly Brands:These brands prioritize sustainable packaging solutions, often willing to absorb the higher cost of bio-PE pouches to align with their core values and attract environmentally conscious consumers. They frequently drive demand for innovative, low-carbon footprint materials.
- Specialty Packaging Suppliers:These suppliers offer customized bio-PE pouch solutions, catering to niche markets requiring specific barrier properties or unique designs.
- Contract Packers:Contract packers integrate bio-PE pouches into their services, allowing brands to outsource packaging operations while fulfilling sustainability commitments.
Volume is concentrated among consumer goods manufacturers, while eco-friendly brands influence product innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's concentrated supply of sugarcane-based feedstocks anchors the global bio-PE pouches market. This single-source dependency creates both strategic opportunities and supply chain vulnerabilities for manufacturers worldwide. The country's agricultural capacity directly influences the global availability of bio-ethylene.
Brazil
Demand for bio-PE pouches in Brazil is driven by domestic food and beverage companies seeking sustainable packaging. The country's national environmental regulations encourage the use of renewable resources in manufacturing. São Paulo hosts a significant portion of the bio-ethylene production capacity, serving both local and international markets.
Germany
Germany's market for bio-PE pouches is propelled by strong consumer preferences for sustainable products and stringent regulatory mandates. The EU's Packaging and Packaging Waste Regulation (PPWR) provides significant incentives for brands to adopt bio-based materials. Converters in North Rhine-Westphalia are actively reformulating films to meet new circularity obligations.
United States
US demand for bio-PE pouches stems from multinational consumer goods firms and eco-friendly brands prioritizing sustainability. The US FDA's food contact substance notifications govern material safety and market entry for these innovative packaging solutions. California's progressive environmental policies often lead to early adoption of bio-based packaging alternatives.
Japan
Japanese brand owners are increasingly adopting bio-PE pouches for premium food and personal care items, driven by corporate sustainability goals. METI initiatives support the development of advanced bio-based materials and circular economy practices. Tokyo-based consumer product companies are integrating these pouches to appeal to environmentally conscious consumers.
India
India's market for bio-PE pouches is expanding due to a rising middle class and increasing awareness of environmental issues in urban centers. The BIS standards are evolving to include guidelines for sustainable packaging materials. Packaging manufacturers in Gujarat are exploring bio-PE solutions for various consumer goods applications.
Bio PE Pouches Market Key Industry Players
Global majors compete with regional champions across flexible packaging innovation and material sourcing capabilities. The market structure is moderately consolidated, featuring a mix of large integrated players and specialized converters. Strategic archetypes include diversified packaging conglomerates, specialized bio-resin producers, and flexible packaging innovators focused on sustainability. Companies are engaging in strategic partnerships for feedstock security and expanding manufacturing footprints to serve multinational clients.
At the scale-driven end, Amcor Plc represents a global packaging powerhouse leveraging extensive manufacturing networks. Braskem exemplifies a specialized bio-resin producer, controlling upstream material supply for bio-polyethylene. Mondi Group occupies a position as a flexible packaging innovator, integrating operations to offer advanced sustainable solutions. These firms anchor different segments of the value chain, from raw material production to finished pouch manufacturing. Their strategies reflect the market's emphasis on material innovation and supply chain resilience.
| Leading Market Players |
|---|
| Amcor Plc |
| Mondi Group |
| Sealed Air Corporation |
| Coveris Holdings S.A. |
| Berry Global Inc. |
| Braskem |
| Huhtamaki |
| UFlex |
| Novamont |
| Others |
Cost & Logistics Intelligence
Bio-ethylene feedstock prices, influenced by global sugarcane commodity markets, directly translate into cost variations for bio-PE resins, impacting final pouch pricing for brand owners. This upstream volatility often flows through the entire value chain, from resin producers to flexible packaging converters and ultimately to consumer goods manufacturers.
Pricing Analysis
Service-level agreements, including technical support for film conversion and regulatory compliance assistance, are often bundled with bio-PE resin contracts, especially for complex applications. The dominant pricing model is contract-based long-term offtake, securing supply for multinational consumer goods firms. Price differentiation stems from certification levels, such as US FDA food contact approval, and the volume scale of procurement. Pricing pressure stems from the higher cost of bio-based feedstocks compared to fossil-fuel alternatives. Eco-friendly brands are generally less price-sensitive, prioritizing sustainability messaging, while large consumer goods manufacturers seek economies of scale.
Supply Chain Analysis
Skilled labor availability in key manufacturing geographies like Brazil for bio-ethylene production and Germany for advanced pouch conversion influences operational efficiency. Supply chain concentration is significant, with Brazil providing a substantial portion of the world's sugarcane-based bio-ethylene. Key raw material dependencies include sugarcane-derived ethanol and specialized barrier materials like EVOH for high-performance films. Single-source vulnerability from Brazil's concentrated bio-ethylene production represents a structural risk. Distribution runs through direct contracts between bio-resin producers and flexible packaging converters, with integrated players like Mondi Group managing internal supply.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is framed by a vertical-integration race, with players actively pursuing upstream control over bio-resin production to secure feedstock and stabilize costs.
For Market Incumbents: Lock in long-term supply agreements for bio-ethylene with key producers to mitigate feedstock price volatility. Invest in advanced coextrusion film technologies to maintain a performance advantage against substitute materials like PLA. Leverage global manufacturing footprints to serve multinational clients, defending against regional niche players. This strategy helps counter the threat of new entrants focusing on specific application segments.
For New Entrants and Emerging Players: Begin with targeting high-value, non-food applications in the personal care sector where premium branding justifies higher material costs. Focus on developing second-generation bio-PE from non-food biomass to diversify feedstock sources. A compelling go-to-market angle involves clear, verifiable communication of carbon footprint reductions and circularity benefits to eco-conscious consumers and brands. This strategy allows penetration into segments less sensitive to initial cost premiums.
For Investors and Strategic Acquirers: New EU Packaging and Packaging Waste Regulation compliance deadlines are the leading indicator that will trigger significant capital expenditure in bio-based packaging solutions. The market exhibits long-term viability driven by escalating regulatory mandates and consumer demand for sustainable packaging over the next decade. Acquisition targets should include specialized bio-resin producers with diversified feedstock portfolios and innovative flexible packaging converters with strong R&D in high-barrier bio-PE films.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Bio-ethylene Production | Secures upstream material supply and reduces reliance on a concentrated geographic base. |
| Backward Integration into Sugarcane Sourcing | Stabilizes feedstock costs and ensures a consistent, verifiable renewable resource supply. |
| Green Manufacturing Transition for Converters | Enhances operational sustainability, meeting brand owner and regulatory environmental targets. |
| Long-term Supply Agreements for Bio-PE Resin | Provides supply chain stability for flexible packaging converters and consumer goods manufacturers. |
| Product Launch of High-Barrier Bio-PE Films | Expands bio-PE applications into oxygen-sensitive food and beverage categories, extending shelf life. |
Research Approach
Multi-period observation of bio-PE production capacities and regulatory compliance trends anchored the trend analysis, supplemented by interviews with bio-resin producers, packaging converters, brand sustainability managers, and regulatory compliance officers. Secondary validation involved extensive review of EU Green Deal reports, US FDA food contact substance notifications, customs trade data for bio-based materials, and corporate sustainability reports. This approach combined bottom-up market sizing with top-down validation of market drivers and restraints.
The forecast framework employed a segment-weighting approach, modeling market growth across product type, material composition, application, end-user industry, and regional regulatory impact over the projection horizon. Compound annual growth rates were derived from historical performance data, projected bio-PE production capacities, and anticipated shifts in sustainable packaging mandates. Key industry-specific forecast inputs included the projected adoption rates of bio-PE in food packaging and the expansion of industrial composting infrastructure.
Underlying measurement precision varies by segment; food packaging and personal care applications carry tighter precision than agricultural supplies. Forecasts reflect assumptions regarding feedstock availability and the evolution of recycling infrastructure. Feedstock price volatility and the pace of regulatory enforcement represent specific risk factors that could revise future projections. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Vietnam Pouch Packaging Market
Pouch
Pouch Dispensing Fitment Market
Pouch
OPP Pouches Market
Pouch
Telemetry Pouch Market
Pouch
Stand-Up Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Global Pouches Packaging Market
Pouch
Doy Pouch Packaging Market
Pouch
Monodose Packs Market
Pouch
Vacuum Chamber Pouches Market
Pouch
Saudi Arabia Pouch Packaging Market
Pouch
Peelable Pouches Market
Pouch
Europe Pouch Packaging Market
Pouch
Liquid Pouch Market
Pouch
Pouch Equipment Market
Pouch
Foil Zipper Bags Market