
 Stem Cell Therapy Market | 2026-2036
Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Stem Cell Therapy Market Analysis
Modular manufacturing platforms for cell expansion and cryopreservation is shifting procurement patterns among hospital buyers and contract manufacturers. Thermo Fisher Scientific leverages integrated bioprocessing workflows to anchor North American supply chains. Lonza Group sustains European dominance through specialized cell and gene therapy CDMO services. Merck KGaA competes on cell culture media portfolios that extend across both research and clinical-grade applications.
Stem cell therapy encompasses the therapeutic use of undifferentiated or partially differentiated cells capable of self-renewal and differentiation into specialized cell types, typically administered through ex vivo expansion in bioreactors followed by infusion or localized implantation. Its primary purpose centers on tissue regeneration, immune modulation, and functional restoration in degenerative diseases, hematologic malignancies, and genetic disorders. Adult stem cells occupy the largest revenue pool due to established clinical validation and lower tumorigenic risk profiles, while induced pluripotent stem cells represent the fastest-expanding segment as gene editing integration reduces immunogenicity barriers. Regenerative medicine applications command premium pricing compared to tissue engineering, where standardization challenges compress margins.
The FDA enforces current good manufacturing practice and regenerative medicine advanced therapy criteria that dictate facility design, donor screening protocols, and lot release testing timelines for commercial entry. The EMA's ATMP framework and Japan's PMDA conditional early approval system create divergent compliance burdens that shape regional manufacturing location decisions. Stakeholders must monitor evolving reimbursement pathways for allogeneic versus autologous products as payers scrutinize durable efficacy evidence.
Market Dynamics
Modular bioreactor platforms are compressing cell expansion timelines from weeks to days, forcing contract manufacturers to retool facilities or surrender hospital procurement contracts to integrated suppliers with captive bioprocessing capacity.
Growth Catalysts
- Regenerative Medicine Advanced Therapy Designation:The FDA's expedited review pathway compresses commercial entry timelines for autologous products, accelerating hospital adoption in the United States.
- Gene Editing Convergence:CRISPR integration with induced pluripotent stem cell workflows reduces immunogenicity barriers, expanding addressable patient populations beyond HLA-matched donors.
- Hematologic Malignancy Centers:Specialized cancer hospitals in Germany and Japan are consolidating stem cell transplantation volume, creating concentrated demand pools that justify dedicated manufacturing infrastructure.
Market Restraints
- Donor Material Volatility:Umbilical cord blood collection depends on live birth rates and procurement network density, creating input supply instability unrelated to manufacturing demand.
- Allogeneic Manufacturing Concentration:Master cell bank development and cryopreservation infrastructure clusters in Switzerland and Singapore, exposing supply chains to single-point-of-failure risks.
- Tumorigenicity Surveillance Burden:EMA's ATMP framework mandates extended patient follow-up protocols that extend cost recovery periods and deter early-stage investment.
Strategic Opportunities
- Point-of-Care Expansion Models:Hospital-based cleanroom mini-factories in the United States bypass centralized CDMO bottlenecks, capturing margin that currently flows to third-party manufacturers.
- Immunomodulation Applications:Graft-versus-host disease prophylaxis and autoimmune disorder protocols represent underpenetrated therapeutic categories with lower regulatory complexity than oncology indications.
- Japan's Conditional Early Approval:PMDA's regenerative medicine framework permits revenue generation during confirmatory trials, reducing capital requirements for product developers targeting the Japanese market.
Industry Challenges
- Cell Culture Scientist Scarcity:GMP-compliant bioprocessing expertise remains concentrated among a limited pool of professionals with experience in both academic stem cell biology and pharmaceutical manufacturing.
- Lot Release Testing Bottlenecks:Potency assay validation timelines frequently exceed cell product shelf life, forcing discard of viable doses and compressing effective manufacturing yield.
- Interoperability Friction:Electronic health record systems at transplant centers lack standardized data fields for cell therapy tracking, complicating chain-of-custody documentation required by national regulators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stem Cell Therapy Market |
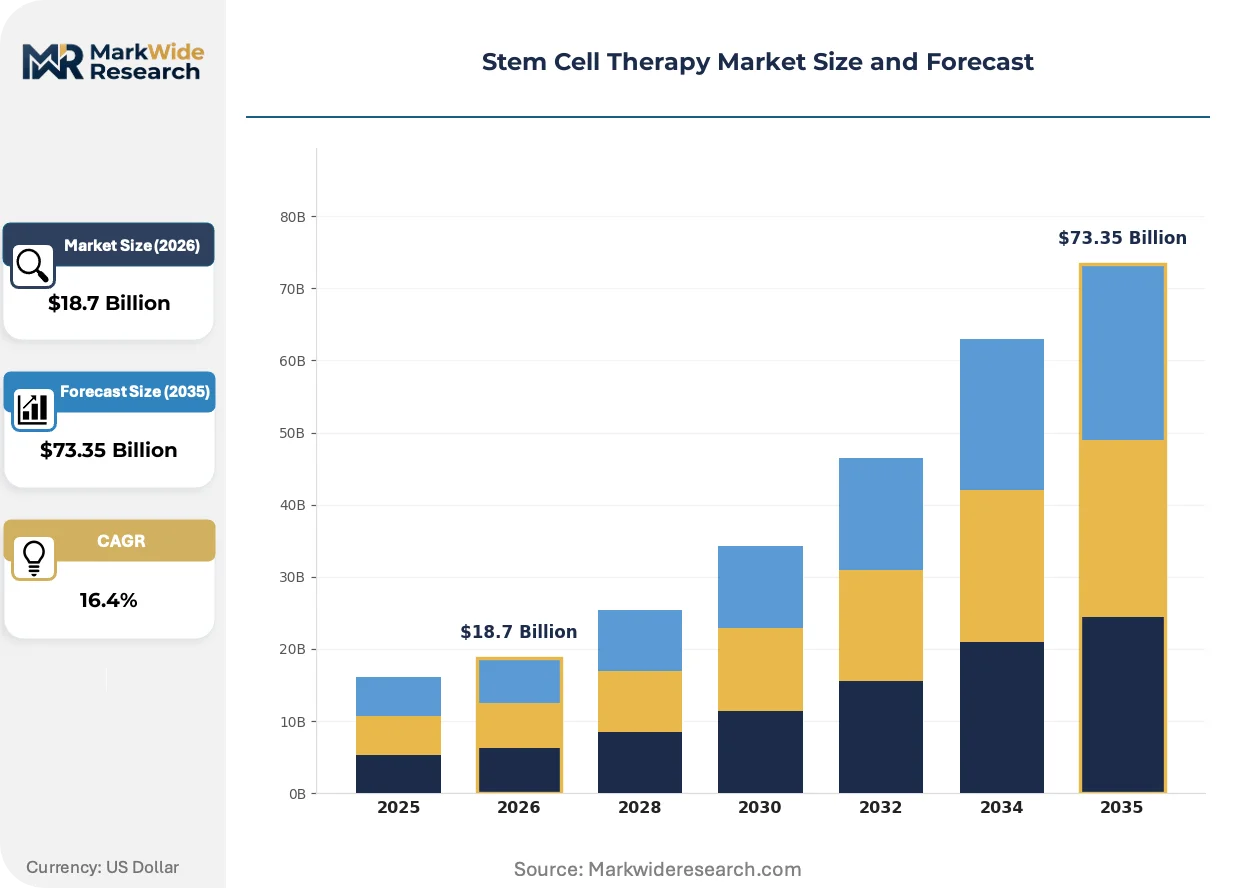
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Stem Cells, Embryonic Stem Cells, Induced Pluripotent Stem Cells, Cord Blood Stem Cells Application: Regenerative Medicine, Cell Therapy, Tissue Engineering, Cancer Treatment End User: Hospitals, Research Institutes, Academic Institutions, Pharmaceutical Companies Technology: Transplantation Techniques, Cell Culture Technology, Gene Editing, Bioprocessing Technology |
| Companies Covered | Thermo Fisher Scientific, Lonza Group, Merck KGaA, Lineage Cell Therapeutics, Mesoblast, STEMCELL Technologies, Miltenyi Biotec, Becton, Dickinson and Company, BrainStorm Cell Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stem Cell Therapy Market Emerging Trajectories
Closed-system automation is displacing open-manipulation workflows across cell therapy manufacturing, with implications for facility capital requirements, contamination risk profiles, and the geographic distribution of production capacity.
Perfusion bioreactor technology is integrating continuous media exchange with real-time metabolite monitoring, enabling higher cell densities than batch expansion protocols. Academic medical centers in the United States are piloting these systems for chimeric antigen receptor T-cell production. The technology is integrating process analytical technology standards that compress lot-to-lot variability and reduce downstream purification burden.
EMA's revised ATMP classification criteria are clarifying borderline products between tissue-engineered substances and cell-based medicinal products, reducing regulatory uncertainty for developers of combination products. Manufacturers must now pre-submit classification requests before clinical trial initiation, adding procedural steps but preventing costly pathway misalignment. European contract development organizations report diverting resources from technical development to regulatory strategy as a consequence.
Hospital procurement committees are consolidating vendor relationships for autologous cell services, replacing fragmented supplier networks with single-source agreements that bundle collection, processing, and cryostorage. Transplant centers in Germany are leading this consolidation, driven by joint purchasing alliances that aggregate volume across multiple hospital systems. The shift pressures smaller regional cell processing laboratories to affiliate with national networks or exit the market entirely.
Stem Cell Therapy Market Segmentation
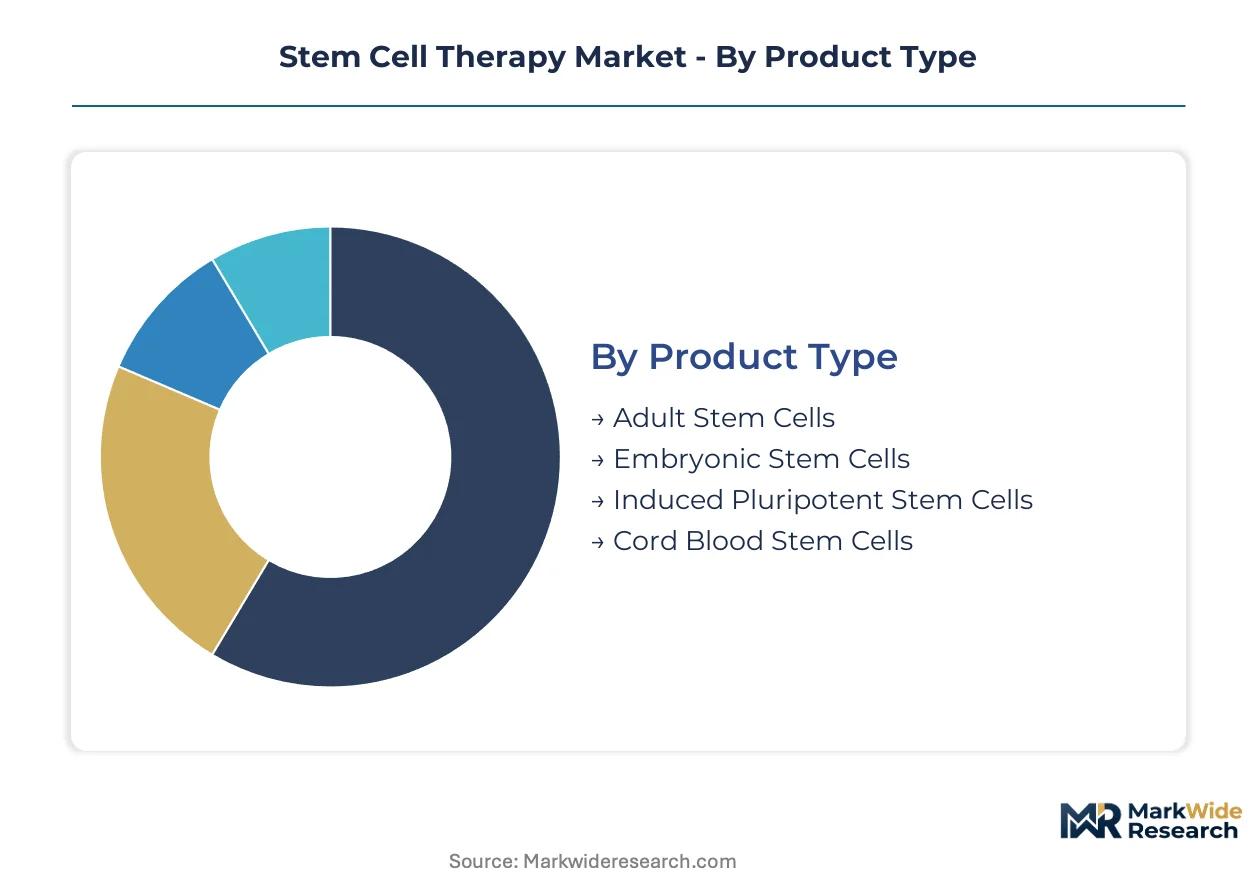
Stem cell therapy segmentation reveals divergent regulatory pathways that dictate facility investment, reimbursement eligibility, and commercialization timelines. Product type classifications determine whether developers pursue autologous or allogeneic manufacturing strategies, while application segments carry distinct FDA and EMA approval burdens.
Product Type:
FDA regenerative medicine advanced therapy designation applies differentially across cell sources, with autologous products qualifying for expedited review while allogeneic master cell banks trigger extended donor screening protocols.
- Adult Stem Cells:Derived from bone marrow, adipose tissue, and peripheral blood with established extraction protocols. Demand concentrates in United States hematologic malignancy centers where Medicare reimbursement pathways for autologous transplantation are codified. Manufacturing yields remain constrained by donor variability and expansion timelines.
- Induced Pluripotent Stem Cells:Somatic cell reprogramming enables patient-specific therapies without embryonic sourcing. Japanese academic medical centers and German research consortia drive clinical translation as CRISPR integration reduces immunogenicity screening burdens.
- Embryonic Stem Cells:Pluripotent lines from blastocyst-stage embryos retain broad differentiation potential. Ethical restrictions limit procurement networks primarily to jurisdictions with permissive oversight frameworks.
- Cord Blood Stem Cells:Hematopoietic progenitors collected at birth require cryogenic infrastructure and HLA-typing registries. Supply volatility from live birth rate fluctuations creates inventory management challenges unrelated to therapeutic demand.
Leading the category by volume: Adult Stem Cells. Growing fastest: Induced Pluripotent Stem Cells.
Application:
Cost tier stratification separates premium-priced regenerative indications from commoditized tissue engineering contracts, with oncology applications commanding reimbursement multiples over wound care.
- Regenerative Medicine:Functional restoration in degenerative conditions including Parkinson's disease and heart failure. Swiss and Singaporean contract manufacturers capture premium margins through GMP-compliant expansion services for cardiac cell therapies.
- Cancer Treatment:Hematopoietic stem cell transplantation and emerging CAR-T protocols. German hospital alliances consolidate procurement volume, creating concentrated demand pools that justify dedicated cleanroom infrastructure.
- Cell Therapy:Direct cellular administration for immune modulation and genetic disorder correction. EMA's ATMP framework mandates extended follow-up protocols that extend cost recovery periods.
- Tissue Engineering:Scaffold-integrated cellular constructs for bone and cartilage repair. Standardization challenges compress margins compared to standalone cell products.
Highest reimbursement tier: Regenerative Medicine. Steepest expansion trajectory: Cancer Treatment.
End User:
Customer type determines procurement scale, with hospital networks demanding integrated service bundles versus research institutes prioritizing technical flexibility over cost efficiency.
- Hospitals:Transplant centers and specialized cancer units in the United States and Germany. Joint purchasing alliances aggregate volume across health systems, pressuring smaller processing laboratories to affiliate with national networks.
- Research Institutes:Preclinical and early-phase clinical investigation facilities. Academic medical centers pilot perfusion bioreactor systems for chimeric antigen receptor T-cell production.
- Academic Institutions:University-affiliated laboratories focused on foundational stem cell biology. Training pipelines for GMP-compliant bioprocessing expertise remain underdeveloped relative to manufacturing demand.
- Pharmaceutical Companies:Sponsored clinical trials and commercial manufacturing partnerships. Thermo Fisher Scientific and Lonza Group anchor supply relationships through integrated bioprocessing workflows.
Dominant procurement volume: Hospitals. Fastest-growing engagement: Pharmaceutical Companies.
Technology:
Supply concentration in bioprocessing equipment creates vendor lock-in risks, with modular platform adoption determining facility capital requirements and contamination risk profiles.
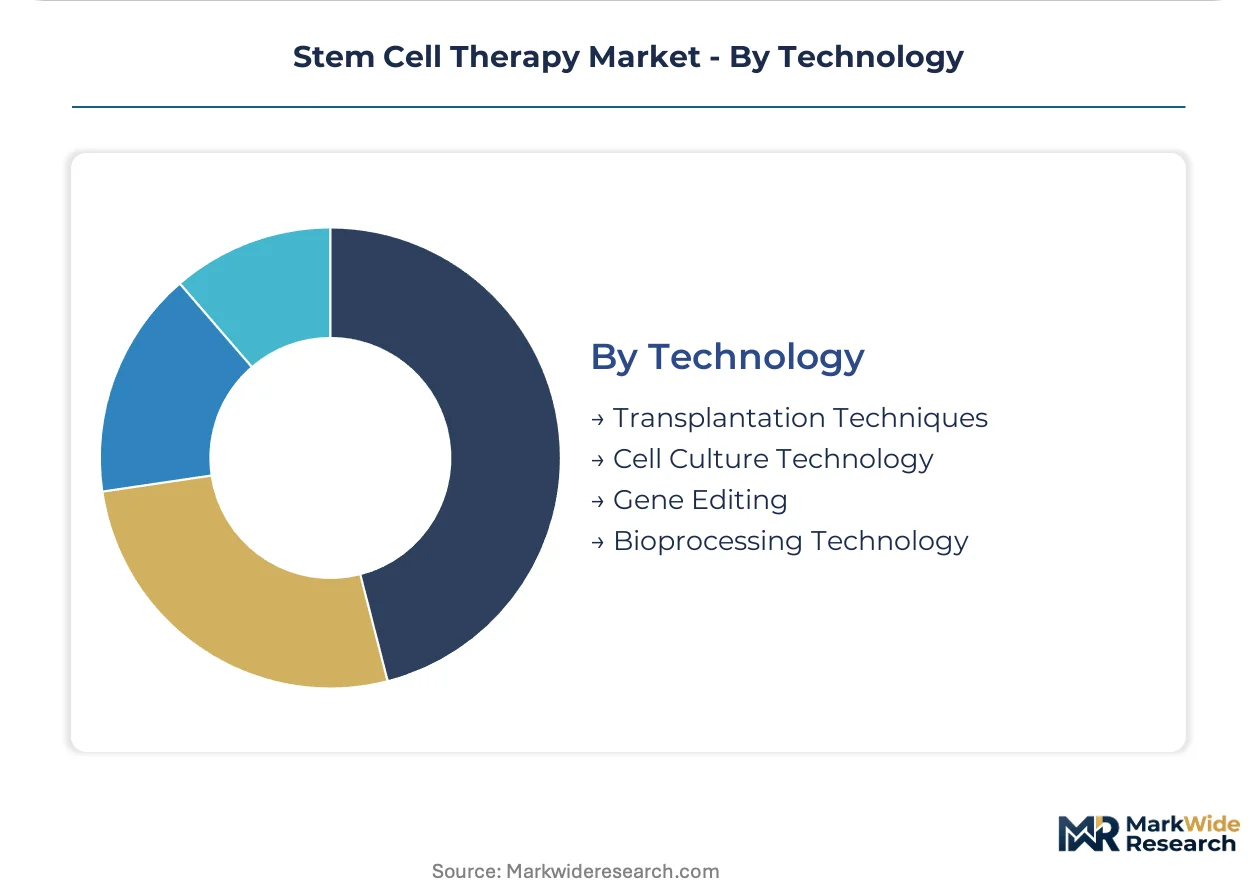
- Bioprocessing Technology:Closed-system automation and continuous media exchange systems. Real-time metabolite monitoring enables higher cell densities than batch expansion protocols.
- Gene Editing:CRISPR-Cas9 integration with stem cell workflows. Reduces immunogenicity barriers and expands addressable patient populations beyond HLA-matched donors.
- Cell Culture Technology:Expansion media, growth factor formulations, and substrate optimization. Merck KGaA competes on portfolios spanning research and clinical-grade applications.
- Transplantation Techniques:Infusion protocols, localized implantation, and surgical delivery methods. Standardization lags behind manufacturing process development.
Widest installed base: Bioprocessing Technology. Gaining share fastest: Gene Editing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Switzerland and Singapore while consumption clusters in United States hospital networks and German cancer centers. This divergence creates logistics-intensive supply chains spanning cryogenic transport corridors. Regulatory fragmentation across FDA, EMA, and PMDA frameworks compounds cross-border distribution complexity.
United States
Specialized cancer hospitals and transplant centers drive autologous procedure volume. The FDA's regenerative medicine advanced therapy designation compresses commercial entry timelines for qualifying products. Hospital-based cleanroom mini-factories in Boston and Houston bypass centralized manufacturing bottlenecks.
Germany
Hematologic malignancy centers consolidate stem cell transplantation volume into concentrated demand pools. The EMA's ATMP framework mandates extended patient follow-up protocols that extend cost recovery periods. Joint purchasing alliances across hospital systems in Bavaria and North Rhine-Westphalia pressure smaller processing laboratories to affiliate with national networks.
Japan
Academic medical centers pioneer induced pluripotent stem cell clinical translation. The PMDA's conditional early approval system permits revenue generation during confirmatory trials. Research consortia in Kanto and Kansai regions reduce capital requirements for product developers targeting domestic markets.
Switzerland
Master cell bank development and cryopreservation infrastructure clusters expose supply chains to single-point-of-failure risks. Swissmedic enforces GMP standards that dictate facility design and lot release testing timelines. Contract manufacturers in Basel and Zurich capture premium margins through GMP-compliant expansion services.
Singapore
Allogeneic manufacturing concentration creates strategic vulnerability for Asia-Pacific supply security. The national pharmaceutical regulator enforces donor screening protocols aligned with international standards. Bioprocessing facilities in the biomedical sciences corridor serve as regional distribution hubs for clinical-grade cell products.
Stem Cell Therapy Market Vendor Landscape
The competitive structure tilts toward integrated bioprocessing suppliers with captive manufacturing capacity. Tiered specialization separates research-grade reagent providers from clinical-grade service organizations. Three archetypes dominate: diversified life science conglomerates with cell therapy divisions, pure-play cell and gene therapy CDMOs, and specialized cell culture media suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as hospital procurement committees consolidate vendor relationships.
Within the integrated supplier tier, Thermo Fisher Scientific and Lonza Group exemplify divergent geographic anchoring strategies. Thermo Fisher Scientific occupies a position tied to North American hospital network procurement patterns. Lonza Group sits within the European CDMO specialization vector. Merck KGaA represents the reagent and media portfolio archetype spanning research and clinical applications.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza Group |
| Merck KGaA |
| Lineage Cell Therapeutics |
| Mesoblast |
| STEMCELL Technologies |
| Miltenyi Biotec |
| Becton, Dickinson and Company |
| BrainStorm Cell Therapeutics |
| Others |
Supply Flow & Price Mechanics
EMA's ATMP framework compliance mandates gate both qualified supply access and premium-tier pricing eligibility for commercial cell therapy products. Hospital procurement committees in Germany and the United States now require documented GMP certification and extended patient follow-up protocols as baseline qualification criteria, compressing margins for non-compliant manufacturers while enabling compliant players to command service premiums.
Pricing Analysis
Margin tightening in autologous cell processing reflects hospital procurement consolidation into joint purchasing alliances across German and United States health systems. Three-tier pricing structure across premium GMP-certified, standard clinical-grade, and research-grade levels separates regenerative medicine applications from commoditized tissue engineering contracts. Cost-down pressure on allogeneic master cell bank services accelerates because payer scrutiny of durable efficacy evidence extends reimbursement timelines. Academic medical centers exhibit highest price sensitivity due to grant-dependent budgets, while specialized cancer hospitals in Japan demonstrate lowest sensitivity given PMDA conditional early approval revenue generation pathways.
Supply Chain Analysis
Dual-sourcing requirements for cryopreservation media and growth factor formulations now dominate hospital procurement committee mandates in North America and Europe. Manufacturing capacity concentrates in Switzerland, Singapore, and Germany, with umbilical cord blood collection networks anchored in United States birth centers and Japanese tissue banks. Raw material dependencies center on fetal bovine serum alternatives, recombinant growth factors, and clinical-grade bioreactor consumables. Single-point-of-failure risk exposure clusters in Swiss master cell bank infrastructure. Distribution runs through cryogenic logistics corridors connecting Basel and Zurich manufacturing hubs to transplant centers in Boston, Houston, and Munich.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Stem Cell Therapy Market operates as a cost-of-compliance story where FDA regenerative medicine advanced therapy designation creates a barrier-to-entry moat for compliant players. EMA's ATMP framework mandates extend cost recovery periods and deter early-stage investment, concentrating viable manufacturing capacity among established GMP-certified organizations.
For Market Incumbents: Lock in hospital procurement relationships through integrated bioprocessing service bundles that combine collection, expansion, and cryostorage. Defend against modular bioreactor platform disruption by anchoring captive manufacturing capacity in Boston and Houston cleanroom mini-factories. Prioritize gene editing integration investments to reduce immunogenicity screening burdens and expand addressable patient populations beyond HLA-matched donors. For New Entrants and Emerging Players: Begin with Japan's PMDA conditional early approval pathway to generate revenue during confirmatory trials and reduce capital requirements. Target immunomodulation applications for graft-versus-host disease prophylaxis as the most penetrable therapeutic category with lower regulatory complexity than oncology indications. Pursue point-of-care expansion models through hospital-based cleanroom mini-factory partnerships that bypass centralized CDMO bottlenecks. For Investors and Strategic Acquirers: FDA regenerative medicine advanced therapy designation acceleration announcements are the leading indicator that commercial entry timelines for autologous products are compressing and hospital adoption curves are steepening. Frame long-term viability around five-to-ten year windows where reimbursement pathway consolidation favors integrated suppliers with captive bioprocessing capacity. Target acquisition profiles toward pure-play cell and gene therapy CDMOs with established GMP-compliant expansion services. Watch potency assay validation timeline reductions as the critical inflection signal for manufacturing yield improvements.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses commercial entry timelines for qualifying autologous products. |
| Manufacturing Scale-Up | Modular bioreactor platform adoption reduces cell expansion timelines from weeks to days in hospital cleanroom facilities. |
| Strategic Partnership | Joint purchasing alliances across German hospital systems aggregate procurement volume and pressure smaller processing laboratories. |
| Backward Integration | Cryopreservation infrastructure ownership in Switzerland and Singapore reduces single-point-of-failure supply chain exposure. |
| Pipeline Diversification | Immunomodulation applications for autoimmune disorders expand addressable markets beyond hematologic malignancy centers. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov records formed the secondary backbone of data collection, supplemented by formulary database reviews and hospital procurement contract analyses. Primary interviews with cell therapy manufacturing executives, regulatory affairs leads, hospital procurement managers, and GPO contracts managers validated secondary findings and informed demand-side assumptions. Bottom-up and top-down triangulation cross-referenced manufacturing capacity data with patient volume projections across transplant centers.
Bottom-up modeling anchored volume and value outputs to facility-level production capacity, patient population incidence, and reimbursement pathway maturation across the projection horizon. Segmentation dimensions included cell source type, application category, end-user archetype, and regional regulatory cluster. CAGRs were derived from spline interpolation of annual capacity expansion announcements and patient volume growth trajectories. Forecast inputs incorporated perfusion bioreactor adoption curves and gene editing integration timelines.
Underlying measurement precision varies by segment; autologous adult stem cell applications carry tighter precision than emerging induced pluripotent stem cell indications due to established Medicare reimbursement codification. Forecasts reflect assumptions around regulatory approval acceleration, hospital procurement consolidation trajectories, and cryogenic logistics infrastructure expansion. Deviation in FDA regenerative medicine advanced therapy designation grant rates or EMA ATMP framework enforcement stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market