
 Global Stem Cells Market | 2026-2036
Global Stem Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Global Stem Cells Market Outlook
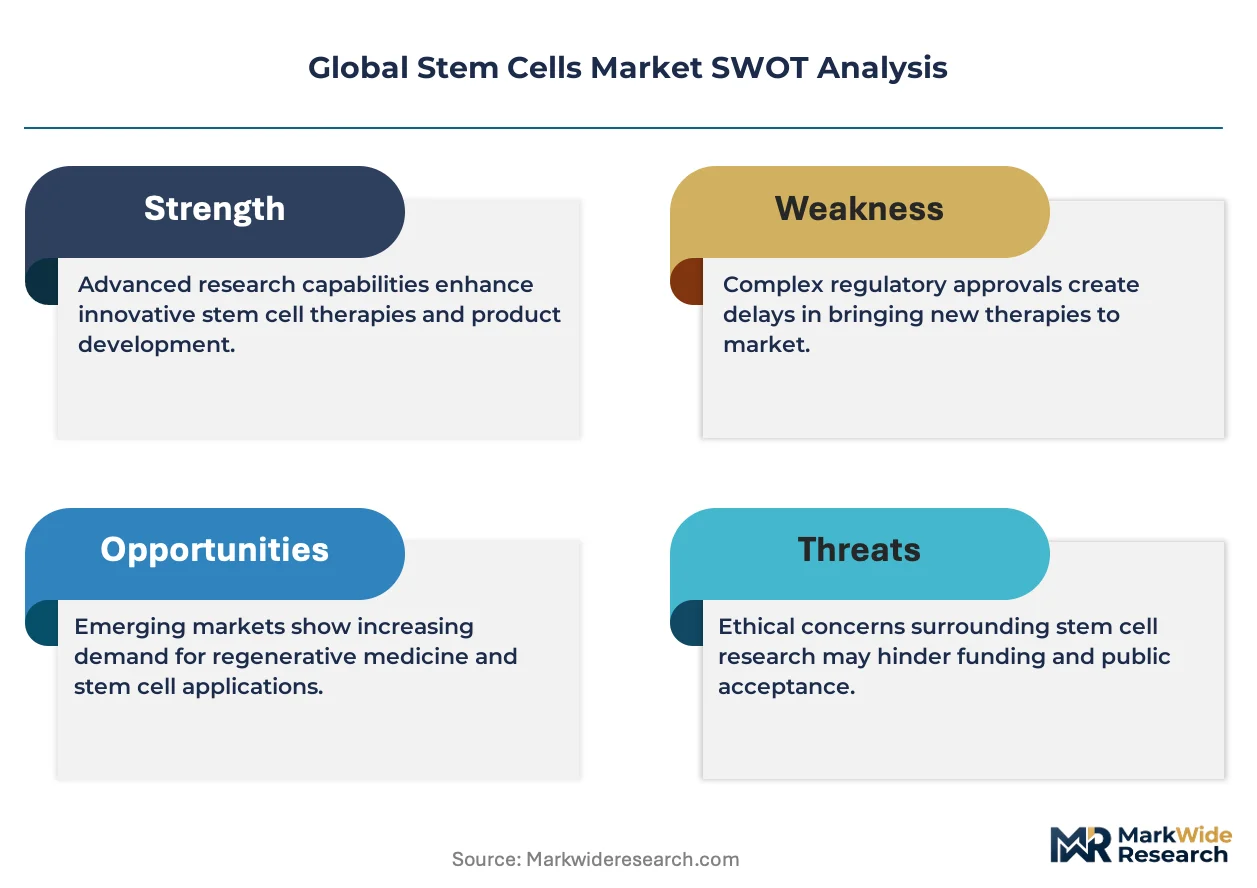
Good Manufacturing Practice certification for cell therapy production is bifurcating the competitive landscape into qualified and non-qualified suppliers. Thermo Fisher Scientific leverages its end-to-end cell culture media and instrumentation portfolio to anchor high-volume contract manufacturing relationships. Lonza dominates specialized bioreactor platforms for adherent stem cell expansion, while Fate Therapeutics differentiates through induced pluripotent stem cell-derived natural killer cell programs.
Stem cells are undifferentiated biological cells capable of self-renewal and differentiation into specialized cell types, typically maintained in defined culture media supplemented with growth factors such as FGF-2 and EGF at precise concentrations. Their primary commercial purpose centers on generating functional tissues for therapeutic implantation, disease modeling for pharmaceutical screening, and personalized cell-based interventions. Adult stem cells occupy the largest revenue share given established clinical utility in hematopoietic transplantation, while induced pluripotent stem cells represent the fastest-expanding category as reprogramming efficiencies improve and allogeneic platforms reduce immunogenicity risks. Cell therapy applications command premium pricing relative to drug discovery tools due to regulatory complexity and patient-specific manufacturing requirements.
The FDA's regenerative medicine advanced therapy designation and the EU's MDR framework for cell-based medicinal products create divergent compliance burdens that shape market access timelines and capital deployment. Japan's PMDA operates an accelerated conditional approval pathway for regenerative medicines that has attracted substantial foreign clinical investment. Stakeholders must monitor evolving reimbursement decisions for chimeric antigen receptor T-cell therapies and next-generation allogeneic products across the United States, Germany, and Japan to anticipate which manufacturing scales and partnership models will prove commercially viable.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing approval timelines for cell-based therapies, creating a bifurcation between manufacturers capable of meeting accelerated compliance standards and those locked out of premium reimbursement tiers.
Growth Catalysts
- Japan's PMDA conditional approval pathway:Foreign sponsors now route pivotal trials through Tokyo to secure earlier commercialization windows for allogeneic platforms.
- Hematopoietic transplantation protocols:Adult stem cell grafts for oncology indications command established reimbursement codes across Germany and the United States.
- Bioreactor automation:Closed-system manufacturing for adherent cell expansion cuts contamination risk and batch failure rates.
Market Restraints
- Fetal bovine serum price volatility:Defined culture media formulations face input cost spikes when serum supply tightens.
- Single-source bioreactor dependency:Swiss and German equipment suppliers control specialized hardware for induced pluripotent stem cell scale-up.
- EU MDR technical documentation burdens:Cell-based medicinal product classifications trigger extended notified body review cycles.
Strategic Opportunities
- South Korean manufacturing partnerships:MFDS-aligned facilities offer lower-cost GMP certification for export to ASEAN markets.
- Cardiac patch implantation:Differentiated cardiomyocyte therapies for heart failure represent underdeveloped therapeutic categories.
- AI-driven cell sorting:Machine vision integration with flow cytometry is compressing quality control labor intensity.
Industry Challenges
- Cell therapy process engineer scarcity:GMP-compliant aseptic technique training programs graduate fewer candidates than manufacturing expansion requires.
- Legacy electronic batch record migration:Paper-based systems at established blood centers resist integration with cloud-based manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Stem Cells Market |
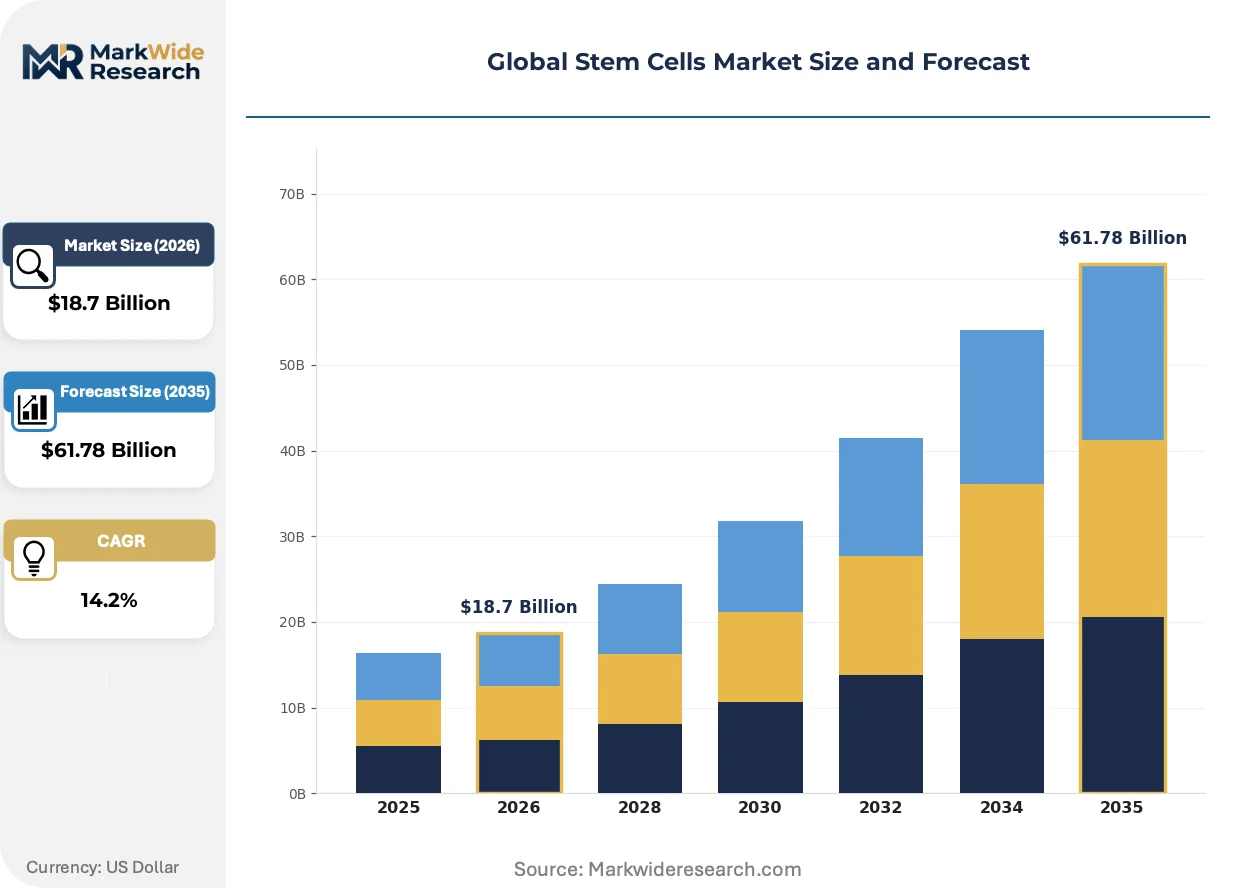
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embryonic Stem Cells, Adult Stem Cells, Induced Pluripotent Stem Cells, Cord Blood Stem Cells Application: Regenerative Medicine, Drug Discovery, Clinical Research, Cell Therapy End User: Research Institutions, Biotechnology Companies, Pharmaceutical Firms, Hospitals Technology: Stem Cell Banking, Isolation Techniques, Expansion Techniques, Preservation Techniques |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, STEMCELL Technologies, Lonza, Bio-Techne, Miltenyi Biotec, Sartorius AG, PromoCell, Fate Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Stem Cells Market Strategic Shifts
Automation and closed-system processing are compressing the labor intensity of cell therapy manufacturing while regulatory convergence around expedited pathways is reshaping where clinical trials locate.
Microfluidic cell culture platforms are miniaturizing bioprocessing footprints for point-of-care manufacturing. Regional hospital networks in Germany and Japan are piloting bedside bioreactor systems to cut cold chain logistics costs. This distributed production model is miniaturizing the economic minimum scale for viable cell therapy operations.
REACH substance restrictions on dimethyl sulfoxide cryoprotectants are forcing reformulation of cell preservation media. European manufacturers are validating propylene glycol alternatives ahead of 2026 sunset clauses. Cryopreservation-dependent allogeneic inventory models face the steepest compliance recertification burdens.
Hospital procurement departments are consolidating cell therapy vendor panels to reduce qualification overhead. Academic medical centers in the United States now require single-source contracts covering media, instrumentation, and training. This buyer concentration is squeezing mid-tier suppliers without end-to-end portfolios.
Global Stem Cells Market Segmentation
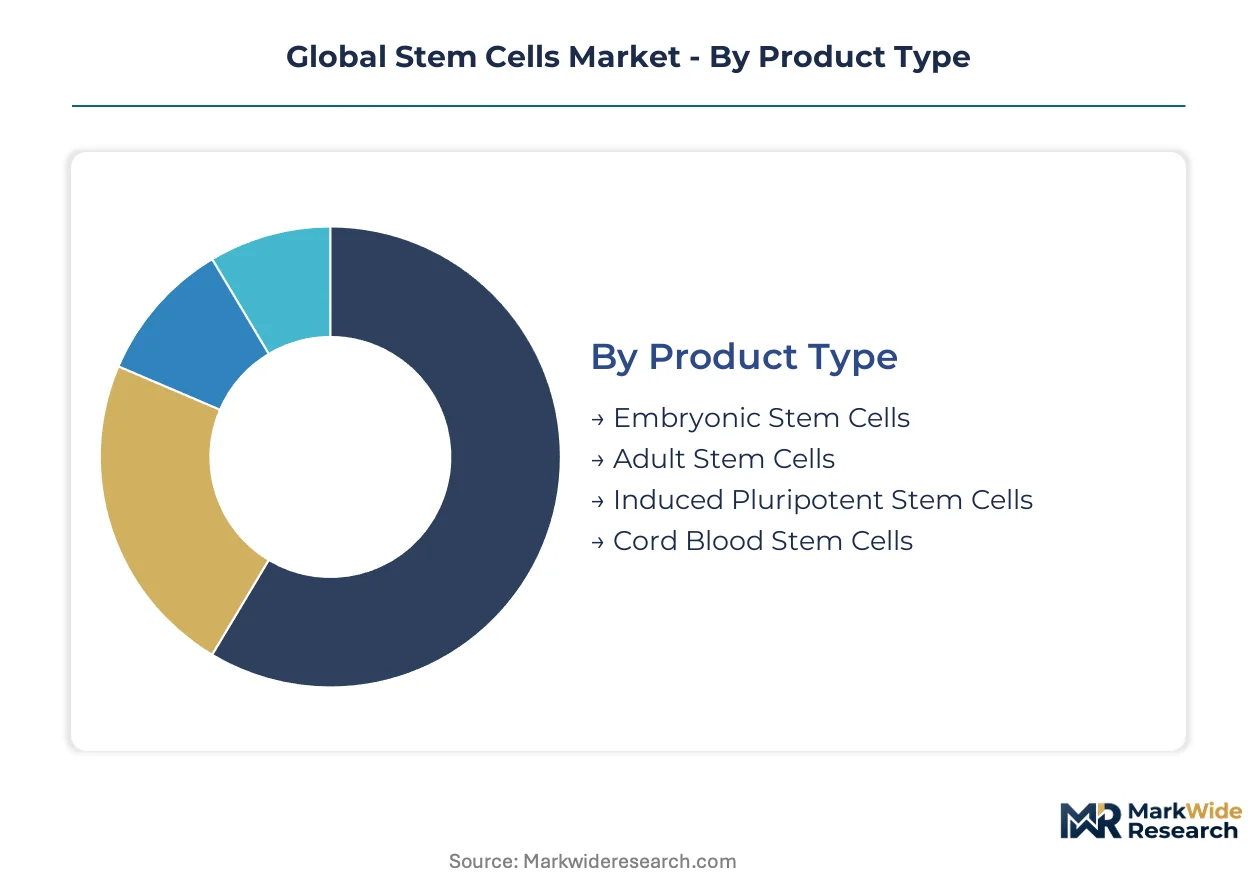
Segmentation in the stem cells market reveals distinct procurement patterns across therapeutic versus research applications. Each category carries divergent regulatory burdens, pricing structures, and geographic demand concentrations that shape supplier strategies.
Product Type:
Domestic production dominates adult stem cell supply chains, while induced pluripotent stem cells flow through export-led manufacturing networks centered in Japan and South Korea.
- Embryonic Stem Cells:Derived from blastocyst-stage embryos with pluripotent differentiation capacity. Ethical review board restrictions in Germany and the United States limit institutional procurement to federally approved lines.
- Adult Stem Cells:Multipotent progenitor cells sourced from bone marrow, adipose tissue, and peripheral blood. Hematopoietic transplantation protocols in the United States and Germany sustain established reimbursement pathways.
- Induced Pluripotent Stem Cells:Somatic cell reprogramming eliminates embryonic sourcing constraints. Japan's PMDA conditional approval pathway accelerates allogeneic platform commercialization.
- Cord Blood Stem Cells:Harvested from umbilical cord tissue at birth. Public banking infrastructure in France and Spain supports autologous therapeutic reserves.
Adult stem cells hold the largest share; momentum sits with induced pluripotent stem cells.
Application:
Cost tier stratification separates premium-priced cell therapy applications from standardized drug discovery tools.
- Regenerative Medicine:Tissue engineering and organ replacement therapies command the highest manufacturing complexity. Cardiovascular patch implantation programs in Germany and Japan attract specialized capital deployment.
- Drug Discovery:Disease modeling platforms screen pharmaceutical candidates against patient-derived cell lines. Contract research organizations in South Korea and Singapore consolidate high-throughput screening demand.
- Clinical Research:Academic medical centers in the United States and the United Kingdom drive investigator-initiated trial demand.
- Cell Therapy:Chimeric antigen receptor and natural killer cell manufacturing requires GMP-certified aseptic processing. FDA regenerative medicine advanced therapy designation compresses approval timelines for qualified sponsors.
Regenerative medicine commands premium pricing; cell therapy is expanding most quickly.
End User:
Customer type determines contract structure — research institutions favor reagent subscriptions while hospitals negotiate outcome-based procurement.
- Research Institutions:University laboratories and academic medical centers purchase small-batch media and characterization tools. NIH grant funding cycles in the United States drive seasonal procurement spikes.
- Biotechnology Companies:Venture-backed cell therapy developers outsource manufacturing to contract development organizations. Series C financing rounds in Boston and San Francisco correlate with bioreactor equipment orders.
- Pharmaceutical Firms:Large-cap drug manufacturers acquire stem cell platforms to replenish pipeline gaps. Swiss and German headquarters control global sourcing decisions.
- Hospitals:Academic medical centers in the United States and Japan integrate point-of-care bioreactor systems for autologous cell processing.
Biotechnology companies drive volume growth; hospitals represent the steepest expansion trajectory.
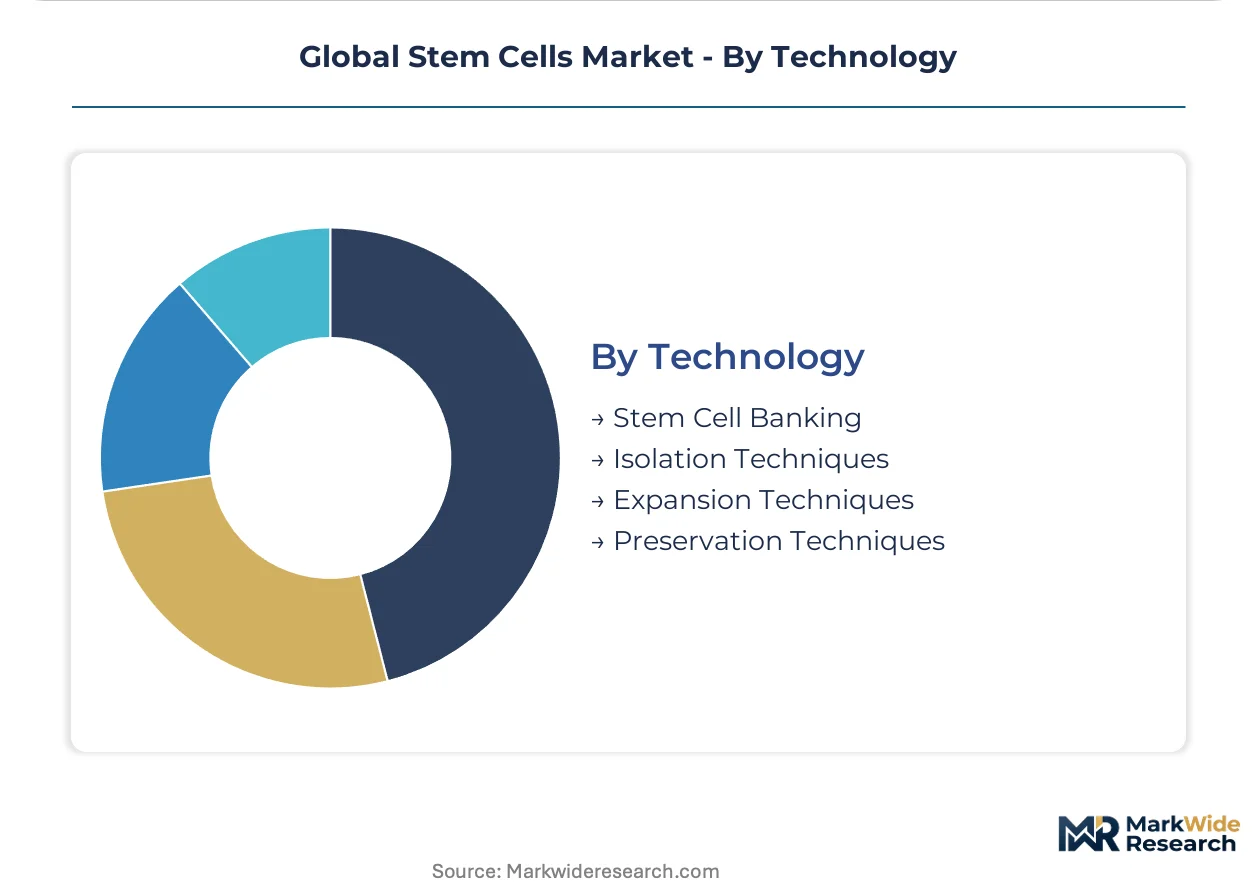
Technology:
Supply concentration in Swiss and German equipment vendors shapes access to specialized bioreactor hardware.
- Stem Cell Banking:Cryopreservation facilities maintain allogeneic inventory for therapeutic distribution. REACH substance restrictions on dimethyl sulfoxide force European operators toward propylene glycol reformulation.
- Isolation Techniques:Density gradient centrifugation and magnetic-activated cell sorting separate target populations. Automation reduces labor intensity in high-throughput clinical applications.
- Expansion Techniques:Adherent culture in bioreactors versus suspension systems determines scale-up economics. Lonza dominates specialized platforms for induced pluripotent stem cell manufacturing.
- Preservation Techniques:Controlled-rate freezing and vitrification maintain cell viability during storage. Asian banking networks in Singapore and South Korea invest in automated cryogenic infrastructure.
Expansion techniques anchor manufacturing economics; stem cell banking is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic logistics corridors linking Frankfurt, Tokyo, and Boston anchor the intercontinental distribution of stem cell therapies. These specialized cold-chain networks enable just-in-time delivery of living cell products with viability windows measured in hours.
United States
Academic medical centers in Boston and San Francisco drive investigator-initiated trial demand for induced pluripotent stem cell platforms. The FDA's regenerative medicine advanced therapy designation compresses approval timelines for qualified sponsors. NIH grant funding cycles create seasonal procurement spikes at university laboratories.
Germany
Cardiovascular patch implantation programs in Berlin and Heidelberg attract specialized capital deployment for differentiated cardiomyocyte therapies. The EMA's centralized marketing authorization procedure governs cell-based medicinal product approvals across member states. Lonza dominates specialized bioreactor platforms for adherent stem cell expansion from Basel.
Japan
Foreign sponsors route pivotal trials through Tokyo to secure earlier commercialization windows for allogeneic platforms. The PMDA's conditional approval pathway for regenerative medicines compresses time-to-market for qualified cell therapies. Osaka-based hospital networks pilot bedside bioreactor systems for point-of-care manufacturing.
South Korea
MFDS-aligned GMP facilities offer lower-cost certification for export to ASEAN markets. The national pharmaceutical regulator enforces harmonized standards with ICH guidelines for cell therapy manufacturing. Seoul-based contract development organizations consolidate high-throughput screening demand from multinational pharmaceutical clients.
Switzerland
Specialized bioreactor hardware suppliers in Basel and Zurich control critical equipment for induced pluripotent stem cell scale-up. Swissmedic operates accelerated assessment pathways for regenerative medicines with breakthrough potential. The country's precision manufacturing cluster supplies closed-system automation to global cell therapy producers.
Global Stem Cells Market Competitive Environment
Listed leaders compete with private specialists across capital access and strategic flexibility dimensions. Thermo Fisher Scientific leverages public market financing to anchor high-volume contract manufacturing relationships, while private specialists such as STEMCELL Technologies retain operational agility in niche media formulations. Three archetypes dominate: diversified life science conglomerates with end-to-end portfolios, specialized bioprocessing equipment vendors, and cell therapy developers with proprietary platform technologies. Competitive moves concentrate on strategic partnerships for manufacturing capacity and geographic expansion into Asian regulatory jurisdictions.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven positioning through integrated cell culture media and instrumentation portfolios. Lonza occupies a specialized position in bioreactor platforms for adherent cell expansion. Fate Therapeutics represents the cell therapy developer archetype, differentiating through induced pluripotent stem cell-derived programs.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| STEMCELL Technologies |
| Lonza |
| Bio-Techne |
| Miltenyi Biotec |
| Sartorius AG |
| PromoCell |
| Fate Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Bioreactor capacity utilization above 80 percent in Swiss and German facilities creates steep scale economies that lock in price floors for GMP-certified stem cell media and instrumentation. This concentration of qualified manufacturing capacity simultaneously limits supply-side competition and anchors premium pricing tiers for contract development organizations.
Pricing Analysis
Volume-discount tiering structures separate procurement contracts for academic research institutions from hospital-based cell therapy programs. Three-tier pricing stratifies across FDA regenerative medicine advanced therapy designation holders, standard GMP-compliant manufacturers, and non-certified research-grade suppliers. Cost compression in the research-grade tier intensifies as hospital procurement departments consolidate vendor panels. Academic medical centers in the United States exhibit highest price sensitivity due to NIH grant funding cycles, while Japanese allogeneic platform developers accept premium pricing for accelerated PMDA pathway access.
Supply Chain Analysis
Switzerland and Germany anchor specialized bioreactor hardware production for adherent stem cell expansion, while South Korea and Japan dominate induced pluripotent stem cell-derived media formulation. Supply chains draw from fetal bovine serum markets concentrated in Australia and New Zealand, plus growth factor production anchored in Singapore. Single-source dependency on Swiss equipment vendors creates vulnerability to export license delays. Distribution runs through cryogenic logistics corridors linking Frankfurt, Tokyo, and Boston for time-sensitive cell therapy delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stem cells market rewards organizations that command scarce GMP-compliant aseptic processing capabilities and closed-system manufacturing expertise. Cell therapy process engineer shortages outpace training program output across the United States, Germany, and Japan.
For Market Incumbents: Fortify manufacturing capacity in PMDA-aligned jurisdictions to capture conditional approval pathway demand. Lock in multi-year media supply contracts with South Korean MFDS-certified facilities before ASEAN export volumes accelerate. Prioritize backward integration into defined culture media formulation to offset fetal bovine serum price volatility. For New Entrants and Emerging Players: Differentiate on AI-driven cell sorting integration with flow cytometry platforms to compress quality control labor intensity. Cardiac patch implantation programs in Germany and Japan represent underpenetrated therapeutic categories with specialized capital requirements. Pursue hospital procurement panel qualification through bundled media-instrumentation-training contracts. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among contract development organizations with embedded bioreactor automation platforms and multi-site GMP certification. Five-to-ten year viability hinges on regulatory pathway diversification across FDA, EMA, and PMDA jurisdictions. Target acquisition archetypes combine Swiss or German equipment expertise with Asian manufacturing partnerships. Monitor reimbursement decisions for next-generation allogeneic products across United States, Germany, and Japan as inflection signals for manufacturing scale economics.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Closed-system bioreactor automation cuts contamination risk for Fate Therapeutics-style allogeneic platforms. |
| Regulatory Approval Pathway | PMDA conditional approval compresses time-to-market for qualified sponsors versus FDA standard review. |
| Strategic Partnership | Lonza-Thermo Fisher style alliances anchor high-volume contract manufacturing with specialized hardware. |
| Geographic Expansion | MFDS-aligned South Korean facilities offer lower-cost GMP certification for ASEAN market access. |
| Pipeline Diversification | Cardiomyocyte therapy programs reduce dependence on hematopoietic transplantation reimbursement codes. |
Study Parameters
Initial hypotheses were tested against primary input from cell therapy process engineers, regulatory affairs leads at FDA and PMDA, hospital procurement managers, and contract development organization executives and refined through secondary validation. Bottom-up demand modeling drew from ClinicalTrials.gov regenerative medicine trial registrations, EMA centralized marketing authorization submissions, and Japanese PMDA conditional approval disclosures. Top-down triangulation anchored in SEC 10-K filings from listed life science conglomerates and customs data for bioreactor equipment trade flows.
Variance-decomposition across the projection horizon isolated volume drivers by product type, application tier, end-user category, and technology platform. CAGRs were derived from segment-level growth rate convergence modeling calibrated to reimbursement pathway expansion timelines and manufacturing capacity buildout announcements. Industry-specific forecast inputs incorporated bioreactor automation adoption curves and REACH substance restriction compliance schedules for cryoprotectant reformulation.
Material uncertainties — regulatory pathway delays, reimbursement denial decisions, and bioreactor equipment supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions about PMDA conditional approval retention rates and FDA regenerative medicine advanced therapy designation sustainment. Recalibration cycles align with material shifts in national reimbursement frameworks and GMP certification capacity expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Asia-Pacific Bacteriophages Therapy Market
Medical Biotechnology
Tularemia Market
Medical Biotechnology
Myoglobin Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Antibody Fragments Market
Medical Biotechnology
Crude Heparin Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Global Red Biotechnology Market
Medical Biotechnology
T Cell-Specific Surface Glycoprotein CD28 Antibody Market
Medical Biotechnology
Recombinant Human Endostatin Market
Medical Biotechnology
Cell Culture Market
Medical Biotechnology
Thalassemia Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Iga Nephropathy (Igan) Market
Medical Biotechnology
Asia-Pacific G-CSF/ PEG-G-CSF Market
Medical Biotechnology
Global Human Embryonic Stem Cells Market