
 T Cell Therapy Market | 2026-2036
T Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
T Cell Therapy Market Intelligence
The divergence in scaled manufacturing capacity between established pharmaceutical firms and specialized biotechnology companies is reorganizing the competitive landscape. Large players like Novartis AG leverage extensive in-house production and logistics networks for their cell therapies. Gilead Sciences sustains its market position through significant investment in autologous therapy manufacturing infrastructure. In contrast, firms such as Autolus Therapeutics often specialize in novel constructs, relying on partners for production scale.
T cell therapy is a form of immunotherapy where a patient's T cells are genetically engineered to target and destroy diseased cells. This process typically involves modifying the cells to express Chimeric Antigen Receptors (CARs) or engineered T-Cell Receptors (TCRs). The CAR-T product segment currently dominates the market due to its success in treating hematological malignancies. Consequently, the oncology application segment holds the largest share, with significant research focused on expanding into solid tumors and autoimmune disorders.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) establish rigorous standards for clinical development and manufacturing. These guidelines, alongside protocols from China's NMPA, directly influence market access and therapy validation. Navigating these complex requirements while scaling production to reduce costs and improve patient access remains the central challenge for all stakeholders.
Market Dynamics
The central dynamic shaping the T cell therapy market is the industrialization of personalized medicine. This creates a fundamental tension between the patient-specific, high-cost autologous model and the drive toward scalable, lower-cost allogeneic therapies for broader patient access.
Growth Catalysts
- Advanced Cell Engineering:Success of Chimeric Antigen Receptor (CAR) and T-Cell Receptor (TCR) technologies in treating hematological cancers provides a strong proof-of-concept, encouraging further investment in next-generation constructs.
- Regulatory Support Mechanisms:Expedited review pathways, such as the FDA's RMAT designation and the EMA's PRIME scheme, accelerate the clinical-to-commercial timeline for therapies addressing significant unmet medical needs.
- Expanding Clinical Research:A surge in clinical trial initiations in geographies like China, supported by national policies and growing biopharmaceutical infrastructure, is broadening the global development pipeline and data pool.
Market Restraints
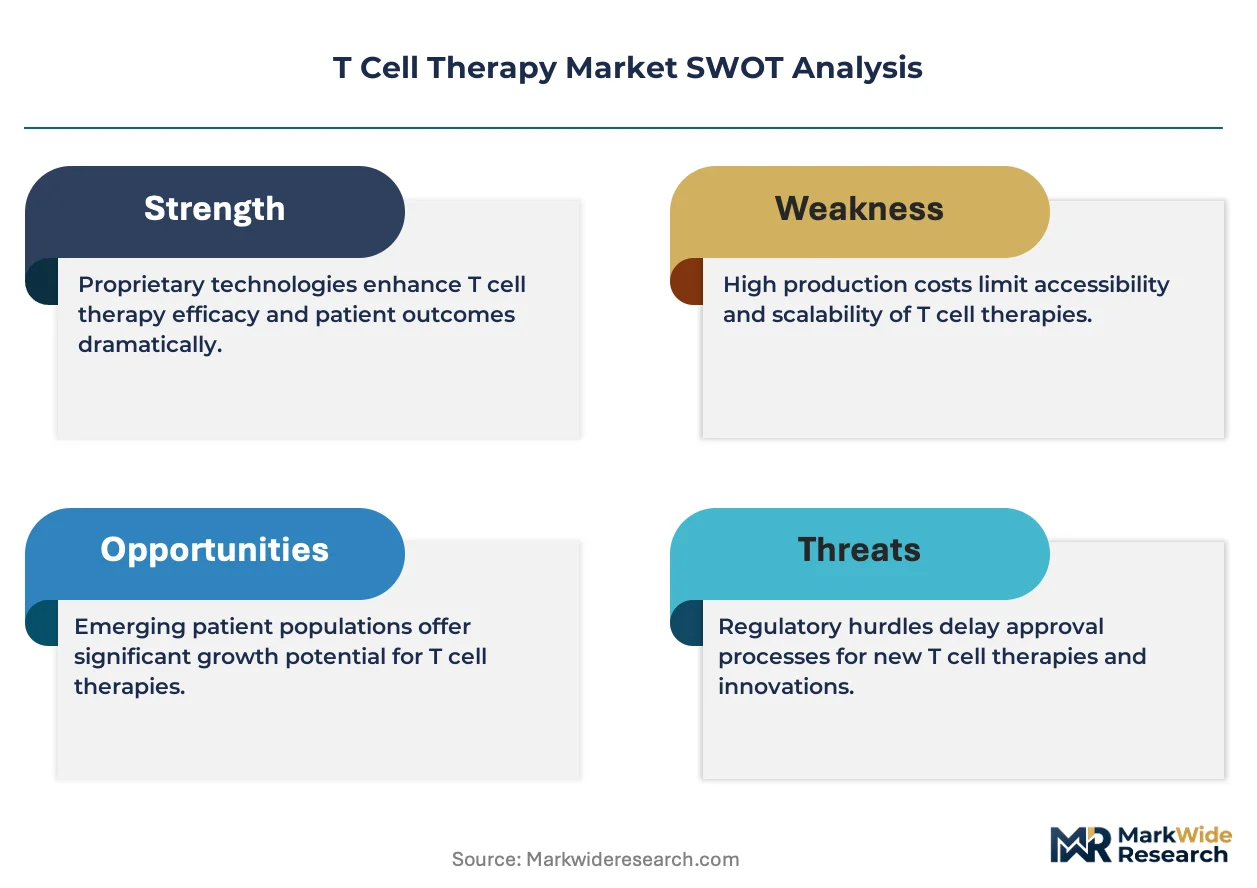
- High Manufacturing Cost:The autologous therapy model, which requires a unique manufacturing batch for each patient, results in extremely high treatment costs and limits scalability and patient accessibility.
- Solid Tumor Efficacy Barrier:T cell therapies face significant hurdles in treating solid tumors due to the immunosuppressive tumor microenvironment, antigen heterogeneity, and difficulties with cell trafficking and persistence.
- Complex Logistical Demands:The vein-to-vein supply chain for autologous therapies is exceptionally complex, requiring cryopreservation, specialized logistics, and precise scheduling, which introduces risks of failure and delays.
Strategic Opportunities
- Therapeutic Area Expansion:Applying T cell engineering principles to treat autoimmune diseases like lupus or multiple sclerosis opens a vast new market beyond the current oncology focus.
- Allogeneic Therapy Development:Creating "off-the-shelf" allogeneic T cell products from healthy donor cells presents a major opportunity to reduce costs, shorten treatment times, and standardize production.
- Non-Viral Gene Delivery:Innovating beyond lentiviral or retroviral vectors for gene delivery, using methods like CRISPR-based editing or transposons, could improve safety profiles and simplify manufacturing processes.
Industry Challenges
- Specialized Talent Scarcity:A significant shortage of personnel with expertise in cell therapy process development, cGMP manufacturing, and regulatory affairs constrains the industry's ability to scale operations.
- Manufacturing Capacity Bottlenecks:The high capital investment needed to build and qualify cGMP-compliant facilities for cell therapy production creates a major bottleneck, limiting supply for both clinical trials and commercial products.
- Reimbursement Model Complexity:Securing favorable reimbursement from payers for high-cost, one-time curative therapies requires extensive health economic outcome data and novel payment structures, delaying patient access post-approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | T Cell Therapy Market |
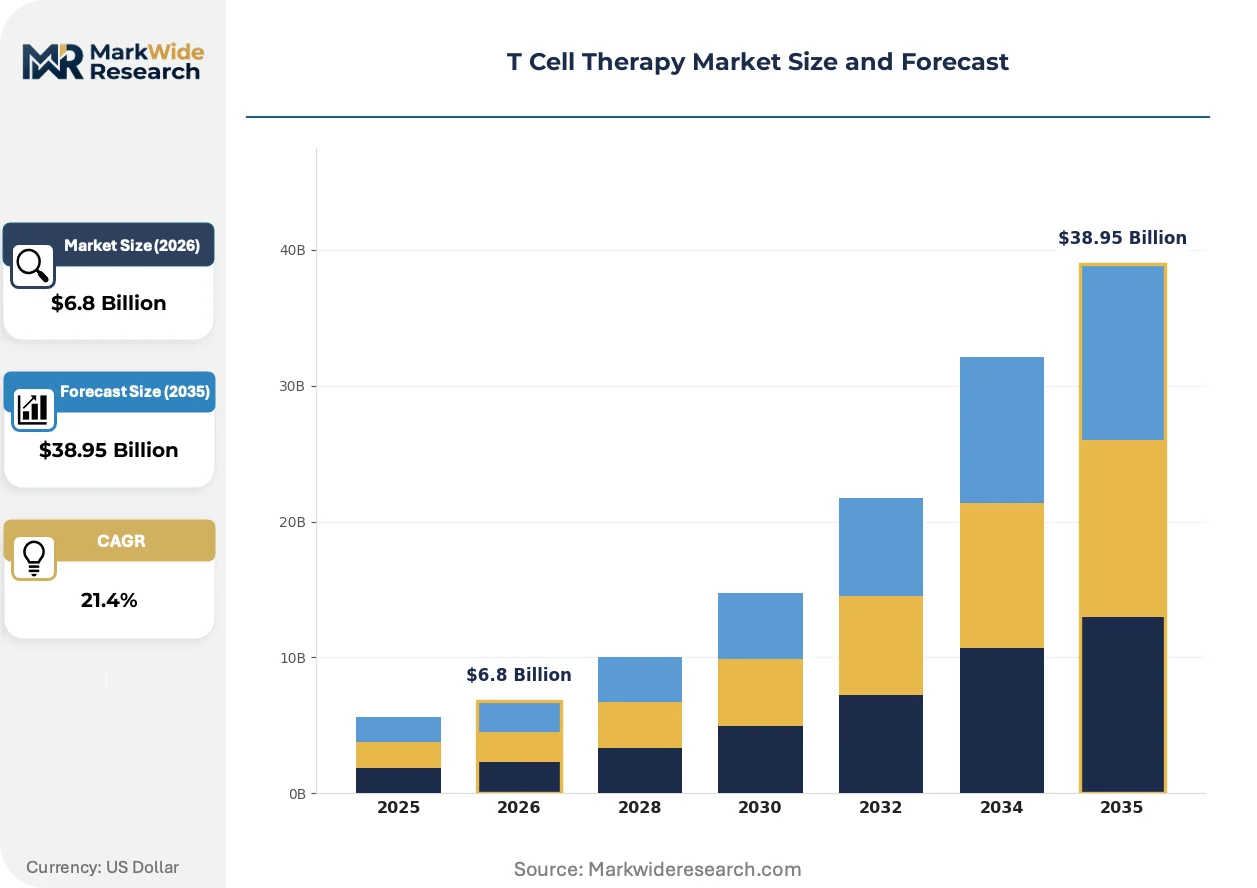
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $38.95 Billion |
| CAGR (2026 – 2036) | 21.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAR-T, TCR-T, NK Cell Therapy, Others Application: Oncology, Autoimmune Disorders, Infectious Diseases, Others End User: Hospitals, Research Institutes, Contract Manufacturing Organizations, Others Delivery Mode: Intravenous, Intratumoral, Subcutaneous, Others |
| Companies Covered | Novartis AG, Gilead Sciences, Bristol-Myers Squibb Company, Johnson & Johnson, Allogene Therapeutics, Autolus Therapeutics, Cartesian Therapeutics, Immunocore, Lonza, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
T Cell Therapy Market Strategic Shifts & Innovations
The technological and commercial trajectory of the T cell therapy market is defined by a push toward industrialization. This involves standardizing complex biological processes and developing allogeneic platforms to move beyond the limitations of patient-specific autologous treatments.
Advanced gene-editing tools, particularly CRISPR/Cas9, provide precise control over T cell modifications to enhance efficacy and safety. Research organizations and biotechnology firms are rapidly incorporating these techniques to develop multi-antigen targeting and safety-switch functionalities. This wave of innovation is fragmenting the development landscape, creating a diverse pipeline of next-generation CAR and TCR therapies that move beyond first-generation single-target constructs.
Regulatory frameworks are adapting to the unique nature of cell therapies. For instance, the US FDA's Regenerative Medicine Advanced Therapy (RMAT) designation offers an expedited approval pathway for products addressing serious or life-threatening conditions. This policy incentivizes sponsors by enabling more frequent interaction with the agency and eligibility for accelerated approval. The oncology segment, especially for hematological cancers, benefits most as developers align clinical strategies to meet RMAT criteria.
A notable behavioral shift involves the move away from traditional fee-for-service payments toward value-based reimbursement agreements. This change disrupts standard commercial models by linking payment to pre-defined clinical outcomes, such as patient response duration or remission status. This trend is most visible in the United States and select European countries, where high upfront therapy costs are compelling payers and manufacturers to negotiate risk-sharing contracts.
T Cell Therapy Market Segmentation
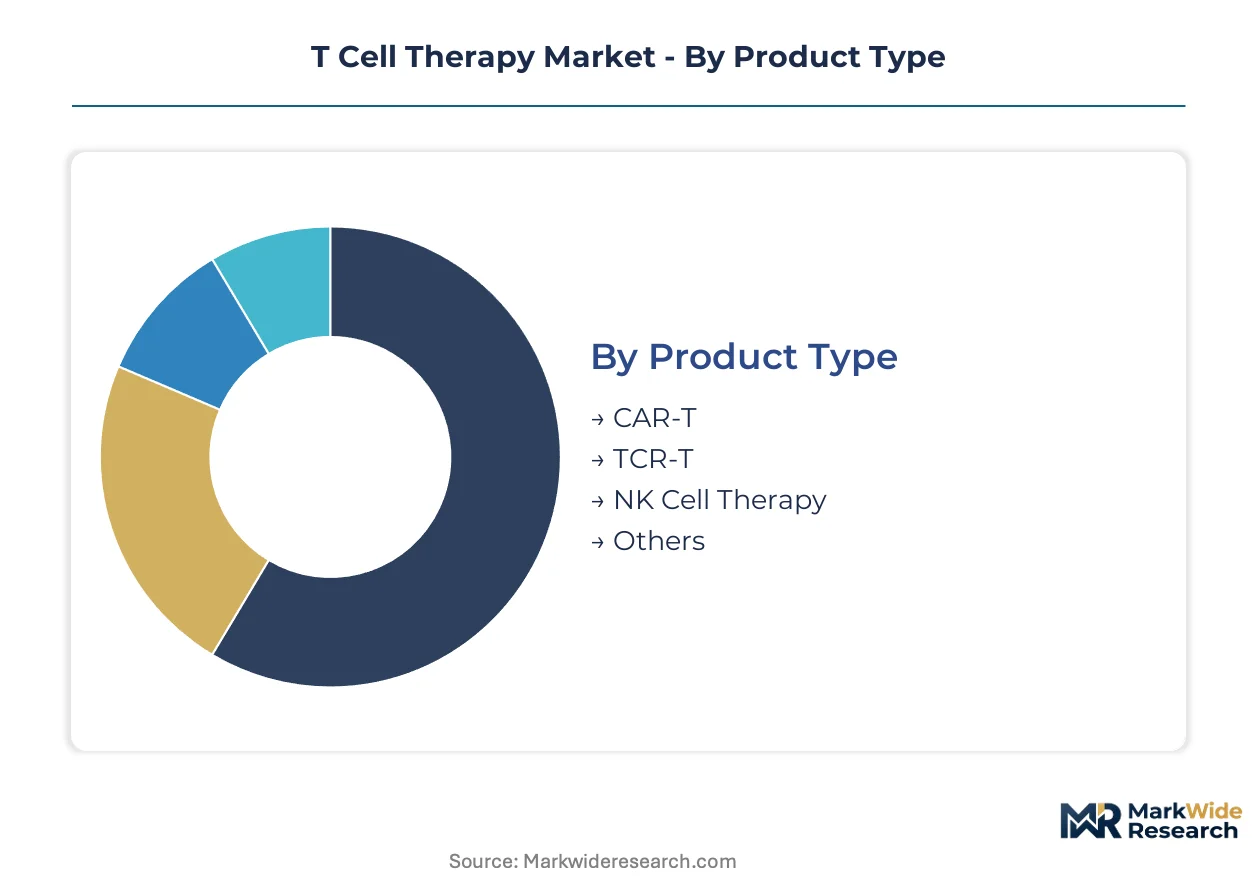
The T cell therapy market segmentation highlights the diverse approaches to engineering immune cells for therapeutic effect. Understanding these distinct categories is essential for identifying areas of innovation, market dominance, and future growth trajectories. This granular analysis reveals the underlying structural shifts and commercial opportunities within personalized medicine.
Product Type:
The product type segment faces substitution pressure from next-generation platforms aiming to overcome current autologous therapy limitations.
- CAR-T:Chimeric Antigen Receptor T cells are genetically modified to express synthetic receptors targeting specific cancer cell antigens. Demand concentrates in hematological cancers, particularly B-cell lymphomas and leukemias, driven by high response rates and regulatory approvals from the US FDA and European Medicines Agency.
- TCR-T:T-Cell Receptor T cells are engineered to recognize intracellular antigens presented by MHC molecules, enabling targeting of a broader range of cancer types. Clinical research in the United States and China shows increased investment in TCR-T for solid tumor applications, addressing a major unmet need.
- NK Cell Therapy:Natural Killer cell therapies harness innate immune cells, offering potential for allogeneic, 'off-the-shelf' treatments with reduced graft-versus-host disease risk.
- Others:This category includes gamma-delta T cells and tumor-infiltrating lymphocytes, which leverage distinct immune mechanisms for cancer recognition and elimination.
CAR-T retains volume leadership; TCR-T holds the steepest expansion curve.
Application:
The application segmentation illustrates where T cell therapies are currently deployed and where future therapeutic frontiers are emerging.
- Oncology:Oncology represents the primary application, focusing on the treatment of various cancers, with significant success in hematological malignancies. The segment's expansion is driven by the urgent need for effective cancer treatments and continued clinical trials in solid tumors across multiple countries.
- Autoimmune Disorders:This emerging application involves re-engineering T cells to modulate immune responses in conditions like lupus or multiple sclerosis. Research in Europe and North America explores T cell therapies for autoimmune diseases, aiming to induce long-term remission.
- Infectious Diseases:T cell therapies are being explored for chronic viral infections, including HIV and hepatitis, by enhancing host immune responses against pathogens.
- Others:This segment covers applications in organ transplantation and gene therapy, where T cells can be engineered to prevent rejection or deliver therapeutic genes.
Oncology accounts for the largest share, while autoimmune disorders demonstrate significant growth potential.
End User:
The end user segment highlights the diverse institutional settings responsible for T cell therapy development, administration, and commercialization.
- Hospitals:Hospitals serve as the primary point of care for T cell therapy administration, managing patient selection, infusion, and post-treatment monitoring. The demand here is directly tied to regulatory approvals and reimbursement policies from agencies like the US FDA and European Medicines Agency.
- Research Institutes:These institutions are central to the discovery and preclinical development of novel T cell constructs and engineering platforms. Their activity is crucial for expanding the therapeutic pipeline, often supported by public funding and collaborations with biotechnology firms.
- Contract Manufacturing Organizations:CMOs provide specialized manufacturing services, addressing the complex logistical and production demands of cell therapies for developers lacking in-house capacity.
- Others:This category includes specialty clinics and academic medical centers that combine research with patient care, often participating in early-phase clinical trials.
Hospitals drive patient access, with research institutes enabling future therapeutic advancements.
Delivery Mode:
The delivery mode segment differentiates T cell therapy administration routes based on target site, efficacy considerations, and patient convenience.
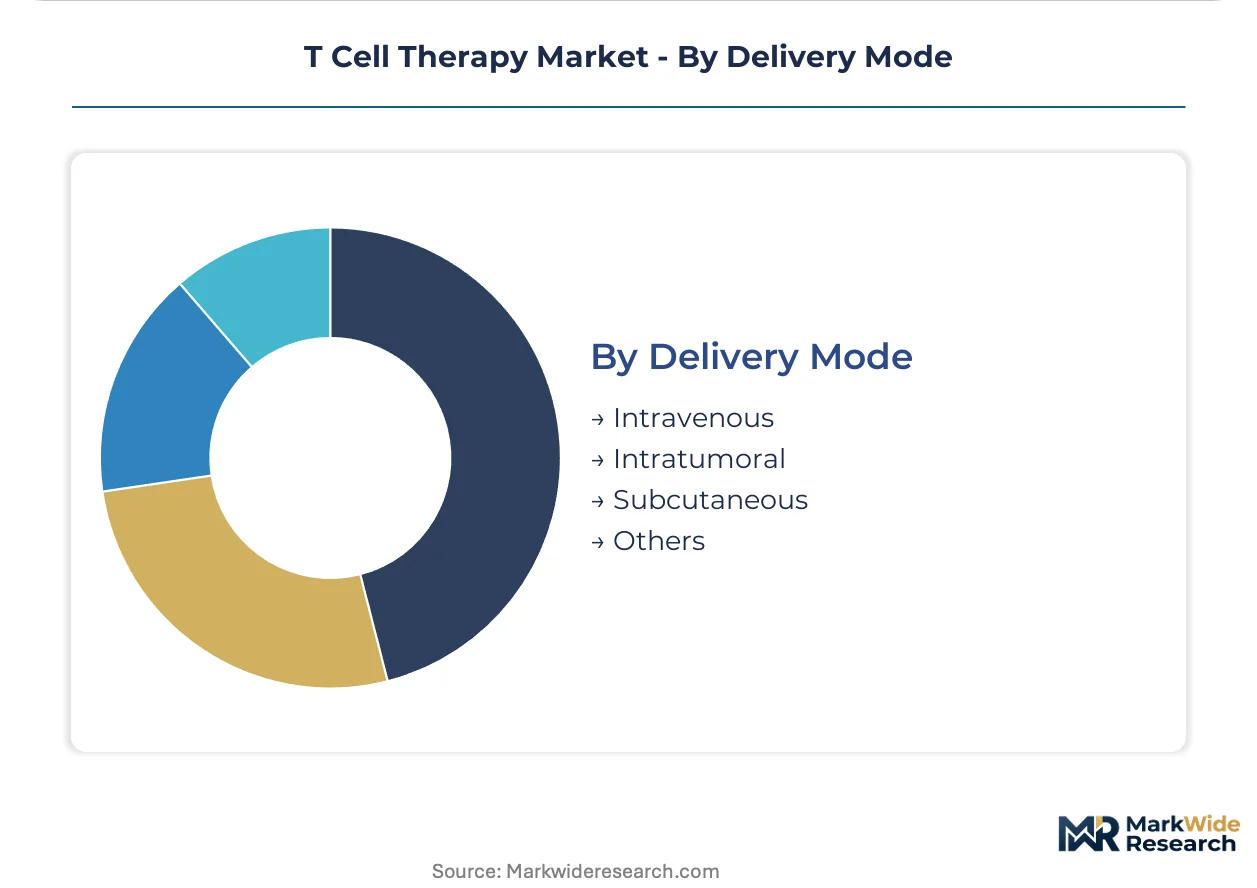
- Intravenous:Intravenous delivery involves infusing engineered T cells directly into the bloodstream, a standard method for systemic distribution in hematological cancers. This route requires careful monitoring for systemic adverse events, as mandated by regulatory bodies in the US and Europe.
- Intratumoral:Intratumoral delivery involves direct injection of T cells into solid tumors, aiming for localized efficacy and reduced systemic toxicity. This approach is gaining traction in clinical trials for solid tumors, driven by efforts to overcome microenvironment barriers.
- Subcutaneous:Subcutaneous administration offers a less invasive option for certain T cell therapies, potentially improving patient convenience and outpatient management.
- Others:This category encompasses various localized delivery methods, such as intrapleural or intraperitoneal injections, tailored for specific cancer types or disease sites.
Intravenous administration remains foundational, as intratumoral methods gain traction for localized treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global T cell therapy market exhibits a dynamic interplay between regions specializing in advanced research and those rapidly expanding clinical and manufacturing capabilities. This creates a complex global ecosystem where innovative treatments developed in one geography often seek approval and patient access across international borders. The United States and Europe lead in commercial approvals, while China significantly contributes to clinical trial expansion.
United States
High incidence of hematological cancers drives significant demand for T cell therapies. The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation accelerates development and approval for these crucial treatments. The Boston-Cambridge biocluster drives substantial T cell therapy innovation, fostering both preclinical and clinical research.
China
Extensive patient populations and robust national policies supporting biopharmaceutical innovation fuel market growth. China's NMPA actively streamlines approval pathways for novel cell therapies, broadening patient access. Shanghai and Beijing host numerous biotechnology parks, serving as key centers for T cell therapy clinical trials and manufacturing.
Germany
An established healthcare infrastructure and strong academic research in cell engineering underpin the market. European Medicines Agency (EMA) guidelines significantly influence clinical development and market access for advanced cell therapies. Munich and Berlin are prominent centers for advanced cell therapy research, attracting investment in manufacturing initiatives.
Japan
An aging population and proactive government initiatives promote regenerative medicine applications. The PMDA provides expedited review for regenerative medical products, facilitating quicker market entry. The Kansai region, including Osaka, fosters biopharmaceutical development and clinical applications for T cell therapies.
T Cell Therapy Market Key Industry Players
Concentration sits with established pharmaceutical firms leveraging extensive infrastructure and specialized biotechnology companies focusing on novel constructs. The market structure exhibits a tiered approach, with large players dominating commercialization and smaller firms driving innovation. Strategic partnerships and capacity expansion are dominant competitive moves, alongside portfolio diversification into new therapeutic areas.
Among the established pharmaceutical firms, Novartis AG exemplifies a large player with extensive in-house production and logistics networks for cell therapies. Gilead Sciences sustains its market position through significant investment in autologous therapy manufacturing infrastructure. In contrast, Autolus Therapeutics, a specialized biotechnology company, often focuses on novel constructs, representing the innovation-driven segment that relies on partners for production scale. These entities collectively shape the market's commercial and technological trajectory.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences |
| Bristol-Myers Squibb Company |
| Johnson & Johnson |
| Allogene Therapeutics |
| Autolus Therapeutics |
| Cartesian Therapeutics |
| Immunocore |
| Lonza |
| Others |
Cost & Logistics Intelligence
The US FDA's Regenerative Medicine Advanced Therapy (RMAT) designation gates both supply qualification and price differentiation for novel T cell therapies. This regulatory pathway influences the capital investment required for cGMP-compliant manufacturing and the subsequent premium pricing of approved treatments.
Pricing Analysis
Hospital procurement managers anchor pricing discussions for T cell therapies, which predominantly follow a value-based reimbursement model. Price differentiation stems from the therapy's clinical outcomes, such as sustained remission duration, and the customization level for patient-specific autologous treatments. Pricing pressure intensifies for high-cost, one-time curative therapies, compelling payers to negotiate risk-sharing contracts. Payers, including government agencies and private insurers, exhibit the highest price sensitivity, while patients typically have lower direct sensitivity due to insurance coverage.
Supply Chain Analysis
The vein-to-vein logistical demands for autologous therapies create significant inventory and lead-time challenges due to cryopreservation requirements. Geographic supply concentration for manufacturing capacity includes the United States, China, and specific European hubs like Germany. Raw material dependencies involve patient-derived T cells, viral vectors for genetic modification, and specialized cell culture media. A structural supply chain risk is the single-source vulnerability for specific viral vector producers. Distribution runs through specialized hospital centers and academic medical institutions capable of handling complex cell therapy administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The T cell therapy market is a high-growth disruption, justified by advanced cell engineering techniques like CRISPR/Cas9 that enhance efficacy and safety profiles.
For Market Incumbents: Fortify market position by investing in allogeneic therapy platforms to reduce per-patient costs and expand patient access. Consolidate specialized logistics networks to streamline the complex vein-to-vein supply chain, mitigating risks of failure and delays. This strategy addresses the threat of high manufacturing costs and the scarcity of specialized talent in cell therapy production.
For New Entrants and Emerging Players: Specialized manufacturing services for novel constructs represent a service-layer gap where incumbents under-serve the market. Target the solid tumor application segment with innovative TCR-T or NK cell therapies, which remain a major unmet medical need. A go-to-market angle focusing on non-viral gene delivery methods could offer improved safety profiles and simplified manufacturing processes.
For Investors and Strategic Acquirers: The US FDA's RMAT designation reshapes the acquisition landscape, favoring companies with therapies addressing serious conditions and demonstrating early clinical success. Long-term viability centers on technologies that can transition from autologous to scalable allogeneic models over the next five to ten years. Acquisition targets include specialized biotechnology firms developing multi-antigen targeting or safety-switch functionalities. Clinical trial success in expanding T cell therapies beyond hematological malignancies is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Allogeneic Therapy Platforms | This initiative drives cost reduction and broadens patient access beyond current autologous therapy limitations. |
| Expand cGMP Manufacturing Capacity | This move addresses current supply bottlenecks, crucial for scaling commercial and clinical product availability. |
| Develop Non-Viral Gene Delivery Methods | This innovation improves safety profiles and simplifies manufacturing, enhancing therapy adoption. |
| Target Solid Tumor Applications | This strategy unlocks a vast new market segment beyond current hematological cancer successes. |
| Form Value-Based Reimbursement Partnerships | This approach secures payer acceptance for high-cost therapies by linking payment to clinical outcomes. |
Research Approach
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and cell engineering scientists anchored the qualitative base for this analysis. This primary research was triangulated with comprehensive secondary validation, including FDA filings, EMA submissions, ClinicalTrials.gov, and company annual reports. Both bottom-up and top-down data synthesis ensured a robust understanding of market dynamics.
Sensitivity analysis framed the forecast framework, employing scenario-based modeling and statistical regression across the analysis window. Segmentation dimensions modeled included product type (CAR-T, TCR-T), application (oncology, autoimmune disorders), end-user (hospitals, research institutes), delivery mode (intravenous, intratumoral), and regional regulatory clusters. Compound annual growth rates were derived from historical data and projected growth drivers, with clinical trial success rates and regulatory approval timelines serving as key industry-specific forecast inputs.
Underlying assumptions cover regulatory stability and continued investment in research and development, with deviation risk concentrated in unexpected clinical trial failures or unforeseen manufacturing challenges. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market