
 Cellular Reprogramming Tools Market | 2026-2036
Cellular Reprogramming Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Reprogramming Tools Market Outlook
ISO 9001 certification cycles for GMP-grade reprogramming reagent manufacturing is reorganizing competitive access across the cellular reprogramming tools landscape. Thermo Fisher Scientific leverages its end-to-end workflow integration to anchor supply relationships with large pharmaceutical buyers. STEMCELL Technologies specializes in feeder-free culture systems that dominate academic and government laboratory procurement channels. Lonza Group controls GMP-compliant production capacity that sustains premium positioning in clinical-grade vector segments.
Cellular reprogramming tools comprise engineered delivery systems—plasmid vectors, modified RNA molecules, viral constructs, and synthetic chemical cocktails—that reset somatic cell identity to pluripotent or alternative differentiated states through forced expression of master regulatory genes. These tools operate through transient or stable transfection protocols achieving reprogramming efficiencies between 0.01% and 10% depending on cell source and method, with primary commercial purpose centered on generating patient-specific disease models and autologous cell therapy starting materials. Viral vector formats retain dominant installed base among biotech firms pursuing clinical applications where integration footprint and transduction efficiency carry decisive weight, while RNA molecule formats represent the fastest-expanding margin pool as transient expression profiles align with regulatory preferences for footprint-free reprogramming in therapeutic contexts. Academic institutions concentrate procurement on chemical compound and small molecule technology segments where cost scalability and protocol simplicity offset lower per-cell efficiency metrics.
FDA's regenerative medicine advanced therapy designation framework and EMA's ATMP classification system impose manufacturing and characterization standards that directly shape product development roadmaps and customer qualification requirements for reprogramming tool vendors. Japan's PMDA operates accelerated review pathways for iPSC-derived therapeutic products that pull GMP-grade tool demand toward Japanese domestic supply chains and technical service capabilities. Stakeholders must monitor evolving pharmacopeial monographs for raw material traceability and potency assay standardization as these specifications increasingly determine competitive eligibility in funded procurement channels.
Market Dynamics
CRISPR-based precision editing is compressing reprogramming protocol timelines from weeks to days, forcing vendors to recalibrate reagent portfolios around footprint-free delivery formats that satisfy both research and clinical-grade qualification pathways.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy Designation:The accelerated approval framework pulls pharmaceutical sponsors toward GMP-qualified reprogramming workflows, expanding contracted demand for vector manufacturing and characterization services.
- Autologous cell therapy pipelines:Biotech firms advancing iPSC-derived therapeutic candidates require scalable reprogramming infrastructure, driving procurement of automated culture systems and synthetic mRNA kits.
- Japan PMDA accelerated review pathways:Domestic supply chain preferences channel investment into localized technical service capabilities and GMP-grade reagent production capacity.
Market Restraints
- Lentiviral vector supply concentration:GMP-compliant viral construct manufacturing clusters in limited production networks, creating bottleneck risk for clinical-stage sponsors dependent on stable transduction formats.
- Primary cell sourcing volatility:Donor tissue acquisition costs fluctuate with ethical review board processing delays and informed consent complexity, compressing margin predictability for contract reprogramming service providers.
- Footprint detection assay burden:Residual plasmid and viral integration screening adds regulatory documentation overhead that slows batch release timelines for footprint-sensitive therapeutic applications.
Strategic Opportunities
- India CDSCO emerging ATMP framework:The regulator's evolving cell therapy guidelines create first-mover positioning for GMP-certified reagent vendors establishing local distribution partnerships.
- Chemical reprogramming convergence:Small-molecule cocktails combined with bioreactor automation enable cost-scalable manufacturing for allogeneic cell banks serving population-scale therapeutic demand.
- Direct-to-academic synthetic RNA distribution:Digital procurement platforms bypass traditional distributor markups, capturing price-sensitive research segment volume through subscription-based reagent access models.
Industry Challenges
- GMP-grade potency assay standardization:Pharmacopeial monograph gaps force vendors to maintain multiple qualification protocols across FDA, EMA, and PMDA submission requirements, inflating quality system overhead.
- Reprogramming efficiency optimization:Low-yield protocols for refractory cell types demand specialized technical field support that strains specialist staffing capacity at mid-scale tool providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Reprogramming Tools Market |
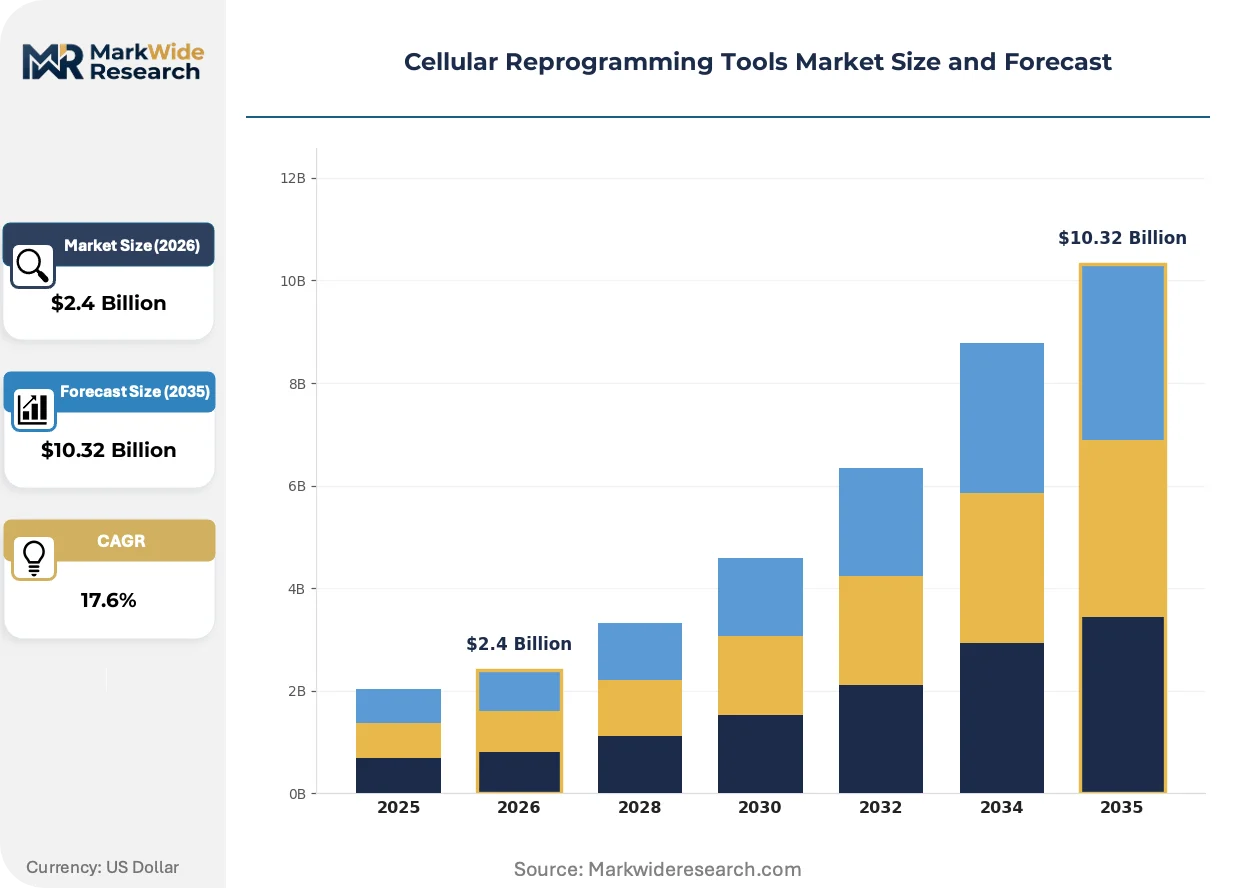
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $10.32 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasmid Vectors, RNA Molecules, Chemical Compounds, Viral Vectors Technology: CRISPR, Transcription Factors, Small Molecules, RNA-Seq Application: Regenerative Medicine, Disease Modeling, Drug Discovery, Toxicology Testing End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Biotech Firms |
| Companies Covered | Thermo Fisher Scientific, STEMCELL Technologies, Merck KGaA, Lonza Group, FUJIFILM Cellular Dynamics, Bio-Techne, Takara Bio, Miltenyi Biotec, REPROCELL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Reprogramming Tools Market Strategic Shifts
Synthetic mRNA formats are compressing the competitive landscape by displacing viral vectors in therapeutic-grade reprogramming workflows, while regulatory pharmacopeia development lags behind technical capability expansion.
Sendai virus vector technology is bifurcating the installed base between legacy integrative methods and transient expression systems. Biotech firms with clinical-stage assets are migrating toward cytoplasmic RNA replication platforms that eliminate nuclear genome integration risk. This technology shift is compressing demand for lentiviral packaging cell lines while expanding specialized manufacturing capacity for self-replicating RNA constructs.
EMA's ATMP classification system revision is tightening raw material traceability requirements for starting cell substrates. The updated guideline forces reprogramming tool vendors to implement electronic batch record systems that document chain-of-custody from donor tissue through final vector formulation. European contract development organizations are responding by consolidating supplier qualification audits around ISO 20387 biobanking standards.
Consolidated procurement by centralized biobanking facilities is displacing decentralized laboratory purchasing across academic medical centers. Large university systems are mandating preferred vendor agreements that bundle reagent supply with technical training and protocol optimization support. This channel restructuring concentrates volume with workflow-integrated suppliers and marginalizes standalone component vendors in the United States research segment.
Cellular Reprogramming Tools Market Segmentation
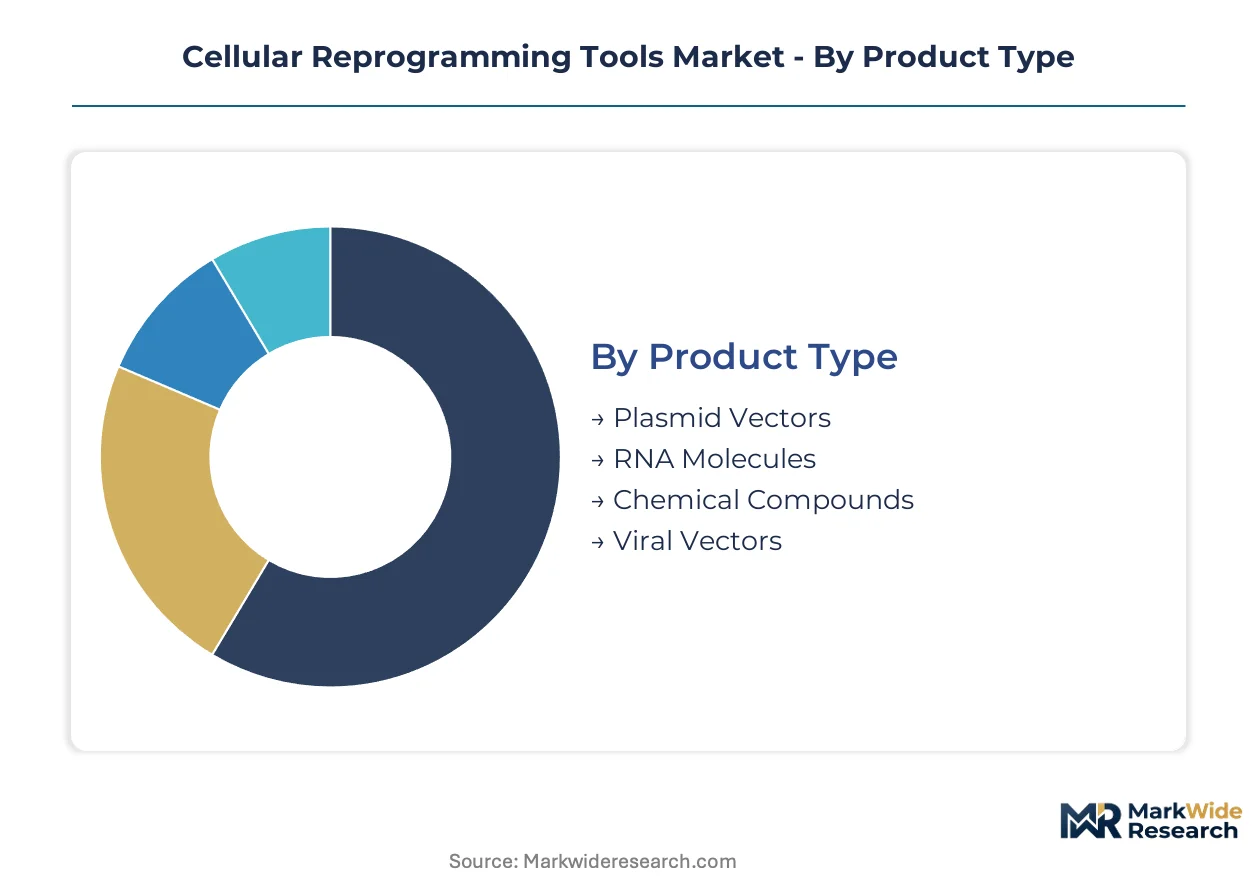
Cellular reprogramming tools fragment across four critical dimensions that determine procurement priorities, regulatory qualification pathways, and margin structures. Technology substitution pressures and end-user consolidation are reshaping segment boundaries faster than traditional category definitions can capture.
Product Type:
RNA Molecule formats face the most acute substitution pressure as synthetic chemistry advances displace legacy viral packaging dependencies across therapeutic-grade workflows.
- RNA Molecules:Synthetic mRNA and modified RNA formats enable transient, footprint-free reprogramming with reduced regulatory documentation burden. Pharmaceutical sponsors in the United States and Japan are consolidating procurement around GMP-certified RNA kits for clinical-stage iPSC pipelines.
- Viral Vectors:Lentiviral and Sendai virus constructs retain entrenched positions where integration footprint tolerance and transduction efficiency outweigh transient expression benefits. Biotech firms with advanced therapeutic candidates continue sourcing GMP-compliant viral constructs despite manufacturing bottleneck risks.
- Plasmid Vectors:Episomal DNA systems offer intermediate persistence profiles for research-grade reprogramming where cost sensitivity dominates protocol design.
- Chemical Compounds:Small-molecule cocktails enable cost-scalable, automation-compatible workflows that academic laboratories favor for high-throughput screening applications.
Viral Vectors anchors the volume base while RNA Molecules gains share at the steepest rate.
Technology:
Cost tier stratification separates premium-precision editing platforms from commodity expression monitoring tools, with CRISPR commanding price multiples over legacy methods.
- CRISPR:Precision editing systems compress reprogramming timelines from weeks to days through targeted activation of master regulatory loci. Large pharmaceutical buyers in Germany and the United States are embedding CRISPR workflows into automated drug discovery infrastructure.
- Transcription Factors:Forced expression of OCT4, SOX2, KLF4, and c-MYC retains protocol standardization advantages for contract manufacturing organizations serving multiple regulatory jurisdictions.
- Small Molecules:Chemical induction pathways reduce vector manufacturing dependencies but require extended culture periods that challenge cost-per-cell economics.
- RNA-Seq:Expression profiling technologies enable quality control and reprogramming efficiency optimization rather than direct cellular conversion.
Transcription Factors maintains the broadest installed base while CRISPR expands most quickly into premium therapeutic applications.
Application:
Customer maturity divides segments between validated clinical pathways and exploratory research programs with diverging technical service requirements.
- Regenerative Medicine:Autologous and allogeneic cell therapy manufacturing demands GMP-grade reagents with full chain-of-custody documentation. Japan's PMDA accelerated review pathways are concentrating domestic supply chain investment around this application.
- Drug Discovery:Patient-specific disease modeling requires scalable reprogramming platforms that integrate with automated screening infrastructure. Pharmaceutical companies are bundling tool procurement with protocol optimization services.
- Disease Modeling:Academic medical centers generate iPSC-derived organoids for mechanistic research with less stringent qualification requirements than therapeutic applications.
- Toxicology Testing:Hepatocyte and cardiomyocyte reprogramming for safety pharmacology screening favors chemical compound formats that reduce batch-to-batch variability concerns.
Drug Discovery captures the largest procurement volume while Regenerative Medicine climbs the fastest as clinical-stage pipelines mature.
End User:
Procurement concentration favors integrated workflow vendors among large buyers while fragmented academic demand sustains specialized component suppliers.
- Pharmaceutical Companies:Global drug developers mandate end-to-end qualification support, preferring vendors with multi-site technical service capabilities and regulatory submission experience across FDA, EMA, and PMDA frameworks.
- Biotech Firms:Venture-backed therapeutic developers prioritize speed-to-IND over cost optimization, accepting premium pricing for GMP-ready reagent formats with pre-validated potency assays.
- Academic Institutions:University laboratories emphasize protocol flexibility and cost scalability, often sourcing chemical reprogramming methods through digital procurement platforms that bypass distributor markups.
- Research Organizations:Government-funded institutes occupy an intermediate position with structured procurement processes but greater tolerance for technical field support requirements than pharmaceutical buyers.
Pharmaceutical Companies dominate absolute spending while Biotech Firms show the steepest expansion trajectory as cell therapy financing environments recover.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's regenerative medicine advanced therapy designation pulls pharmaceutical sponsors toward GMP-qualified reprogramming workflows in the United States. Japan's PMDA accelerated review pathways channel domestic supply chain investment into iPSC-derived therapeutic infrastructure. Germany's EMA-aligned ATMP classification system tightens raw material traceability requirements across European contract manufacturing networks.
United States
Pharmaceutical companies in Massachusetts and California are scaling automated iPSC workflows for drug discovery pipelines. FDA's RMAT designation compresses IND timelines for sponsors using qualified reprogramming platforms. The Boston-Cambridge biotech cluster concentrates demand for GMP-certified synthetic mRNA kits among venture-backed cell therapy developers.
Japan
Domestic biotech firms are advancing clinical-stage iPSC-derived therapeutic candidates through PMDA accelerated review pathways. METI funding programs support localized GMP-grade reagent production capacity and technical service capabilities. The Kansai region around Osaka hosts concentrated manufacturing infrastructure for footprint-free reprogramming vector production.
Germany
EMA's ATMP classification revision forces electronic batch record implementation for chain-of-custody documentation from donor tissue through final vector formulation. The country's pharmaceutical manufacturing base in Baden-Württemberg and North Rhine-Westphalia drives demand for ISO 20387-aligned biobanking standards. Heidelberg and Munich academic medical centers are consolidating procurement around preferred vendor agreements with workflow-integrated suppliers.
United Kingdom
Research organizations in London and Cambridge are migrating toward chemical reprogramming methods for cost-scalable disease modeling applications. The Medicines and Healthcare products Regulatory Agency aligns with EMA ATMP standards while maintaining distinct submission requirements for advanced therapy medicinal products. The Cambridge cell therapy cluster is expanding specialized manufacturing capacity for self-replicating RNA constructs.
India
CDSCO's emerging ATMP framework creates positioning opportunities for GMP-certified reagent vendors establishing local distribution partnerships. Contract research organizations in Hyderabad and Bengaluru are building reprogramming service capabilities to serve global pharmaceutical sponsors. The country's national pharmaceutical regulator is developing cell therapy guidelines that will shape qualification requirements for imported reagent formats.
Cellular Reprogramming Tools Market Competitive Environment
Player mix skews toward integrated life science conglomerates with end-to-end workflow capabilities alongside specialized cell biology tool providers. Three archetypes dominate: diversified platform vendors with multi-site technical service networks, feeder-free culture system specialists serving academic procurement channels, and GMP-compliant vector manufacturers with premium clinical-grade positioning. Competitive moves concentrate on strategic partnerships for automated culture system integration and capacity expansion for synthetic RNA manufacturing.
Within the diversified platform tier, Thermo Fisher Scientific and Merck KGaA occupy positions anchored by broad reagent portfolios and regulatory submission experience across FDA, EMA, and PMDA frameworks. STEMCELL Technologies exemplifies the specialized archetype with concentrated presence in academic and government laboratory channels. Lonza Group sits within the clinical-grade manufacturing tier, sustaining premium positioning through GMP-compliant production capacity. Takara Bio and REPROCELL represent Asia-Pacific-originated competitors with regional supply chain advantages in Japanese and broader Asian markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| STEMCELL Technologies |
| Merck KGaA |
| Lonza Group |
| FUJIFILM Cellular Dynamics |
| Bio-Techne |
| Takara Bio |
| Miltenyi Biotec |
| REPROCELL |
| Others |
Value Chain & Pricing Dynamics
GMP-certified manufacturing capacity utilization above 85% in the United States and Japan is compressing marginal production economics and elevating price floors for clinical-grade reprogramming reagents. Scale concentration among multi-site vector producers allows premium capture for FDA-validated potency assays while forcing mid-tier academic suppliers toward cost-absorbing distributor relationships.
Pricing Analysis
Certification level creates the primary spread across the Cellular Reprogramming Tools Market, with GMP-grade RNA kits commanding substantial premiums over research-use-only formats. Three-tier pricing structure across premium clinical-grade, validated research-grade, and economy chemical formats reflects ISO 20387 biobanking compliance investments. Cost compression in the academic segment intensifies as digital procurement platforms eliminate traditional distributor markups. Biotech firms show the least price sensitivity due to speed-to-IND imperatives, while university laboratories aggressively negotiate volume discounts on chemical reprogramming cocktails.
Supply Chain Analysis
Plasmid DNA foundry capacity in the United States, viral packaging cell line networks in Germany, and synthetic mRNA manufacturing clusters in Japan constitute the three chokepoints determining global reagent availability. GMP-grade reagent production draws from pharmaceutical-grade nucleotide supplies, specialized bioreactor consumables, and qualified donor tissue sourcing. Single-source vulnerability concentrates in lentiviral vector packaging lines where contamination events trigger six-month qualification resets. Distribution runs through direct technical service relationships for pharmaceutical buyers and digital platforms for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdiction requirements creates specialist positioning opportunities as pharmaceutical sponsors demand multi-territory qualification support that conglomerates struggle to customize. The proliferation of footprint-free reprogramming formats is splintering technical service needs beyond standardized viral vector protocols.
For Market Incumbents: Secure GMP-grade potency assay standardization leadership across FDA, EMA, and PMDA submission requirements before pharmacopeial monograph gaps close. Incumbent players should deepen backward integration into synthetic mRNA manufacturing capacity in the Kansai region to preempt Japanese domestic supply chain preferences. Defensive consolidation around automated culture system partnerships will counter emerging platform-agnostic entrants. For New Entrants and Emerging Players: Anchor in India's CDSCO emerging ATMP framework through local distribution partnerships before global vendors establish GMP-certified reagent presence. Chemical reprogramming convergence for allogeneic cell banks offers the most penetrable white space, with cost-scalable manufacturing protocols underserved by incumbent viral vector specialists. A subscription-based synthetic RNA distribution model targeting price-sensitive academic segments bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among GMP-compliant vector manufacturers with multi-year pharmaceutical service contracts. Long-term viability in this market rests on regulatory submission experience depth rather than raw technology differentiation. Acquisition targets should display ISO 20387-aligned biobanking capabilities and established technical service networks across at least two major regulatory jurisdictions. The signal to watch is PMDA accelerated review pathway expansion pulling domestic supply chain investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Certification Pathway | ISO 20387 alignment opens pharmaceutical procurement channels previously blocked to research-grade vendors. |
| Synthetic RNA Manufacturing Scale-Up | Self-replicating RNA construct capacity in Japan satisfies PMDA footprint-free preferences for clinical-stage pipelines. |
| Automated Culture System Integration | Bioreactor partnerships with Lonza Group compress per-cell reprogramming costs for allogeneic cell banks. |
| Digital Procurement Platform Launch | Subscription models bypass distributor markups and capture price-sensitive academic volume in the United States. |
| Regional Technical Service Expansion | Localized support capabilities in Germany satisfy EMA ATMP raw material traceability documentation requirements. |
Study Parameters
A spread of perspectives from cell therapy manufacturing directors, regulatory affairs leads at ATMP sponsors, academic laboratory principal investigators, and GMP facility quality officers converged on the working assumptions driving this analysis. Primary field engagement combined with secondary validation against FDA RMAT designation filings, EMA ATMP classification submissions, PMDA accelerated review pathway decisions, and ISO 20387 biobanking standard development records. Bottom-up reagent procurement volume estimates triangulated against top-down pharmaceutical pipeline segmentation.
Segmentation dimensions modeled include reprogramming format technology, application maturity from research through clinical-grade, end-user procurement concentration, and regional regulatory framework clustering. CAGRs were derived from installed base migration rates between viral vector and RNA molecule formats, cross-referenced against pharmaceutical sponsor pipeline advancement velocities. Forecast inputs incorporated automated culture system adoption curves and synthetic mRNA kit penetration assumptions across therapeutic-grade workflows.
Material uncertainties — pharmacopeial monograph finalization timelines, PMDA domestic supply chain preference enforcement intensity, and lentiviral vector manufacturing contamination event frequency — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as footprint-free regulatory acceptance thresholds and chemical reprogramming efficiency breakthroughs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Global Mrna Therapeutics Market