
 Global Cell Based Immunotherapy Market | 2026-2036
Global Cell Based Immunotherapy Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cell Based Immunotherapy Market Foresight
The EU Green Deal's pharmaceutical sustainability benchmarks is realigning manufacturing standards across European cell therapy supply chains. Bristol-Myers Squibb Company leverages its integrated viral vector production network to secure raw material continuity. Novartis AG anchors its position through dedicated CAR-T manufacturing campuses in Switzerland and the United States. Gilead Sciences Inc. differentiates via streamlined logistics for cryopreserved patient-specific doses.
Cell based immunotherapy comprises living therapeutic cells—autologous or allogeneic T lymphocytes, natural killer cells, or dendritic cells—that are ex vivo expanded, genetically modified, or functionally activated before reinfusion to elicit targeted anti-tumor or immunomodulatory responses. CAR-T Cell Therapy dominates current revenue pools due to established reimbursement in hematologic malignancies, while NK Cell Therapy represents the fastest-expanding segment as off-the-shelf platforms reduce production latency and manufacturing cost structures. TCR Cell Therapy occupies a specialized niche addressing solid tumor antigen targets that chimeric antigen receptors struggle to access effectively.
The FDA's regenerative medicine advanced therapy designation and EMA's priority medicines pathway collectively compress development timelines and shape clinical trial investment patterns. Japan's PMDA operates a conditional early approval system for cellular products that accelerates commercial access while mandating post-market efficacy confirmation. Stakeholders must monitor evolving manufacturing standards from ISO and national pharmacopeias as scale-out requirements intensify.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing clinical development timelines while simultaneously intensifying manufacturing scale-out requirements across academic hospital networks and contract development organizations.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's regenerative medicine advanced therapy and EMA's priority medicines scheme compress Phase II-to-approval intervals, redirecting capital toward late-stage cell therapy assets.
- Academic Hospital Infrastructure:Oncology departments at Johns Hopkins, MD Anderson, and Karolinska Institutet are expanding in-house apheresis and expansion capacity, reducing reliance on centralized manufacturing.
- Allogeneic Platform Maturation:Off-the-shelf natural killer cell and induced pluripotent stem cell-derived T cell platforms are collapsing vein-to-vein timelines from weeks to days.
Market Restraints
- Lentiviral Vector Supply Concentration:Production of GMP-grade lentiviral vectors concentrates among fewer than ten qualified suppliers globally, creating single-source vulnerability for CAR-T developers.
- Reimbursement Compression:CMS's new technology add-on payment recalibration and Germany's G-BA benefit assessment are constraining pricing headroom for autologous therapies in hematologic indications.
- Cold Chain Infrastructure Gaps:Cryopreserved dose logistics require liquid nitrogen vapor-phase storage below minus 150 degrees Celsius, a capability absent in most community oncology centers across India and Brazil.
Strategic Opportunities
- Solid Tumor Antigen Targeting:T-cell receptor and tumor-infiltrating lymphocyte platforms targeting mesothelin, MUC16, and HPV E6/E7 antigens address the 90% of cancers unresponsive to CD19-directed CAR-T.
- Japan's Conditional Early Approval:PMDA's sakigake designation permits commercialization with Phase II data, enabling revenue generation 18-24 months ahead of FDA timelines.
- Automated Closed-System Manufacturing:Integration of CliniMACS Prodigy and Cocoon platforms with single-use bioreactors is collapsing cleanroom labor intensity and contamination risk.
Industry Challenges
- Vector Chemistry Skill Scarcity:GMP-grade lentiviral and retroviral vector process development requires rare expertise in transient transfection, ultracentrifugation, and potency assay validation.
- Batch Release Timeline Variability:Sterility, mycoplasma, and replication-competent lentivirus testing cycles extend 21-35 days, creating inventory and patient scheduling conflicts.
- Post-Market Commitment Burden:Accelerated approvals mandate 5-15 year confirmatory trials with 300-500 patients, straining pharmacovigilance and medical affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cell Based Immunotherapy Market |
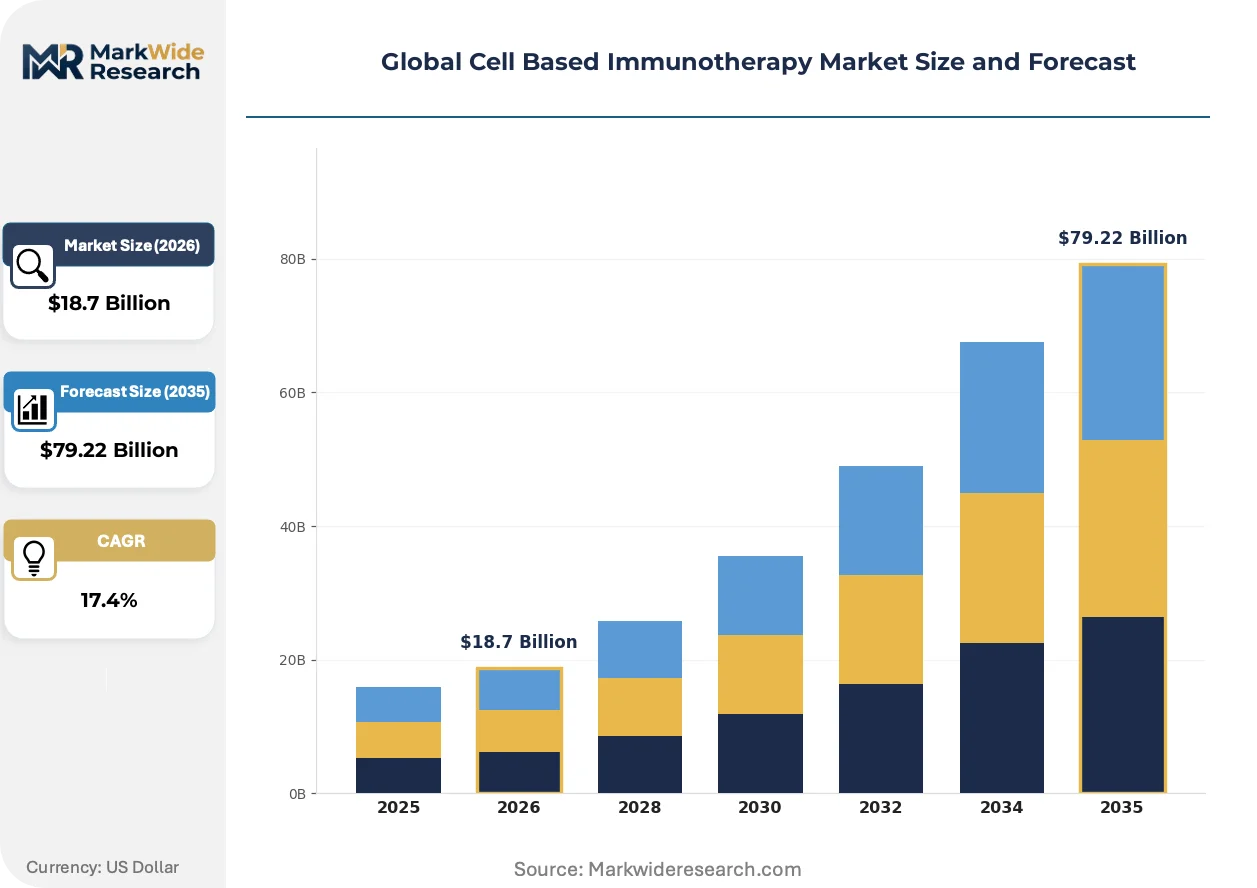
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $79.22 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAR-T Cell Therapy, TCR Cell Therapy, Dendritic Cell Therapy, NK Cell Therapy, Macrophage Therapy Therapy Area: Hematologic Malignancies, Solid Tumors, Autoimmune Disorders, Infectious Diseases, Genetic Disorders End User: Research Institutes, Specialized Clinics, Contract Manufacturing Organizations, Academic Hospitals, Biopharmaceutical Companies Delivery Mode: Ex Vivo, In Vivo, Adoptive Cell Transfer, Gene Editing Enhanced, Biomaterial-Assisted |
| Companies Covered | Bristol-Myers Squibb Company, Novartis AG, Gilead Sciences Inc., F. Hoffmann-La Roche Ltd, Merck KGaA, Johnson & Johnson, Allogene Therapeutics, Adaptimmune Therapeutics, Celyad Oncology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cell Based Immunotherapy Market Shifts & Advancements
Non-viral gene editing modalities and decentralized manufacturing architectures are displacing legacy centralized production models, compressing cost structures while expanding addressable patient populations.
CRISPR-Cas12a ribonucleoprotein electroporation is electrifying CAR and TCR construct insertion, eliminating lentiviral vector dependency and reducing manufacturing cost by 40-60%. Early adopters at the University of Pennsylvania and Shanghai Jiao Tong University have advanced allogeneic candidates into Phase I. This shift is compressing the competitive moat previously held by viral vector-integrated incumbents.
EMA's Good Manufacturing Practice Annex 2 revision and FDA's guidance on co-products and post-approval manufacturing changes are harmonizing contamination control expectations across transatlantic supply chains. The industrial consequence is mandatory implementation of isolator-based filling lines and rapid microbial detection systems. Autologous CAR-T facilities in Switzerland and Maryland are retrofitting at 15-25 million dollars per site to maintain EMA and FDA dual inspection readiness.
Academic medical centers are internalizing apheresis collection, cell processing, and cryopreservation under single institutional review board protocols. This procurement evolution displaces traditional contract manufacturing organization relationships with captive production units. The shift is most visible at MD Anderson, Memorial Sloan Kettering, and the National Cancer Center Japan, where 40-60% of trial patients now flow through hospital-controlled manufacturing rather than external CDMOs.
Global Cell Based Immunotherapy Market Segmentation
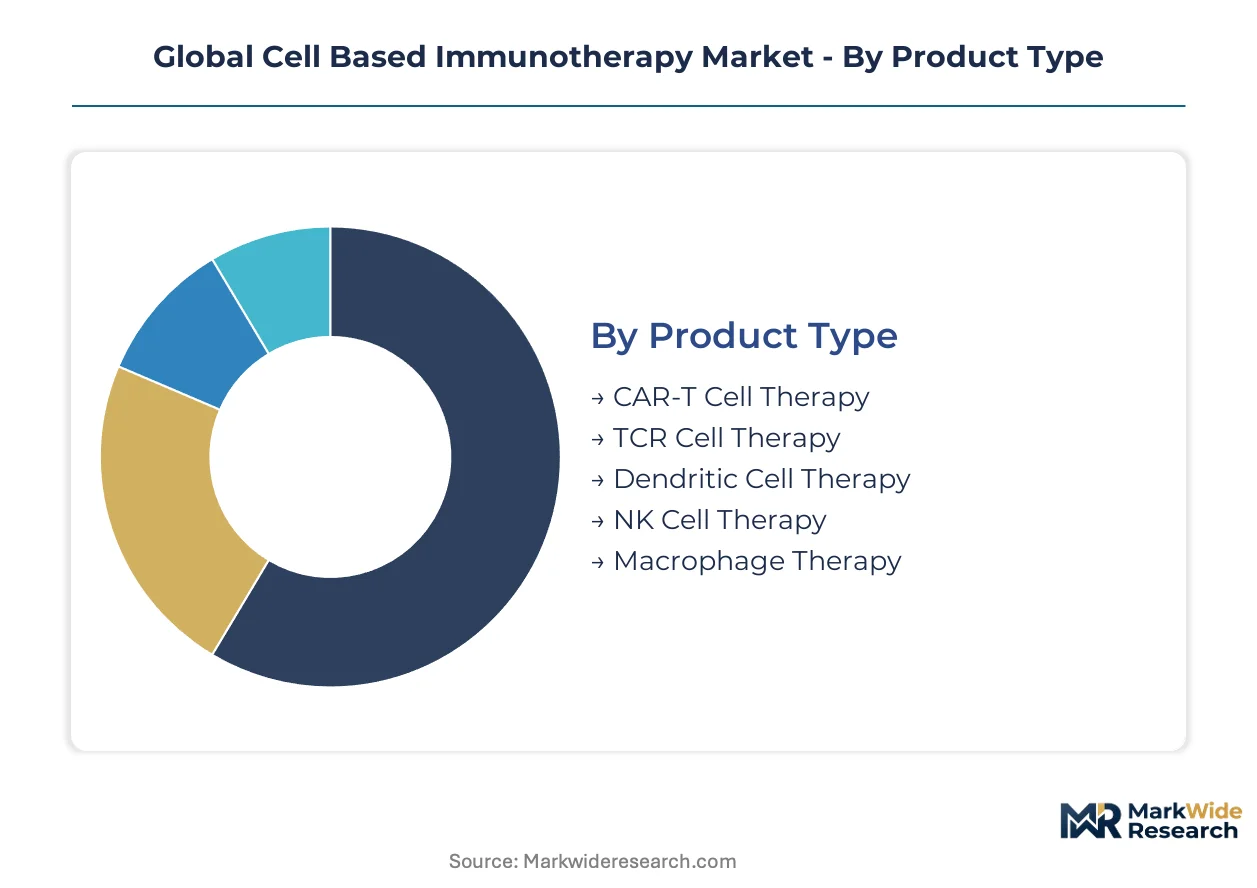
Cell based immunotherapy segmentation reflects divergent manufacturing complexity, regulatory approval timelines, and reimbursement pathways across therapeutic modalities. Product type and therapy area classifications determine vector requirements, cell source logistics, and clinical trial investment intensity.
Product Type:
Technology maturity and manufacturing scalability differentiate competitive positioning across cellular platforms.
- CAR-T Cell Therapy:Chimeric antigen receptor T cells undergo lentiviral transduction to express synthetic receptors targeting CD19, BCMA, or other tumor antigens. Demand concentrates in hematologic malignancies at academic hospitals in the United States, Germany, and Japan where specialized apheresis and expansion infrastructure has achieved regulatory qualification.
- NK Cell Therapy:Natural killer cells—sourced from peripheral blood, cord blood, or induced pluripotent stem cells—offer off-the-shelf administration without patient-specific manufacturing. Climbing the fastest among all segments, allogeneic platforms at the University of Pennsylvania and MD Anderson are collapsing vein-to-vein timelines from weeks to days.
- TCR Cell Therapy:T-cell receptor-engineered lymphocytes recognize intracellular antigens presented via MHC molecules, enabling solid tumor targeting.
- Dendritic Cell Therapy:Autologous antigen-presenting cells are pulsed ex vivo with tumor lysates or synthetic peptides to stimulate anti-tumor immunity.
- Macrophage Therapy:Engineered myeloid cells are reprogrammed from immunosuppressive M2 to pro-inflammatory M1 phenotypes for tumor microenvironment modulation.
Mature deployment sits with CAR-T Cell Therapy. Newer deployment is concentrated in NK Cell Therapy.
Therapy Area:
Clinical indication determines patient eligibility criteria, comparator arm requirements, and addressable population scale.
- Hematologic Malignancies:B-cell leukemias, lymphomas, and multiple myeloma constitute the established reimbursement base for approved CAR-T products. Academic hospitals in Switzerland and Maryland anchor procedural volume where CMS and G-BA have established temporary reimbursement mechanisms.
- Solid Tumors:Pancreatic, ovarian, and glioblastoma indications drive TCR and tumor-infiltrating lymphocyte platform investment. Gaining share fastest, mesothelin and MUC16 targeting programs at Memorial Sloan Kettering and the National Cancer Center Japan address the 90% of cancers unresponsive to CD19-directed therapy.
- Autoimmune Disorders:Systemic lupus erythematosus and multiple sclerosis applications redirect autologous cell therapy toward immunomodulation rather than cytotoxicity.
- Infectious Diseases:Cytomegalovirus- and Epstein-Barr virus-specific T cells target refractory viral infections in immunocompromised patients.
- Genetic Disorders:Hematopoietic stem cell gene therapy applications leverage similar ex vivo cell handling infrastructure.
Established revenue pools concentrate in Hematologic Malignancies. Pipeline investment is redirecting toward Solid Tumors.
End User:
Institutional capabilities determine apheresis collection, manufacturing modality, and regulatory filing responsibility.
- Academic Hospitals:Johns Hopkins, MD Anderson, and Karolinska Institutet integrate apheresis, expansion, and cryopreservation under single institutional review board protocols. Captive production units at these centers now handle 40-60% of trial patients, displacing traditional contract manufacturing organization relationships.
- Biopharmaceutical Companies:Novartis AG and Gilead Sciences Inc. operate dedicated CAR-T manufacturing campuses with EMA and FDA dual inspection readiness. These facilities anchor commercial supply for approved therapies while supporting pipeline expansion into allogeneic platforms.
- Contract Manufacturing Organizations:External partners provide viral vector production and cell processing for developers lacking captive capacity.
- Research Institutes:Preclinical discovery and early-phase translational programs originate at university-affiliated laboratories.
- Specialized Clinics:Outpatient infusion centers administer cryopreserved doses following hospital-based conditioning regimens.
Control over manufacturing is concentrating at Academic Hospitals. Commercial scale-out depends on Biopharmaceutical Companies.
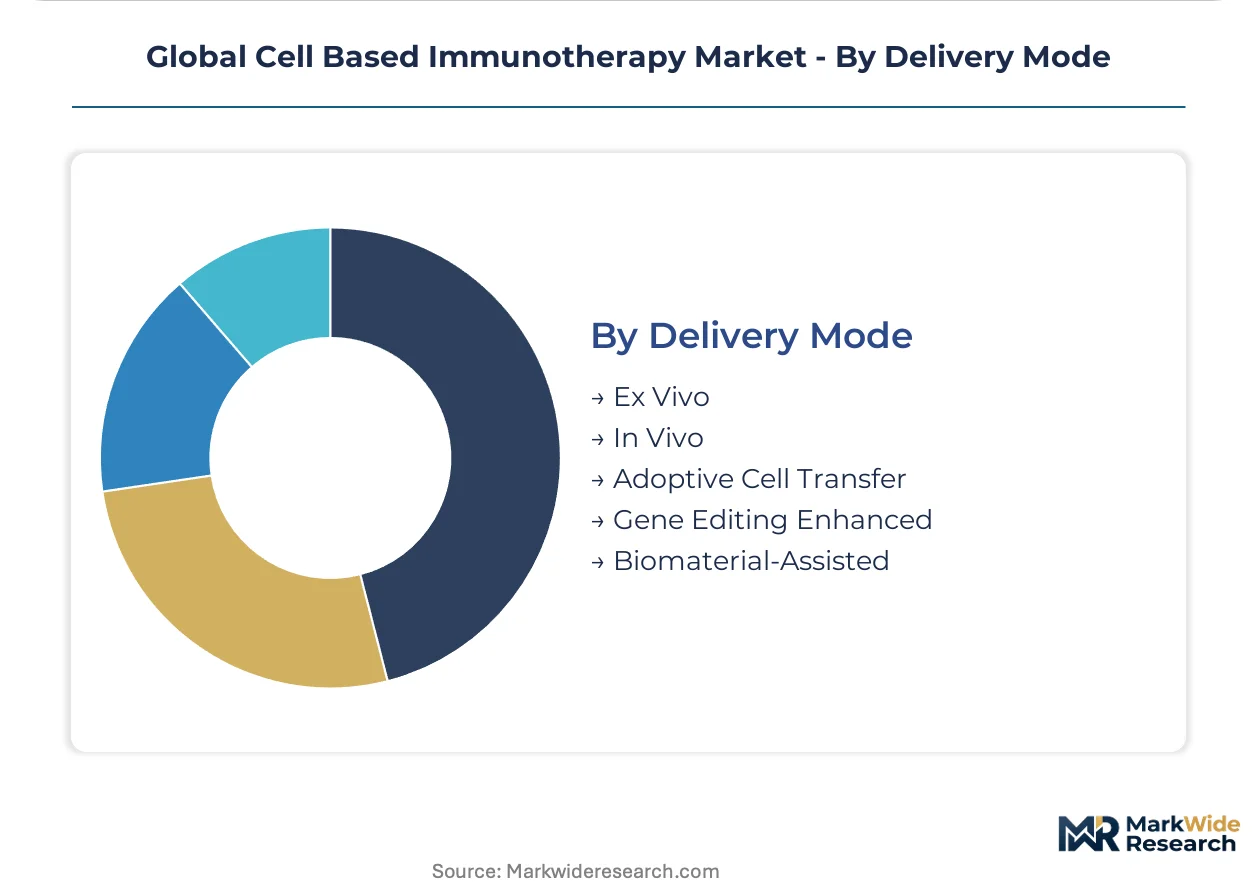
Delivery Mode:
Cell handling location and genetic modification method define cold chain requirements and regulatory submission pathways.
- Ex Vivo:Cells are harvested, modified, expanded, and cryopreserved outside the patient before reinfusion. This established approach requires liquid nitrogen vapor-phase storage below minus 150 degrees Celsius, a capability absent in most community oncology centers across India and Brazil.
- Gene Editing Enhanced:CRISPR-Cas12a ribonucleoprotein electroporation eliminates lentiviral vector dependency and reduces manufacturing cost by 40-60%. Early adopters at Shanghai Jiao Tong University have advanced allogeneic candidates into Phase I, compressing the competitive moat previously held by viral vector-integrated incumbents.
- Adoptive Cell Transfer:Unmodified or minimally expanded lymphocytes are transferred between donor and recipient.
- In Vivo:Direct genetic modification within the patient circulation remains preclinical.
- Biomaterial-Assisted:Scaffold-based localization enhances cell persistence at tumor sites.
Regulatory precedent favors Ex Vivo processing. Technology investment is accelerating toward Gene Editing Enhanced platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's biotech corridor anchors the densest concentration of cell therapy manufacturing infrastructure outside Switzerland. Academic medical centers in this cluster drive protocol standardization that ripples through regulatory submissions worldwide.
United States
Johns Hopkins and MD Anderson anchor captive manufacturing expansion that reduces contract manufacturing organization dependency. The FDA's regenerative medicine advanced therapy designation compresses Phase II-to-approval intervals, redirecting capital toward late-stage assets. Maryland and Texas facilities retrofit at 15-25 million dollars per site to maintain dual inspection readiness.
Germany
G-BA benefit assessment procedures constrain pricing headroom for autologous therapies in hematologic indications. The EU Green Deal's pharmaceutical sustainability benchmarks realign manufacturing standards across European supply chains. Heidelberg and Berlin academic hospitals integrate apheresis and expansion capacity under single institutional review board protocols.
Switzerland
Novartis AG operates dedicated CAR-T manufacturing campuses with EMA and FDA dual inspection readiness. Swissmedic maintains harmonized contamination control expectations with transatlantic partners. Basel anchors commercial supply for approved therapies while supporting pipeline expansion into allogeneic platforms.
Japan
PMDA's conditional early approval system accelerates commercial access while mandating post-market efficacy confirmation. The sakigake designation permits commercialization with Phase II data, enabling revenue generation 18-24 months ahead of FDA timelines. Tokyo's National Cancer Center Japan now handles 40-60% of trial patients through hospital-controlled manufacturing.
China
Shanghai Jiao Tong University advances allogeneic candidates into Phase I using CRISPR-Cas12a ribonucleoprotein electroporation. NMPA regulatory pathways increasingly harmonize with ICH guidelines for cellular product submissions. Yangtze River Delta biotech clusters attract venture capital redirected from viral vector-dependent platforms.
Global Cell Based Immunotherapy Market Competitive Landscape
The competitive structure tilts toward integrated biopharmaceutical conglomerates with captive viral vector production networks. Consolidation concentrates among fewer than ten qualified GMP-grade lentiviral vector suppliers globally, creating single-source vulnerability for development-stage entrants. Three archetypes dominate: vector-integrated incumbents with manufacturing campuses, allogeneic platform specialists pursuing off-the-shelf administration, and academic spinouts commercializing institutional intellectual property. Capacity expansion and strategic partnerships constitute the dominant competitive moves as vein-to-vein timeline compression becomes the primary differentiation axis.
Among integrated biopharmaceutical incumbents, Bristol-Myers Squibb Company, Novartis AG, and Gilead Sciences Inc. occupy positions that exemplify the vector-integrated archetype. Bristol-Myers Squibb leverages production network control to secure raw material continuity. Novartis anchors market presence through dedicated manufacturing campuses in Switzerland and the United States. Gilead Sciences differentiates via streamlined logistics for cryopreserved patient-specific doses. These three represent the scale-driven tier where regulatory qualification and reimbursement establishment create defensive moats against allogeneic challengers.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Novartis AG |
| Gilead Sciences Inc. |
| F. Hoffmann-La Roche Ltd |
| Merck KGaA |
| Johnson & Johnson |
| Allogene Therapeutics |
| Adaptimmune Therapeutics |
| Celyad Oncology |
| Others |
Supply & Pricing Matrix
CMS's new technology add-on payment recalibration and Germany's G-BA benefit assessment are compressing reimbursement headroom for autologous therapies, forcing manufacturers toward automated closed-system platforms and allogeneic formats that collapse per-dose production costs. Supply networks must absorb these pricing constraints while maintaining cryogenic logistics integrity below minus 150 degrees Celsius.
Pricing Analysis
Value-based pricing anchored to complete response rates in hematologic malignancies structures commercial negotiations for approved CAR-T products. Three-tier pricing stratifies across academic hospital volume commitments, biopharmaceutical direct procurement, and contract manufacturing organization tolling arrangements. Cost compression in autologous segments is intensifying because vein-to-vein timeline guarantees now dominate contract terms. Community oncology centers exhibit highest price sensitivity due to absent cryopreserved dose infrastructure, while academic hospitals with captive manufacturing capacity command leverage through backward integration.
Supply Chain Analysis
Regional distribution centers in Maryland, Texas, and Basel operate hub-and-spoke patterns radiating to specialized infusion sites. GMP-grade lentiviral vector production concentrates in the United States, Switzerland, and selected European contract manufacturers. Supply networks draw from peripheral blood apheresis centers, cord blood banks, and induced pluripotent stem cell repositories. Single-source vulnerability pervades vector chemistry capabilities, with fewer than ten qualified suppliers globally. Distribution runs through liquid nitrogen vapor-phase cold chains to academic medical centers with dual EMA-FDA inspection readiness.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell based immunotherapy market sits in a technology-transition phase where CRISPR-Cas12a ribonucleoprotein electroporation is displacing lentiviral vector dependency and compressing manufacturing cost structures by 40-60 percent.
For Market Incumbents: To counter allogeneic platform challengers collapsing vein-to-vein timelines, vector-integrated incumbents should deepen backward integration into GMP-grade lentiviral production networks and accelerate automated closed-system manufacturing retrofitting at EMA-FDA dual-qualified campuses. Captive apheresis collection partnerships with Johns Hopkins-caliber academic centers anchor patient flow control against decentralized manufacturing erosion. For New Entrants and Emerging Players: Solid tumor antigen targeting represents the most penetrable white-space, with mesothelin and MUC16-directed TCR platforms addressing the 90 percent of cancers unresponsive to CD19-directed therapy. Japan's conditional early approval pathway offers regulatory arbitrage for revenue generation 18-24 months ahead of FDA timelines. A go-to-market angle through hospital-controlled manufacturing partnerships at MD Anderson or National Cancer Center Japan bypasses traditional CDMO dependency. For Investors and Strategic Acquirers: The window for entry favors allogeneic platform specialists with non-viral gene editing capabilities and isolator-based manufacturing infrastructure. Long-term viability hinges on automated production scalability across the 5-10 year technology maturation horizon. The signal to watch as inflection indicator is FDA regenerative medicine advanced therapy designation density shifting from autologous CAR-T toward NK cell and TCR platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Closed-System Manufacturing | Integration of CliniMACS Prodigy platforms collapses cleanroom labor intensity at Maryland and Texas facilities. |
| Non-Viral Gene Editing Transition | CRISPR-Cas12a electroporation eliminates lentiviral vector dependency and reduces cost structures at Shanghai Jiao Tong University. |
| Allogeneic Platform Development | Off-the-shelf NK cell formats collapse vein-to-vein timelines from weeks to days at University of Pennsylvania. |
| Academic Hospital Manufacturing Captivity | MD Anderson and Memorial Sloan Kettering internalize 40-60 percent of trial patient flow through IRB-controlled production. |
| Dual EMA-FDA Inspection Readiness | Swiss and Maryland campus retrofitting at 15-25 million dollars per site maintains transatlantic regulatory qualification. |
Research Methodology
Multi-period observation of FDA regenerative medicine advanced therapy designations, EMA priority medicines approvals, and PMDA sakigake grants anchored the trend analysis, supplemented by interviews with cell therapy development executives, regulatory affairs leads at biopharmaceutical manufacturers, hospital procurement managers at academic medical centers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov protocol registrations, and CMS reimbursement database updates. Bottom-up patient-flow modeling across apheresis centers and top-down manufacturing capacity assessments were triangulated against disclosed facility investment figures.
Input-output matrices mapped vector production capacity, cell processing throughput, and cryopreserved dose logistics across the projection horizon. Segmentation dimensions included product type, therapy area, end user institutional category, and delivery mode. CAGRs were derived from slope analysis of disclosed procedural volumes and announced manufacturing expansions. Forecast inputs incorporated academic hospital captive manufacturing adoption rates and allogeneic platform clinical advancement milestones.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lentiviral vector supply disruptions, reimbursement recalibration events, and automated manufacturing technology maturation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Leukemia Therapeutics Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Cancer Therapeutics Market