
 Global Duchenne Muscular Dystrophy Treatment Market | 2026-2036
Global Duchenne Muscular Dystrophy Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Duchenne Muscular Dystrophy Treatment Market Foresight
Specialty clinics are rotating toward gene therapy administration as corticosteroid prescribing stabilizes in mature markets. Sarepta Therapeutics anchors the exon skipping segment with established regulatory footholds in North America. PTC Therapeutics leverages its European market access to sustain reimbursement negotiations across multiple jurisdictions. Santhera Pharmaceuticals competes in the cardiac care adjacency with differentiated positioning against neuromuscular competitors.
Duchenne Muscular Dystrophy treatment encompasses pharmaceutical and biologic interventions targeting the X-linked recessive disorder caused by dystrophin gene mutations, with gene therapy products requiring ultra-cold chain logistics and single-infusion protocols designed to restore partial muscle function. The primary purpose spans preserving ambulation, delaying respiratory decline, and extending survival in pediatric and adolescent male patients. Gene therapy represents the fastest-growing product type as manufacturing scale constraints create margin concentration among vector producers. Exon skipping drugs occupy the mature revenue core where pricing power faces payer resistance. Intravenous delivery dominates hospital-based administration while subcutaneous formats gain traction in home care settings.
The FDA's accelerated approval framework and EMA's PRIME designation system jointly compress development timelines for dystrophin-targeting therapies, while Japan's PMDA orphan drug incentives attract sponsors to file in Tokyo ahead of broader Asian expansion. The EU AI Act introduces compliance obligations for algorithmic patient stratification tools used in clinical trial recruitment. Stakeholders must monitor how gene therapy durability data reshapes payer willingness to fund single-administration treatments against chronic corticosteroid regimens.
Market Dynamics
Gene therapy manufacturing bottlenecks are compressing commercialization timelines while vector production scarcity concentrates margin capture among contract development organizations with established adeno-associated virus platforms.
Growth Catalysts
- FDA Accelerated Approval Pathway:The FDA's streamlined review for rare disease therapies truncates Phase II-to-launch intervals, enabling sponsors to reach reimbursement negotiations eighteen months faster than standard oncology timelines.
- Exon Skipping Platform Expansion:Second-generation antisense oligonucleotide chemistry improves dystrophin restoration rates in amenable mutation subpopulations, broadening addressable patient pools beyond the original forty-five mutation targets.
- Japan PMDA Orphan Incentives:Tax credits and priority review vouchers attract gene therapy sponsors to Tokyo filings, establishing regulatory beachheads for subsequent Asian market expansion.
Market Restraints
- Ultra-Cold Chain Infrastructure Gaps:Vector stability requirements demand minus eighty-degree Celsius logistics networks that remain concentrated in the United States, Germany, and Japan, excluding middle-income markets from therapy access.
- Payer Resistance to Single-Administration Pricing:Annual corticosteroid costs of twelve thousand dollars create anchoring effects that complicate negotiations for three-million-dollar gene therapy infusions, particularly in German statutory health insurance.
- Manufacturing Yield Constraints:Suspension bioreactor productivity for triple-transfection AAV production remains below ten percent functional capsid recovery, capping batch volumes and inflating cost of goods.
Strategic Opportunities
- Latin American Regulatory Harmonization:Brazil ANVISA's alignment with FDA bioequivalence standards enables sponsors to leverage US trial data for accelerated market entry into São Paulo and Mexico City treatment centers.
- Cardiac Phenotype Indication Expansion:Dystrophin restoration in cardiomyocytes represents an untapped application beyond skeletal muscle preservation, with distinct reimbursement pathways through cardiology rather than neurology budgets.
- Subcutaneous Formulation Migration:Home administration of exon skipping drugs via subcutaneous pumps reduces hospital burden and unlocks pharmacy benefit manager coverage distinct from medical benefit infusion coding.
Industry Challenges
- Gene Therapy Durability Uncertainty:Five-year follow-up data gaps complicate health technology assessment submissions to England's NICE, delaying National Health Service formulary inclusion decisions.
- Cross-Border Vector Transport Compliance:EU GDP guidelines for genetically modified organism shipment classification create customs clearance friction between Belgian vector manufacturing sites and Spanish administration centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Duchenne Muscular Dystrophy Treatment Market |
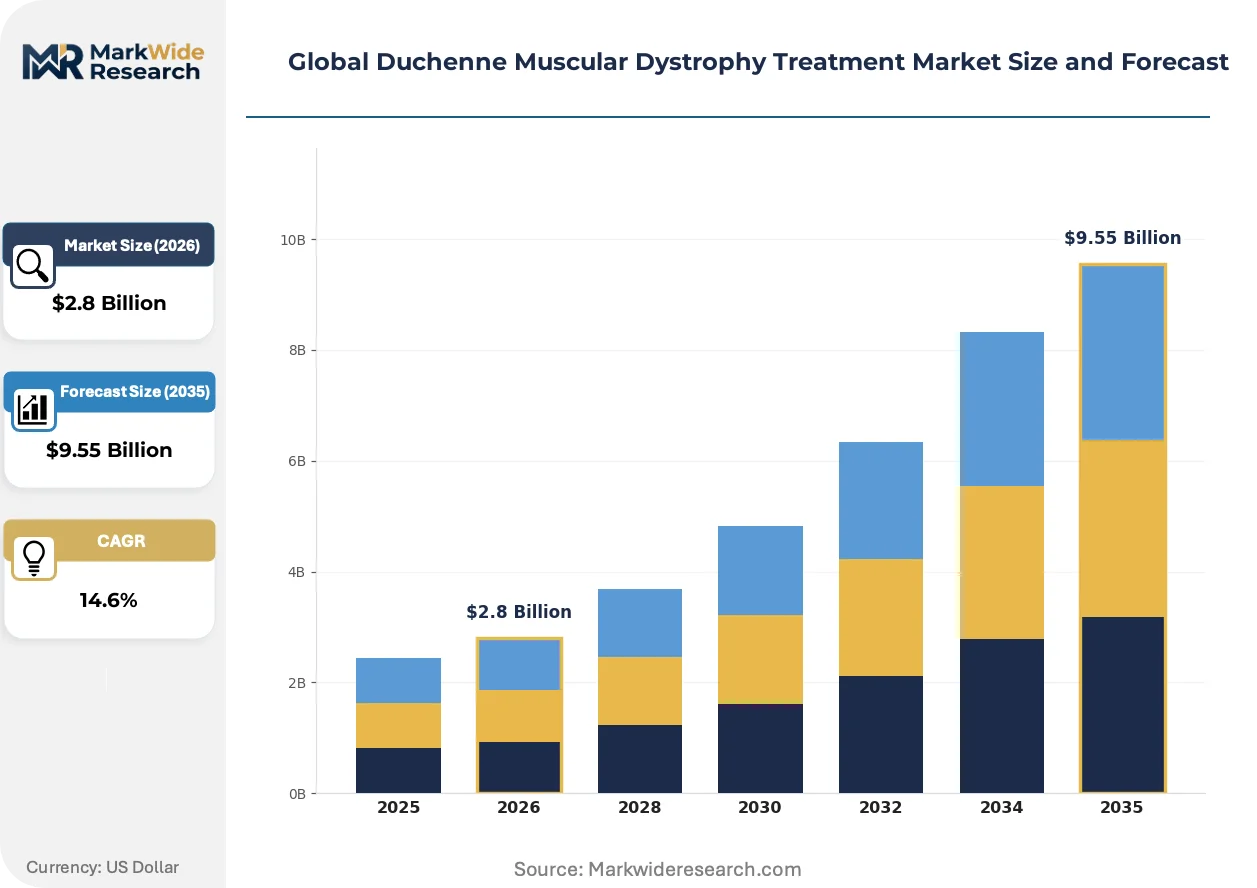
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Corticosteroids, Exon Skipping Drugs, Utrophin Modulators, Anti-inflammatory Agents Therapy Area: Muscle Strength Enhancement, Respiratory Support, Cardiac Care, Physical Rehabilitation, Immune Modulation End User: Specialty Clinics, Pediatric Neurology Centers, Research Institutes, Home Care Providers, Patient Advocacy Groups Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular, Inhalation |
| Companies Covered | Sarepta Therapeutics, PTC Therapeutics, NS Pharma, Italfarmaco S.p.A., Santhera Pharmaceuticals, Nippon Shinyaku, Capricor Therapeutics, FibroGen, Solid Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Duchenne Muscular Dystrophy Treatment Market Shifts & Advancements
Micro-dystrophin construct engineering is compressing the competitive window for first-generation gene therapies while CRISPR-based exon editing approaches advance through preclinical validation. These platform shifts are reconfiguring R&D allocation across vector biology, regulatory strategy, and manufacturing scale-up.
Next-generation AAV capsid engineering is decomposing the liver-tropism limitation that constrained first-wave Duchenne gene therapies to high vector doses. Sarepta Therapeutics and academic vector cores are selecting muscle-targeting serotypes that enable tenfold dose reductions, improving safety margins for pediatric ambulatory patients. This capsid refinement is decomposing the manufacturing volume requirements that previously gated commercial feasibility, enabling single-facility supply to address entire European patient populations.
EMA's PRIME designation system is compressing scientific advice timelines for advanced therapy medicinal products, with parallel EMA-FDA orphan drug cluster meetings enabling synchronized regulatory strategy. The industrial consequence is consolidated global development programs rather than sequential geographic filings. Gene therapy sponsors with PRIME status are securing accelerated assessment slots that compress EMA opinion-to-Commission decision intervals from 210 to 150 days, affecting primarily the exon skipping and gene replacement segments where European pricing premiums justify priority filing.
Specialty pharmacy networks are displacing hospital outpatient departments as the primary administration site for corticosteroid and exon skipping regimens. US payers are mandating exclusive specialty pharmacy arrangements that consolidate patient monitoring data and capture pharmacy rebate value. This channel migration is most visible in Texas and Florida, where independent neuromuscular centers are ceding infusion volume to CVS Specialty and Accredo-managed sites with integrated adherence tracking and prior authorization management capabilities.
Global Duchenne Muscular Dystrophy Treatment Market Segmentation
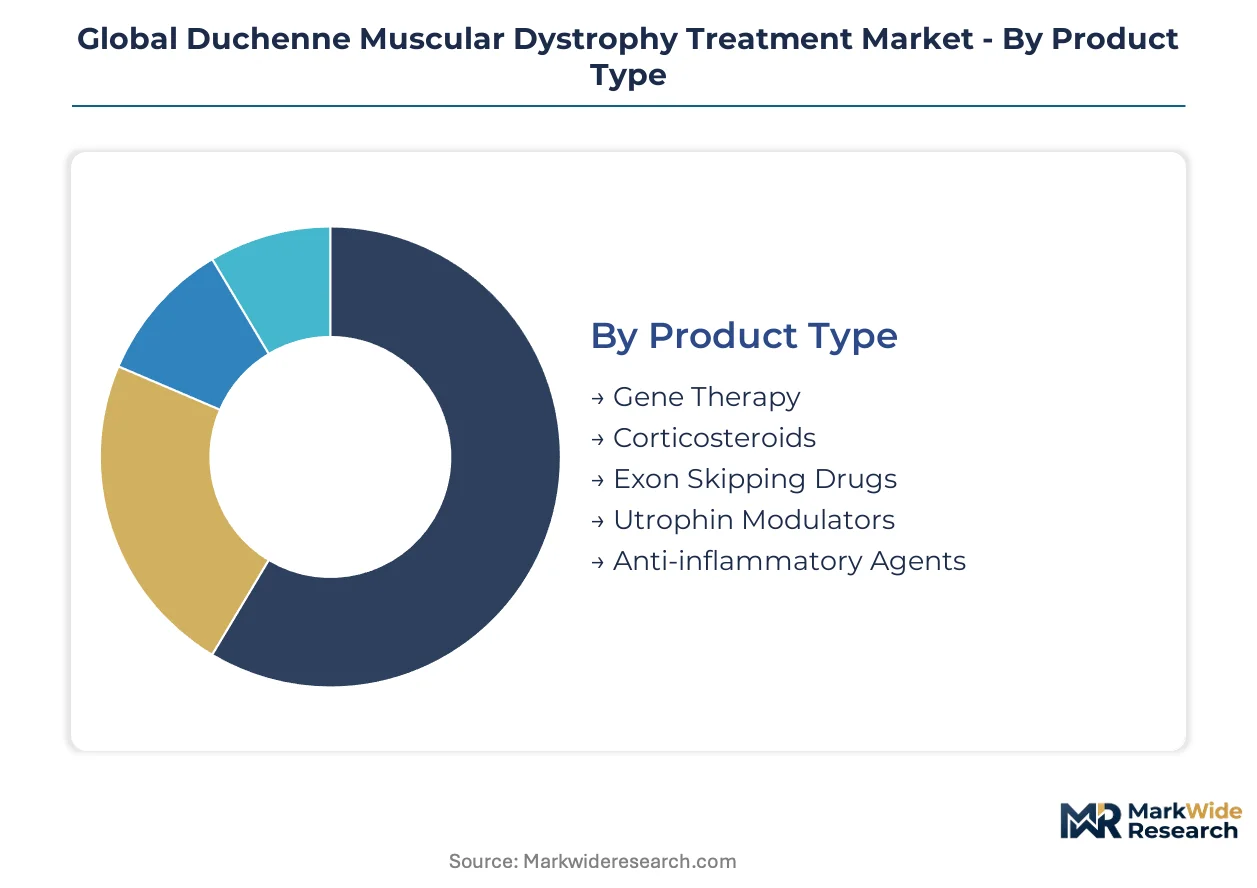
Duchenne Muscular Dystrophy treatment markets fragment across biological mechanism, clinical application, and care setting. Each segmentation axis carries distinct regulatory pathways, reimbursement codes, and supply chain requirements that shape commercial strategy.
Product Type:
FDA accelerated approval and EMA PRIME designation create divergent market access timelines across biological categories, with gene therapies commanding distinct logistics infrastructure compared to small-molecule regimens.
- Gene Therapy:Adeno-associated virus vectors deliver micro-dystrophin constructs via single-infusion protocols. Ultra-cold chain requirements at minus eighty degrees Celsius restrict administration to certified centers in the United States, Germany, and Japan where vector stability infrastructure exists.
- Exon Skipping Drugs:Antisense oligonucleotides restore reading frame in amenable mutation subpopulations through weekly intravenous infusion. Payer resistance to chronic high-cost administration complicates formulary placement in German statutory health insurance and England's NICE assessments.
- Corticosteroids:Standard-of-care glucocorticoid regimens delay disease progression through chronic oral or intermittent dosing. Generic substitution pressure concentrates volume in pharmacy benefit manager formularies.
- Utrophin Modulators:Small-molecule upregulators of the dystrophin homolog target mutation-agnostic patient pools. Clinical validation gaps delay regulatory submission timelines.
- Anti-inflammatory Agents:Adjunctive therapies targeting fibrotic cascade progression. Narrow labeling restricts addressable population to steroid-intolerant subgroups.
Gene therapy handles the majority of throughput value concentration; gene therapy is expanding most quickly on share as manufacturing scale constraints ease.
Therapy Area:
Clinical endpoints and reimbursement logic vary sharply across organ system targets, with cardiac indications accessing distinct budget lines from neuromuscular preservation.
- Muscle Strength Enhancement:Primary functional outcomes including ambulation preservation and upper limb function. Six-minute walk test endpoints anchor FDA accelerated approval decisions for dystrophin-restoring therapies.
- Cardiac Care:Cardiomyopathy progression delay through dystrophin restoration in myocardial tissue. Cardiology department budgets in Texas Medical Center and Heidelberg University Hospital provide separate reimbursement pathways from neurology allocations.
- Respiratory Support:Pulmonary function preservation and nocturnal ventilation delay. Home mechanical ventilation cost offsets justify payer investment in disease-modifying upstream therapy.
- Physical Rehabilitation:Adjunctive occupational and physical therapy maintaining functional independence. Bundled payment models in Medicare Advantage constrain standalone reimbursement.
- Immune Modulation:Corticosteroid-sparing approaches targeting inflammatory myopathy. Limited clinical evidence restricts prescriber adoption outside academic medical centers.
Muscle strength enhancement captures the dominant patient volume; cardiac care is climbing the fastest as micro-dystrophin constructs demonstrate cardiomyocyte transduction.
End User:
Site-of-care migration from hospital outpatient departments to integrated specialty networks reconfigures purchasing authority and data capture economics.
- Specialty Clinics:Dedicated neuromuscular centers with genetic counseling and multidisciplinary care coordination. CVS Specialty and Accredo networks in Florida and Texas consolidate infusion volume through exclusive payer contracts.
- Pediatric Neurology Centers:Academic medical centers with clinical trial infrastructure and natural history study enrollment. Boston Children's Hospital and Cincinnati Children's anchor US gene therapy access.
- Home Care Providers:Subcutaneous pump administration and nursing support for chronic regimens. Pharmacy benefit manager coverage expansion enables site-of-care migration.
- Research Institutes:Phase I/II trial execution and biomarker validation. EMA PRIME designation requirements mandate European academic partnership.
- Patient Advocacy Groups:Registry maintenance and trial recruitment acceleration. Parent Project Muscular Dystrophy and CureDuchenne shape FDA patient-focused drug development meetings.
Specialty clinics manage the majority of commercial throughput; home care providers are gaining share fastest as subcutaneous formulations advance.
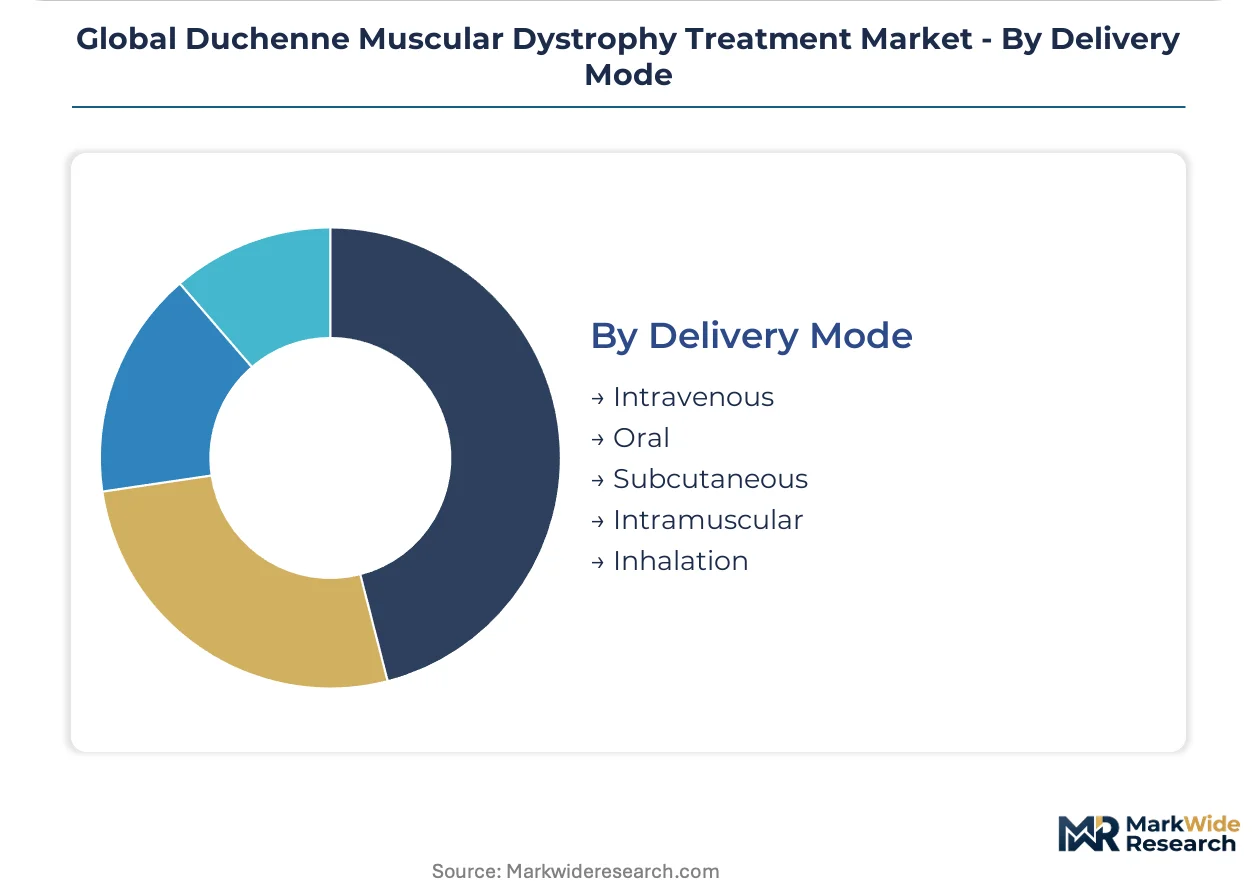
Delivery Mode:
Route of administration determines supply chain configuration, with hospital-based infusion requiring distinct cold chain infrastructure from oral or home-administered alternatives.
- Intravenous:Hospital or infusion center administration for gene therapy and exon skipping drugs. Prior authorization complexity concentrates volume in sites with dedicated neuromuscular pharmacy support.
- Subcutaneous:Home pump administration for chronic antisense oligonucleotide regimens. Reimbursement coding migration from medical to pharmacy benefit unlocks PBM rebate capture.
- Oral:Corticosteroid and small-molecule maintenance therapy. Generic substitution and adherence monitoring dominate commercial dynamics.
- Intramuscular:Localized vector delivery in investigational protocols. Limited to early-phase academic trials.
- Inhalation:Pulmonary-targeted delivery for respiratory phenotype modification. Formulation stability challenges delay clinical translation.
Intravenous delivery handles the majority of gene therapy and exon skipping volume; subcutaneous administration is advancing fastest on share as home care infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The ultra-cold chain infrastructure connecting Philadelphia International Airport to European hubs underwrites transatlantic vector distribution for gene therapy programs. Dedicated pharmaceutical corridors link manufacturing sites in Massachusetts to administration centers in Texas and Florida. This logistics architecture concentrates patient access in markets with minus eighty-degree Celsius storage capabilities.
United States
Boston Children's Hospital and Cincinnati Children's anchor gene therapy administration volume. FDA accelerated approval pathways compress Phase II-to-launch intervals by eighteen months versus standard oncology timelines. The Texas Medical Center corridor consolidates infusion capacity through CVS Specialty and Accredo exclusive payer contracts.
Germany
Heidelberg University Hospital maintains cardiac phenotype trial infrastructure for dystrophin-restoring therapies. EMA PRIME designation enables sponsors to secure accelerated assessment slots compressing opinion-to-Commission decision intervals from 210 to 150 days. Bavarian statutory health insurance funds negotiate single-administration gene therapy pricing against twelve-thousand-dollar annual corticosteroid anchors.
Japan
PMDA orphan drug tax credits attract sponsors to file in Tokyo ahead of broader Asian expansion. Priority review vouchers compress regulatory timelines for micro-dystrophin construct submissions. The Kanto region's cold chain infrastructure supports vector stability requirements for pediatric neuromuscular centers.
United Kingdom
NICE health technology assessment submissions face five-year gene therapy durability data gaps delaying National Health Service formulary inclusion. England's clinical trial infrastructure maintains natural history study enrollment partnerships with academic medical centers. London-based specialty pharmacy networks displace hospital outpatient departments for corticosteroid administration.
Brazil
ANVISA alignment with FDA bioequivalence standards enables sponsors to leverage US trial data for São Paulo market entry. Middle-income market exclusion from ultra-cold chain networks limits gene therapy access to private treatment centers. The country's national pharmaceutical regulator maintains genetically modified organism shipment classification protocols creating customs clearance friction.
Global Duchenne Muscular Dystrophy Treatment Market Competitive Landscape
Concentration sits with gene therapy vector developers and exon skipping platform holders. The competitive structure fragments across biological mechanism rather than consolidating around integrated care provision. Three archetypes dominate: micro-dystrophin construct engineers, antisense oligonucleotide chemists, and cardiac phenotype specialists. Capacity expansion in Belgian vector manufacturing sites and strategic partnerships for AAV suspension bioreactor technology represent the dominant competitive moves.
Among US-based biologics developers, Sarepta Therapeutics and PTC Therapeutics exemplify divergent platform strategies. Sarepta occupies a position within the gene replacement archetype, while PTC represents the European market access-focused exon skipping tier. Santhera Pharmaceuticals anchors the cardiac care adjacency with differentiated positioning against neuromuscular competitors. These three entities collectively illustrate how regulatory foothold geography—North American accelerated approval versus European reimbursement negotiation—shapes competitive archetype selection.
| Leading Market Players |
|---|
| Sarepta Therapeutics |
| PTC Therapeutics |
| NS Pharma |
| Italfarmaco S.p.A. |
| Santhera Pharmaceuticals |
| Nippon Shinyaku |
| Capricor Therapeutics |
| FibroGen |
| Solid Biosciences |
| Others |
Supply & Pricing Matrix
Capacity reservation contracts with Belgian vector manufacturing sites lock in AAV supply access and stabilize cost visibility for gene therapy sponsors navigating FDA accelerated approval timelines. These arrangements tether pricing power to suspension bioreactor yield improvements while excluding middle-income markets lacking minus eighty-degree Celsius infrastructure.
Pricing Analysis
Volume-discount tiering structures separate single-infusion gene therapy protocols from chronic exon skipping regimens and generic corticosteroid maintenance. Pricing stratifies across premium micro-dystrophin constructs, standard antisense oligonucleotide platforms, and economy glucocorticoid tiers differentiated by mutation amenability and administration burden. Cost compression in the corticosteroid tier intensifies because of pharmacy benefit manager formulary substitution, while German statutory health insurance exhibits highest price sensitivity to single-administration gene therapy anchors.
Supply Chain Analysis
Philadelphia International Airport container availability constraints and transatlantic pharmaceutical corridor congestion elevate inbound logistics costs for temperature-sensitive vector shipments. Manufacturing concentrates in Belgium, Massachusetts, and North Carolina, drawing from triple-transfection plasmid banks, HEK293 cell lines, and specialized resin chromatography media. Single-source vulnerability at suspension bioreactor facilities creates supply chain risk. Distribution runs through certified specialty pharmacy networks with integrated cold chain monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy sponsors face substitution defense imperatives as CRISPR-based exon editing advances through preclinical validation, threatening first-generation micro-dystrophin construct positioning. Incumbents must navigate this platform transition while preserving reimbursement negotiations.
For Market Incumbents: Consolidate manufacturing scale through backward integration into AAV suspension bioreactor technology, securing yield improvements above ten percent functional capsid recovery. Lock in exclusive specialty pharmacy contracts across Texas and Florida to defend channel control against CVS Specialty and Accredo network consolidation. Counter CRISPR platform substitution threats by accelerating cardiac phenotype indication expansion into distinct cardiology budget lines. For New Entrants and Emerging Players: Differentiate on subcutaneous formulation development for exon skipping drugs, targeting home care provider segments where pharmacy benefit manager coverage migration unlocks reimbursement pathways. Penetrate Latin American markets through Brazil ANVISA regulatory harmonization, leveraging FDA trial data for São Paulo market entry. Pursue utrophin modulator platforms addressing mutation-agnostic patient pools overlooked by mutation-specific competitors. For Investors and Strategic Acquirers: Capital is best deployed toward vector biology specialists with established EMA PRIME designation and muscle-targeting AAV capsid engineering capabilities. Long-term viability hinges on five-year durability data generation enabling NICE health technology assessment approval. Watch for inflection signals in Belgian manufacturing site capacity expansion announcements indicating supply constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Belgian suspension bioreactor expansion addresses ten percent functional capsid yield constraints. |
| Regulatory Approval Pathway | EMA PRIME designation compresses opinion-to-Commission decision intervals for advanced therapy medicinal products. |
| Pipeline Diversification | Cardiac phenotype indication expansion accesses Heidelberg University Hospital cardiology budgets. |
| Licensing Agreement | Academic vector core partnerships enable muscle-targeting serotype selection for dose reduction. |
| Clinical Trial Advancement | Natural history study enrollment at Boston Children's Hospital anchors FDA accelerated approval submissions. |
Research Methodology
Operator-level perspectives from gene therapy development executives, regulatory affairs leads, payer access specialists, and hospital procurement managers anchored the qualitative base. These primary insights combined with FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary database validation. Bottom-up patient population modeling and top-down revenue triangulation across treatment mechanism segments refined the analytical framework.
Sensitivity analysis tested vector manufacturing yield scenarios, payer resistance coefficients, and regulatory timeline compression effects across the projection horizon. The forecast framework modeled segmentation across gene therapy, exon skipping, corticosteroid, and emerging platform categories by therapy area, end user site-of-care, and delivery mode. CAGRs derived from patient incidence projections, pricing negotiation outcomes, and manufacturing scale-up curves incorporating AAV capsid engineering advancement rates.
Decision-makers should treat outputs as directional under assumptions of stable FDA accelerated approval pathway integrity and sustained German statutory health insurance orphan drug reimbursement; material deviation in gene therapy durability data or EMA PRIME designation criteria would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Gene Panel Market