
 Retinitis Pigmentosa Treatment Market | 2026-2036
Retinitis Pigmentosa Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Retinitis Pigmentosa Treatment Market Outlook
Recombinant adeno-associated viral vectors are consolidating as the dominant delivery vehicle for retinal gene therapies, displacing earlier synthetic nanoparticle platforms that carried higher immunogenicity risks and manufacturing inconsistency. Spark Therapeutics leverages its pioneering FDA-approved Luxturna infrastructure to sustain manufacturing scale across specialized viral vector facilities. ProQR Therapeutics anchors its competitive position through RNA-editing platforms targeting specific RP gene mutations. Novartis competes via ophthalmology franchise depth and global distribution networks for rare disease therapeutics.
Retinitis pigmentosa treatment encompasses therapeutic interventions targeting inherited retinal dystrophies caused by mutations in over 80 identified genes, primarily affecting photoreceptor and retinal pigment epithelium function through progressive degeneration. Gene therapy interventions typically employ subretinal delivery of functional gene copies via engineered viral vectors to restore phototransduction in surviving cells. Pharmaceutical segments including oral and topical formulations currently occupy the largest revenue share due to broader accessibility and established reimbursement pathways. Subretinal delivery modes command premium positioning despite surgical complexity, as this route achieves direct transduction of retinal pigment epithelium and photoreceptors with superior efficacy thresholds. Research institutions represent the fastest-growing end-user channel, driven by expanded investigator-initiated trials and academic-industry partnerships in gene therapy development.
FDA orphan drug designation and regenerative medicine advanced therapy pathways shape clinical trial incentives and accelerated review timelines for RP developers seeking US market access. EMA's Committee for Orphan Medicinal Products and the EU ATMP framework establish parallel European standards for gene therapy quality, safety, and efficacy verification. Japan's PMDA sakigake designation system creates prioritized consultation pathways for novel retinal therapies targeting the country's substantial RP patient population. Stakeholders must monitor how evolving payer evidence requirements for single-administration gene therapies will reshape pricing negotiations and patient access programs across these regulatory jurisdictions.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation is compressing clinical development timelines and redistributing capital toward gene therapy platforms, fundamentally altering how retinal disease developers sequence regulatory submissions and manufacturing investments.
Growth Catalysts
- EMA's ATMP Framework:The EU's advanced therapy medicinal products pathway provides centralized marketing authorization for gene therapies, reducing regulatory fragmentation across member states and accelerating patient access timelines.
- Subretinal Delivery Infrastructure:Specialized vitreoretinal surgical centers in the United States, Germany, and Japan are standardizing subretinal injection protocols, building the procedural capacity required for gene therapy commercialization.
- Orphan Drug Incentives:FDA orphan drug designation grants seven-year market exclusivity and tax credits for clinical trial costs, redirecting venture capital toward rare retinal disease indications with smaller addressable populations.
Market Restraints
- Viral Vector Manufacturing Bottleneck:Recombinant adeno-associated virus production capacity concentrates at specialized contract manufacturing organizations in the United States and Europe, creating supply constraints for multi-product pipelines.
- Reimbursement Uncertainty:Single-administration gene therapies face payer resistance due to high upfront costs and limited long-term efficacy data, forcing developers to construct outcomes-based payment arrangements.
- Immunogenicity Risks:Pre-existing neutralizing antibodies against AAV serotypes exclude substantial patient subpopulations from treatment eligibility, narrowing addressable markets for first-generation products.
Strategic Opportunities
- Japan's Sakigake Designation:PMDA's prioritized consultation system offers early regulatory dialogue for novel retinal therapies, positioning Japan as a favorable launch geography for gene therapy developers.
- RNA-Editing Platforms:Antisense oligonucleotide and base-editing technologies enable mutation-agnostic approaches targeting dominant-negative alleles, expanding addressable genetic variant coverage beyond what replacement therapies can achieve.
- Academic-Industry Partnerships:Research institutions in Boston, Basel, and Kyoto are establishing dedicated retinal gene therapy accelerators, creating de-risked pathways from discovery through first-in-human studies.
Industry Challenges
- Vitreoretinal Surgical Training:Subretinal injection requires specialized skills distinct from standard ophthalmic surgery, creating a procedural bottleneck as commercial volumes scale beyond academic medical centers.
- Long-Term Durability Monitoring:Gene therapy developers must construct fifteen-to-twenty-year follow-up registries to satisfy payer and regulator demands for sustained efficacy evidence, imposing substantial post-market infrastructure costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinitis Pigmentosa Treatment Market |
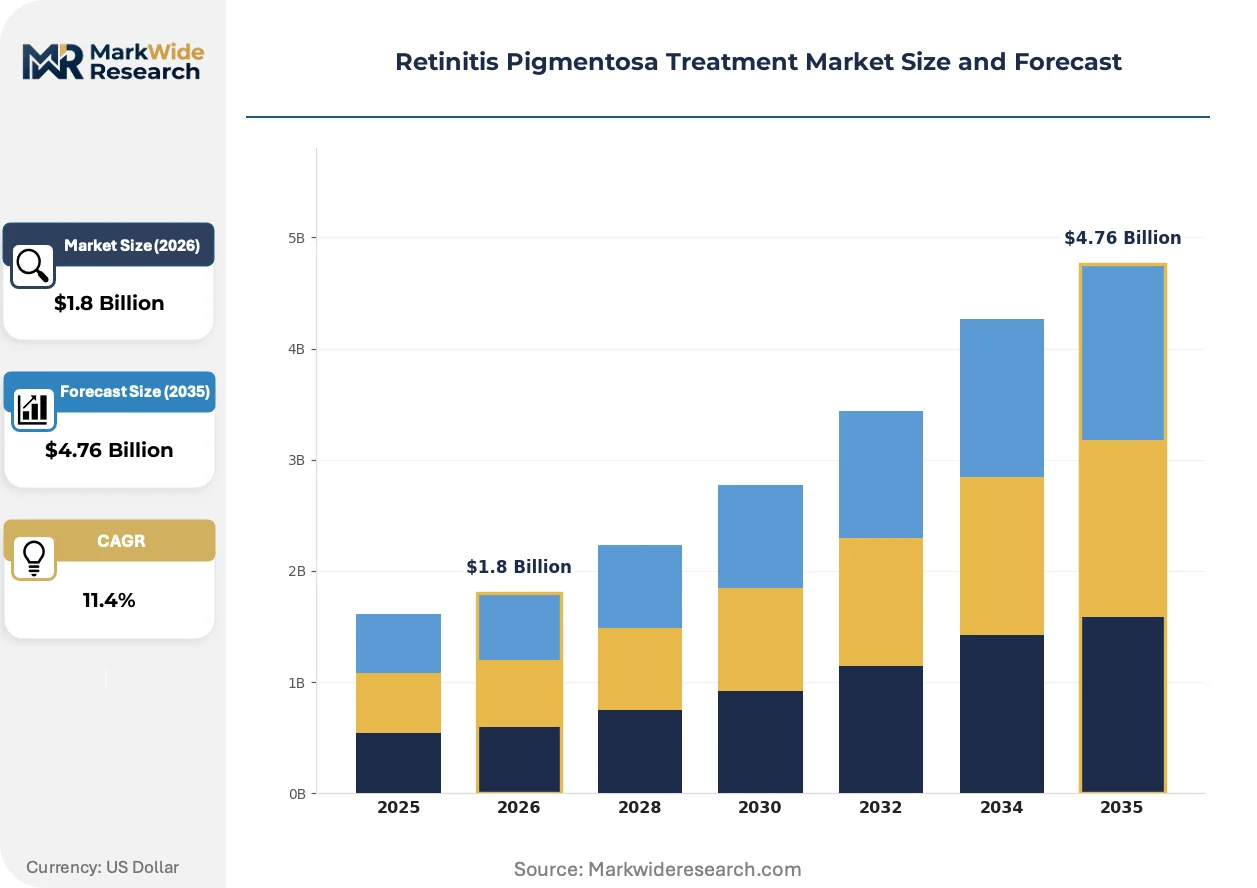
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Pharmaceutical, Medical Devices, Nutraceuticals Delivery Mode: Intravitreal, Subretinal, Oral, Topical End User: Hospitals, Clinics, Homecare, Research Institutions Treatment Stage: Early Intervention, Disease Progression, Symptom Management, Advanced Therapy |
| Companies Covered | Spark Therapeutics, ProQR Therapeutics, Gensight Biologics, Biogen, Regeneron Pharmaceuticals, Novartis, Nanoscope Therapeutics, Ocugen, MeiraGTx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinitis Pigmentosa Treatment Market Strategic Shifts
Gene delivery technologies are diversifying beyond first-generation viral vectors, while regulatory frameworks adapt to accommodate single-administration therapies with complex manufacturing and long-duration follow-up requirements.
Dual-vector systems and engineered AAV capsids with enhanced retinal tropism are expanding into clinical development pipelines, addressing payload size limitations and pre-existing immunity barriers that constrained earlier platforms. Ophthalmology-focused contract development organizations in the United States and Europe are scaling dedicated viral vector suites to support these programs. The structural consequence is that manufacturing partnerships are becoming the critical gating factor for pipeline progression, compressing timelines for developers with captive production assets.
The FDA's regenerative medicine advanced therapy designation grants rolling review and priority evaluation to qualifying gene therapies, compressing regulatory review timelines from twelve to eight months for eligible submissions. This pathway requires demonstration of preliminary clinical evidence addressing unmet medical need in serious conditions. Retinal gene therapy developers targeting RPE65 and other validated mutations are restructuring clinical trial designs to capture this designation, prioritizing US regulatory submissions over parallel EMA filings.
Patient advocacy organizations are consolidating demand-side influence, shifting from passive funding sources to active clinical trial design partners and reimbursement negotiators. The Foundation Fighting Blindness and similar entities in the United States now participate in protocol development and endpoint selection discussions, displacing traditional investigator-driven trial architectures. This concentration is most visible in the United States, where organized patient cohorts command attention from payers and regulators evaluating novel therapies for ultra-rare indications.
Retinitis Pigmentosa Treatment Market Segmentation
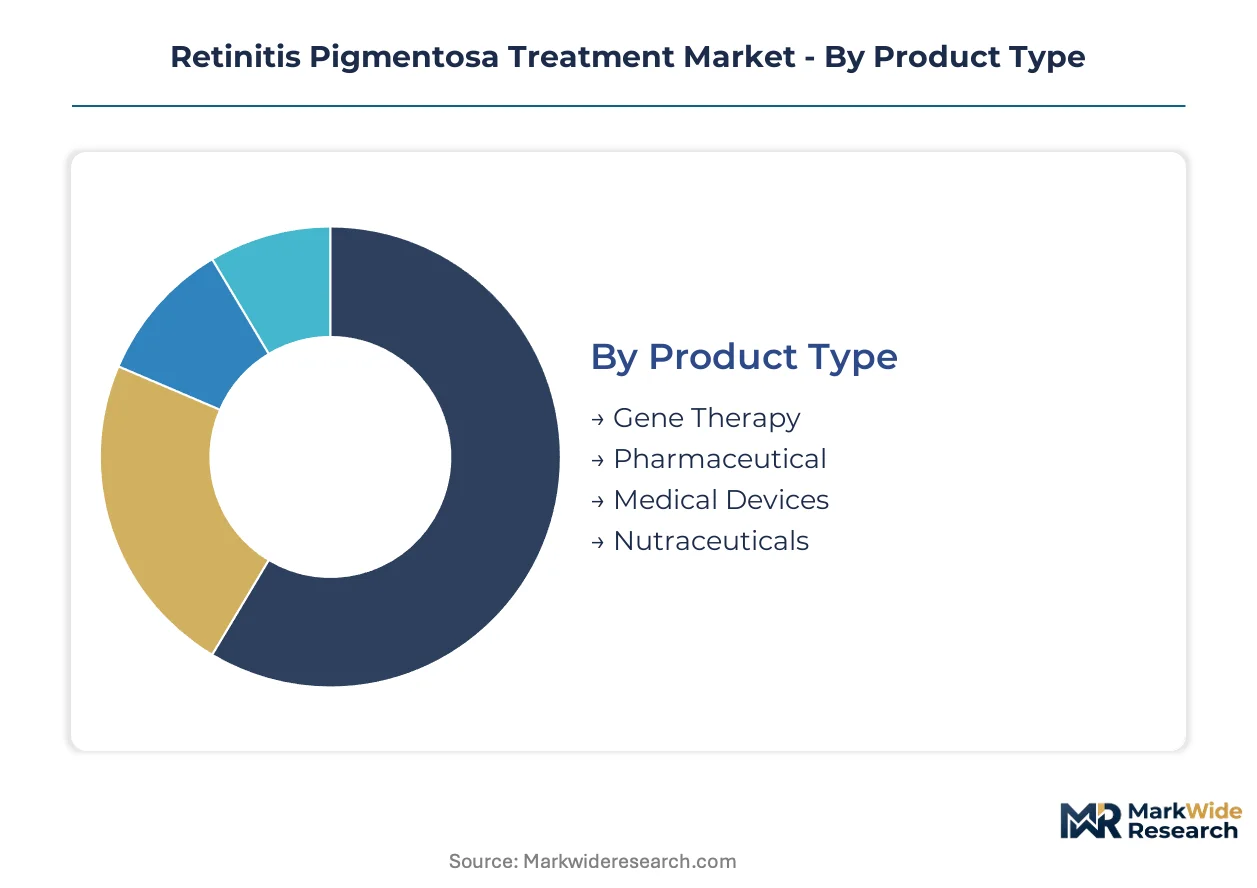
Retinitis pigmentosa treatment segmentation reflects divergent technical requirements across genetic subtypes, surgical capabilities, and reimbursement pathways. Each category captures distinct buyer economics—from hospital systems financing gene therapy suites to patients self-administering oral supplements.
Product Type:
Cost tiers separate curative interventions from chronic management approaches, with reimbursement complexity rising proportionally to therapeutic permanence.
- Gene Therapy:Functional gene copies delivered via engineered viral vectors directly address monogenic RP mutations at the cellular level. Subretinal administration in specialized surgical centers in the United States and Germany commands premium positioning due to manufacturing scale constraints and FDA regenerative medicine advanced therapy pathways.
- Pharmaceutical:Oral and topical formulations targeting oxidative stress, inflammation, and metabolic support currently generate the broadest patient access through established pharmacy distribution and payer familiarity with chronic medication coverage.
- Medical Devices:Retinal prosthetics and visual aids compensate for photoreceptor loss through electrical stimulation or optical enhancement, serving patients with advanced degeneration beyond gene therapy candidacy.
- Nutraceuticals:Vitamin A palmitate, omega-3 fatty acids, and antioxidant formulations occupy the lowest price tier with minimal regulatory scrutiny, appealing to patients seeking self-directed intervention.
Volume sits with Pharmaceutical; growth tilts toward Gene Therapy.
Delivery Mode:
Application setting determines technical infrastructure requirements, with surgical routes demanding capital investment and nonsurgical options enabling broader geographic reach.
- Subretinal:Direct injection beneath the neural retina achieves optimal transduction efficiency for retinal pigment epithelium and photoreceptor cells. Academic medical centers in Japan and the United States are standardizing vitreoretinal surgical protocols to support commercial gene therapy volumes.
- Intravitreal:Injection into the vitreous cavity offers reduced surgical complexity compared to subretinal approaches, though retinal penetration limitations constrain efficacy for certain genetic targets.
- Oral:Systemic administration via capsule or tablet formulations bypasses ocular barriers entirely, enabling home-based chronic management without specialized ophthalmic infrastructure.
- Topical:Eye drop formulations provide localized drug delivery with minimal invasiveness, though corneal penetration challenges limit therapeutic payload delivery to posterior segment tissues.
Patient volume concentrates in Oral and Topical; steepest expansion trajectory belongs to Subretinal as gene therapy pipelines mature.
End User:
Customer type differentiation reflects capital intensity, reimbursement sophistication, and clinical trial participation depth across the care continuum.
- Research Institutions:Academic medical centers and dedicated retinal research facilities in Boston, Basel, and Kyoto are expanding investigator-initiated gene therapy trials and industry partnerships. EMA ATMP framework familiarity and FDA orphan drug incentive navigation distinguish these buyers from community providers.
- Hospitals:Tertiary care systems with dedicated ophthalmology departments and surgical suites capture complex interventions requiring anesthesia support and overnight observation capabilities.
- Clinics:Specialized ophthalmology practices and ambulatory surgery centers handle diagnostic evaluation, chronic management, and selected surgical procedures with lower acuity requirements.
- Homecare:Patient-administered therapies and remote monitoring programs extend treatment access beyond institutional settings, particularly for oral pharmaceutical and nutraceutical regimens.
Revenue share clusters in Hospitals; share expansion is gaining fastest in Research Institutions.
Treatment Stage:
Maturity of disease progression dictates therapeutic objective, from preservation of remaining function to substitution of lost capability.
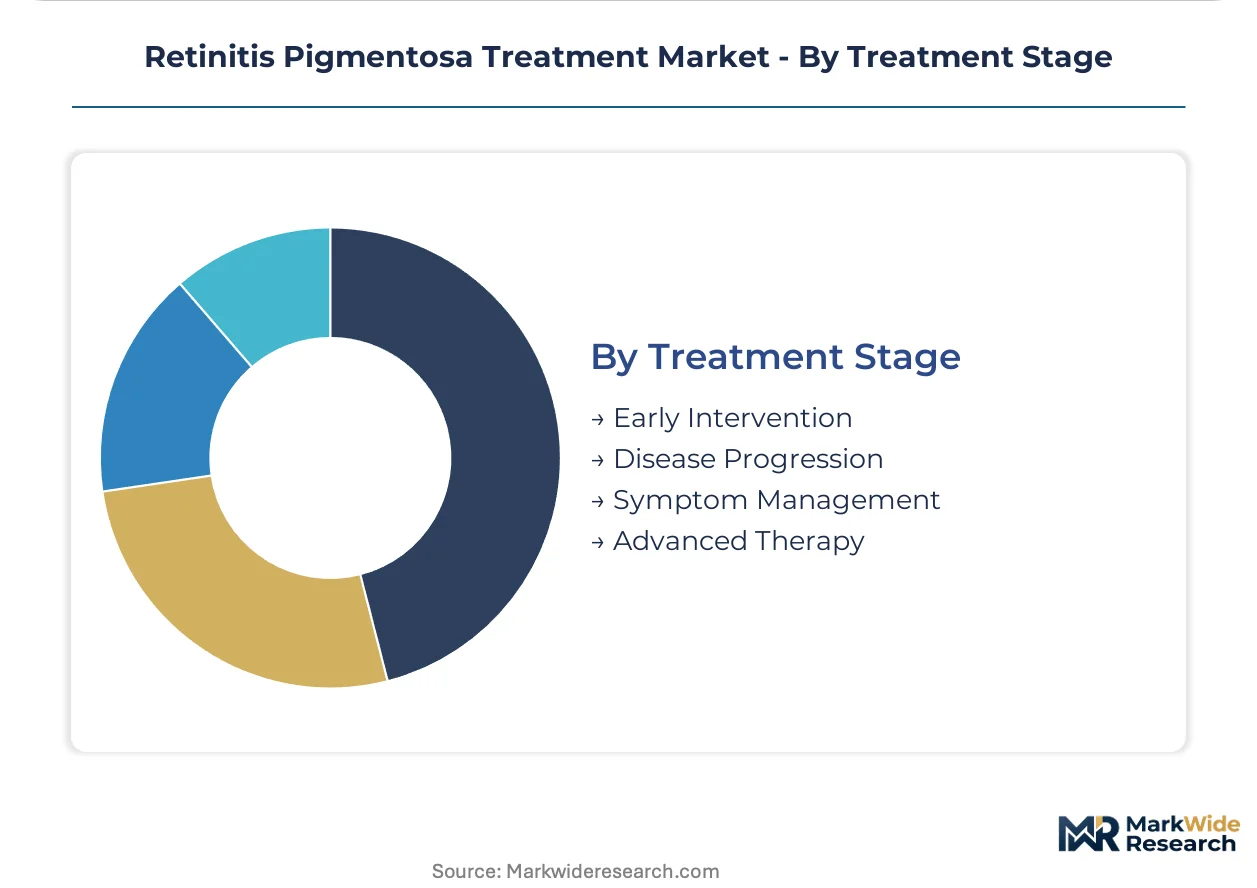
- Early Intervention:Gene therapy and neuroprotective approaches target patients with confirmed genetic diagnosis and measurable but preserved visual function. PMDA sakigake designation pathways in Japan prioritize regulatory consultation for novel therapies addressing this window.
- Advanced Therapy:Curative or substantially disease-modifying interventions including subretinal gene delivery require sufficient viable retinal tissue for transduction, creating narrow candidacy criteria.
- Disease Progression:Interventions aimed at slowing rate of photoreceptor loss occupy the largest addressable population as genetic testing expands diagnostic identification of at-risk individuals.
- Symptom Management:Low vision rehabilitation, optical aids, and supportive medications serve patients with substantial irreversible vision loss where disease modification is no longer feasible.
Patient volume concentrates in Disease Progression; strategic investment tilts toward Early Intervention as genetic screening expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient recruitment for gene therapy trials concentrates in the United States, Germany, and Japan, where specialized vitreoretinal surgical infrastructure and streamlined regulatory pathways for rare diseases have created concentrated demand pockets for advanced RP interventions.
United States
Academic medical centers in Boston and Philadelphia drive investigator-initiated gene therapy trials through the Foundation Fighting Blindness clinical research network. FDA orphan drug designation grants seven-year market exclusivity and tax credits, redirecting venture capital toward rare retinal disease indications. Spark Therapeutics maintains manufacturing scale across specialized viral vector facilities in the Philadelphia corridor.
Germany
University hospitals in Tübingen and Munich anchor European gene therapy development through EMA ATMP framework navigation and centralized marketing authorization pathways. German vitreoretinal surgical centers standardize subretinal injection protocols, building procedural capacity for commercial gene therapy volumes. The country's national pharmaceutical regulator facilitates early scientific advice meetings for novel retinal therapies.
Japan
PMDA sakigake designation creates prioritized consultation pathways for gene therapy developers targeting Japan's substantial RP patient population. Tokyo and Osaka host specialized retinal treatment centers with established investigator-initiated trial infrastructure. Japanese ophthalmology departments participate actively in multinational gene therapy protocols, leveraging regulatory harmonization with FDA and EMA standards.
United Kingdom
London and Oxford concentrate retinal gene therapy research through academic-industry partnerships and NHS specialized commissioning frameworks. The Medicines and Healthcare products Regulatory Agency operates rolling review pathways for advanced therapy medicinal products. British patient advocacy organizations influence clinical trial design and reimbursement negotiations for ultra-rare retinal indications.
France
Paris and Strasbourg host dedicated retinal research facilities with EMA ATMP framework familiarity and early access programs for innovative therapies. ANSM provides scientific advice and accelerated assessment pathways for gene therapies addressing unmet medical needs. French university hospitals participate in multinational gene therapy trials through European Reference Networks for rare eye diseases.
Retinitis Pigmentosa Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with gene therapy developers consolidating around captive viral vector production while pharmaceutical incumbents leverage established distribution networks for chronic management products. The competitive structure fragments across three tiers: integrated gene therapy platforms with manufacturing assets, RNA-editing specialists with mutation-agnostic technologies, and diversified ophthalmology franchises with global commercial infrastructure. Strategic moves concentrate on manufacturing partnerships to secure AAV supply and academic alliances to de-risk early-stage programs.
Within the integrated gene therapy tier, Spark Therapeutics and Novartis occupy positions anchored by FDA-approved infrastructure and global rare disease distribution networks. ProQR Therapeutics exemplifies the RNA-editing specialist archetype, targeting specific genetic variants through antisense oligonucleotide platforms. These three companies represent divergent technical approaches to RP intervention—viral gene replacement, global commercial scale, and mutation-specific RNA modulation—reflecting the market's segmentation across curative modalities.
| Leading Market Players |
|---|
| Spark Therapeutics |
| ProQR Therapeutics |
| Gensight Biologics |
| Biogen |
| Regeneron Pharmaceuticals |
| Novartis |
| Nanoscope Therapeutics |
| Ocugen |
| MeiraGTx |
| Others |
Value Chain & Pricing Dynamics
AAV vector production costs at contract manufacturing organizations in the United States and Europe cascade through three distinct pricing tiers, with subretinal gene therapies commanding premium positioning while oral pharmaceuticals and nutraceuticals occupy accessible price bands shaped by manufacturing scale and reimbursement complexity.
Pricing Analysis
Volume concentrates in chronic oral and topical formulations with established pharmacy distribution, while margins cluster in subretinal gene therapies where viral vector manufacturing constraints and specialized surgical delivery create scarcity pricing. Price differentiation hinges on FDA regenerative medicine advanced therapy designation status and captive manufacturing assets versus outsourced production. Cost compression in pharmaceutical segments intensifies as generic alternatives expand, while gene therapy pricing faces payer resistance demanding outcomes-based arrangements. Hospital systems exhibit highest price sensitivity for capital-intensive surgical infrastructure, whereas research institutions demonstrate lowest sensitivity due to grant funding and trial sponsorship.
Supply Chain Analysis
Viral vector production rests on specialized contract manufacturing organizations concentrated in the United States, Germany, and Switzerland, with plasmid DNA supply and cell culture media anchoring upstream dependencies. Recombinant adeno-associated virus manufacturing draws from HEK293 cell lines, baculovirus expression systems, and purification resins sourced from limited qualified suppliers. Single-source vulnerability pervades AAV serotype-specific capsid production, where proprietary engineered variants lock developers to exclusive manufacturing partnerships. Distribution runs through hospital pharmacy channels for gene therapies and retail pharmacy networks for chronic pharmaceutical management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Viral vector manufacturing capacity constraints prop pricing power for developers with captive production assets, creating a supply-constrained market structure favoring integrated platforms over outsourced pipelines.
For Market Incumbents: Cement manufacturing scale advantages through backward integration into plasmid DNA production and expansion of dedicated viral vector suites in the Philadelphia corridor. Lock in exclusive supply agreements with academic medical centers in Boston and Tübingen to preempt competitor access to subretinal surgical capacity. RNA-editing platforms pose substitution threat requiring pipeline diversification into antisense oligonucleotide modalities. For New Entrants and Emerging Players: Telemedicine-enabled genetic counseling and remote patient identification offer lower-friction entry into diagnostic and early-intervention segments underserved by incumbent field forces. Japan's PMDA sakigake designation pathway represents most penetrable regulatory geography for first-time filers seeking prioritized consultation. Partner with Foundation Fighting Blindness patient registry infrastructure to accelerate trial recruitment without building proprietary networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor RNA-editing specialists with mutation-agnostic platforms in Basel and Boston clusters, where platform breadth offsets single-asset risk. Long-term viability hinges on fifteen-to-twenty-year durability data generation capabilities and post-market registry infrastructure. Watch for FDA breakthrough therapy designation grants to early-intervention gene therapies as inflection signal for reimbursement negotiability.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive AAV production at Spark Therapeutics' Philadelphia facilities reduces supply risk for commercial volumes. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses review timelines from twelve to eight months for qualifying submissions. |
| Academic Partnership | Foundation Fighting Blindness clinical research network in Boston provides de-risked patient access for first-in-human studies. |
| Pipeline Diversification | RNA-editing platforms at ProQR Therapeutics expand addressable genetic variant coverage beyond replacement therapy limitations. |
| Reimbursement Strategy | Outcomes-based payment arrangements with CMS and commercial payers address upfront cost resistance for single-administration therapies. |
Study Parameters
Independent corroboration across vitreoretinal surgeons, gene therapy development executives, payer access specialists, and regulatory affairs leads underwrites the qualitative findings on subretinal delivery infrastructure and reimbursement negotiation dynamics. Secondary validation draws from FDA orphan drug designation filings, EMA ATMP framework guidance documents, ClinicalTrials.gov protocol registrations, and hospital procurement database analysis. Bottom-up patient population estimates by genetic subtype triangulate against top-down pharmaceutical revenue aggregation.
Comparable-period anchoring to historical gene therapy launch trajectories in ophthalmology establishes baseline assumptions for adoption curve modeling across the projection horizon. Segmentation dimensions include treatment modality, delivery route, end-user channel, and disease progression stage. CAGRs derive from logistic diffusion curves applied to genetic screening expansion rates and surgical capacity buildout timelines. Forecast inputs incorporate PMDA sakigake designation uptake velocity and EMA centralized authorization pathway completion rates.
The model holds under sustained orphan drug incentive structures and stable viral vector manufacturing economics; deviation in FDA regenerative medicine advanced therapy designation revocation or AAV immunogenicity exclusion rate expansion would shift trajectory. A small set of triggers—payer outcomes-based contract adoption velocity, dual-vector system clinical readouts, and academic medical center surgical training program scaling—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Induced Pluripotent Stem Cells Production Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Global Dendritic Cell Cancer Vaccines Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market