
 Europe Viral Vector Purification Market | 2026-2036
Europe Viral Vector Purification Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Viral Vector Purification Market Foresight
The EU Green Deal is hardening sustainability mandates across biopharmaceutical supply chains, pushing viral vector manufacturers toward lower-solvent purification platforms. Thermo Fisher Scientific leverages its pan-European distribution network to supply chromatography media for gene therapy production. Lonza Group Ltd anchors its competitive position through integrated CDMO services spanning vector production and downstream processing. Merck KGaA differentiates via membrane filtration technologies that reduce energy intensity in large-scale purification runs.
Europe viral vector purification encompasses the separation, concentration, and contaminant removal of viral particles used as delivery vehicles for genetic material, typically employing resin-based chromatography columns with pore sizes calibrated to 20–100 nanometers and tangential-flow filtration skids operating at transmembrane pressures of 5–30 psi. Chromatography media commands the largest product category share due to recurring consumable demand across multi-step purification trains, while affinity chromatography leads technology adoption for its selectivity in capturing AAV and lentiviral serotypes. Contract Manufacturing represents the fastest-expanding end user segment as pharmaceutical sponsors outsource downstream scale-up to specialized European CDMOs.
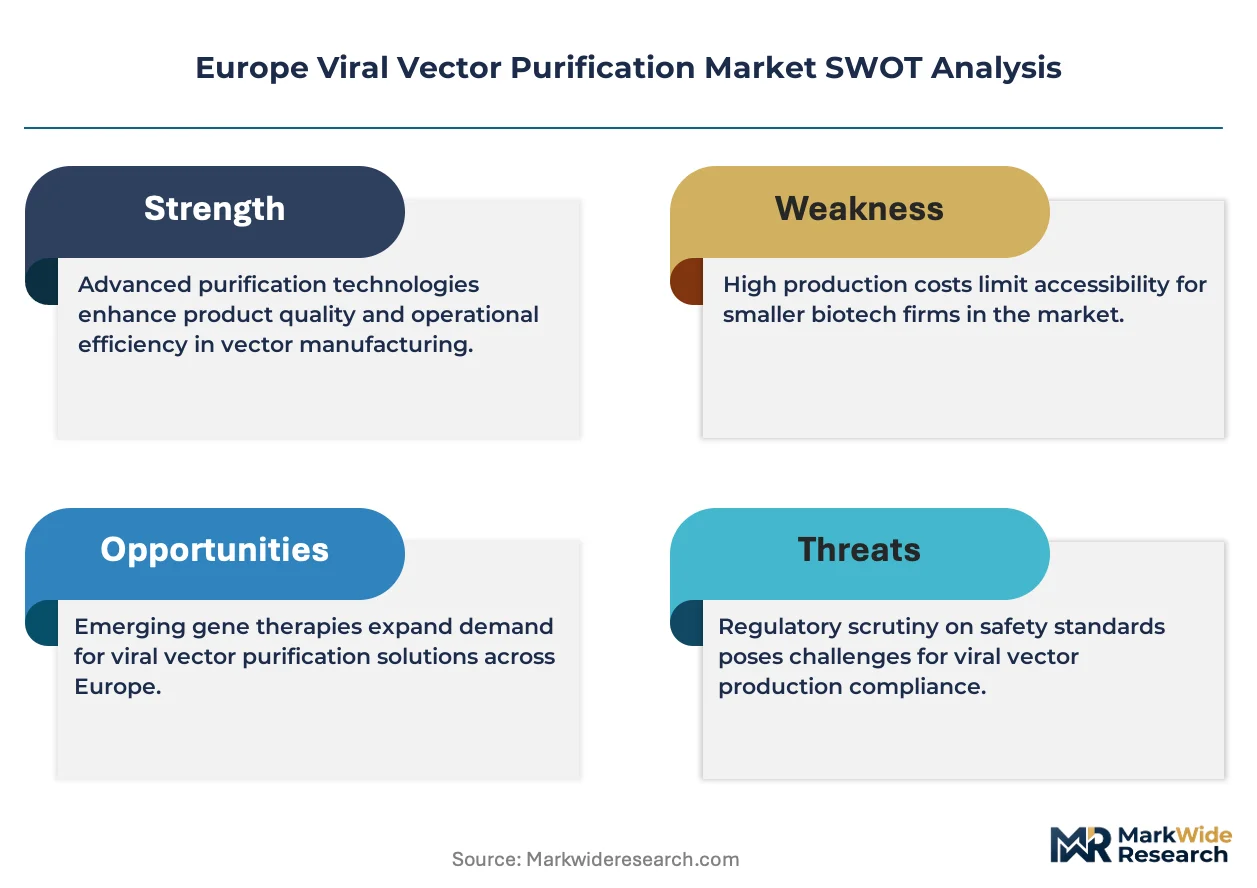
EMA's ATMP framework and the EU GMP Annex 1 revision for sterile manufacturing jointly elevate purity thresholds for clinical-grade viral vectors entering European trials. REACH compliance adds material qualification burdens for chromatography resins and single-use films, favoring suppliers with documented substance registrations. Stakeholders must weigh EMA's emerging guidance on replication-competent virus testing against the capital requirements for redundant purification trains.
Market Dynamics
EMA's evolving ATMP guidelines are compressing purification timelines while mandating higher purity thresholds, forcing gene therapy developers to reconfigure downstream processes around single-use chromatography architectures that eliminate cross-contamination risks between patient-specific batches.
Growth Catalysts
- REACH-compliant resin qualification:Chromatography suppliers with documented substance registrations capture preferential placement in European CDMO procurement frameworks.
- Gene therapy clinical pipeline expansion:Sponsors advancing AAV and lentiviral candidates into Phase II/III trials multiply purification train capacity requirements across Germany, France, and Switzerland.
- Single-use tangential-flow filtration:Disposable membrane cassettes reduce facility turnaround times between campaigns, accelerating batch release for time-critical ATMP manufacturing.
Market Restraints
- Protein A ligand supply concentration:Three suppliers control affinity resin production, exposing purification operations to input cost volatility and allocation constraints during demand surges.
- Replication-competent virus testing mandates:EMA's emerging guidance requires redundant analytical capabilities that extend facility validation timelines and capital deployment cycles.
- Energy-intensive cold-chain logistics:Frozen vector storage and transport between purification stages elevates operational expenditure and carbon footprint compliance burdens under EU Green Deal thresholds.
Strategic Opportunities
- Polish and Spanish CDMO greenfield development:Lower facility construction costs and available specialized labor pools attract purification capacity expansion outside established German and Swiss clusters.
- Continuous chromatography integration:Simulated moving bed systems promise productivity gains over batch processing, with early adopters in Swiss biologics manufacturing testing multi-column periodic counter-current configurations.
- EU GMP Annex 1 revision:Sterile manufacturing upgrades for viral vector fill-finish create bundled demand for integrated downstream purification and aseptic processing services.
Industry Challenges
- Downstream process development talent scarcity:European biopharmaceutical manufacturers compete for chromatography modeling specialists and viral clearance study designers with limited graduate program throughput.
- Legacy stainless-steel facility retrofit complexity:Existing multi-product biologics plants face structural barriers converting to single-use purification trains due to fixed piping infrastructure and space constraints.
- Vector-specific resin customization cycles:Novel AAV serotypes and engineered capsids require bespoke affinity ligand development, extending qualification timelines beyond standard platform process deployment schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Viral Vector Purification Market |
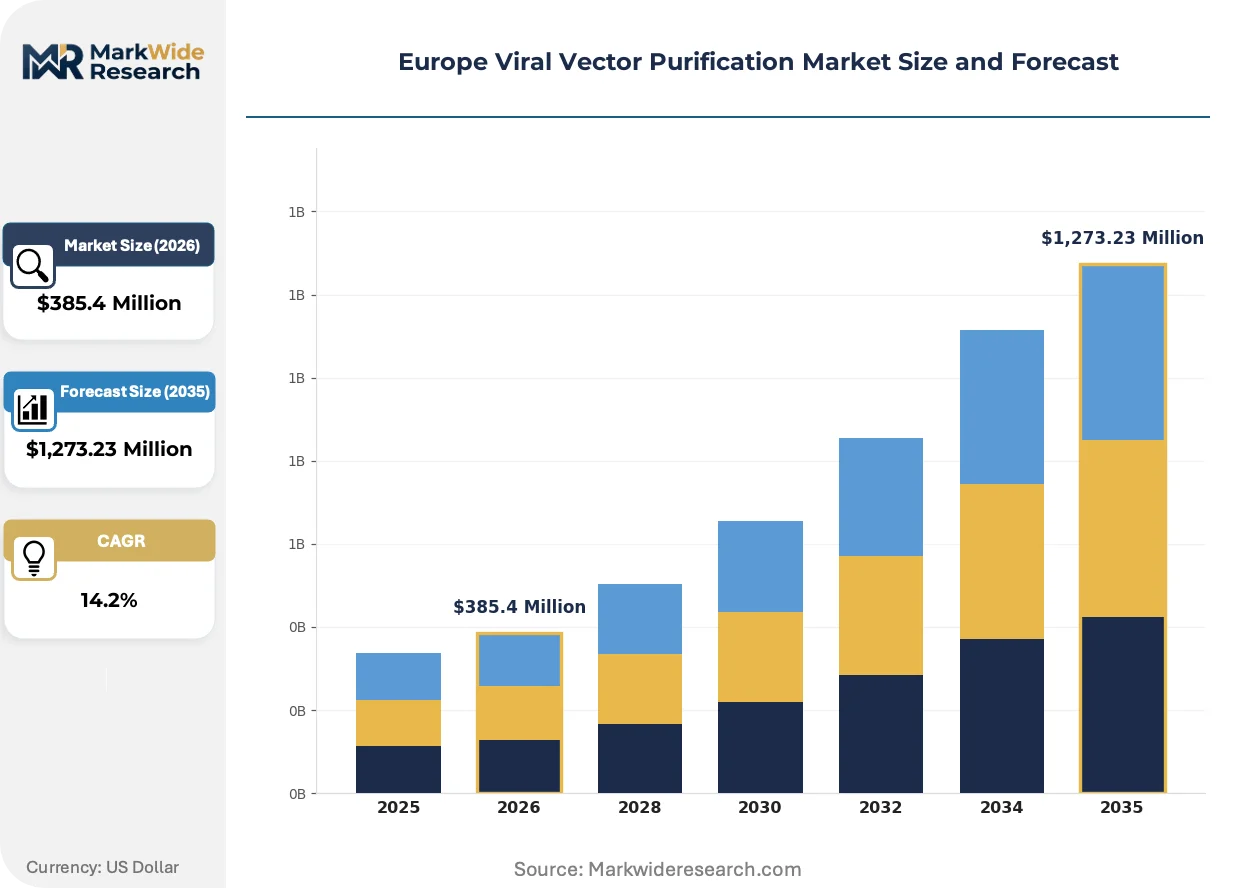
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,273.23 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chromatography Media, Filtration Systems, Precipitation Agents, Buffers Technology: Affinity Chromatography, Ultrafiltration, Ion Exchange, Size Exclusion End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Contract Manufacturing Application: Gene Therapy, Vaccine Development, Genetic Engineering, Cell Therapy |
| Companies Covered | Thermo Fisher Scientific, Lonza Group Ltd, Merck KGaA, SIRION BIOTECH GmbH, Bio-Rad Laboratories, Sartorius, Cytiva, Oxford Biomedica plc, Batavia Biosciences B.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Viral Vector Purification Market Shifts & Advancements
Modular purification architectures are displacing fixed stainless-steel installations across European gene therapy manufacturing, enabling rapid reconfiguration between viral vector serotypes and accelerating facility commissioning timelines for emerging CDMO entrants.
Pre-packed chromatography columns is modularizing downstream process development by eliminating resin packing validation burdens and enabling plug-and-play substitution between capture, intermediate, and polishing steps. Mid-scale gene therapy manufacturers in the United Kingdom and Netherlands are adopting these disposable formats to compress campaign changeover intervals. The technology is compressing capital requirements for multi-product facilities while reducing technical risk in technology transfer between development and commercial sites.
EU GMP Annex 1's 2022 revision mandates enhanced contamination control strategies for sterile ATMP manufacturing, requiring viral vector purifiers to implement closed-system processing and single-use barrier technologies. The regulation elevates documentation burdens for chromatography skid design and filter housing configurations. German and French manufacturers are responding by qualifying entirely disposable purification trains that eliminate open manipulations between unit operations.
CDMO outsourcing concentration is restructuring procurement patterns as pharmaceutical sponsors consolidate downstream scale-up relationships with specialized European service providers. Traditional equipment vendors face margin pressure from integrated service contracts bundling resin supply, skid rental, and process development support. This behavioral shift is most pronounced among mid-cap gene therapy developers headquartered in Switzerland and the United Kingdom lacking captive manufacturing infrastructure.
Europe Viral Vector Purification Market Segmentation
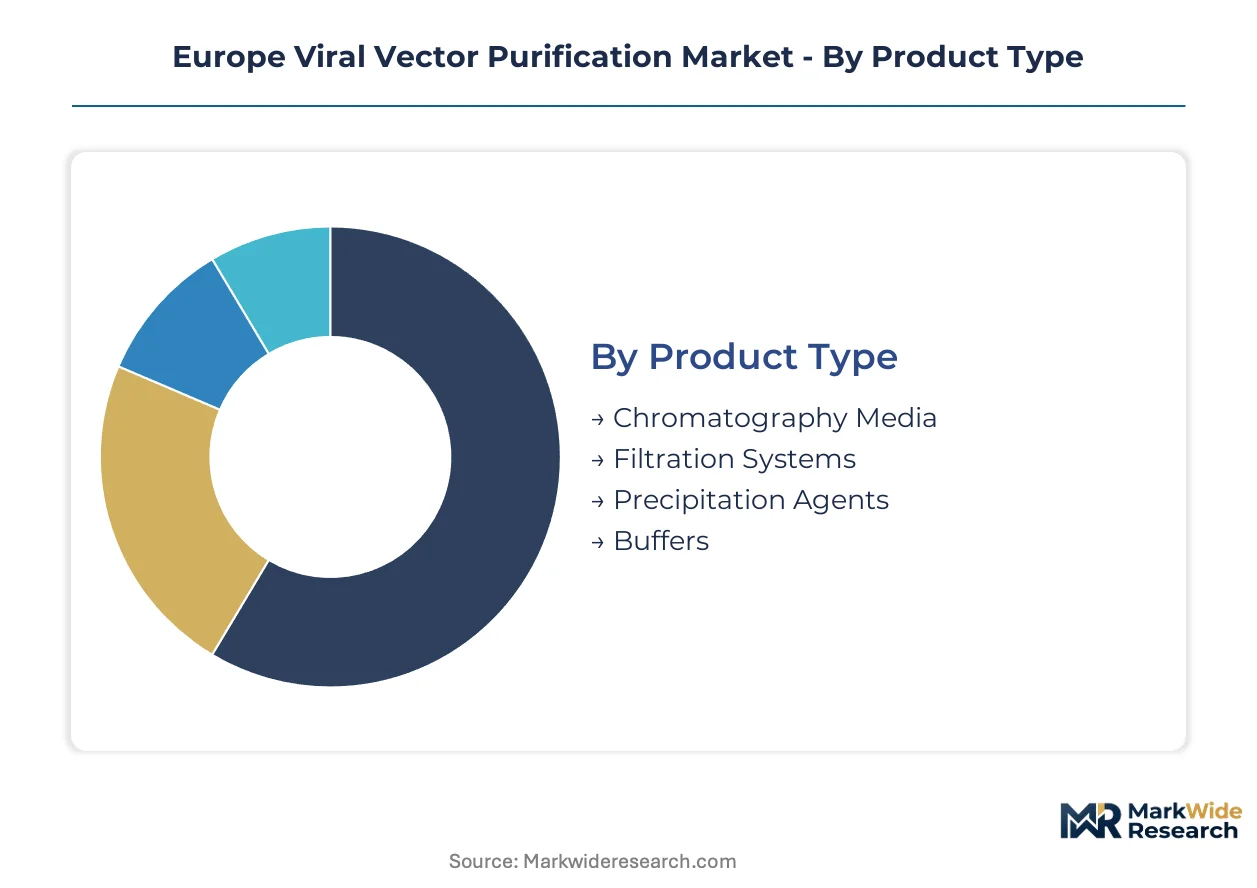
Segmentation in viral vector purification reveals how procurement priorities diverge across buyer types and manufacturing scales. European sponsors select purification platforms based on regulatory compliance burdens, batch flexibility requirements, and vector serotype specificity rather than unit cost alone.
Product Type:
Capital deployment intensity and consumable replenishment cycles drive buyer selection across product categories.
- Chromatography Media:Resin-based separation matrices with pore architectures calibrated to 20–100 nanometers enable selective capture of AAV and lentiviral particles. German and Swiss CDMOs concentrate demand here due to recurring multi-step purification train requirements and EMA's escalating purity thresholds for clinical-grade vectors.
- Filtration Systems:Tangential-flow skids operating at 5–30 psi transmembrane pressure concentrate and buffer-exchange viral preparations. Academic institutions in the United Kingdom and Netherlands favor single-use membrane cassettes that eliminate cleaning validation between serotype campaigns.
- Precipitation Agents:Polyethylene glycol and salt-based flocculation reagents offer low-cost viral enrichment prior to chromatographic polishing.
- Buffers:Formulated salt and pH solutions maintain vector stability across purification stages and final formulation.
Volume sits with chromatography media; growth tilts toward filtration systems.
Technology:
Technical selectivity requirements and process development timelines determine technology adoption patterns.
- Affinity Chromatography:Ligand-functionalized resins exploit serotype-specific capsid interactions to achieve single-step viral capture with purity exceeding 90%. Gene therapy developers in France and Germany prioritize this technology for AAV manufacturing where capsid heterogeneity demands precise discrimination.
- Ion Exchange:Charge-based separation exploits surface plasmid and protein contaminant differences from viral particles. Mid-scale manufacturers deploy this as a lower-cost polishing alternative when affinity resin allocation tightens.
- Ultrafiltration:Molecular weight cutoff membranes concentrate viral titers while removing small-molecule process residuals.
- Size Exclusion:Porous bead matrices separate by hydrodynamic radius, typically deployed for final aggregate removal rather than primary capture.
Affinity chromatography commands the dominant installed base; ion exchange is expanding most quickly among cost-constrained developers.
End User:
Internal manufacturing capability versus outsourcing preference shapes procurement channel selection.
- Contract Manufacturing:European CDMOs bundle resin supply, skid rental, and process development into integrated service contracts. Pharmaceutical sponsors lacking captive infrastructure in Switzerland and the United Kingdom consolidate relationships with specialized downstream providers to compress scale-up timelines.
- Pharmaceutical Companies:Large-cap sponsors with approved ATMP portfolios operate dedicated purification suites requiring qualified multi-supplier resin strategies.
- Academic Institutions:University-based gene therapy research programs prioritize pre-packed disposable formats to minimize technical staff requirements.
- Research Organizations:Non-profit translational centers bridge discovery and clinical manufacturing with pilot-scale purification capabilities.
Contract manufacturing absorbs the steepest capacity expansion; pharmaceutical companies retain the largest single-site volume commitments.
Application:
Clinical development stage and regulatory pathway urgency dictate purification stringency levels.
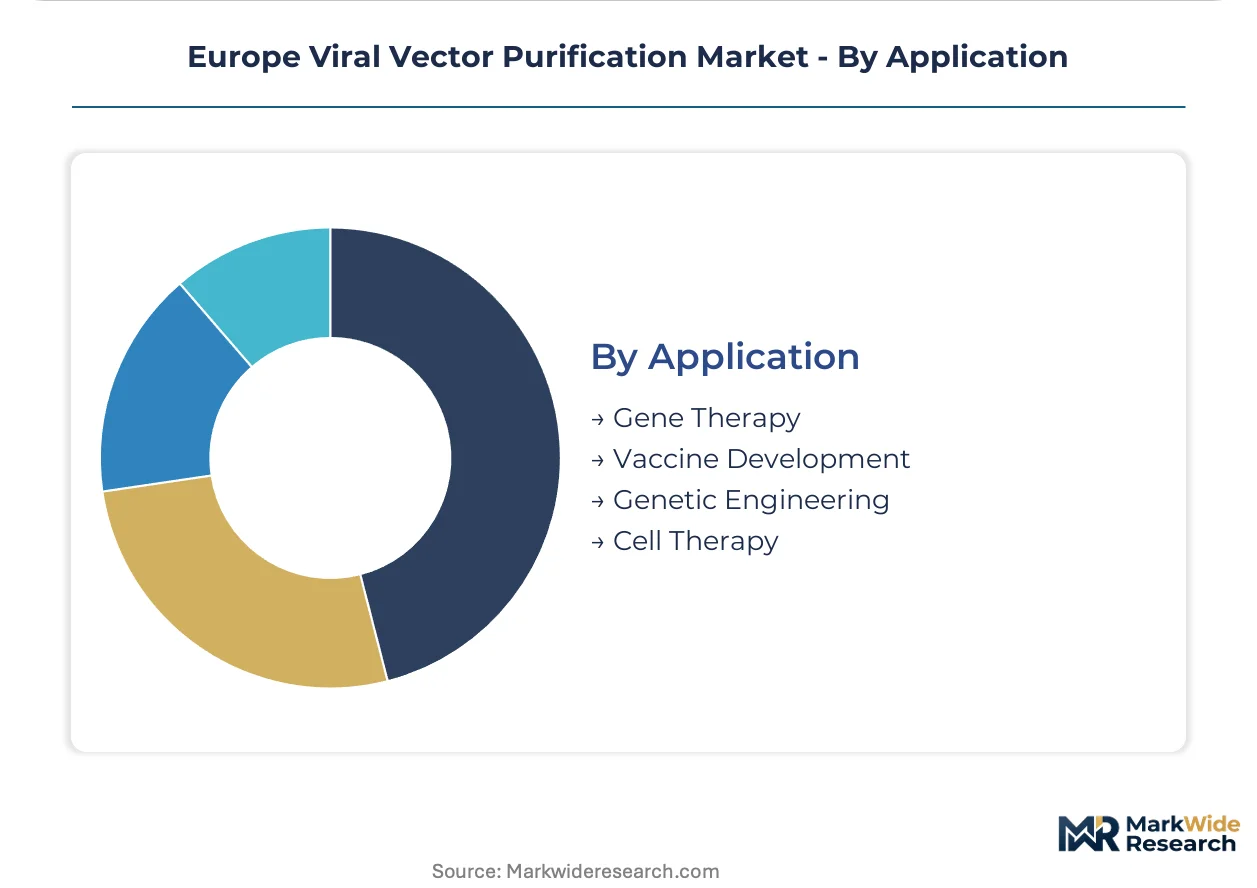
- Gene Therapy:AAV and lentiviral vector manufacturing for inherited disease indications requires redundant clearance validation and replication-competent virus testing mandated by EMA's ATMP framework. German manufacturers lead European capacity deployment for Phase III candidates.
- Vaccine Development:Viral vector-based prophylactic programs, including pandemic preparedness initiatives, demand rapid campaign turnaround that favors single-use purification architectures.
- Cell Therapy:CAR-T and stem cell modification applications utilize lentiviral transduction requiring distinct clearance profiles from gene therapy applications.
- Genetic Engineering:Research-grade viral tools for laboratory applications tolerate lower purity specifications than clinical manufacturing.
Gene therapy anchors current revenue concentration; vaccine development is gaining share fastest amid vector platform diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Basel-Zurich corridor anchors European viral vector purification capacity, with Swiss biologics manufacturing clusters hosting the continent's densest concentration of ATMP-compliant downstream processing infrastructure.
Germany
German gene therapy developers expand purification capacity to meet EMA's evolving ATMP guidelines for Phase III candidates. REACH compliance requirements favor chromatography suppliers with documented substance registrations in procurement frameworks. Bavaria's Munich-Leipzig biotech corridor hosts redundant purification train deployments for replication-competent virus testing mandates.
Switzerland
Swiss CDMOs bundle resin supply and skid rental into integrated service contracts for mid-cap gene therapy sponsors. Swissmedic's ATMP oversight aligns with EMA frameworks while permitting accelerated clinical trial initiations. Basel's pharmaceutical manufacturing cluster concentrates continuous chromatography adoption with multi-column periodic counter-current configurations.
United Kingdom
UK academic institutions prioritize pre-packed disposable chromatography formats to minimize technical staff requirements in university-based gene therapy programs. The Medicines and Healthcare products Regulatory Agency's post-Brexit ATMP pathway maintains EMA-aligned purity thresholds. London-Oxford-Cambridge golden triangle hosts pilot-scale purification capabilities bridging discovery and clinical manufacturing.
France
French manufacturers qualify entirely disposable purification trains eliminating open manipulations between unit operations under EU GMP Annex 1 revisions. ANSM's national implementation of EMA guidance elevates documentation burdens for chromatography skid design. Paris-Saclay biocluster anchors affinity chromatography deployment for AAV serotype-specific capsid discrimination.
Netherlands
Dutch mid-scale manufacturers adopt single-use membrane cassettes reducing facility turnaround times between serotype campaigns. ECHA's REACH enforcement adds material qualification burdens for single-use films in downstream processing. Leiden-Rotterdam biotech corridor concentrates viral clearance study design expertise for contract manufacturing scale-up.
Europe Viral Vector Purification Market Competitive Landscape
The competitive structure tilts toward integrated CDMO service providers with captive resin supply relationships and pan-European distribution networks. Three strategic archetypes dominate: diversified life science conglomerates with chromatography media portfolios, specialized viral vector CDMOs with downstream process development capabilities, and filtration technology specialists with membrane-based purification platforms. Competitive moves concentrate on strategic partnerships bundling equipment supply with process development support, and geographic expansion into Polish and Spanish greenfield development zones.
Within the diversified conglomerate tier, Thermo Fisher Scientific leverages its pan-European distribution network to supply chromatography media, while Merck KGaA differentiates via membrane filtration technologies reducing energy intensity in large-scale purification runs. Lonza Group Ltd anchors the integrated CDMO archetype through services spanning vector production and downstream processing. These three entities exemplify the market's trajectory toward bundled procurement relationships consolidating resin supply, skid rental, and regulatory compliance support.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Lonza Group Ltd |
| Merck KGaA |
| SIRION BIOTECH GmbH |
| Bio-Rad Laboratories |
| Sartorius |
| Cytiva |
| Oxford Biomedica plc |
| Batavia Biosciences B.V. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up CDMO specialists concentrate procurement leverage across European viral vector purification, compressing resin supply margins while enforcing long-term offtake discipline that stabilizes input costs for multi-product gene therapy facilities.
Pricing Analysis
Outcome-based pricing anchored to batch yield and purity thresholds dominates CDMO contracts, with affinity resin tiers separating GMP-certified clinical-grade supply from research-use formulations. Price differentiation rests on REACH documentation depth and single-use validation bundles. Cost compression in research-grade chromatography media intensifies as academic buyers consolidate purchasing through university procurement consortia. Mid-cap gene therapy developers exhibit highest price sensitivity, while Phase III sponsors prioritize yield guarantees over unit resin costs.
Supply Chain Analysis
Direct-to-CDMO channels handle commercial-scale resin demand, with distributor networks serving academic and pilot-scale buyers. Supply concentrates in Germany, Switzerland, and the United States for Protein A ligand and chromatography base matrices. Manufacturing draws from agarose bead feedstocks, synthetic polymer backbones, and serotype-specific affinity ligands. Single-source vulnerability in affinity resin production exposes purification operations to allocation constraints during clinical pipeline surges. Distribution runs through pan-European logistics hubs with temperature-controlled storage for pre-packed column inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European viral vector purification is consolidating into a vertical-integration race, with CDMOs capturing upstream resin supply relationships and downstream fill-finish capabilities to control margin leakage across the ATMP value chain.
For Market Incumbents: Deploy continuous chromatography engineering to differentiate against batch-process competitors and capture productivity premiums from Swiss and German gene therapy sponsors. Lock in exclusive resin supply partnerships with ECHA-registered suppliers before REACH compliance deadlines tighten procurement pools. Consolidate relationships with mid-cap developers lacking captive manufacturing infrastructure to defend against emerging Polish and Spanish CDMO entrants. For New Entrants and Emerging Players: Digital-channel route partnerships with university technology transfer offices open pilot-scale purification service entry points before clinical-scale qualification burdens escalate. Target Netherlands and United Kingdom academic institutions with pre-packed disposable column offerings that eliminate resin packing expertise requirements. Pursue modular skid rental models that compress capital barriers for biotech sponsors transitioning from discovery to IND-enabling studies. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized viral clearance study design boutiques in the Leiden-Rotterdam corridor, where talent scarcity and CDMO outsourcing concentration create durable margin structures. Evaluate target viability through lens of EMA ATMP inspection history and replication-competent virus testing capability depth. Monitor EMA guidance publication velocity as inflection signal for capital deployment timing in redundant purification train infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Chromatography Adoption | Swiss biologics manufacturers test multi-column periodic counter-current configurations for productivity gains. |
| REACH-Compliant Resin Qualification | Documented substance registrations secure preferential placement in European CDMO procurement frameworks. |
| Single-Use Purification Train Deployment | French manufacturers qualify entirely disposable systems eliminating open manipulations under EU GMP Annex 1. |
| Polish and Spanish Greenfield Development | Lower facility construction costs attract purification capacity expansion outside established German clusters. |
| Integrated CDMO Service Bundling | Resin supply, skid rental, and process development consolidation captures mid-cap sponsor relationships. |
Research Methodology
Multi-period observation of EMA ATMP submission volumes, CDMO capacity expansion announcements, and chromatography media procurement patterns anchored the trend analysis, supplemented by interviews with gene therapy development executives, downstream process engineers, regulatory affairs specialists, and university technology transfer officers. Secondary validation drew from EMA inspection databases, ClinicalTrials.gov vector trial registrations, REACH substance registration records, and EU GMP Annex 1 guidance documents. Bottom-up segmentation modeling triangulated against top-down market sizing from pan-European biologics manufacturing cluster analysis.
Input-output matrices mapped resin consumption intensity across purification train configurations, vector serotype categories, and manufacturing scale tiers. Segmentation dimensions spanned product type, technology modality, end-user archetype, application indication, and regional regulatory cluster. CAGRs were derived from regression analysis of historical capacity deployment against clinical pipeline progression rates, with vector-specific resin customization cycles and facility validation timelines incorporated as industry-specific forecast inputs across the projection horizon.
The model holds under stable EMA ATMP regulatory interpretation and continued gene therapy clinical pipeline advancement; deviation in replication-competent virus testing mandate timing or REACH substance restriction scope would shift capacity deployment trajectories. Forecasts reflect documented assumptions regarding sponsor outsourcing propensity and CDMO consolidation velocity. Periodic stress-testing of base assumptions against regulatory guidance publication schedules and clinical trial suspension rates is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Middle East and Africa Viral Vector Purification Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
Cord Blood Banking Market