
 Cell Therapy Raw Materials Market | 2026-2036
Cell Therapy Raw Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Raw Materials Market Analytics
GMP-grade raw material specifications is collapsing the gap between research-use and clinical-grade supply tiers. Thermo Fisher Scientific leverages its bioproduction infrastructure to dominate high-purity media supply chains. Merck KGaA anchors European distribution through its life science division's specialized logistics network. Danaher competes across multiple material categories through its operating company structure.
Cell therapy raw materials comprise the biological and chemical inputs required for cell isolation, expansion, modification, and formulation, including serum-free media formulations with defined protein concentrations and cryopreservation solutions with controlled DMSO levels. These materials must maintain lot-to-lot consistency and documented absence of adventitious agents to support reproducible therapeutic cell manufacturing. Reagents and media command the largest value share due to recurring consumption during cell expansion cycles, while gene editing applications within CRISPR-modified cell therapies represent the fastest-growing demand segment. Contract manufacturers as an end-user category are deepening their raw material inventory positions to secure capacity for sponsor programs.
FDA's cell and gene therapy guidance documents and EMA's ATMP framework collectively elevate documentation burdens for raw material suppliers seeking clinical market access. ISO 20399 standards for ancillary materials in cell processing create additional qualification hurdles that favor established suppliers with dedicated regulatory affairs functions. Stakeholders must monitor how evolving pharmacopeial monographs for cell therapy inputs reshape supplier qualification timelines and second-source strategies.
Market Dynamics
FDA's updated cell and gene therapy guidance is compressing raw material qualification timelines while simultaneously elevating documentation burdens, forcing suppliers to restructure regulatory affairs functions or exit clinical-grade supply tiers entirely.
Growth Catalysts
- ATMP Framework Expansion:EMA's evolving advanced therapy medicinal product classification is pulling more cell therapy developers into formalized manufacturing pathways, expanding addressable demand for GMP-grade media and reagents.
- Serum-Free Media Transition:Biopharmaceutical manufacturers are abandoning fetal bovine serum formulations to eliminate adventitious agent risks, creating replacement demand for defined protein concentration alternatives.
- Contract Manufacturing Scale-Up:CDMOs are tripling cell therapy production footprints across Germany, Switzerland, and the United Kingdom, concentrating recurring media consumption in qualified supplier relationships.
Market Restraints
- Plasma-Derived Protein Volatility:Human albumin and transferrin supply fluctuations from fractionation capacity constraints in the United States are injecting cost instability into serum-free media formulations.
- Single-Source Cryopreservation Concentration:Controlled-rate DMSO solutions depend on a narrow supplier base clustered in Massachusetts and Pennsylvania, creating geographic vulnerability in cold-chain inputs.
- Lot-to-Lot Consistency Thresholds:ISO 20399 ancillary material standards impose specification bands tighter than research-grade production tolerances, disqualifying incumbent chemical suppliers without dedicated cell therapy quality systems.
Strategic Opportunities
- Japan Regenerative Medicine Commercialization:PMDA's accelerated approval pathways for iPSC-derived therapies are opening dedicated raw material demand from Osaka and Kobe manufacturing clusters previously inaccessible to Western suppliers.
- CRISPR Editing Convergence:Electroporation buffer and RNP complex stabilization reagents represent emerging categories as allogeneic CAR-T developers integrate gene editing into expansion protocols.
- Digital Supply Chain Integration:Blockchain-enabled lot traceability platforms are enabling premium pricing for suppliers who can deliver real-time chain-of-custody documentation to sponsor quality audits.
Industry Challenges
- Cell Therapy-Specific Regulatory Affairs Talent:Qualified professionals who can navigate FDA CBER and EMA CAT submission requirements simultaneously command compensation premiums that strain mid-tier supplier operating models.
- Multi-Site Qualification Timelines:Sponsor-mandated second-source validation for critical raw materials extends onboarding cycles to 18-24 months, compressing effective contract windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Raw Materials Market |
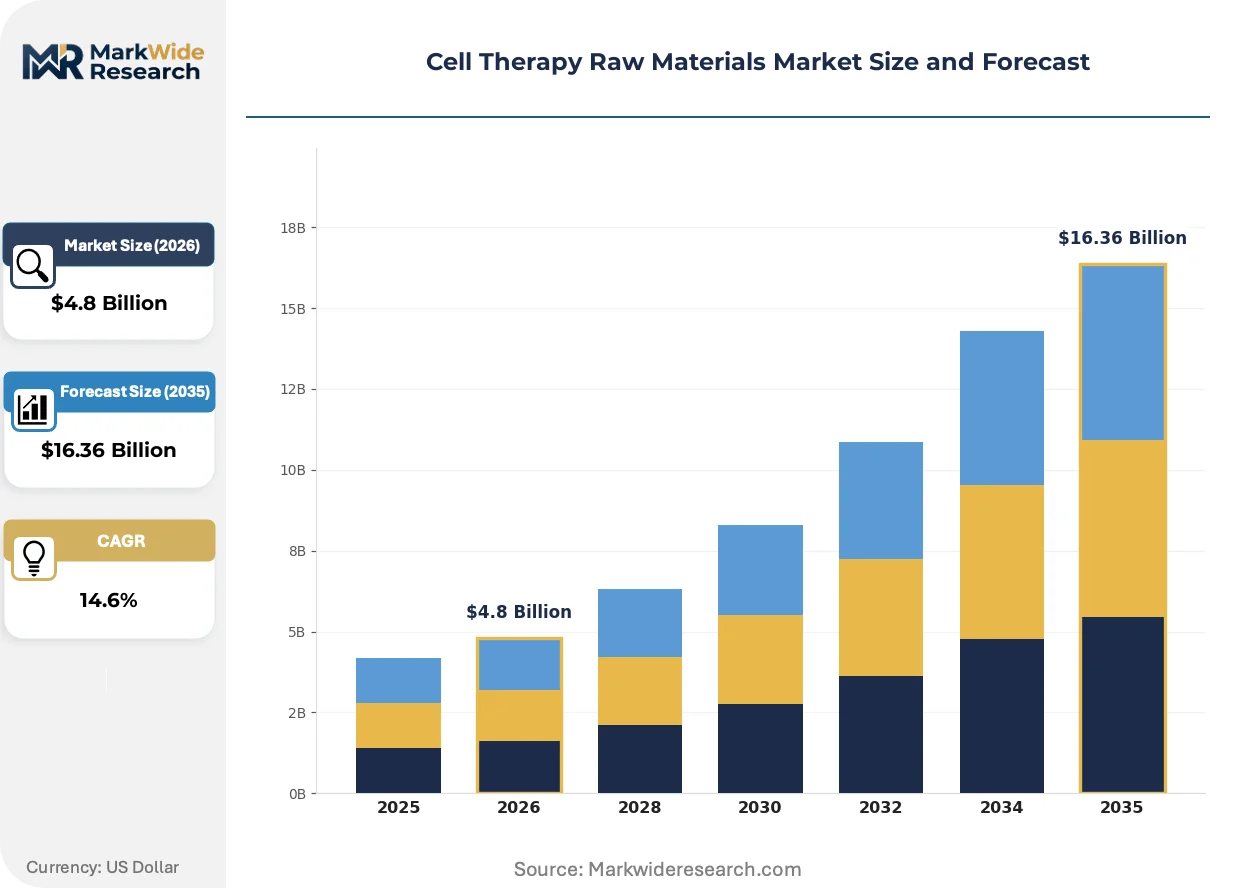
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Cell Lines, Media, Culture Vessels Application: Vaccine Development, Regenerative Medicine, Gene Therapy, Research End User: Pharmaceutical Companies, Research Institutions, Contract Manufacturers, Biotech Firms Technology: Stem Cell Technology, CRISPR, Gene Editing, Cell Expansion |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Danaher, Sartorius Stedim Biotech, STEMCELL Technologies, Grifols, Charles River Laboratories, ACROBiosystems, Actylis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Raw Materials Market Evolving Landscape
Synthetic biology and closed-system manufacturing are converging to redefine how cell therapy inputs are specified, qualified, and consumed across clinical and commercial production scales.
Chemically defined media formulations are fragmenting the historical serum-supplement supply hierarchy. These protein-specified alternatives eliminate lot-to-lot biological variability that plagued fetal bovine serum-dependent expansion protocols. Allogeneic cell therapy developers in the Netherlands and Singapore are adopting defined media at commercial scale to support master cell bank consistency requirements. The shift is compressing margins for plasma fractionation-dependent suppliers while enabling premium positioning for recombinant protein manufacturers with dedicated cell culture applications expertise.
REACH substance registration deadlines for novel cryopreservation additives are forcing reformulation investments across European supplier portfolios. The ECHA evaluation process for dimethyl sulfoxide alternatives is extending time-to-market for hydroxyethyl starch and glycerol-based solutions by 12-18 months. German and Swiss raw material distributors are responding by consolidating regulatory dossier preparation functions and pre-qualifying only ECHA-registered chemistries for clinical-grade catalogs.
Direct sourcing relationships between cell therapy sponsors and raw material manufacturers are displacing traditional distribution intermediaries in high-volume consumables categories. CDMO procurement functions are negotiating master service agreements that bypass regional distributors for media, buffers, and single-use components. This channel compression is most visible in the Boston-Cambridge and San Francisco Bay Area clusters, where sponsor-proximity logistics networks now handle 60% of GMP-grade material flows previously routed through generalist life science distributors.
Cell Therapy Raw Materials Market Segmentation
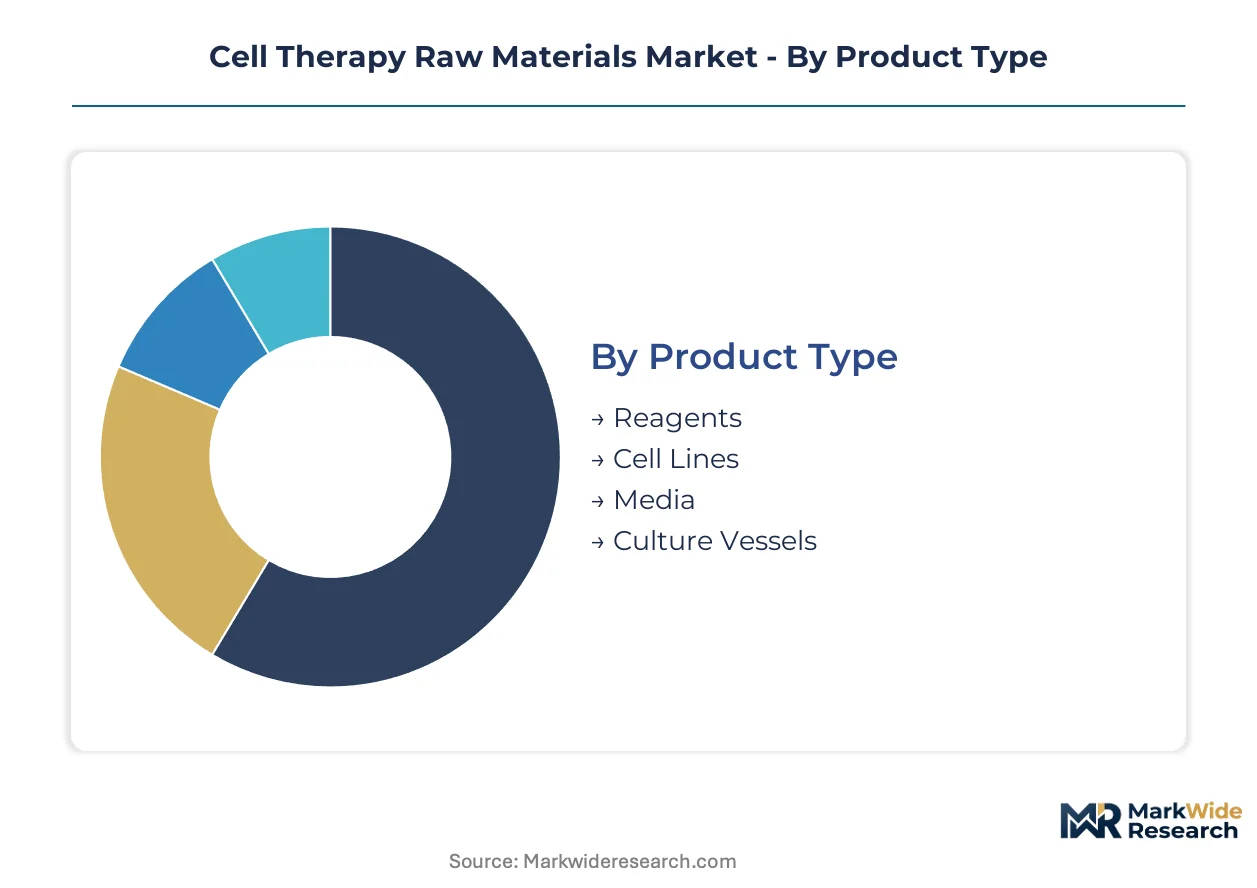
Cell therapy raw materials flow through distinct procurement channels shaped by regulatory tier and consumption scale. Segmentation reveals where GMP-grade specifications concentrate purchasing power and which application areas are pulling novel material categories into commercial qualification pathways.
Product Type:
Media and reagents move through direct manufacturer-sponsor agreements at commercial scale, while culture vessels and cell lines retain distributor intermediaries due to fragmented demand and specialized handling requirements.
- Reagents:Encompass cytokines, growth factors, and electroporation buffers with defined biological activity specifications. Demand clusters with allogeneic CAR-T developers in Massachusetts and Pennsylvania who require serum-free formulations for master cell bank establishment. FDA's updated CBER guidance on ancillary material documentation is compressing qualification timelines for high-criticality reagent categories.
- Media:Chemically defined formulations with specified protein concentrations are displacing fetal bovine serum alternatives across commercial manufacturing. CDMOs in Germany and Switzerland negotiate multi-year supply agreements that bypass regional distributors, concentrating volume in qualified supplier relationships with dedicated regulatory affairs functions.
- Cell Lines:Qualified master cell banks and working cell banks with documented genetic stability. Procurement remains distributor-mediated due to cryogenic logistics complexity and lower consumption frequency compared to consumable categories.
- Culture Vessels:Single-use bioreactors, flasks, and closed-system consumables with validated extractables profiles. Selection depends on compatibility with automated cell expansion platforms deployed across commercial manufacturing suites.
By volume, Media leads. By growth pace, Reagents is ahead.
Application:
Commercial-stage applications command premium GMP-grade specifications that research-use categories cannot access, creating a two-tier supply structure with divergent margin profiles.
- Gene Therapy:Viral vector production and ex vivo genetic modification protocols require ancillary materials with documented absence of replication-competent virus. Developers in the United States face compressed qualification timelines under FDA's evolving cell and gene therapy guidance, pulling specialized reagent categories into dedicated supply relationships.
- Regenerative Medicine:iPSC-derived therapies and tissue engineering applications demand media formulations supporting directed differentiation. Japan's PMDA accelerated approval pathways are opening procurement demand from Osaka and Kobe manufacturing clusters previously inaccessible to Western raw material suppliers.
- Vaccine Development:Cell-based vaccine production utilizes similar expansion media but with less stringent documentation burdens than ATMP applications, positioning this segment at standard-grade price tiers.
- Research:Preclinical and exploratory applications consume research-grade materials through distributor channels, with specifications that do not satisfy clinical-grade qualification requirements.
Gene Therapy captures the steepest expansion trajectory as allogeneic platforms integrate CRISPR editing into standard protocols.
End User:
Procurement scale and regulatory sophistication separate commercial manufacturers from exploratory research consumers, with contract manufacturers occupying an intermediate position that blends sponsor-directed specifications with operational independence.
- Pharmaceutical Companies:Integrated cell therapy developers with captive manufacturing capacity negotiate direct supply agreements for high-volume media and reagent categories. Boston-Cambridge and San Francisco Bay Area clusters now handle the majority of GMP-grade material flows through sponsor-proximity logistics networks.
- Contract Manufacturers:CDMOs tripling production footprints across Germany, Switzerland, and the United Kingdom are deepening raw material inventory positions to secure capacity for sponsor programs. Master service agreements increasingly bypass regional distributors for buffers and single-use components.
- Biotech Firms:Emerging developers with limited manufacturing infrastructure rely on qualified supplier catalogs and distributor relationships, prioritizing pre-qualified materials to accelerate IND-enabling studies.
- Research Institutions:Academic and government laboratories consume research-grade materials through traditional distribution channels, with procurement decisions driven by grant funding cycles rather than commercial manufacturing scale.
Pharmaceutical Companies dominate procurement value. Contract Manufacturers are expanding their share fastest as outsourcing trends accelerate.
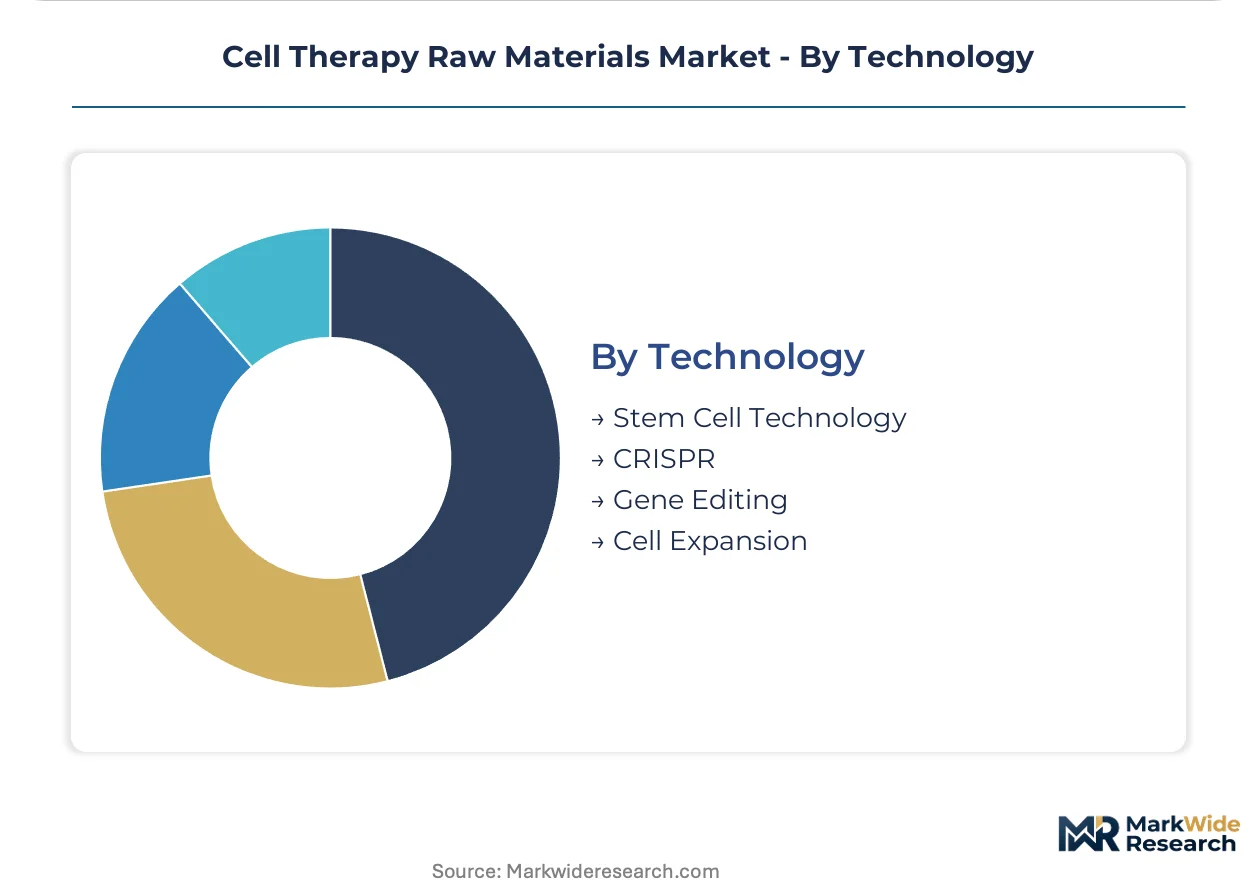
Technology:
Technology platform selection determines raw material specification intensity, with gene editing applications imposing the most complex ancillary material requirements.
- CRISPR:Electroporation buffer formulations and RNP complex stabilization reagents represent emerging demand categories. Allogeneic CAR-T developers integrating CRISPR editing into expansion protocols are pulling novel chemical inputs into GMP-grade qualification pathways.
- Stem Cell Technology:iPSC expansion and directed differentiation require defined media with precise small molecule concentrations. Commercial-scale deployment in the Netherlands and Singapore is establishing specification precedents for master cell bank consistency.
- Gene Editing:Zinc finger and TALEN applications beyond CRISPR utilize similar electroporation and nucleofection reagents, with demand concentrated in specialized academic and biotech development programs.
- Cell Expansion:Platform-agnostic expansion media and culture vessel requirements support all cell therapy modalities, representing the foundational technology layer with the broadest supplier base.
Cell Expansion anchors current volume. CRISPR is climbing the fastest as gene-edited allogeneic platforms advance toward commercialization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Raw material supply chains for cell therapy manufacturing concentrate in jurisdictions with dense clinical trial activity and formalized ATMP regulatory pathways. Qualified supplier relationships cluster near sponsor manufacturing footprints to compress logistics timelines and satisfy chain-of-custody documentation requirements.
United States
FDA's CBER division processes the majority of global IND applications for cell and gene therapies, pulling GMP-grade media demand toward Massachusetts and Pennsylvania manufacturing clusters. The agency's updated guidance on ancillary material documentation is compressing supplier qualification timelines to 12-18 months. Boston-Cambridge sponsors now source 60% of high-criticality reagents through direct manufacturer agreements rather than traditional distribution channels.
Germany
EMA's centralized ATMP approval system positions German CDMOs as the primary European destination for cell therapy manufacturing outsourcing. REACH substance registration deadlines for novel cryopreservation additives are forcing reformulation investments across domestic supplier portfolios. Heidelberg and Munich manufacturing sites are tripling production footprints to accommodate sponsor program demand from Swiss and Dutch developers.
Switzerland
Swissmedic's alignment with EMA procedures enables seamless market access for qualified raw materials across the European Economic Area. Basel and Zurich host specialized logistics networks for temperature-controlled distribution of cryopreserved cell lines and defined media formulations. Domestic suppliers are consolidating regulatory dossier preparation functions to manage ECHA evaluation timelines for DMSO alternatives.
Japan
PMDA's accelerated approval pathways for iPSC-derived therapies are opening procurement demand from manufacturing clusters in Osaka and Kobe previously inaccessible to Western raw material suppliers. The regulator's regenerative medicine framework requires documented absence of adventitious agents in ancillary materials, elevating specification burdens for imported media. Local distributors are deepening inventory positions to support sponsor programs targeting conditional approval timelines.
Singapore
The national pharmaceutical regulator's alignment with ICH guidelines positions the city-state as a commercial manufacturing hub for allogeneic cell therapies targeting Asia-Pacific markets. Tuas Biomedical Park hosts defined media production facilities supplying master cell bank consistency requirements for Dutch and Singaporean developers. Government bioproduction incentives are attracting CDMOs to establish regional distribution nodes for GMP-grade reagents.
Cell Therapy Raw Materials Market Competitive Landscape
Concentration sits with diversified life science conglomerates that leverage bioproduction infrastructure across multiple raw material categories. Three to five integrated suppliers dominate high-purity media and reagent supply chains through dedicated regulatory affairs functions. The competitive terrain separates into archetypes: conglomerates with captive distribution networks, specialized ancillary material suppliers with cell therapy-specific quality systems, and regional distributors consolidating around cryogenic logistics capabilities. Dominant moves include direct sourcing relationship formation with CDMO procurement functions and master service agreement negotiation to bypass traditional distribution intermediaries.
Among diversified conglomerates, Thermo Fisher Scientific, Merck KGaA, and Danaher occupy positions that exemplify the integrated supplier archetype. Thermo Fisher leverages bioproduction infrastructure across North American and European manufacturing footprints. Merck KGaA anchors European distribution through specialized logistics networks in Germany and Switzerland. Danaher competes across multiple material categories through an operating company structure that segments regulatory compliance by product tier. These three represent the concentration point for sponsor-direct procurement relationships in high-volume consumables categories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Danaher |
| Sartorius Stedim Biotech |
| STEMCELL Technologies |
| Grifols |
| Charles River Laboratories |
| ACROBiosystems |
| Actylis |
| Others |
Value Network & Pricing Analysis
Chemically defined media displacing fetal bovine serum simultaneously redraws procurement geography toward recombinant protein manufacturers and collapses historical margin premiums for plasma fractionation-dependent suppliers. FDA's updated CBER guidance on ancillary material documentation compresses qualification timelines to 12-18 months, forcing buyers to consolidate volumes with qualified suppliers who can absorb regulatory compliance costs.
Pricing Analysis
FDA's updated cell and gene therapy guidance dictates the pricing tier structure across GMP-grade, research-use, and pre-qualified material categories. Three-tier pricing structure across premium, standard, and economy levels separates validated ancillary materials with full regulatory dossiers from research-grade alternatives with limited documentation. Cost compression in research-grade tiers is intensifying because CDMOs are bypassing distributors for direct manufacturer agreements. Academic research institutions exhibit highest price sensitivity due to grant funding constraints, while commercial-stage pharmaceutical sponsors prioritize supply security over unit economics.
Supply Chain Analysis
Controlled-rate DMSO solutions from Massachusetts and Pennsylvania suppliers create a chokepoint that concentrates cold-chain input vulnerability in the northeastern United States. German and Swiss distribution networks draw from domestic recombinant protein production and Dutch cell line manufacturing to serve EMA-regulated CDMOs. Single-source cryopreservation concentration, plasma-derived protein volatility from US fractionation capacity, and REACH registration delays for novel additives constitute the dominant structural risks. Distribution runs through sponsor-proximity logistics networks in Boston-Cambridge and San Francisco Bay Area clusters that now handle the majority of GMP-grade material flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy raw materials constitute a high-growth disruption as allogeneic CAR-T platforms integrate CRISPR editing and serum-free media transitions accelerate under tightening FDA and EMA documentation requirements.
For Market Incumbents: Fortify regulatory affairs capabilities to navigate simultaneous FDA CBER and EMA CAT submission requirements, compressing onboarding cycles for sponsor-mandated second-source validation. Backward integration into recombinant protein production secures margin position against plasma fractionation-dependent competitors facing human albumin supply fluctuations. Capacity addition in Singapore and Japan addresses PMDA accelerated approval pathway demand from Osaka and Kobe manufacturing clusters. For New Entrants and Emerging Players: Anchor in CRISPR electroporation buffer and RNP complex stabilization reagents as emerging categories where qualification pathways remain unsettled and incumbent dossier advantages are weakest. Japan's iPSC-derived therapy manufacturing clusters offer the most penetrable geography due to PMDA's regenerative medicine framework and limited Western supplier presence. A go-to-market angle centered on blockchain-enabled lot traceability platforms enables premium positioning against established distributors. For Investors and Strategic Acquirers: The market sits at a commercialization acceleration phase that favors specialized ancillary material suppliers with cell therapy-specific quality systems over generalist chemical distributors. Long-term viability hinges on regulatory dossier depth and sponsor-direct relationship density rather than geographic coverage breadth. The signal to watch is CDMO master service agreement announcements that bypass regional distributors for media and buffer categories.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Consolidation | ECHA-registered chemistries for DMSO alternatives pre-qualify suppliers for REACH compliance deadlines. |
| Direct Sourcing Relationship Formation | Sponsor-proximity logistics networks in Boston-Cambridge displace traditional distribution intermediaries. |
| Blockchain Traceability Platform Deployment | Real-time chain-of-custody documentation commands premium pricing from quality audit-intensive sponsors. |
| Asian Manufacturing Footprint Expansion | Singapore's Tuas Biomedical Park and Japan's Osaka-Kobe clusters open previously inaccessible procurement demand. |
| Serum-Free Media Formulation Investment | Defined protein concentration alternatives eliminate adventitious agent risks and capture replacement demand. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cell therapy manufacturing executives, CDMO procurement leads, regulatory affairs directors, and quality assurance managers at sponsor organizations. Secondary validation drew from FDA CBER guidance documents, EMA ATMP framework updates, ISO 20399 ancillary material standards, and clinical trial registration databases. Bottom-up volume estimates triangulated against top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Across the analysis window, the forecasting framework modeled reagent and media consumption intensity per manufacturing suite, gene editing application penetration curves, and contract manufacturing capacity expansion trajectories. Segmentation dimensions included GMP-grade versus research-use regulatory tiers, autologous versus allogeneic therapy modalities, and direct versus distributor-mediated procurement channels. CAGRs were derived from regression analysis of historical capacity buildouts correlated with ancillary material consumption coefficients.
Material uncertainties — regulatory guidance revisions, plasma fractionation capacity constraints, and ECHA evaluation timeline extensions — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as FDA CBER documentation requirements and EMA ATMP classification evolution reshape supplier qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
T Cell Therapy Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market