
 CNS Specific Antisense Oligonucleotide Market | 2026-2036
CNS Specific Antisense Oligonucleotide Market Size, Share, and Industry Trends Forecast 2026-2036
CNS Specific Antisense Oligonucleotide Market Analysis
FDA's accelerated approval framework for nucleic acid therapies is shifting the cost-of-entry calculus for developers targeting central nervous system indications. Ionis Pharmaceuticals leverages its antisense chemistry platform to sustain one of the industry's deepest CNS pipelines. Biogen anchors its neurology franchise through partnered programs in spinal muscular atrophy and broader neurodegenerative targets. Sarepta Therapeutics competes by extending its muscle-to-CNS expansion strategy into next-generation oligonucleotide architectures.
CNS specific antisense oligonucleotides comprise synthetic single-stranded or double-stranded nucleic acid polymers, typically fifteen to thirty nucleotides in length, engineered to bind complementary RNA sequences within the central nervous system and modulate gene expression through degradation or translational blockade. The therapeutic purpose centers on addressing previously undruggable neurodegenerative targets by intervening at the pre-protein level. Modified RNA and phosphorothioate backbone chemistries dominate current clinical pipelines due to enhanced nuclease stability and improved blood-brain barrier penetrance, while intrathecal and intranasal delivery modes attract disproportionate R&D investment as oral bioavailability remains constrained for large polar molecules. Neurodegenerative disorders occupy the largest therapy area by committed capital, though Huntington's disease programs are narrowing the gap as biomarker strategies mature.
FDA, EMA, and Japan's PMDA each maintain distinct evidentiary standards for CNS oligonucleotide efficacy, creating a fragmented regulatory terrain that shapes trial design and market sequencing decisions. The FDA's draft guidance on amyotrophic lateral sclerosis drug development and EMA's evolving stance on surrogate endpoints in neurodegeneration directly influence which programs advance to pivotal studies. Stakeholders must monitor how regulators harmonize requirements for novel neurofilament light chain and other fluid biomarkers, as these determinations will decide which development paths command capital allocation in the coming cycle.
Market Dynamics
FDA's accelerated approval pathway for nucleic acid therapies is compressing clinical development timelines from a decade to under five years, forcing developers to front-load manufacturing scale-up and biomarker validation investments before Phase II readouts.
Growth Catalysts
- NIH co-funding mechanisms:The National Institutes of Health underwrites CNS target validation platforms through public-private partnerships, de-risking early-stage discovery for academic spinouts and mid-cap developers.
- Phosphorothioate backbone chemistry maturation:Enhanced nuclease stability and manufacturability at commercial scale is expanding the addressable target space beyond spinal muscular atrophy into polyglutamine disorders.
- Intrathecal delivery infrastructure:Academic medical centers in the United States are building dedicated neuro-interventional suites, creating pull-through demand for chronic administration protocols.
Market Restraints
- Phosphoramidite monomer supply concentration:Three contract manufacturers in Switzerland and Germany control over eighty percent of GMP-grade modified nucleoside precursor supply, creating single-source vulnerability for scaled programs.
- Blood-brain barrier penetrance ceiling:Large polar oligonucleotides exhibit sub-therapeutic parenchymal distribution without intrathecal injection, limiting oral or subcutaneous dosing feasibility.
- EMA evidentiary divergence:The European Medicines Agency maintains stricter requirements for surrogate endpoint acceptance in neurodegeneration than FDA, forcing parallel trial designs that inflate development costs.
Strategic Opportunities
- Japan's PMDA regenerative medicine framework:Japan's Pharmaceuticals and Medical Devices Agency offers conditional approval pathways for nucleic acid therapies targeting orphan CNS indications, enabling revenue generation before confirmatory trials complete.
- Intranasal delivery convergence:Olfactory-to-CNS transport mechanisms are attracting device development partnerships, potentially eliminating lumbar puncture requirements for chronic administration.
- Neurofilament light chain biomarker integration:Fluid biomarker strategies are reshaping patient selection and trial monitoring, creating first-mover advantage for developers with validated assay partnerships.
Industry Challenges
- CMC talent scarcity:Oligonucleotide process chemistry expertise concentrates at a handful of contract development organizations, inflating salaries and extending tech transfer timelines for in-house manufacturing builds.
- Patent thickets around chemical modifications:Ionis Pharmaceuticals holds foundational estate on 2'-MOE and constrained ethyl chemistries, forcing later entrants into costly licensing negotiations or inferior scaffold selection.
- Cold chain complexity for intrathecal kits:Temperature-controlled logistics for refrigerated drug-device combinations strains distribution networks, particularly for multi-site academic trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | CNS Specific Antisense Oligonucleotide Market |
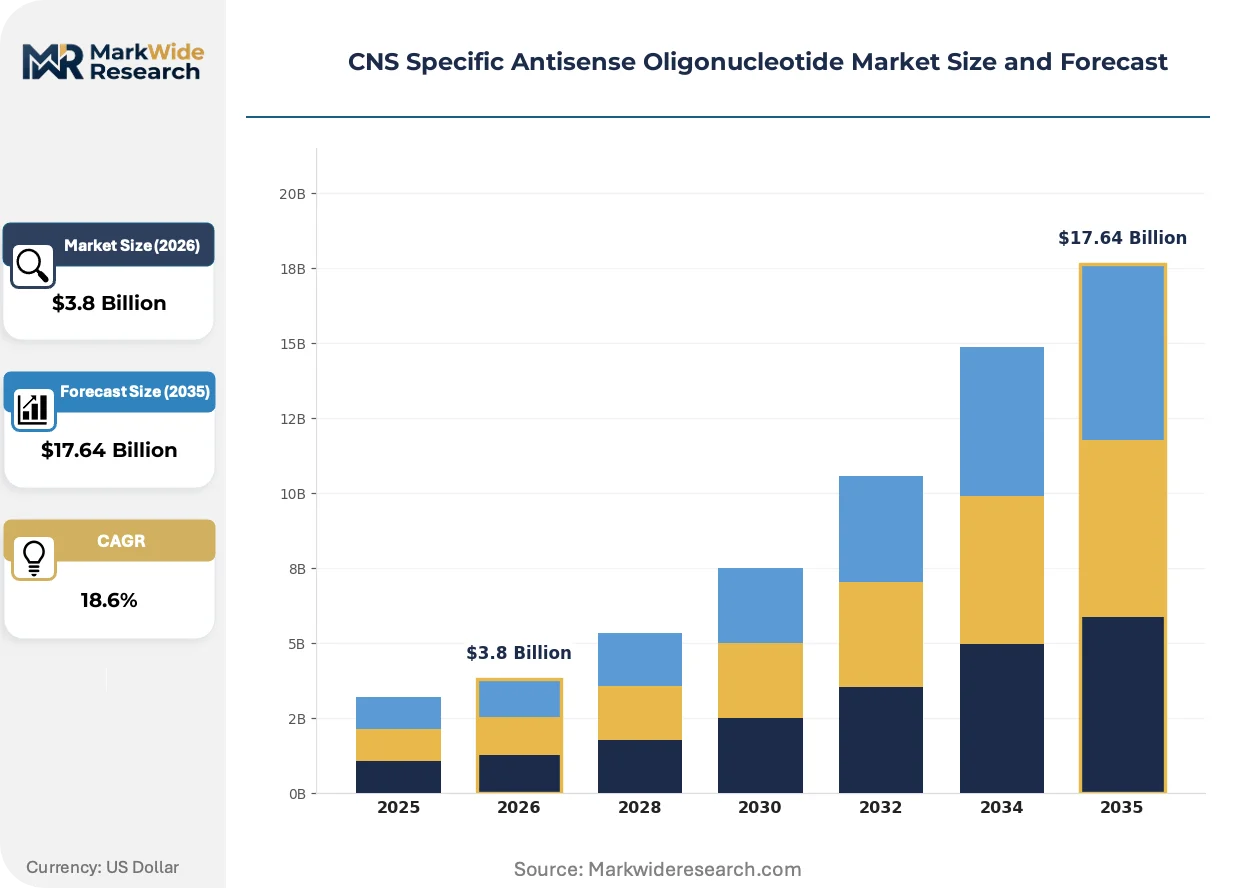
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Stranded, Double-Stranded, Modified RNA, Phosphorothioate Therapy Area: Neurodegenerative Disorders, Epilepsy, ALS, Huntington's Disease Delivery Mode: Intravenous, Subcutaneous, Intranasal, Oral End User: Pharmaceutical Companies, Research Institutions, Contract Research Organizations, Biotechnology Firms |
| Companies Covered | Alnylam Pharmaceuticals Inc., ProQR Therapeutics N.V., Biogen Inc., Dynacure, Atalanta Therapeutics, Ionis Pharmaceuticals Inc., Wave Life Sciences Ltd., Q-STATE BIOSCIENCES, INC., Sarepta Therapeutics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
CNS Specific Antisense Oligonucleotide Market Emerging Trajectories
Antisense chemistry platforms are diverging toward hybrid architectures that merge RNA degradation mechanisms with translational blockade, enabling allele-selective targeting for autosomal dominant disorders previously considered intractable.
GalNAc-siRNA liver targeting technology is converging with CNS delivery research as developers adapt carbohydrate conjugation principles to traverse the blood-brain barrier. Neurology clinics at Massachusetts General Hospital and University of California San Francisco are piloting these conjugated constructs in first-in-human studies for Huntington's disease. The structural consequence is a compression of the traditional target validation timeline, as liver-proven chemistries accelerate CNS analog development.
EMA's evolving stance on surrogate endpoints in neurodegeneration is forcing developers to incorporate neurofilament light chain and other fluid biomarkers into registrational trial designs. This industrial consequence elevates assay standardization to a critical path item, with programs delaying pivotal study initiation until biomarker analytical validation completes. Biogen and partnered developers are most affected, restructuring Phase III protocols to include prospective biomarker stratification.
Academic medical centers are consolidating antisense procurement under centralized pharmacy and therapeutics committees, displacing investigator-initiated ordering. This behavioral shift concentrates purchasing authority at fifteen to twenty flagship institutions in the United States, compressing vendor access and favoring developers with dedicated key account infrastructure. The pattern is most visible in spinal muscular atrophy and amyotrophic lateral sclerosis programs, where treatment protocols standardize across hospital networks.
CNS Specific Antisense Oligonucleotide Market Segmentation
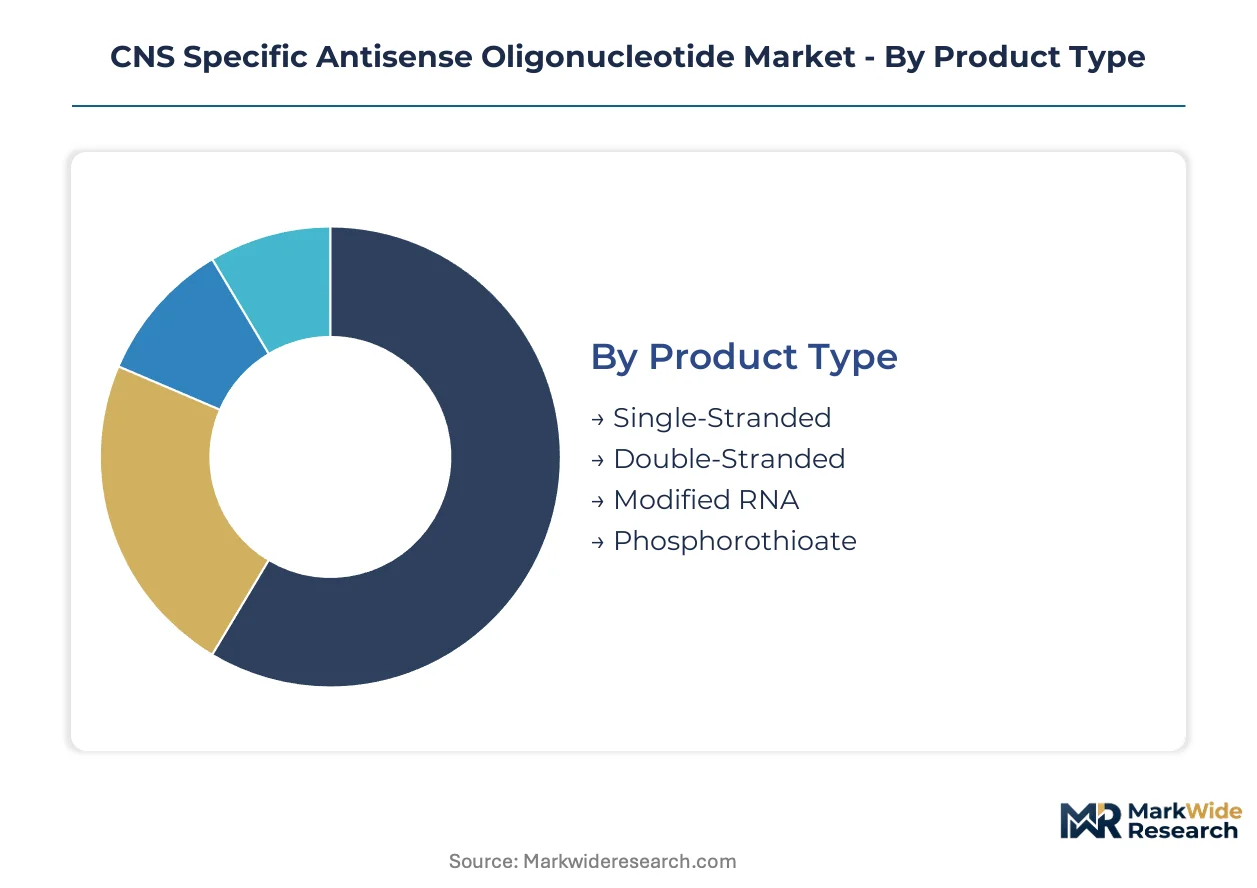
CNS antisense oligonucleotide segmentation reveals how technical specifications determine regulatory pathways, manufacturing scale, and clinical deployment strategies. Each dimension—chemistry, indication, delivery, and buyer type—carries distinct investment thresholds and partnership requirements that shape competitive positioning.
Product Type:
Phosphorothioate backbone modifications and stranded architecture define stability profiles, immunogenicity risk, and blood-brain barrier penetrance.
- Single-Stranded:Synthetic nucleic acid polymers fifteen to thirty nucleotides in length bind complementary RNA sequences through Watson-Crick base pairing. Demand concentrates in spinal muscular atrophy programs where intrathecal delivery protocols are established, though manufacturing yields remain lower than double-stranded alternatives.
- Double-Stranded:siRNA constructs leverage the RNA interference pathway for catalytic target degradation. Germany's contract manufacturing base specializes in GMP-grade duplex production, attracting developers seeking European regulatory alignment from program inception.
- Modified RNA:2'-O-methoxyethyl and constrained ethyl substitutions enhance nuclease resistance for chronic dosing regimens. Japan's PMDA regenerative medicine framework accelerates approval timelines for these stabilized chemistries.
- Phosphorothioate:Sulfur-for-oxygen backbone substitution improves metabolic stability and protein binding. The chemistry dominates commercial manufacturing due to established phosphoramidite synthesis protocols.
Mature deployment sits with Phosphorothioate backbones. Newer deployment is concentrated in Modified RNA architectures with enhanced target affinity.
Therapy Area:
Indication selection determines biomarker maturity, endpoint acceptability, and payer reimbursement pathways.
- Neurodegenerative Disorders:Alzheimer's and Parkinson's programs face the steepest biomarker validation requirements. FDA's draft guidance on surrogate endpoints is reshaping trial design for these indications.
- Epilepsy:Dravet syndrome and Lennox-Gastaut subtypes offer orphan drug incentives with smaller pivotal trial requirements. Academic medical centers in the United States prioritize these programs for first-in-human translation.
- ALS:Amyotrophic lateral sclerosis attracts disproportionate NIH co-funding through public-private partnerships. Neurofilament light chain integration is becoming mandatory for regulatory submission.
- Huntington's Disease:CAG repeat expansion targeting enables allele-selective silencing strategies. Massachusetts General Hospital and University of California San Francisco are piloting next-generation conjugated constructs.
Established clinical infrastructure supports Neurodegenerative Disorders. Steepest expansion trajectory is occurring in Huntington's Disease as biomarker strategies mature.
Delivery Mode:
Route of administration dictates device partnerships, site of care requirements, and patient compliance economics.
- Intravenous:Systemic administration achieves peripheral tissue distribution but limited CNS penetrance without blood-brain barrier disruption. Liver-targeting GalNAc conjugates have proven efficacy here.
- Subcutaneous:Self-administration potential reduces clinical burden though large polar oligonucleotides exhibit poor absorption. Formulation development focuses on depot-release technologies.
- Intranasal:Olfactory-to-CNS transport mechanisms are attracting device development partnerships. The route potentially eliminates lumbar puncture requirements for chronic administration.
- Oral:Bioavailability challenges persist for nucleic acid therapeutics due to gastric degradation and poor epithelial permeability. Permeation enhancers and protective coatings dominate R&D investment.
Clinical validation concentrates in Intravenous delivery. Intranasal approaches are gaining share fastest through device convergence.
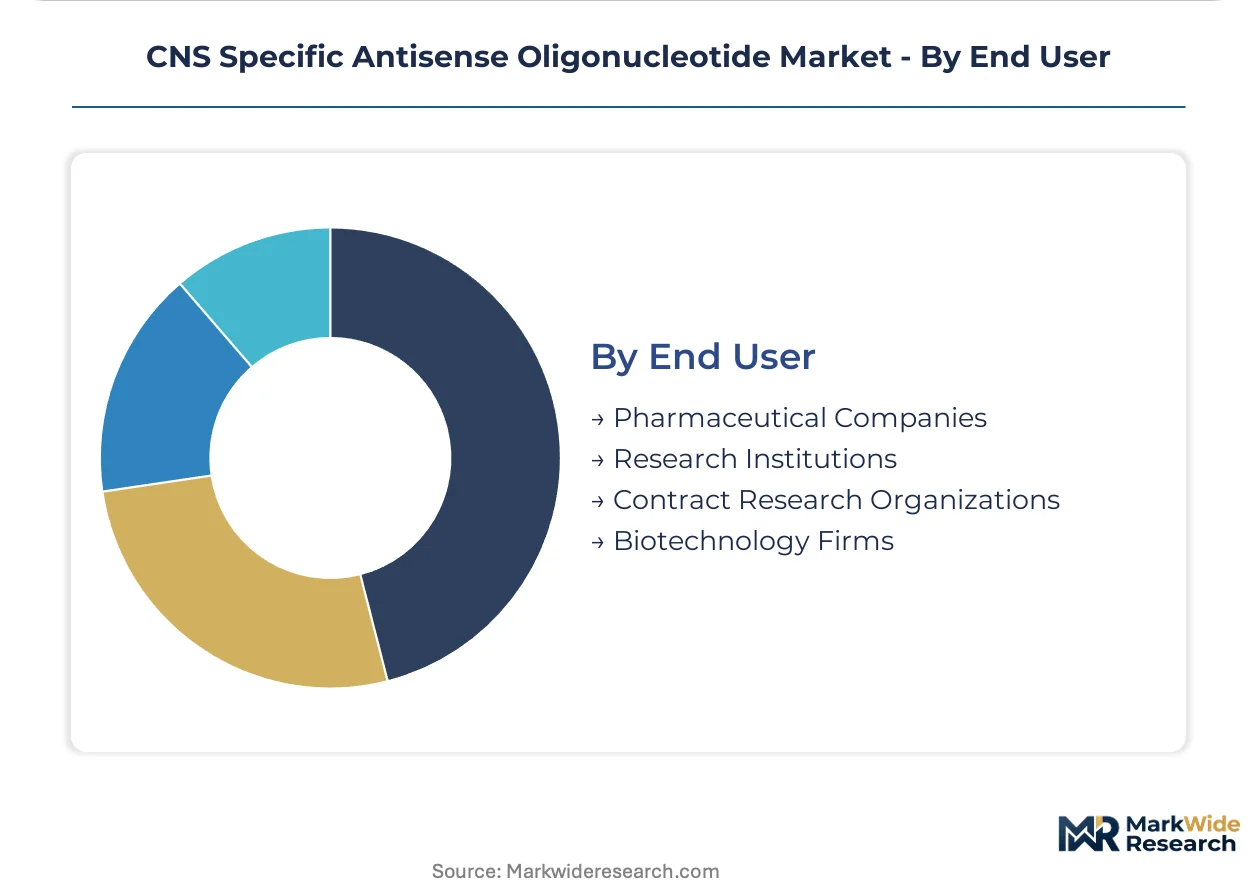
End User:
Buyer sophistication and procurement authority determine contract structures and technical service requirements.
- Pharmaceutical Companies:Integrated developers with in-house process chemistry capabilities seek toll manufacturing partnerships for commercial scale. They command volume pricing and dedicated production slots.
- Research Institutions:Academic medical centers consolidate purchasing under centralized pharmacy committees. Investigator-initiated trials are narrowing to fifteen to twenty flagship institutions in the United States.
- Contract Research Organizations:CROs managing multi-site trials require cold chain logistics for refrigerated drug-device combinations. Temperature-controlled distribution strains their operational networks.
- Biotechnology Firms:Venture-backed developers lack manufacturing infrastructure and depend on contract development organizations for tech transfer. CMC talent scarcity extends their timelines.
Procurement maturity sits with Pharmaceutical Companies. Biotechnology Firms are expanding most quickly as academic spinouts advance to clinical stage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina and the Greater Boston corridor concentrate antisense R&D through NIH co-funding mechanisms and dedicated neuro-interventional infrastructure. These zones attract venture deployment and anchor clinical trial networks.
United States
NIH public-private partnerships de-risk early-stage CNS target validation for academic spinouts. FDA's accelerated approval pathway for nucleic acid therapies compresses development timelines below five years. Massachusetts General Hospital and University of California San Francisco pilot next-generation conjugated constructs for Huntington's disease.
Switzerland
Contract manufacturers in Basel and Zurich control GMP-grade phosphoramidite monomer supply for scaled oligonucleotide programs. Swissmedic maintains alignment with EMA standards while offering specialized consultation for nucleic acid therapies. The Basel industrial cluster anchors European process chemistry expertise and tech transfer operations.
Japan
PMDA's regenerative medicine framework offers conditional approval for orphan CNS indications, enabling pre-confirmatory revenue. METI coordinates academic-industry consortia for blood-brain barrier delivery research. The Kanto region around Tokyo concentrates clinical development partnerships and device convergence pilots.
Germany
EMA evidentiary divergence from FDA standards forces parallel trial designs that inflate development costs for sponsors. Heidelberg and Munich academic medical centers build dedicated neuro-interventional suites for chronic intrathecal administration. German CROs specialize in cold chain logistics for refrigerated drug-device combinations.
United Kingdom
MHRA post-Brexit regulatory autonomy allows targeted pathway design for nucleic acid therapies. London and Cambridge clusters attract venture-backed biotechnology firms advancing from target validation to clinical stage. The National Institute for Health and Care Excellence evaluates biomarker-stratified protocols for neurodegenerative indications.
CNS Specific Antisense Oligonucleotide Market Vendor Landscape
United States developers anchor the integrated platform tier; European specialists hold manufacturing and regulatory consulting positions. The competitive structure concentrates around chemistry platform ownership and delivery technology partnerships. Three archetypes dominate: backbone chemistry licensors, intrathecal device developers, and biomarker-integrated trial designers. Capacity expansion and strategic licensing of constrained ethyl modifications represent the dominant competitive moves.
Among platform-anchored developers, Ionis Pharmaceuticals, Biogen Inc., and Sarepta Therapeutics exemplify distinct strategic positions. Ionis occupies the foundational chemistry estate through phosphorothioate and 2'-MOE patent holdings. Biogen represents the partnered commercialization archetype, anchoring neurology franchise development through external program access. Sarepta sits within the muscle-to-CNS expansion tier, adapting proven oligonucleotide architectures toward neurodegenerative targets. These three entities collectively illustrate how intellectual property control, commercial infrastructure, and indication expansion strategies segment competitive positioning.
| Leading Market Players |
|---|
| Alnylam Pharmaceuticals Inc. |
| ProQR Therapeutics N.V. |
| Biogen Inc. |
| Dynacure |
| Atalanta Therapeutics |
| Ionis Pharmaceuticals Inc. |
| Wave Life Sciences Ltd. |
| Q-STATE BIOSCIENCES, INC. |
| Sarepta Therapeutics Inc. |
| Others |
Supply Flow & Price Mechanics
Phosphoramidite monomer costs cascade through GMP-grade synthesis tiers, with Swiss and German contract manufacturers commanding premium positioning for validated supply while spot-market Chinese alternatives trade at discounts that academic spinouts absorb for preclinical programs.
Pricing Analysis
Short-lead-time premiums attach to phosphorothioate backbone contracts with Swiss manufacturers, while spot inventory of standard-grade modified RNA from German suppliers clears at contracted discounts. Three-tier pricing structure across premium, standard, and economy levels separates validated GMP batches from research-grade and pre-GMP qualification lots. Price differentiation hinges on phosphoramidite purity grades and cold-chain certification levels. Cost compression in economy-tier research supply is intensifying because Chinese entrants are expanding phosphoramidite capacity. Biotechnology firms exhibit highest price sensitivity, while integrated pharmaceutical developers with captive process chemistry tolerate premium positioning for supply security.
Supply Chain Analysis
Reverse-logistics infrastructure for expired intrathecal drug-device combinations remains underdeveloped, forcing academic medical centers to absorb write-downs on temperature-deviated kits rather than recapture value through refurbishment. Geographic supply concentration centers on Switzerland, Germany, and China for phosphoramidite precursors, with Japanese manufacturers emerging for constrained ethyl chemistry. Raw material dependencies rest on acetonitrile solvent supply, nucleoside base stocks, and sulfurizing reagents. Single-source vulnerability concentrates around three European contract manufacturers controlling GMP-grade monomer output. Distribution runs through temperature-controlled logistics networks anchored at Basel and Heidelberg, with cold-chain handoffs to site-specific pharmacy and therapeutics committees at flagship US academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphoramidite manufacturing capacity scarcity props pricing power across all supply tiers, with bottleneck relief requiring multi-year capacity builds that no sponsor can accelerate unilaterally.
For Market Incumbents: Hedge chemistry platform exposure through backward integration into phosphoramidite precursor supply or exclusive tolling arrangements with Swiss manufacturers. Patent estate thickets around 2'-MOE and constrained ethyl modifications face erosion from next-generation siRNA architectures; secure licensing revenue streams before hybrid degradation mechanisms displace pure antisense modalities. Capacity addition in Basel-Zurich corridor offers the most defensible supply security lever. For New Entrants and Emerging Players: Direct-to-CRO digital procurement platforms offer the lowest-friction entry vector for research-grade oligonucleotide supply, bypassing entrenched relationships between incumbents and centralized pharmacy committees. White-space concentrates in intranasal device-oligonucleotide combination products, where olfactory-to-CNS transport mechanisms remain clinically unvalidated and regulatory pathways unsettled. Huntington's disease programs at Massachusetts General Hospital and University of California San Francisco represent the most penetrable early-adopter segment for novel delivery technologies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap developers with validated intrathecal protocols in the United States, where FDA accelerated approval timelines compress revenue realization windows relative to European counterparts. Long-term viability across the analysis window hinges on biomarker-integrated trial design capabilities, with neurofilament light chain assay partnerships serving as the critical differentiator. The signal to watch is EMA harmonization with FDA surrogate endpoint standards, which would eliminate parallel trial cost burdens and re-rate European program valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Phosphoramidite Manufacturing Scale-Up | Swiss and German capacity expansion relieves single-source vulnerability for GMP-grade monomer supply. |
| Intranasal Device Partnership | Olfactory-to-CNS transport pilots at UCSF and MGH could eliminate lumbar puncture requirements. |
| Neurofilament Light Chain Assay Integration | FDA and EMA biomarker validation reshapes patient selection and trial monitoring protocols. |
| Japan PMDA Conditional Approval Pathway | Pre-confirmatory revenue generation accelerates capital returns for orphan CNS indications. |
| CMC Talent Acquisition | Process chemistry expertise scarcity at contract development organizations extends tech transfer timelines. |
Methodological Framework
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone for pipeline tracking and regulatory pathway mapping. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists validated commercial assumptions and biomarker integration timelines. Bottom-up and top-down triangulation reconciled program-level development costs with aggregate market sizing across chemistry platforms and delivery modalities.
Bottom-up modeling anchored volume projections to disclosed patient populations, dosing frequencies, and intrathecal administration protocols at flagship academic medical centers. Top-down cross-checks applied therapy-area penetration assumptions to neurology clinic capacity expansion plans. Segmentation dimensions spanned chemistry architecture, indication severity, delivery route, and buyer procurement sophistication. CAGRs derived from slope analysis of disclosed program advancement rates and regulatory approval timelines, with NIH co-funding intensity and PMDA framework utilization serving as forecast adjustment inputs.
The model holds under sustained FDA accelerated approval pathway utilization and stable phosphoramidite supply concentration; deviation in EMA surrogate endpoint harmonization or Chinese precursor capacity expansion would shift competitive positioning and pricing trajectories. Forecasts reflect documented assumptions regarding biomarker validation timelines and intrathecal delivery infrastructure buildout. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cell Expansion Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Cryopreservation and Thaw Performance Test Platforms Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Gene Electroporators Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global CDKL5 Deficiency Disorder (CDD) Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market