
 MRNA Therapeutics Contract Development and Manufacturing Organization Market | 2026-2036
MRNA Therapeutics Contract Development and Manufacturing Organization Market Size, Share, and Industry Trends Forecast 2026-2036
MRNA Therapeutics Contract Development and Manufacturing Organization Market Insights
Buyer concentration among biopharmaceutical companies is expanding as large-cap developers consolidate their CDMO relationships around multi-year platform partnerships rather than transactional project work. Lonza leverages its global manufacturing network to anchor mRNA production capacity across Switzerland and the United States. Thermo Fisher Scientific sustains competitive intensity through integrated supply chains spanning raw materials, plasmid DNA, and fill-finish services. Samsung Biologics differentiates via large-scale bioreactor infrastructure purpose-built for nucleic acid manufacturing at its Songdo campus.
MRNA Therapeutics Contract Development and Manufacturing Organizations are specialized service providers that execute in-vitro transcription, lipid nanoparticle encapsulation, and quality-controlled purification of messenger RNA drug substances under regulated conditions, with batch yields and impurity profiles monitored against pharmacopeial standards to ensure therapeutic-grade output for clinical and commercial use. Commercial Production currently dominates service revenue as developers outsource late-stage manufacturing, while Lipid Nanoparticle technology leads fastest growth due to its established delivery efficacy in approved COVID-19 and oncology pipelines. RNA Vaccines occupy the largest product type share, though RNA Medicines for rare genetic disorders represent the emerging margin pool attracting specialized CDMO investment.
FDA enforces Current Good Manufacturing Practice standards for mRNA therapeutics through its Center for Biologics Evaluation and Research, while EMA applies its Good Manufacturing Practice guidelines via national competent authorities across EU member states, with both frameworks demanding extensive validation of aseptic processing and analytical consistency. ISO 13485 and ICH Q5A standards further constrain supplier qualification and viral safety testing protocols. Stakeholders must monitor how evolving regulatory harmonization between FDA and EMA on nucleic acid drug substance specifications reshapes CDMO audit burdens and capital deployment timelines.
Market Dynamics
Platform standardization around lipid nanoparticle encapsulation is consolidating CDMO selection criteria, as developers now prioritize partners with validated end-to-end IVT-to-LNP workflows over fragmented single-service vendors.
Growth Catalysts
- EMA nucleic acid GMP harmonization:The agency's draft guidelines on mRNA drug substance specifications are accelerating CDMO qualification investments across EU member states, expanding contractable manufacturing capacity for European biotech sponsors.
- Oncology pipeline expansion:Personalized neoantigen vaccines are electrifying demand for small-batch, high-changeover manufacturing capabilities that traditional biologics CDMOs cannot readily supply.
- Plasmid DNA supply scarcity:Concentration of GMP-grade pDNA production in North American and European specialist facilities is forcing developers into captive CDMO relationships to secure raw material continuity.
Market Restraints
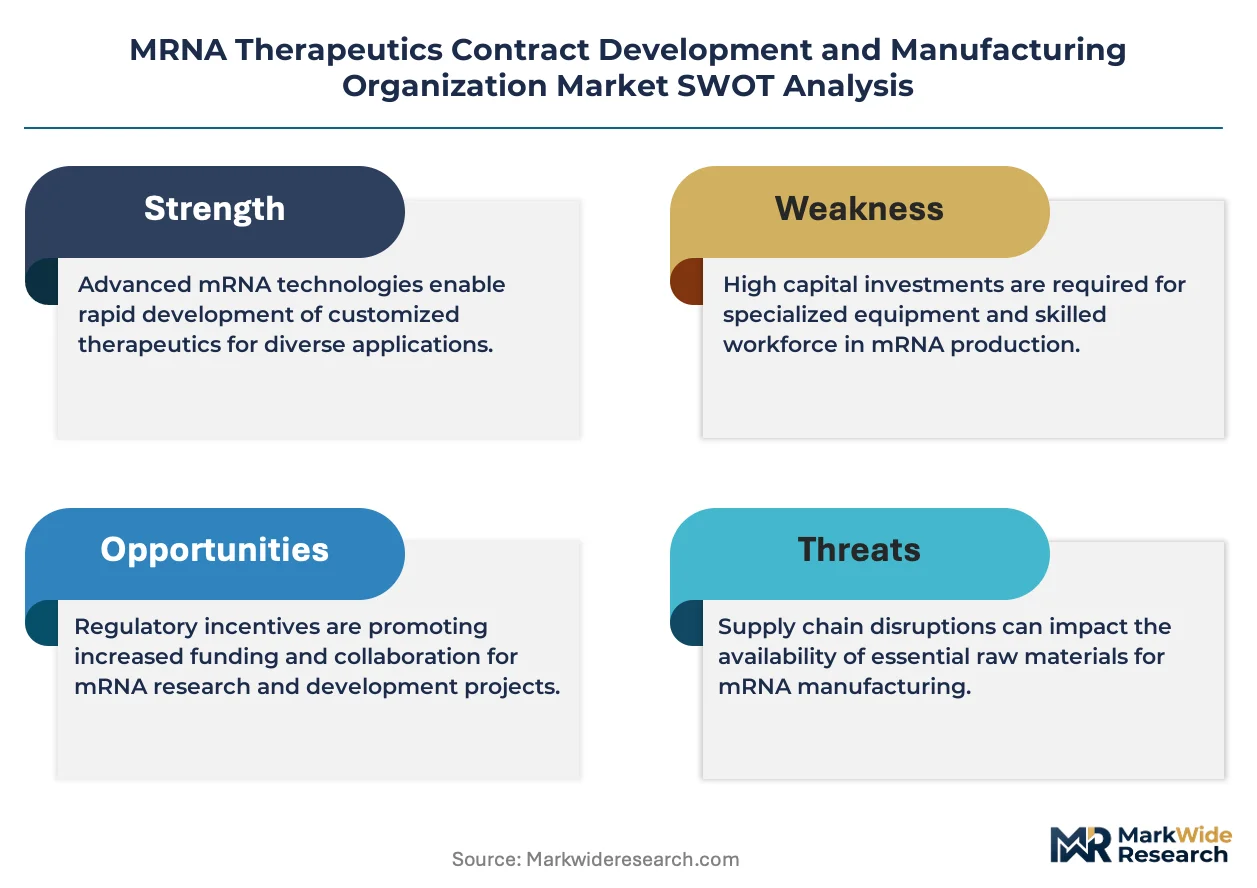
- Chromatography resin cost volatility:Purification-grade synthetic resins for oligonucleotide separation face input cost pressure from petroleum-derived monomer supply constraints, compressing CDMO margin structures.
- Swiss manufacturing concentration:Disproportionate share of validated mRNA drug substance capacity sits within a 150-kilometer radius of Basel, creating single-point-of-failure exposure for global supply continuity.
- Enzyme supplier oligopoly:T7 RNA polymerase and capping enzyme production concentrates among three specialized biotechnology suppliers, limiting CDMO negotiation leverage on critical input pricing.
Strategic Opportunities
- Japan PMDA regulatory pathway:The agency's 2023 guidance on nucleic acid therapeutics creates first-mover advantage for CDMOs establishing local GMP audit history ahead of domestic biopharma pipeline maturation.
- Self-amplifying RNA convergence:Integration of replicon technology with conventional mRNA manufacturing infrastructure offers yield multiplication without proportional capital expansion, opening mid-scale CDMO participation.
- India CDSCO export incentive alignment:The country's production-linked incentive scheme for biotechnology manufacturing is attracting contract development investment for cost-sensitive vaccine export markets.
Industry Challenges
- Analytical method transfer bottlenecks:Sponsor-developed potency assays for novel mRNA constructs require 12-18 month validation cycles at CDMO sites, delaying clinical supply initiation.
- Aseptic processing workforce scarcity:Qualified operators for closed-system in-vitro transcription under ISO 5 conditions remain concentrated among incumbent biologics manufacturers, constraining capacity expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRNA Therapeutics Contract Development and Manufacturing Organization Market |
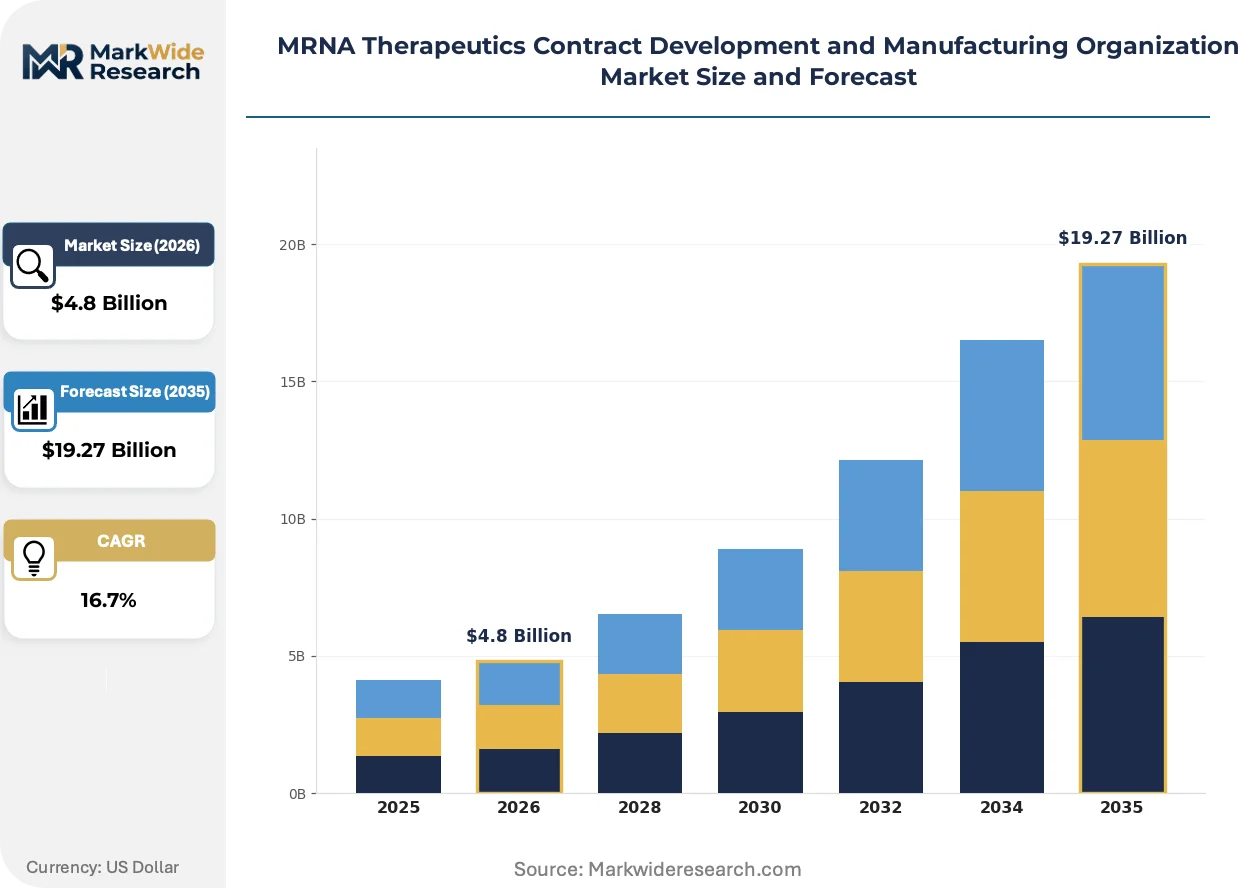
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Formulation Development, Process Development, Analytical Testing, Commercial Production Technology: In-vitro Transcription, Lipid Nanoparticles, Cell-free Systems, Quality By Design End User: Biopharmaceutical Companies, Academic Institutions, Government Research Labs, Startups Product Type: RNA Vaccines, RNA Medicines, Diagnostic Kits, Others |
| Companies Covered | Lonza, Thermo Fisher Scientific, Catalent, Wuxi Biologics, Eurofins Scientific, Recipharm AB, Aldevron, Samsung Biologics, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRNA Therapeutics Contract Development and Manufacturing Organization Market Trends and Innovations
Continuous manufacturing modalities are displacing batch-process dominance in nucleic acid production, with integrated perfusion-based IVT systems now entering commercial validation phases.
Microfluidic lipid nanoparticle formation is electrifying encapsulation efficiency benchmarks, achieving polydispersity indices below 0.1 at throughputs exceeding 10 liters per hour. Mid-cap biopharma developers are adopting these platforms for Phase II oncology candidates, compressing formulation development timelines from 18 months to under 6 months. The technology is enabling geographic decentralization of fill-finish operations, reducing cold-chain distribution burdens for temperature-sensitive drug products.
FDA's emerging guidance on real-time release testing for mRNA vaccines is reshaping analytical investment patterns across CDMO quality organizations. The framework permits parametric release based on in-process monitoring rather than end-point testing, accelerating batch disposition timelines. Commercial production segments with established process analytical technology infrastructure are capturing disproportionate sponsor preference for late-stage programs.
Biopharma procurement functions are consolidating CDMO panels from 8-12 qualified vendors to 2-3 strategic platform partnerships, embedding quality agreements and capacity reservation clauses into multi-year contracts. This concentration is displacing transactional project-based sourcing for clinical-stage manufacturing. United States-based developers with approved COVID-19 products are most advanced in this transition, locking in dedicated manufacturing suites through 2028.
MRNA Therapeutics Contract Development and Manufacturing Organization Market Segmentation
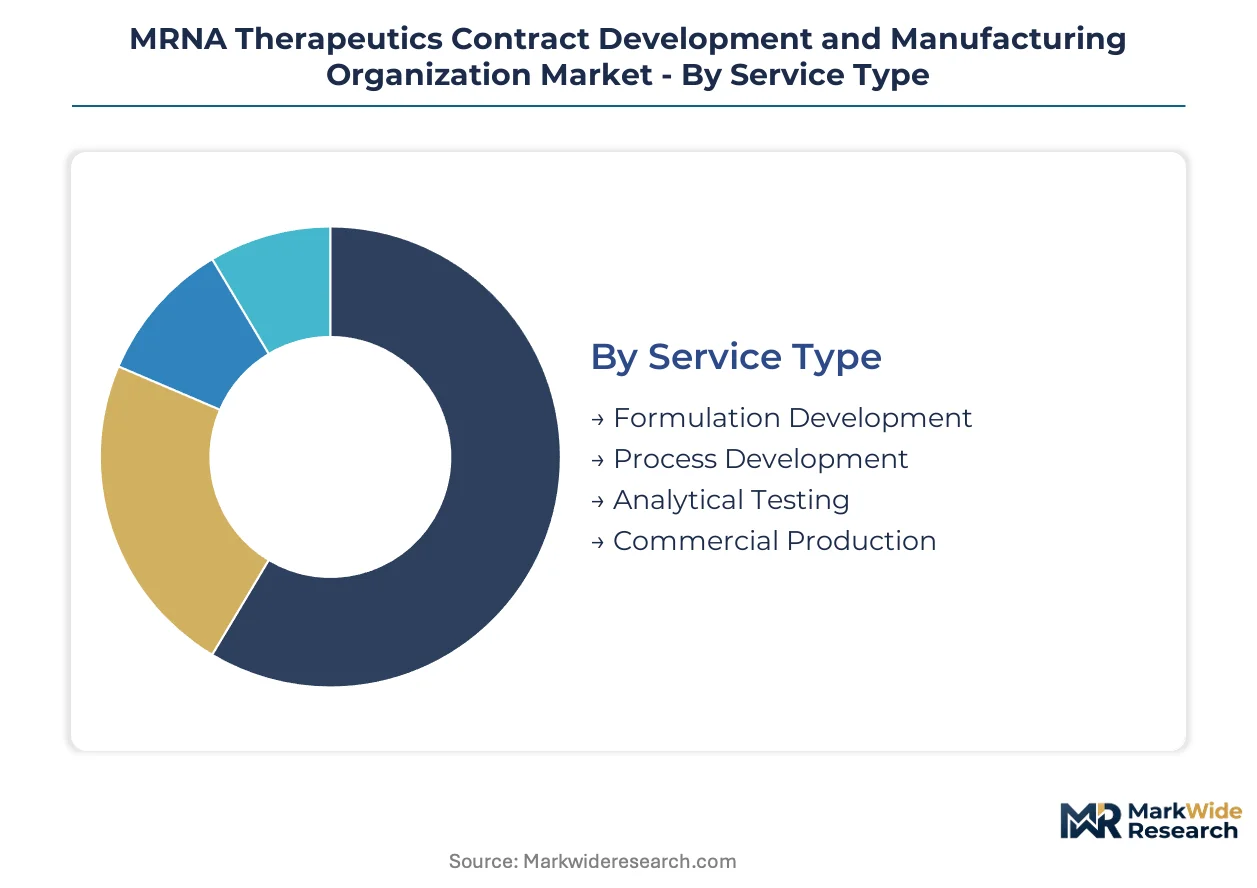
mRNA CDMO procurement is shifting from transactional project sourcing toward platform-aligned partnerships, making segment-level capability matching critical for sponsor qualification decisions. Developers now evaluate CDMOs against end-to-end workflow compatibility rather than discrete service procurement.
Service Type:
Service selection cycles accelerate as biopharmaceutical sponsors consolidate vendor panels around integrated platform capabilities rather than fragmented single-service contracts.
- Commercial Production:Late-stage GMP manufacturing of drug substance and drug product under validated aseptic conditions, with batch records submitted to FDA and EMA for lot release. Demand clusters among United States-based developers with approved COVID-19 products seeking dedicated suite capacity through 2028.
- Process Development:Optimization of in-vitro transcription reaction kinetics, lipid nanoparticle encapsulation efficiency, and purification yield to meet target product profile specifications. Sponsors in the Boston-Cambridge corridor prioritize CDMOs with demonstrated tech transfer acceleration for personalized neoantigen vaccines.
- Formulation Development:Stability-indicating buffer selection and lyophilization cycle design for temperature-sensitive mRNA constructs.
- Analytical Testing:Potency assay validation, impurity profiling, and release testing against pharmacopeial standards.
Volume placements concentrate in Commercial Production; the faster expansion belongs to Process Development.
Technology:
Technology adoption patterns reflect sponsor pipeline composition, with oncology developers prioritizing encapsulation precision over yield maximization.
- Lipid Nanoparticles:Microfluidic and T-junction mixing platforms for encapsulating mRNA in ionizable lipid, cholesterol, helper lipid, and PEG-lipid formulations. United States and European sponsors with Phase II oncology candidates drive demand for polydispersity indices below 0.1.
- In-vitro Transcription:Enzymatic synthesis of capped and polyadenylated mRNA from linearized plasmid DNA templates using T7 RNA polymerase. CDMOs in Switzerland and the United States dominate validated capacity for G-grade nucleoside-modified constructs.
- Cell-free Systems:Continuous manufacturing modalities displacing batch-process dominance in nucleic acid production.
- Quality By Design:Systematic approach to process development that emphasizes understanding the relationship between process parameters and product quality.
Adoption intensity runs highest for Lipid Nanoparticles; Cell-free Systems are climbing the fastest as continuous processing validates at commercial scale.
End User:
End-user procurement sophistication varies dramatically, dictating CDMO engagement models from transactional to strategic.
- Biopharmaceutical Companies:Large-cap and mid-cap developers outsourcing mRNA manufacturing under multi-year platform partnerships with embedded capacity reservation clauses. FDA and EMA guideline tightening around nucleic acid GMP is accelerating their CDMO consolidation from 8-12 vendors to 2-3 strategic relationships.
- Academic Institutions:Research-grade mRNA production for preclinical proof-of-concept studies, typically sourced through university-affiliated core facilities or small-scale CDMOs.
- Government Research Labs:Pandemic preparedness and biodefense contract manufacturing requiring surge capacity agreements.
- Startups:Venture-backed developers seeking flexible, milestone-based CDMO contracts with minimal upfront capital commitment.
Contract value concentrates with Biopharmaceutical Companies; the steepest expansion trajectory belongs to Startups as venture financing flows into mRNA oncology platforms.
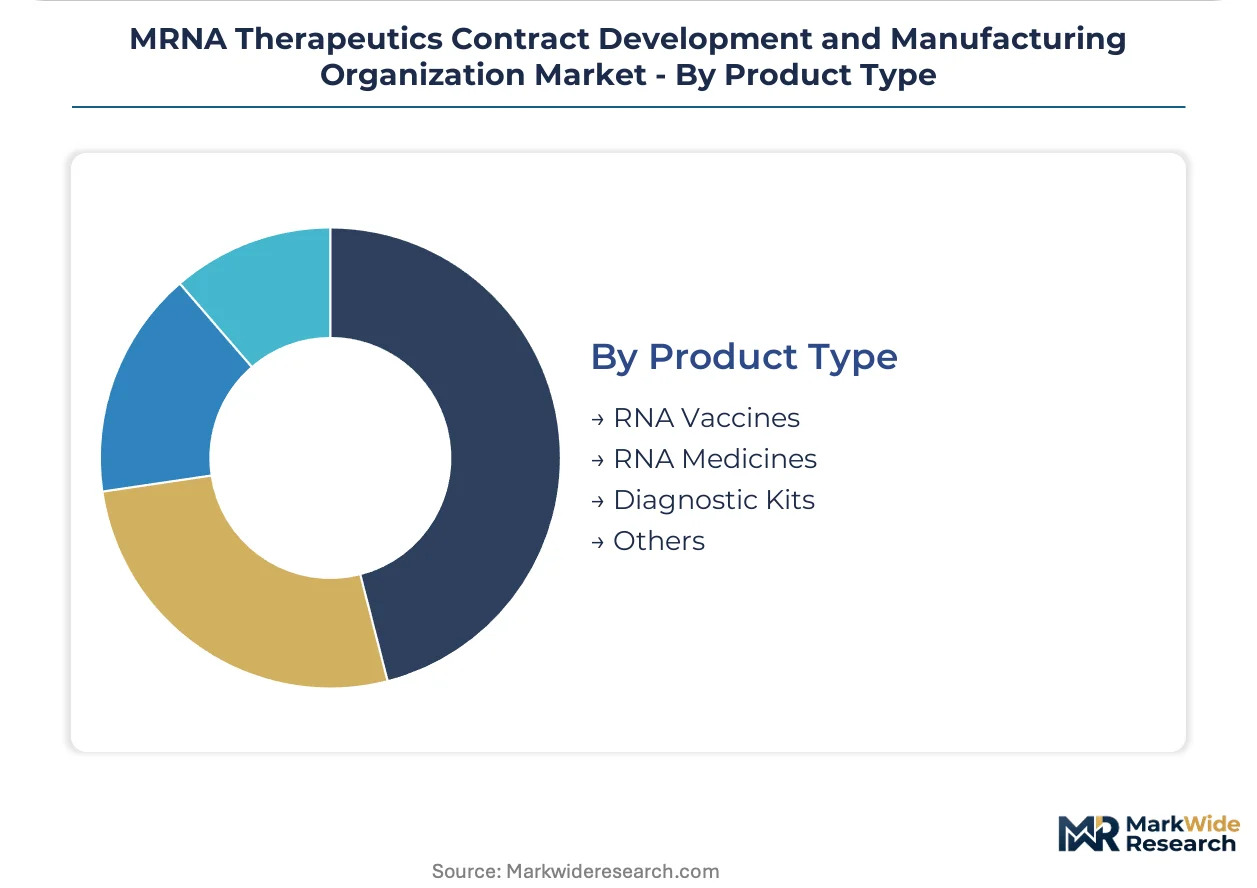
Product Type:
Product-type demand distribution reflects therapeutic area maturity and reimbursement pathway clarity.
- RNA Vaccines:Prophylactic and therapeutic vaccines against infectious disease and cancer, representing the largest installed base of approved mRNA products. COVID-19 franchise manufacturers in the United States sustain the dominant share of CDMO capacity allocation.
- RNA Medicines:mRNA-encoded protein replacement therapies and gene editing applications for rare genetic disorders. Developers targeting methylmalonic acidemia and other ultra-rare indications are creating specialized margin pools for CDMOs with small-batch, high-changeover capabilities.
- Diagnostic Kits:mRNA-based biomarker detection and companion diagnostic applications.
- Others:Emerging applications including self-amplifying RNA and circular RNA constructs.
Manufacturing volume anchors in RNA Vaccines; RNA Medicines are gaining share fastest as rare disease pipelines mature toward clinical supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States biopharmaceutical sponsors concentrate CDMO procurement in the Boston-Cambridge corridor, where venture-backed mRNA developers compete for limited GMP manufacturing slots. FDA nucleic acid GMP enforcement through its Center for Biologics Evaluation and Research tightens qualification standards, accelerating developer migration toward multi-year platform partnerships with validated suppliers.
United States
COVID-19 franchise manufacturers sustain dominant share of commercial production capacity allocation through dedicated suite reservations extending to 2028. FDA real-time release testing guidance for mRNA vaccines reshapes analytical investment patterns across quality organizations. The Boston-Cambridge biotech corridor hosts the densest cluster of developers seeking end-to-end IVT-to-LNP manufacturing partnerships.
Switzerland
Validated mRNA drug substance capacity concentrates disproportionately within a 150-kilometer radius of Basel, creating supply continuity exposure for global sponsors. Swissmedic applies GMP guidelines for nucleic acid therapeutics with emphasis on aseptic processing validation. Lonza leverages its global manufacturing network to anchor production capacity across Swiss and United States sites.
Germany
EMA nucleic acid GMP harmonization accelerates CDMO qualification investments across EU member states, expanding contractable capacity for European biotech sponsors. The country's national pharmaceutical regulator enforces extensive validation requirements for aseptic processing and analytical consistency. The Rhine-Main biotech cluster attracts specialized CDMO investment for rare genetic disorder pipelines.
Japan
PMDA's 2023 guidance on nucleic acid therapeutics creates first-mover advantage for CDMOs establishing local GMP audit history ahead of domestic biopharma pipeline maturation. METI biotechnology manufacturing incentives support capacity expansion for temperature-sensitive drug products. The Kanto region around Tokyo concentrates qualified operators for closed-system in-vitro transcription under ISO 5 conditions.
India
CDSCO export incentive alignment through production-linked incentive schemes attracts contract development investment for cost-sensitive vaccine export markets. Plasmid DNA supply scarcity forces developers into captive CDMO relationships to secure raw material continuity. The Hyderabad-Bangalore biotech corridor emerges as a destination for mid-scale mRNA manufacturing infrastructure.
MRNA Therapeutics Contract Development and Manufacturing Organization Market Competitive Landscape
Swiss and United States producers anchor one tier of validated commercial capacity; Asian specialists hold emerging positions in process development and cost-sensitive manufacturing. The vendor base organizes around three strategic archetypes: integrated life sciences conglomerates with raw material-to-fill-finish supply chains, pure-play biologics CDMOs with nucleic acid manufacturing specialization, and emerging Asian contractors leveraging government incentive alignment. Dominant competitive moves include multi-year platform partnerships embedding capacity reservation clauses and geographic expansion into underpenetrated regulatory jurisdictions.
Within the integrated conglomerate tier, Thermo Fisher Scientific exemplifies supply chain breadth spanning plasmid DNA, enzymes, and analytical testing. Lonza represents the pure-play CDMO archetype with validated end-to-end mRNA workflows across Swiss and United States manufacturing networks. Samsung Biologics anchors the Asian specialist position with large-scale bioreactor infrastructure purpose-built for nucleic acid manufacturing.
| Leading Market Players |
|---|
| Lonza |
| Thermo Fisher Scientific |
| Catalent |
| Wuxi Biologics |
| Eurofins Scientific |
| Recipharm AB |
| Aldevron |
| Samsung Biologics |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
FDA nucleic acid GMP enforcement gates qualified supply access and premium-tier pricing for mRNA CDMO services, as validated aseptic processing capabilities command substantial markups over standard biologics manufacturing. Developers seeking dedicated suite capacity through multi-year platform partnerships absorb premium pricing to secure regulatory-compliant production slots.
Pricing Analysis
Volume placements anchor in transactional project-based contracts for early-stage developers, while margin capture concentrates in strategic platform partnerships embedding capacity reservation clauses and quality agreement premiums. Pricing stratifies across GMP-grade commercial production, validated process development, and research-grade analytical services, with FDA and EMA audit history commanding the widest spreads. Cost compression in chromatography resin inputs is intensifying because petroleum-derived monomer supply constraints squeeze mid-tier CDMO margins. Venture-backed startups in the Boston-Cambridge corridor exhibit the highest price sensitivity, whereas approved COVID-19 franchise manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Regional distribution centers for plasmid DNA templates and lipid raw materials concentrate in Switzerland, the United States, and Germany, creating hub-and-spoke patterns radiating from Basel and Boston-Cambridge manufacturing clusters. GMP-grade pDNA production draws from North American and European specialist facilities, while T7 RNA polymerase and capping enzyme supply rests on three specialized biotechnology suppliers. Single-source vulnerability in Swiss manufacturing concentration within 150 kilometers of Basel exposes global sponsors to supply continuity disruption. Distribution runs through temperature-controlled logistics networks serving fill-finish operations with cold-chain requirements for lipid nanoparticle drug products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA nucleic acid GMP harmonization is accelerating CDMO qualification investments that weaker capitalized players cannot match, consolidating contractable capacity around validated incumbents with multi-year platform partnership infrastructure.
For Market Incumbents: Hedge against enzyme supplier oligopoly exposure through captive supply agreements or backward integration into T7 RNA polymerase production capabilities. Expand validated manufacturing footprint beyond Swiss concentration risk by qualifying additional sites in the United States or Japan ahead of PMDA pipeline maturation. Defensive consolidation of analytical testing capabilities insulates against sponsor-developed potency assay transfer bottlenecks. For New Entrants and Emerging Players: Launch via self-amplifying RNA convergence platforms that leverage existing mRNA infrastructure without proportional capital requirements, targeting mid-scale manufacturing gaps. Penetrate the India CDSCO export incentive corridor for cost-sensitive vaccine markets underserved by incumbent Western CDMOs. White-space opportunity sits with personalized neoantigen vaccine process development, where small-batch high-changeover capabilities remain scarce among traditional biologics manufacturers. For Investors and Strategic Acquirers: FDA real-time release testing guidance adoption is the leading indicator that CDMOs with established process analytical technology infrastructure will capture disproportionate late-stage sponsor preference. Long-term viability favors platform-integrated service providers spanning IVT-to-LNP workflows over fragmented single-service vendors. Acquisition targets should demonstrate validated end-to-end manufacturing capabilities with embedded capacity reservation contracts extending through the mid-term horizon.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Year Platform Partnership | Embedded capacity reservation clauses through 2028 lock in dedicated suite allocation for approved COVID-19 franchise manufacturers. |
| Geographic Manufacturing Expansion | Japan PMDA GMP audit history creation captures first-mover advantage ahead of domestic biopharma pipeline maturation. |
| Continuous Manufacturing Validation | Integrated perfusion-based IVT systems entering commercial phases displace batch-process dominance in nucleic acid production. |
| Microfluidic LNP Platform Adoption | Polydispersity indices below 0.1 at throughputs exceeding 10 liters per hour compress formulation development timelines for oncology candidates. |
| Plasmid DNA Supply Security | Captive CDMO relationships secure raw material continuity against GMP-grade pDNA production scarcity in North American and European facilities. |
Research Methodology
Independent corroboration across primary interviews with drug development executives, regulatory affairs leads, CDMO procurement managers, and analytical testing directors underwrites the qualitative findings in this study. Secondary validation draws from FDA Center for Biologics Evaluation and Research filings, EMA nucleic acid GMP guideline drafts, ClinicalTrials.gov pipeline tracking, and Swissmedic inspection reports. Bottom-up service-type demand modeling and top-down market sizing triangulate volume and value estimates.
Comparable-period anchoring to historical commercial production capacity allocations and platform partnership announcement patterns structures the projection horizon across the analysis window. Segmentation dimensions include service type, technology platform, end-user procurement sophistication, and product-type therapeutic application, with regional regulatory cluster effects modeled separately. CAGRs derive from fitted growth curves incorporating sponsor pipeline maturation rates, CDMO qualification investment cycles, and enzyme supply capacity expansion timelines.
Regulatory harmonization delays, chromatography resin input cost volatility, and aseptic processing workforce scarcity are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumption sets around sponsor consolidation behavior and platform standardization adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Oncolytic Adenovirus Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Engineered T Cells Market