
 Hemophilia Gene Therapy Market | 2026-2036
Hemophilia Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Hemophilia Gene Therapy Market Outlook
The patient base for hemophilia gene therapy is broadening beyond traditional academic medical centers toward community hematology clinics and integrated health networks. BioMarin Pharmaceutical Inc. leverages its established rare disease commercial infrastructure to anchor access in Western markets, while Spark Therapeutics, Inc. competes through deep manufacturing expertise in adeno-associated virus production. Pfizer Inc. sustains scale advantages via its global distribution footprint and payer negotiation capabilities.
Hemophilia gene therapy delivers functional clotting factor genes via viral or non-viral vectors to correct inherited bleeding disorders, typically using adeno-associated virus serotypes engineered for liver tropism and sustained factor VIII or IX expression. Adeno-Associated Virus vectors currently dominate clinical pipelines due to established safety profiles and durable transgene expression, though CRISPR-Cas9 approaches are attracting investment for their potential to eliminate immunogenicity risks associated with viral delivery. Intravenous administration remains the standard delivery mode in approved and late-stage programs, while subcutaneous alternatives are gaining research attention for their outpatient convenience and reduced infusion center burden.
FDA, EMA, and PMDA each maintain distinct expedited review frameworks for gene therapies, with FDA's Regenerative Medicine Advanced Therapy designation and EMA's PRIME scheme accelerating access timelines while imposing rigorous long-term follow-up requirements. These regulatory structures shape development priorities by rewarding robust durability data and post-marketing surveillance commitments over initial efficacy endpoints. Stakeholders must weigh vector manufacturing capacity constraints against payer willingness to absorb single-administration pricing models as the therapeutic paradigm shifts from chronic prophylaxis toward potential functional cures.
Market Dynamics
Vector manufacturing capacity constraints are compressing commercial timelines as developers race to secure contract development and manufacturing organization slots for adeno-associated virus production ahead of regulatory submissions.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy designation:The expedited review pathway accelerates clinical development timelines for hemophilia gene therapies, reducing regulatory uncertainty for sponsors pursuing liver-directed factor VIII or IX expression programs.
- Non-viral delivery platforms:Lipid nanoparticle and polymer-based vector alternatives are attracting development investment as they promise reduced immunogenicity profiles compared to adeno-associated virus serotypes.
- Specialized hemophilia treatment centers:Concentrated patient populations at United States academic medical centers enable efficient clinical trial recruitment and post-marketing surveillance infrastructure.
Market Restraints
- Plasmid DNA supply concentration:Limited qualified suppliers of GMP-grade plasmid DNA for viral vector production create single-source dependencies that amplify batch failure risks.
- EMA long-term follow-up mandates:Fifteen-year post-authorization safety monitoring requirements impose sustained pharmacovigilance costs that strain developer economics.
- Pre-existing neutralizing antibodies:Natural immunity to common adeno-associated virus serotypes in 30-60% of hemophilia patients excludes substantial portions of the addressable population from approved therapies.
Strategic Opportunities
- Subcutaneous administration routes:Needle-free delivery technologies could expand treatment access beyond infusion center-dependent intravenous protocols.
- Japan's PMDA Sakigake designation:Priority review incentives for regenerative medicines accelerate market entry timelines for novel vector constructs.
- CRISPR-Cas9 in vivo editing:Direct genomic correction approaches may circumvent viral vector immunogenicity entirely, opening treatment to previously excluded patient cohorts.
Industry Challenges
- Vector analytical method standardization:Inconsistent potency assays across manufacturing sites complicate comparability studies and regulatory submissions.
- Gene therapy workforce scarcity:Shortages of viral vector process development specialists and regulatory affairs professionals with advanced therapy product experience constrain operational scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemophilia Gene Therapy Market |
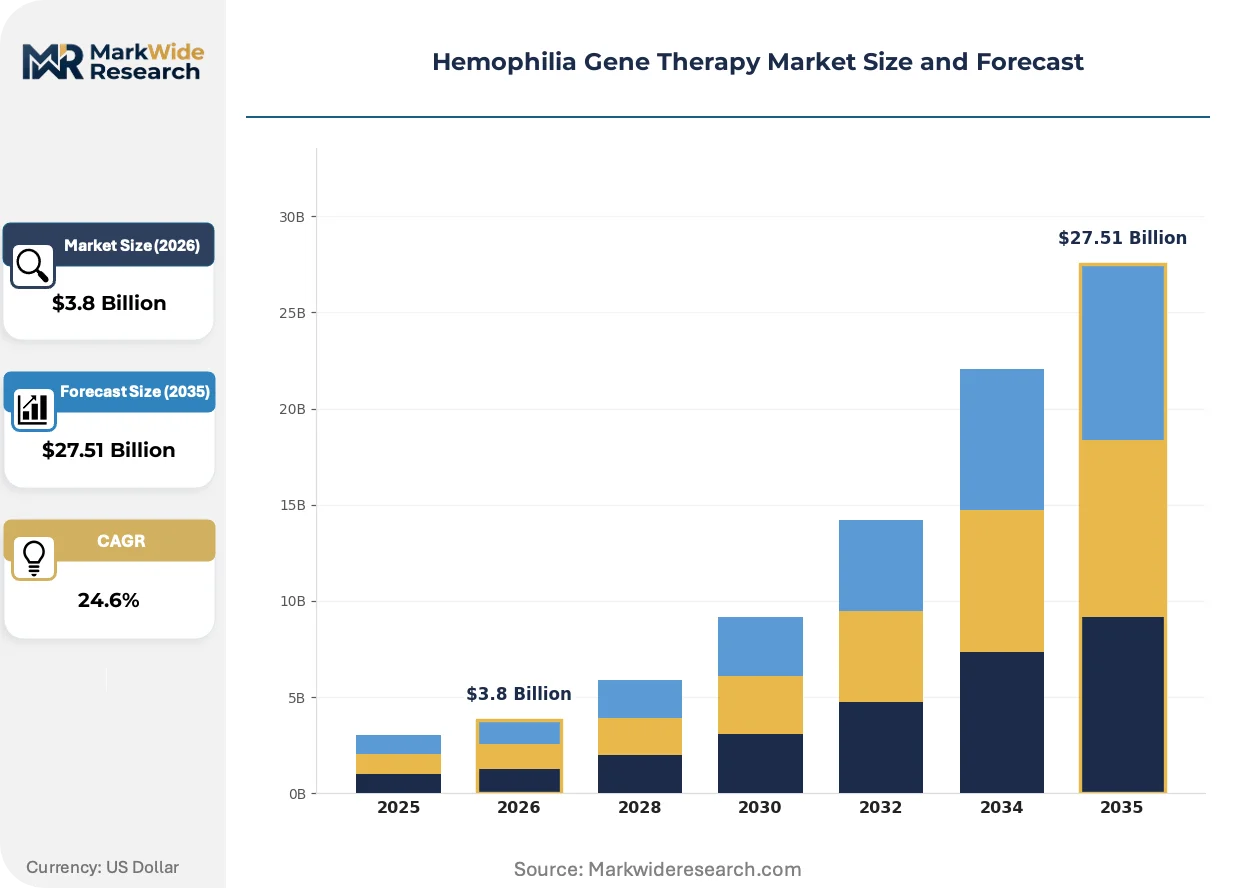
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $27.51 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adeno-Associated Virus, Lentiviral Vector, Sleeping Beauty Transposon, CRISPR-Cas9 Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Local Administration End User: Hospitals, Specialty Clinics, Research Institutions, Patients Therapy Stage: Preclinical, Clinical Trials, Early Commercialization, Post-Marketing |
| Companies Covered | BioMarin Pharmaceutical Inc., Spark Therapeutics, Inc., uniQure N.V., Pfizer Inc., Sangamo Therapeutics, Inc., Ultragenyx, Freeline Therapeutics Holdings plc., CSL Behring, Expression Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemophilia Gene Therapy Market Strategic Shifts
Gene therapy manufacturing is pivoting toward platform standardization as developers seek to amortize facility investments across multiple rare disease indications rather than single-product dedicated lines.
Next-generation adeno-associated virus capsid engineering is converging with machine learning-directed protein design. Biotech developers are deploying artificial intelligence to predict liver tropism and immunogenicity profiles before wet-lab validation. This convergence is compressing preclinical candidate selection timelines from years to months while expanding the universe of serotypes viable for clinical translation.
EMA's PRIME eligibility criteria now explicitly reward manufacturing process robustness alongside clinical efficacy data. Sponsors must demonstrate vector lot-to-lot consistency and supply chain redundancy prior to accelerated assessment. German and French national health technology assessment bodies are incorporating these durability metrics into reimbursement negotiations, shifting commercial focus from initial approval toward sustained expression evidence.
Payer contracting for hemophilia gene therapy is fragmenting across single-administration pricing and annuity-based models. United States commercial insurers and Medicaid programs are piloting outcomes-based arrangements that tie reimbursement to sustained factor expression levels. Germany's statutory health insurance funds are negotiating indication-specific budgets that cap total gene therapy expenditure within hemophilia care pathways.
Hemophilia Gene Therapy Market Segmentation
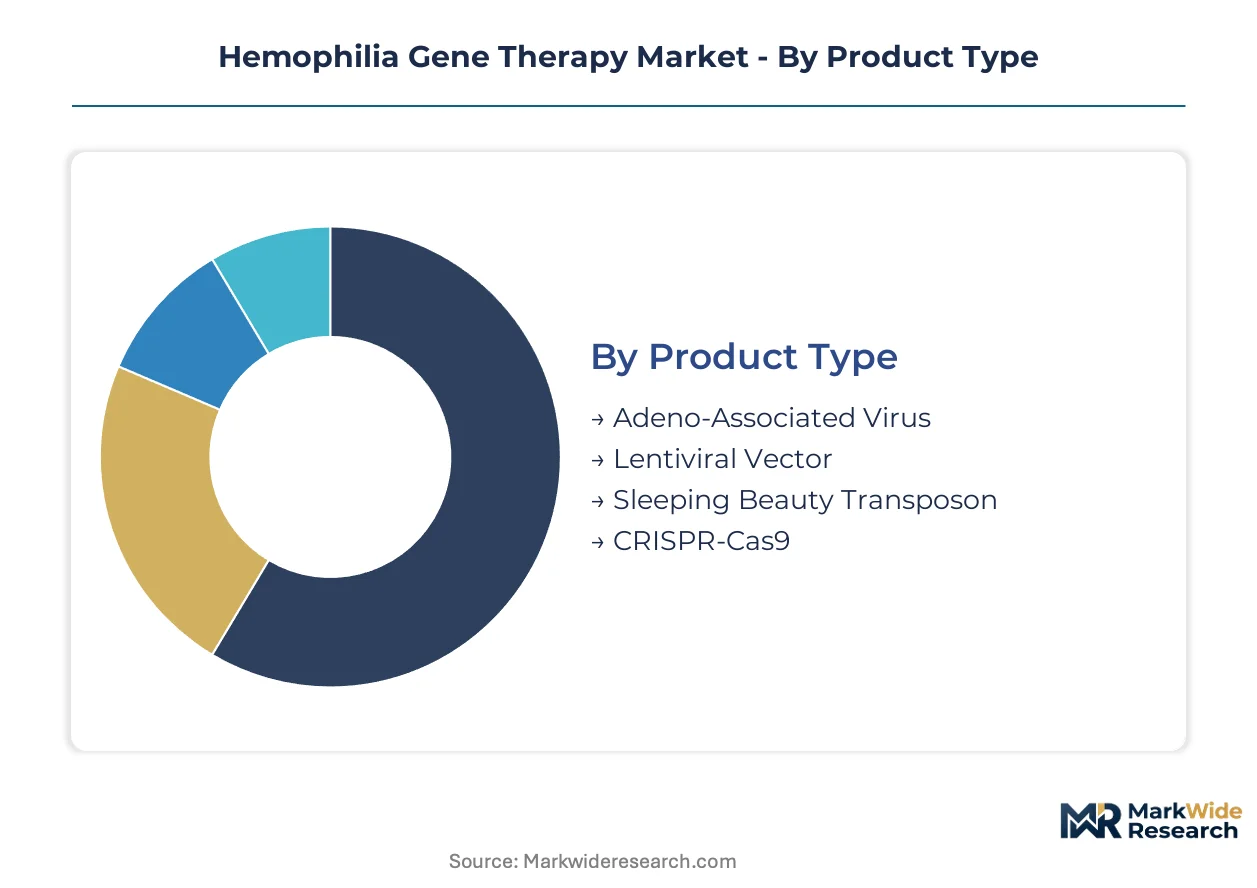
Segmentation in hemophilia gene therapy reveals how vector engineering choices, administration logistics, and care setting economics determine commercial viability. Each dimension carries distinct regulatory, reimbursement, and manufacturing implications that shape developer resource allocation.
Product Type:
Integration depth varies sharply across vector platforms, with some functioning as standalone episomal systems while others require chromosomal embedding for durable expression.
- Adeno-Associated Virus:Episomal vectors engineered for liver tropism dominate approved and late-stage pipelines. United States academic medical centers currently concentrate demand for serotype 5 and 8 variants, though pre-existing neutralizing immunity in 30-60% of patients creates access barriers that capsid engineering programs aim to solve.
- CRISPR-Cas9:Direct genomic editing platforms circumvent viral immunogenicity entirely by integrating functional factor VIII or IX genes directly into host chromosomes. German research institutions are driving early demand for in vivo liver-directed approaches that promise permanent correction without vector redosing limitations.
- Lentiviral Vector:Integrating retroviral systems enable stable transgene expression through chromosomal insertion, primarily in ex vivo hematopoietic stem cell applications.
- Sleeping Beauty Transposon:Non-viral DNA delivery systems use transposase enzymes for genomic integration, attracting investment for reduced manufacturing complexity compared to viral platforms.
Adeno-Associated Virus leads volumes today; CRISPR-Cas9 is gaining share fastest.
Delivery Mode:
Cost tier stratification separates hospital-based infusion center models from outpatient administration alternatives that reduce facility overhead.
- Intravenous:Hepatic vein infusion via peripheral or central venous access remains the standard for approved adeno-associated virus therapies. Japan's PMDA has streamlined review pathways specifically for intravenous liver-directed programs, concentrating near-term commercial investment in this administration class.
- Subcutaneous:Needle-free delivery technologies promise to shift treatment from infusion centers to outpatient settings. United States integrated health networks are piloting subcutaneous protocols to reduce per-patient facility costs and expand community hematology clinic access.
- Intramuscular:Direct muscle injection targets localized factor expression, primarily in early-stage research for hemophilia B muscular delivery.
- Local Administration:Site-specific vector delivery to joints or surgical fields addresses acute bleeding complications rather than prophylactic correction.
Intravenous administration anchors current revenue; subcutaneous alternatives are climbing the fastest as outpatient economics improve.
End User:
Customer type segmentation reflects divergent purchasing authority across institutional buyers, with volume concentration shifting from academic centers toward community networks.
- Specialty Clinics:United States hemophilia treatment centers historically concentrated gene therapy access due to infusion infrastructure and long-term follow-up capabilities. These centers now face patient volume pressure as integrated health networks build competing administration capacity.
- Hospitals:Academic medical centers maintain dominance for complex cases requiring surgical backup and intensive monitoring. German university hospitals anchor European commercialization through EMA-mandated pharmacovigilance infrastructure.
- Research Institutions:Early-phase clinical trial sites drive precommercial vector demand and investigator-initiated studies.
- Patients:Direct-to-patient administration models remain experimental, contingent on subcutaneous delivery maturation and home healthcare reimbursement.
Specialty clinics lead volumes today; hospitals are expanding share fastest through integrated network consolidation.
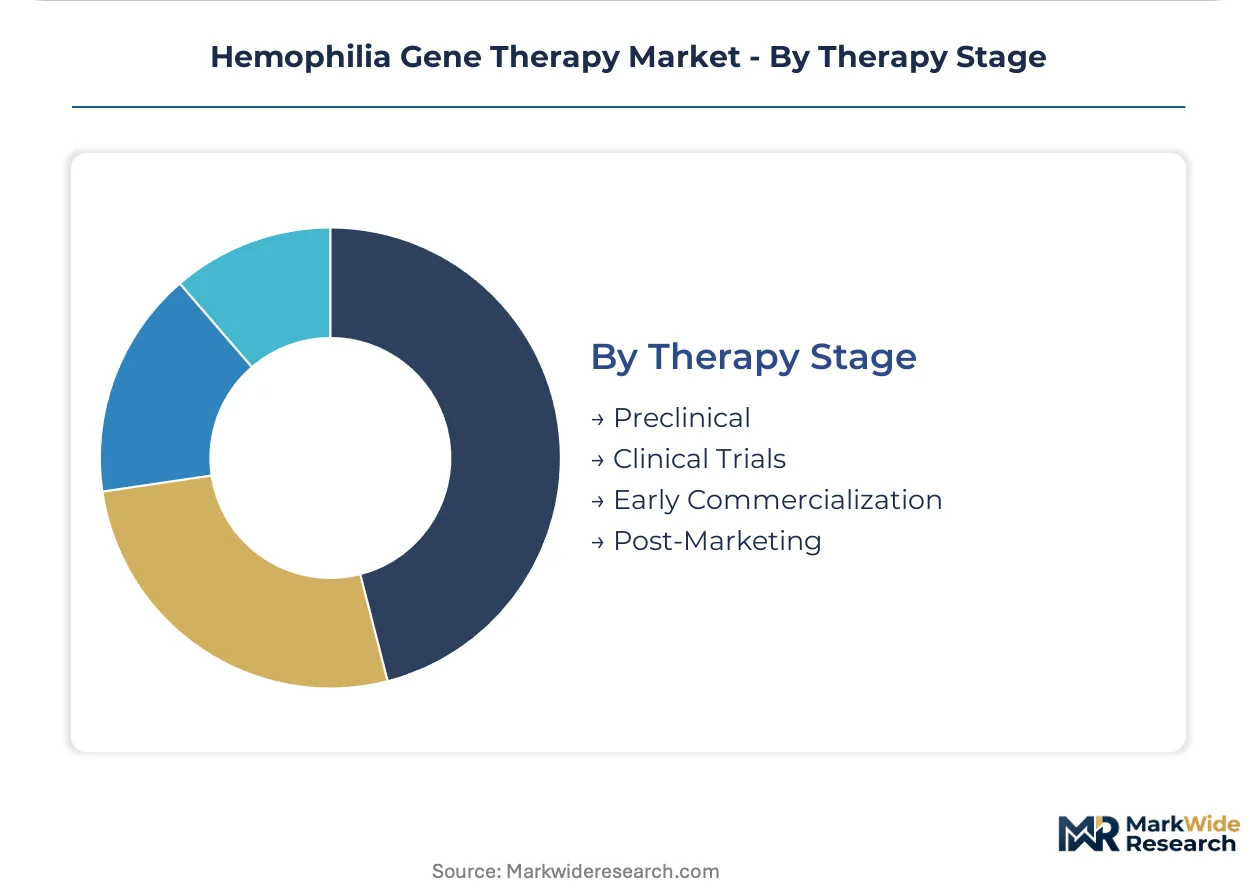
Therapy Stage:
Maturity stratification separates development-phase manufacturing from commercial-scale production, with margin profiles inverting as programs advance.
- Clinical Trials:Phase I-III programs consume the majority of current good manufacturing practice vector capacity. United States contract development and manufacturing organizations report 18-24 month booking backlogs for clinical-grade adeno-associated virus production.
- Post-Marketing:Commercial supply chains face EMA fifteen-year follow-up mandates that sustain pharmacovigilance revenue streams. Japan's PMDA Sakigake-designated products are entering this phase with accelerated review benefits converting to sustained market exclusivity.
- Preclinical:Research-grade vector supply supports candidate selection and toxicology studies ahead of investigational new drug filings.
- Early Commercialization:Initial approved indications face payer negotiation delays and manufacturing scale-up challenges before volume expansion.
Clinical trials lead volumes today; post-marketing stages are gaining share fastest as prior approvals mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States concentrates more hemophilia gene therapy clinical trials than Germany and Japan combined, yet reimbursement fragmentation creates divergent commercial trajectories across these three markets.
United States
Academic medical centers in Boston and Philadelphia drive patient recruitment for liver-directed factor VIII programs. FDA's Regenerative Medicine Advanced Therapy designation compresses review timelines for sponsors demonstrating sustained expression data. The Research Triangle in North Carolina anchors contract manufacturing capacity for clinical-grade adeno-associated virus production.
Germany
Statutory health insurance funds negotiate indication-specific budgets that cap total gene therapy expenditure within hemophilia care pathways. EMA's fifteen-year post-authorization safety monitoring mandates sustain pharmacovigilance infrastructure at university hospitals in Munich and Heidelberg. The Rhine-Main cluster around Frankfurt concentrates viral vector process development specialists.
Japan
PMDA's Sakigake designation for regenerative medicines accelerates market entry timelines for novel vector constructs targeting hemophilia B. The Kanto region surrounding Tokyo hosts specialized hemophilia treatment centers with long-term follow-up capabilities. Osaka-based research institutions pilot subcutaneous delivery protocols to reduce infusion center dependency.
United Kingdom
NHS England's specialized commissioning framework evaluates gene therapy cost-effectiveness against lifetime prophylaxis expenditure for severe hemophilia patients. The Medicines and Healthcare products Regulatory Agency aligns post-marketing surveillance requirements with EMA standards. London and Cambridge anchor early-phase clinical trial sites for CRISPR-Cas9 editing approaches.
Switzerland
Swissmedic maintains distinct expedited review pathways for advanced therapy medicinal products with curative intent. Basel's pharmaceutical cluster supports vector manufacturing technology transfer from research institutions to commercial production. Zurich university hospitals coordinate pan-European pharmacovigilance data collection for liver-directed gene therapies.
Hemophilia Gene Therapy Market Competitive Environment
United States producers anchor one tier; European specialists hold manufacturing process advantages in viral vector platforms. The market structure consolidates around rare disease commercial infrastructure and contract manufacturing capacity. Three archetypes dominate: integrated pharmaceutical conglomerates with global distribution networks, pure-play gene therapy developers with deep vector expertise, and emerging biotechs pursuing non-viral delivery platforms. Capacity expansion and strategic partnerships constitute the primary competitive moves as developers secure limited CDMO slots ahead of regulatory submissions.
Within the integrated pharmaceutical tier, Pfizer Inc. occupies a position exemplifying scale advantages in payer negotiation and global distribution infrastructure. BioMarin Pharmaceutical Inc. and Spark Therapeutics, Inc. represent the specialized gene therapy developer archetype, with the former leveraging established rare disease commercial footprints and the latter anchoring manufacturing expertise in adeno-associated virus production. These three entities collectively illustrate how vector manufacturing capabilities and reimbursement access determine competitive positioning in this market.
| Leading Market Players |
|---|
| BioMarin Pharmaceutical Inc. |
| Spark Therapeutics, Inc. |
| uniQure N.V. |
| Pfizer Inc. |
| Sangamo Therapeutics, Inc. |
| Ultragenyx |
| Freeline Therapeutics Holdings plc. |
| CSL Behring |
| Expression Therapeutics |
| Others |
Value Chain & Pricing Dynamics
EMA's fifteen-year post-authorization safety monitoring mandate gates both qualified vector supply and premium-tier pricing access for hemophilia gene therapies, as developers must embed sustained pharmacovigilance costs into single-administration pricing models while securing GMP-certified manufacturing slots.
Pricing Analysis
Capacity additions in the United States are reshaping price floors for clinical-grade adeno-associated virus production as contract development and manufacturing organizations expand bioreactor footprints. Pricing stratifies across premium, standard, and economy tiers based on vector serotype rarity and lot release testing rigor. Cost compression in standard-tier AAV production is intensifying because CDMO booking backlogs extend eighteen to twenty-four months. Community hematology clinics exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers demonstrate lowest sensitivity given bundled research funding.
Supply Chain Analysis
Regional distribution centers for gene therapy vectors concentrate around Boston, Philadelphia, and the Research Triangle in hub-and-spoke patterns radiating toward specialty clinics. Plasmid DNA supply draws from qualified United States, German, and Japanese GMP facilities with limited second-source alternatives. Single-source vulnerability in serotype-specific capsid production amplifies batch failure risks across clinical programs. Distribution runs through cold-chain logistics networks tethered to infusion center infrastructure with validated chain-of-custody protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hemophilia gene therapy functions as a regulatory compounder where FDA's Regenerative Medicine Advanced Therapy designation accelerates clinical development timelines and concentrates demand among sponsors demonstrating durable expression data.
For Market Incumbents: Extend manufacturing platform standardization across multiple rare disease indications to amortize facility investments and defend against emerging non-viral delivery competitors. Secure captive plasmid DNA supply through backward integration into GMP-grade raw material production. Prioritize EMA PRIME eligibility to anchor European reimbursement negotiations. For New Entrants and Emerging Players: Community hematology clinics represent an underserved buyer archetype with limited gene therapy access due to infusion center dependency. Subcutaneous delivery protocols offer the most penetrable administration segment for outpatient expansion. Pursue partnerships with United States integrated health networks to bypass academic medical center concentration. For Investors and Strategic Acquirers: Roll-up economics work for pure-play gene therapy developers because vector manufacturing capacity scarcity creates acquisition premiums for CDMO-accessible pipelines. Five-to-ten year viability hinges on CRISPR-Cas9 platform maturation displacing viral immunogenicity constraints. Monitor PMDA Sakigake designation conversion rates as inflection indicators for Japanese market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDMO capacity expansion in the Research Triangle reduces clinical program queue times for AAV production. |
| Regulatory Approval Pathway | FDA Regenerative Medicine Advanced Therapy designation compresses review timelines for liver-directed factor programs. |
| Pipeline Diversification | CRISPR-Cas9 platform investment circumvents pre-existing neutralizing antibody exclusions in thirty to sixty percent of patients. |
| Licensing Agreement | Subcutaneous delivery technology licensing shifts treatment economics from infusion centers toward outpatient settings. |
| Reimbursement Strategy | Outcomes-based contracting with United States commercial insurers ties payment to sustained factor expression levels. |
Study Parameters
Direct dialogue with gene therapy development executives, regulatory affairs leads, formulary directors at major payers, and hospital procurement managers grounded this analysis, cross-validated against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases through bottom-up and top-down triangulation.
Bottom-up modeling segmented the market across vector platform, delivery mode, end-user institution type, and therapy stage, while top-down validation anchored aggregate demand to epidemiological prevalence data and treatment center capacity. CAGRs were derived from vector manufacturing expansion timelines and regulatory approval velocity across the analysis window. Forecast inputs incorporated CDMO booking backlogs and payer negotiation patterns specific to single-administration gene therapy pricing.
Underlying measurement precision varies by segment; approved AAV therapies and late-stage clinical programs carry tighter precision than preclinical CRISPR-Cas9 approaches. Forecasts reflect documented assumptions regarding vector durability evidence and post-marketing surveillance compliance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Cord Blood Banking Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Stem Cell Therapy Market