
 Oncolytic Virus Cancer Therapy Market | 2026-2036
Oncolytic Virus Cancer Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Oncolytic Virus Cancer Therapy Market Outlook
North American biotech manufacturing is expanding its viral vector production footprint to serve late-stage oncolytic virus pipelines. Amgen leverages its established biologics infrastructure to support commercial-scale manufacturing of engineered herpes simplex virus platforms. Replimune sustains a differentiated position through its proprietary HSV-1 backbone designed for systemic delivery and potent immunogenicity. Oncolytics Biotech anchors its competitive profile in the pelareorep program, targeting metastatic breast and pancreatic malignancies through selective viral replication in Ras-activated tumor cells.
Oncolytic virus cancer therapy employs replication-competent viral vectors that selectively infect and lyse malignant cells while triggering systemic anti-tumor immune responses through pathogen-associated molecular pattern signaling and dendritic cell activation. These therapeutics are manufactured through adherent or suspension cell culture systems using HEK293, Vero, or producer cell lines, with downstream purification via chromatography and filtration to achieve clinical-grade titers exceeding 10^10 infectious units per dose. Virotherapy occupies the largest commercial segment due to the established reimbursement pathway for T-VEC in melanoma, while combination therapy with immune checkpoint inhibitors represents the fastest-expanding category as trials demonstrate enhanced objective response rates. Hospitals dominate the end-user landscape owing to the requirement for specialized interventional radiology and surgical oncology capabilities for intratumoral administration.
The FDA's breakthrough therapy designation and the EMA's PRIME scheme compress regulatory timelines for oncolytic virus candidates, while the FDA's CBER maintains stringent requirements for replication-competent virus shedding studies and environmental risk assessments. China's NMPA has issued technical guidelines for gene therapy products that encompass oncolytic viruses, mandating extended pharmacovigilance for viral persistence and latency. Japan's PMDA operates under the Sakigake designation system, which prioritizes review for regenerative medicine and gene therapy products including oncolytic platforms. Stakeholders must monitor evolving biosafety containment standards and regional divergence in gene therapy reimbursement policy as these factors will determine viable market entry sequencing.
Market Dynamics
The FDA's accelerated approval pathway for breakthrough gene therapies compresses development timelines for engineered viral vectors while academic medical centers scale adoptive infrastructure for intratumoral delivery protocols.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's accelerated review pathway compresses clinical development timelines for oncolytic virus candidates demonstrating substantial improvement over existing therapies.
- Combination Immunotherapy Protocols:Immune checkpoint inhibitor integration with virotherapy enhances objective response rates in melanoma and solid tumor indications.
- China:The NMPA's technical guidelines for gene therapy products provide regulatory clarity for oncolytic virus developers seeking market authorization.
Market Restraints
- Manufacturing Scale Constraints:Viral vector production requires specialized adherent or suspension cell culture systems with limited global contract manufacturing capacity.
- Intratumoral Administration Complexity:The requirement for interventional radiology and surgical oncology capabilities restricts site selection and patient access.
- EMA PRIME Scheme Variability:Divergent national reimbursement policies across EU member states create market access fragmentation for approved therapies.
Strategic Opportunities
- Systemic Delivery Platforms:Engineered HSV-1 backbones designed for intravenous administration expand addressable patient populations beyond injectable lesions.
- Germany:Concentration of Phase II and Phase III clinical trial sites creates partnership opportunities for late-stage asset development.
- PMDA Sakigake Designation:Japan's priority review system for regenerative medicine and gene therapy products accelerates regulatory timelines for first-in-class candidates.
Industry Challenges
- Biosafety Containment Expertise:Replication-competent virus shedding studies and environmental risk assessments require specialized facilities with limited qualified personnel.
- Pharmacovigilance Infrastructure:Extended monitoring for viral persistence and latency demands longitudinal patient tracking systems that strain post-market surveillance capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oncolytic Virus Cancer Therapy Market |
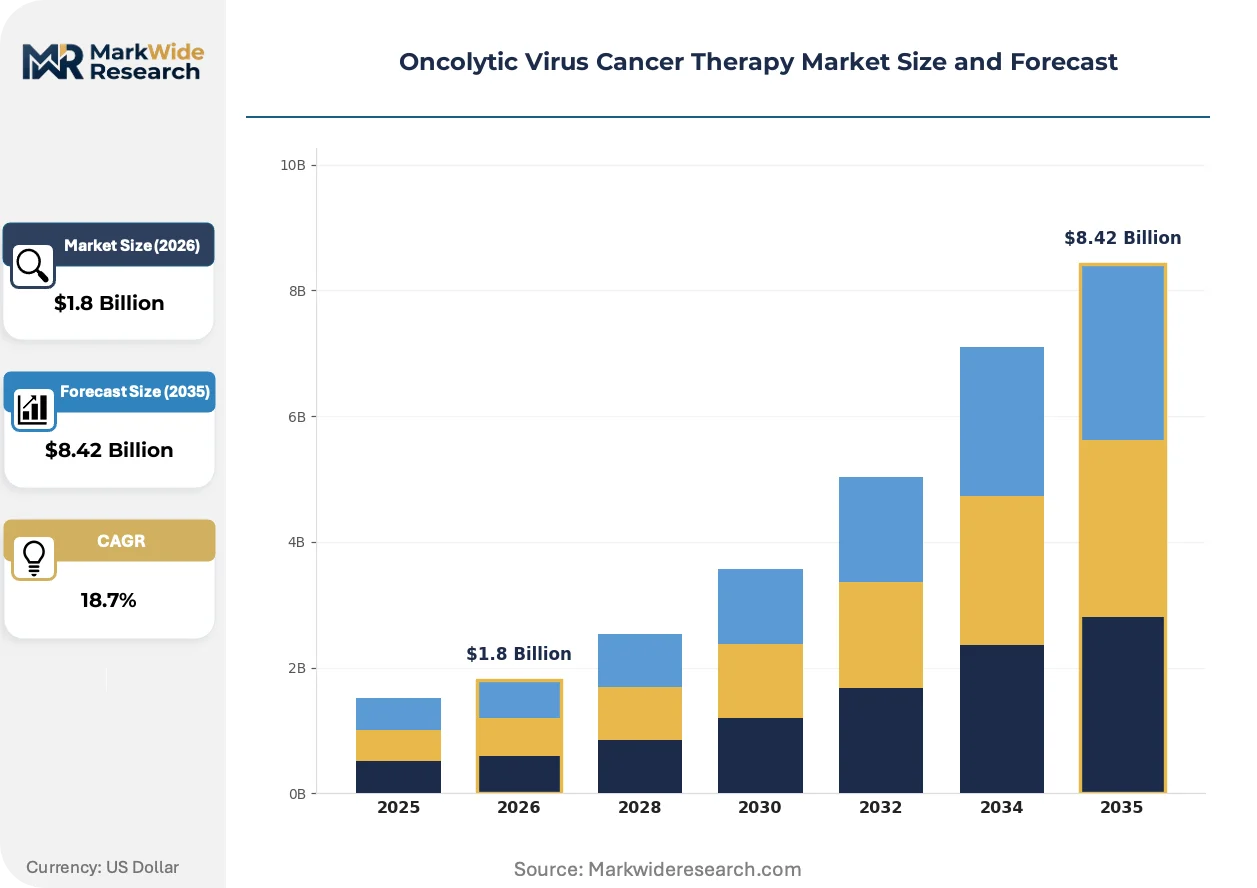
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Virotherapy, Combination Therapy, Monotherapy, Gene Therapy Technology: Transduction, Transfection, Electroporation, Oncolytic Vaccines End User: Clinics, Research Laboratories, Hospitals, Treatment Centers Treatment Stage: Adjuvant, Neoadjuvant, Palliative, Maintenance |
| Companies Covered | Amgen, Oncolytics Biotech, Transgene SA, Replimune, Genelux Corporation, Takara Bio, Candel Therapeutics, TILT Biotherapeutics, Targovax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oncolytic Virus Cancer Therapy Market Strategic Shifts
Engineered viral vector platforms are actively reshaping therapeutic possibilities through selective tumor cell replication mechanisms and potent immunogenicity triggers.
Next-generation HSV-1 backbones is consolidating competitive positioning among developers pursuing systemic delivery routes. Academic medical centers in the United States are adopting these platforms for Phase II combination trials with checkpoint inhibitors. This consolidation is compressing the development gap between intratumoral and intravenous administration paradigms.
REACH compliance requirements for viral vector manufacturing materials are tightening supplier qualification standards across European production networks. EMA's PRIME scheme is accelerating quality-by-design implementation for oncolytic virus processes. Contract manufacturers in Germany and Switzerland are responding by investing in closed-system bioreactor infrastructure.
Hospital procurement of virotherapy is increasingly bundling interventional radiology services with surgical oncology capabilities to capture comprehensive episode-of-care reimbursement. Specialized cancer centers are displacing general oncology practices as the primary administration sites for T-VEC and pipeline candidates. This concentration is most visible in United States academic medical centers with established immuno-oncology programs.
Oncolytic Virus Cancer Therapy Market Segmentation
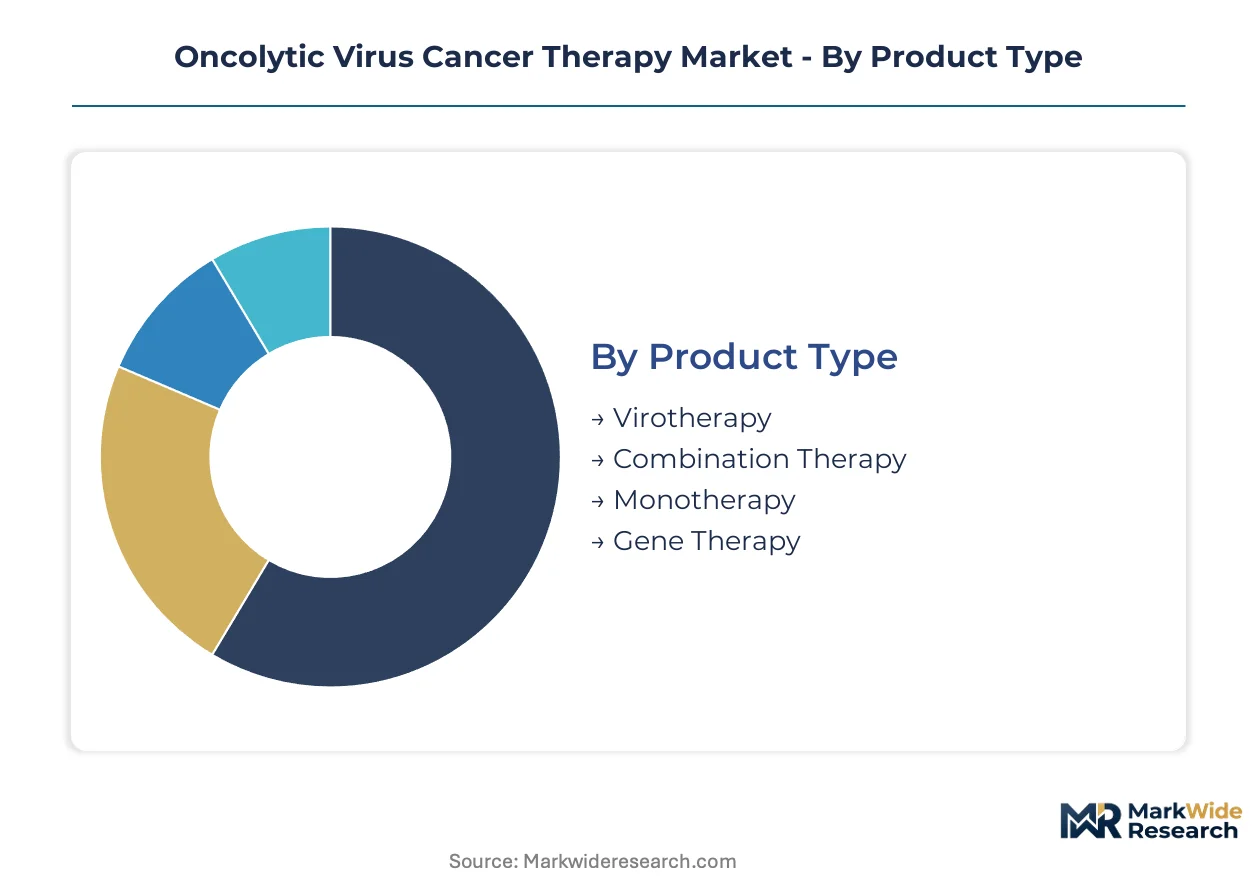
Oncolytic virus cancer therapy segments diverge sharply between established reimbursement pathways and experimental protocols. Product type and end-user concentration determine manufacturing scale, regulatory strategy, and commercial infrastructure requirements across development pipelines.
Product Type:
Virotherapy commands premium pricing through validated reimbursement codes, while combination therapy segments scale through volume expansion in immuno-oncology protocols.
- Virotherapy:Replication-competent viral vectors including T-VEC deliver selective tumor cell lysis with established FDA approval pathways. Demand concentrates in United States melanoma treatment centers leveraging existing interventional radiology infrastructure for intratumoral administration.
- Combination Therapy:Oncolytic virus platforms integrated with immune checkpoint inhibitors demonstrate enhanced objective response rates in Phase II solid tumor trials. Deployment is accelerating fastest in academic medical centers across Germany and China pursuing systemic delivery protocols.
- Monotherapy:Single-agent viral vectors without immunomodulatory payloads occupy niche indications with limited combination eligibility.
- Gene Therapy:Engineered viral backbones incorporating transgenes for immune stimulation remain predominantly preclinical with specialized manufacturing requirements.
Mature deployment sits with virotherapy. Newer deployment is concentrated in combination therapy.
Technology:
Delivery mechanism selection determines manufacturing complexity, dose consistency, and regulatory validation burden across viral vector platforms.
- Transduction:Viral-mediated gene transfer using engineered HSV-1 or adenoviral vectors enables stable genomic integration with high efficiency. United States contract manufacturers specializing in adherent cell culture systems capture demand from late-stage clinical developers.
- Electroporation:Electrical pulse-mediated membrane permeabilization supports plasmid DNA delivery with reduced immunogenicity concerns. Adoption is climbing fastest in European research laboratories optimizing ex vivo cell modification protocols.
- Transfection:Chemical-mediated nucleic acid entry serves early-stage discovery with limited clinical translation due to efficiency variability.
- Oncolytic Vaccines:Viral vector platforms engineered for antigen presentation function primarily in preclinical immunotherapy development.
Established clinical infrastructure supports transduction. Emerging applications favor electroporation.
End User:
Site-of-care capabilities dictate patient access, reimbursement capture, and administration protocol standardization across delivery settings.
- Hospitals:Comprehensive cancer centers with embedded interventional radiology and surgical oncology departments administer intratumoral virotherapy under episode-of-care reimbursement. United States academic medical centers with immuno-oncology programs anchor demand concentration.
- Treatment Centers:Specialized outpatient facilities focused on infusion therapy and radiation oncology are gaining share fastest for systemic delivery candidates in Phase III development.
- Clinics:Community oncology practices face capability constraints for complex viral vector administration and biosafety containment.
- Research Laboratories:Academic and contract research organizations support preclinical and early-phase clinical manufacturing with limited direct patient contact.
Volume concentration rests with hospitals. Capability expansion is shifting toward treatment centers.
Treatment Stage:
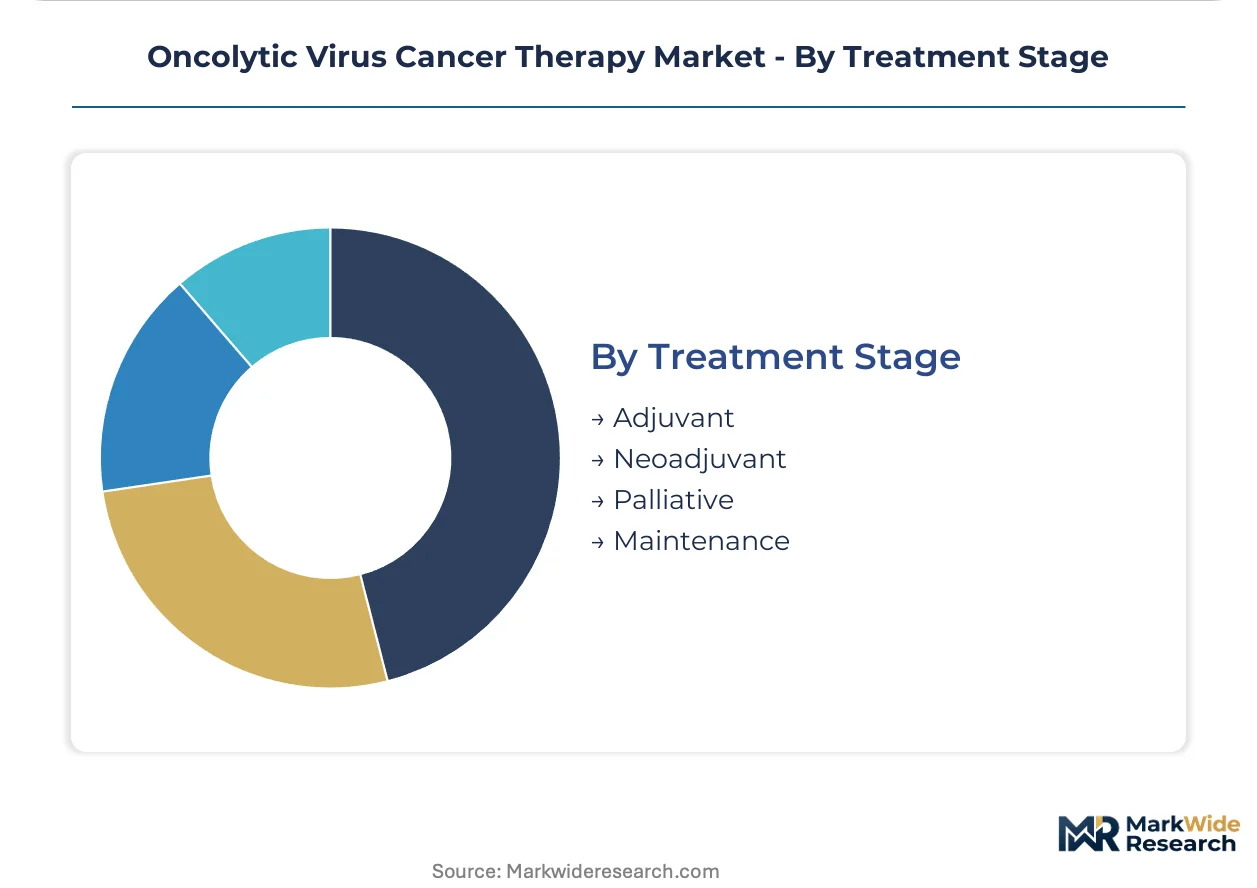
Clinical integration point determines patient eligibility, combination therapy options, and endpoint validation requirements across regulatory pathways.
- Neoadjuvant:Pre-surgical virotherapy administration enables tumor debulking and immune priming with pathological complete response endpoints. China's NMPA technical guidelines for gene therapy products are accelerating trial design in this segment.
- Palliative:Symptom-focused oncolytic virus deployment in advanced malignancies leverages quality-of-life endpoints with streamlined regulatory requirements.
- Adjuvant:Post-surgical viral vector administration for residual disease eradication faces endpoint validation challenges in solid tumor indications.
- Maintenance:Extended dosing protocols for remission prolongation require longitudinal viral shedding monitoring and pharmacovigilance infrastructure.
Regulatory clarity favors neoadjuvant. Access expansion is concentrating in palliative.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Viral vector manufacturing clusters anchor geographic demand concentration for oncolytic virus therapies. Academic medical centers with immuno-oncology programs and specialized interventional radiology capabilities drive site-of-care infrastructure investment across leading markets.
United States
FDA breakthrough therapy designations and CBER's accelerated pathways compress development timelines for engineered viral vectors. The agency mandates stringent replication-competent virus shedding studies and environmental risk assessments for all candidates. Academic medical centers in Boston, Houston, and San Francisco anchor intratumoral delivery protocol adoption with embedded surgical oncology departments.
Germany
EMA's PRIME scheme accelerates quality-by-design implementation for oncolytic virus manufacturing processes. REACH compliance requirements tighten supplier qualification standards for viral vector production materials. Contract manufacturers in Munich and Basel respond with closed-system bioreactor infrastructure investments.
China
NMPA technical guidelines for gene therapy products provide regulatory clarity for oncolytic virus developers seeking market authorization. Extended pharmacovigilance requirements mandate longitudinal tracking for viral persistence and latency. Phase II and Phase III clinical trial sites concentrate in Shanghai and Beijing with state-backed biotechnology park development.
Japan
PMDA operates under the Sakigake designation system prioritizing review for regenerative medicine and gene therapy products. The framework accelerates regulatory timelines for first-in-class oncolytic candidates demonstrating substantial improvement. Tokyo and Osaka host specialized cancer centers with interventional radiology capabilities for intratumoral administration.
Switzerland
Swissmedic maintains alignment with EMA standards while offering streamlined pathways for advanced therapy medicinal products. The regulatory framework supports viral vector manufacturing with stringent biosafety containment requirements. Basel and Zurich anchor contract manufacturing capacity for European late-stage clinical supply.
Oncolytic Virus Cancer Therapy Market Competitive Environment
Global majors compete with regional champions across manufacturing scale and delivery platform specialization. The market structures around three tiers: established biologics manufacturers with viral vector infrastructure, emerging biotechnology firms with proprietary engineered backbones, and specialized contract development organizations. Strategic archetypes include platform technology licensors, integrated end-to-end developers, and manufacturing-focused service providers. Capacity expansion in adherent and suspension cell culture systems dominates competitive moves alongside strategic partnerships for late-stage clinical supply.
Within the integrated developer tier, Amgen leverages established biologics infrastructure to anchor commercial-scale manufacturing capabilities. Replimune occupies a differentiated position through proprietary HSV-1 backbone engineering for systemic delivery routes. Oncolytics Biotech exemplifies the clinical-stage specialist archetype with focused pipeline development in solid tumor indications.
| Leading Market Players |
|---|
| Amgen |
| Oncolytics Biotech |
| Transgene SA |
| Replimune |
| Genelux Corporation |
| Takara Bio |
| Candel Therapeutics |
| TILT Biotherapeutics |
| Targovax |
| Others |
Value Chain & Pricing Dynamics
Virologist concentrations in Boston and Basel drive labor-cost differentials that widen pricing-tier spreads between boutique academic medical centers and high-volume hospital systems. FDA-mandated biosafety containment expertise commands premium compensation, compressing margins for contract manufacturers while sustaining elevated service-bundled pricing for intratumoral delivery protocols.
Pricing Analysis
Episode-of-care bundling separates comprehensive interventional radiology-plus-surgical oncology packages from unbundled administration-only pricing. Three-tier pricing structure across premium academic medical centers, standard comprehensive cancer hospitals, and economy-tier treatment centers reflects certification grade and after-sales pharmacovigilance monitoring intensity. Cost compression in the economy tier is intensifying because community oncology practices lack viral shedding containment infrastructure. Hospital systems with embedded immuno-oncology programs demonstrate lowest price sensitivity, while independent clinics face acute budget constraints for biosafety facility upgrades.
Supply Chain Analysis
GMP certification for replication-competent viral vectors gates supplier qualification, with only United States, German, and Swiss contract manufacturers holding validated adherent and suspension cell culture capacity. HEK293 producer cell lines, chromatography resins, and closed-system bioreactor hardware draw from specialized biotechnology suppliers concentrated in Basel and Boston. Single-source vulnerability in viral vector plasmid supply creates acute exposure for late-stage clinical developers. Distribution runs through cold-chain logistics networks terminating at hospital-based pharmacy compounds with specialized containment infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Viral vector manufacturing capacity scarcity props pricing power for qualified contract manufacturers, with biosafety containment expertise serving as the binding constraint across all development stages.
For Market Incumbents: Deploy backward integration into proprietary producer cell line development to secure supply continuity against emerging platform technology threats from electroporation-based competitors. Capture channel control through exclusive hospital system partnerships for intratumoral administration training and certification investment. Counter margin pressure from REACH compliance cost escalation by consolidating European manufacturing footprints in Basel and Munich. For New Entrants and Emerging Players: Systemic delivery platform engineering offers the most penetrable wedge for addressing metastatic patient populations excluded from intratumoral protocols. Target China's NMPA-regulated trial sites for neoadjuvant indication development, leveraging state-backed biotechnology park infrastructure. Pursue go-to-market positioning through academic medical center licensing rather than direct hospital contracting. For Investors and Strategic Acquirers: Re-rating potential sits with clinical-stage specialists possessing Phase II solid tumor data given FDA breakthrough therapy designation catalysts. Long-term viability hinges on manufacturing scale execution rather than discovery platform differentiation. Watch for PMDA Sakigake designation announcements as the inflection signal for first-in-class systemic delivery candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II combination protocols with checkpoint inhibitors at academic medical centers validate systemic delivery mechanisms. |
| Manufacturing Scale-Up | Closed-system bioreactor investments in Basel and Munich respond to EMA PRIME scheme quality-by-design requirements. |
| Regulatory Approval Pathway | FDA CBER breakthrough therapy designation compresses development timelines for engineered HSV-1 backbones. |
| Licensing Agreement | Platform technology out-licensing to Chinese developers leverages NMPA technical guidelines for gene therapy products. |
| Pipeline Diversification | Ras-activated tumor targeting expands addressable indications beyond melanoma into pancreatic and breast malignancies. |
Study Parameters
FDA filings, ClinicalTrials.gov, and EMA assessment reports formed the secondary backbone, cross-referenced with primary interviews involving regulatory affairs leads, hospital procurement managers, and contract manufacturing executives. Bottom-up and top-down triangulation validated viral vector production capacity estimates and pricing tier boundaries across United States, German, and Chinese market clusters.
Bottom-up modeling anchored volume projections to Phase II and Phase III trial site concentrations, while top-down analysis calibrated value estimates against reimbursement pathway maturity. Segmentation dimensions spanned product type, delivery technology, end-user site capabilities, and treatment stage across the projection horizon. CAGRs derived from patient population eligibility curves and manufacturing capacity expansion timelines, with biosafety containment facility commissioning schedules serving as critical forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen regulatory revocation of breakthrough therapy designations and disruptive platform shifts away from viral vectors toward non-viral delivery systems. Forecasts reflect assumptions regarding sustained reimbursement for T-VEC and comparable virotherapies. A model refresh is warranted upon material change in FDA CBER environmental risk assessment requirements or EMA PRIME scheme eligibility criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market