
 Clean Room Panels Market | 2026-2036
Clean Room Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Room Panels Market Analysis
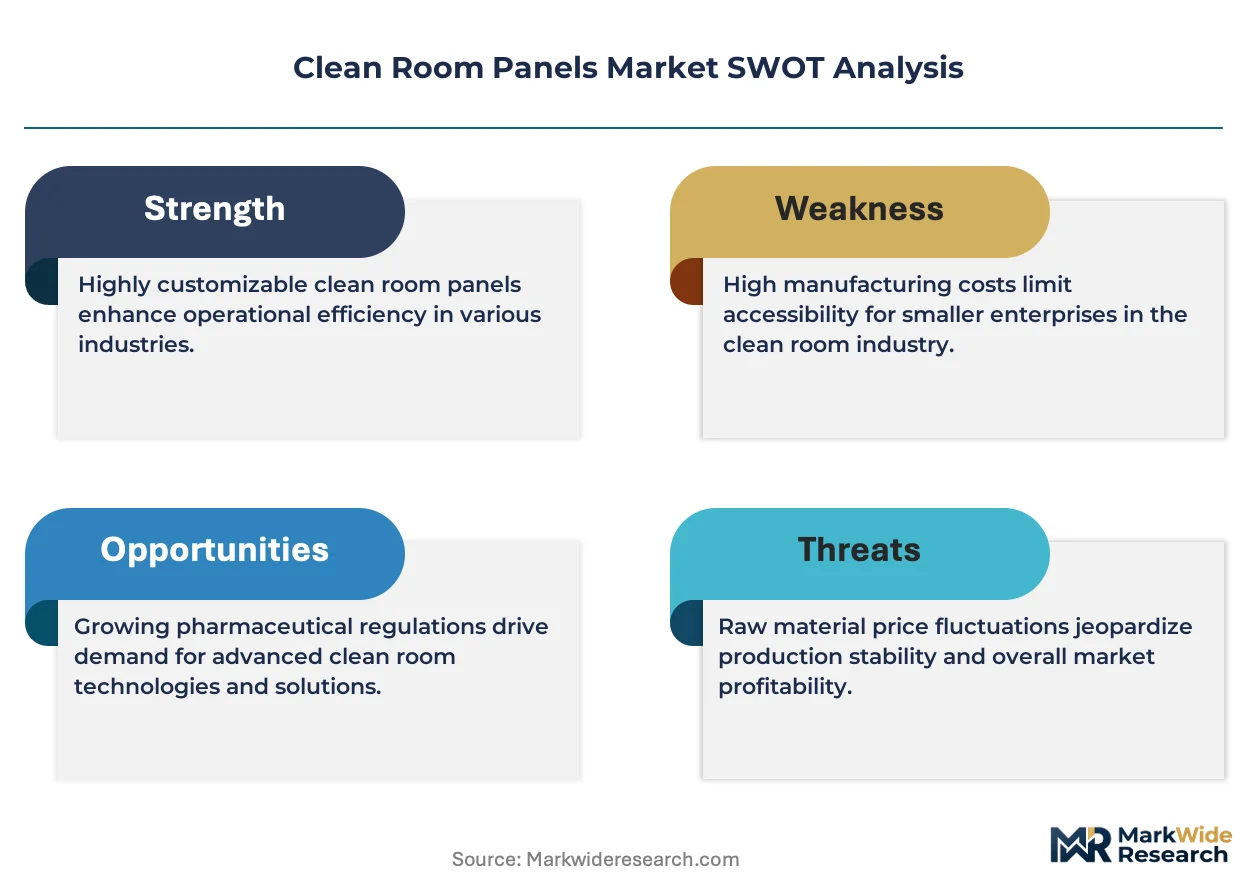
Project finance tied to semiconductor fab buildouts is narrowing the competitive field to firms capable of bonding large-scale contracts. AES Clean Technology leverages its vertical integration across design and installation to sustain margin capture on turnkey pharmaceutical projects. PortaFab Corporation anchors its position through geographic dominance in North American modular cleanroom construction. G-CON Manufacturing differentiates via prefabricated POD systems that compress deployment timelines for biologics manufacturers.
Clean room panels are engineered envelope systems, typically constructed from aluminum honeycomb or steel-faced composites with sealed joint geometries, designed to maintain ISO 14644 classified particulate environments. Their primary purpose is to create hermetically bounded production zones where airborne contamination remains below process-critical thresholds. Modular installations lead demand in biotechnology and semiconductor applications where reconfiguration flexibility protects capital efficiency. Flush panel configurations command premium positioning in pharmaceutical aseptic suites where crevices harbor microbial risk. Demountable systems represent the fastest-growing installation category as contract manufacturers prioritize asset mobility across multi-product facilities.
The EPA enforces particulate emissions frameworks that indirectly elevate clean room integrity requirements in US pharmaceutical operations. EMA's Annex 1 revisions on sterile manufacturing mandate material surfaces that withstand aggressive sanitization protocols. ISO 14644-1 classification standards shape global procurement specifications for panel suppliers seeking cross-border qualification. Stakeholders must monitor how evolving cleanroom classification thresholds in advanced packaging and cell therapy production reshape panel specification roadmaps.
Market Dynamics
Semiconductor fabrication facilities in Taiwan and South Korea are expanding clean room footprints to support advanced node production below 3nm, forcing panel suppliers to scale bonding capacity for hermetic envelope systems that maintain ISO 14644-1 Class 1-3 environments.
Growth Catalysts
- EU F-Gas Regulation:Accelerating replacement cycles for legacy polyurethane-insulated panels as fluorinated gas phaseout mandates drive upgrades to mineral wool and vacuum-insulated alternatives in pharmaceutical manufacturing across Germany, France, and Italy.
- Biologics manufacturing expansion:Cell therapy production facilities in Singapore and Boston are specifying flush-panel aseptic suites to eliminate microbial harborage points, creating specification pull for seamless welded joint geometries.
- Aluminum honeycomb core adoption:Advanced packaging cleanrooms in Hsinchu and Pyeongtaek are prioritizing lightweight, thermally stable panel substrates that reduce structural load while maintaining dimensional integrity across temperature cycling.
Market Restraints
- Aluminum price volatility:Honeycomb core and extrusion framing constitute 35-45% of panel material cost, exposing fabricators to London Metal Exchange aluminum fluctuations that compress margins on fixed-price fab contracts.
- East Asian supply concentration:High-purity aluminum foil and specialized sealant chemistries originate from concentrated Japanese and South Korean chemical suppliers, creating single-source vulnerability for Western panel integrators.
- Legacy silicone sealant incompatibility:Aggressive vapor-phase hydrogen peroxide sterilization protocols in aseptic filling lines degrade conventional gasket materials, forcing premature panel replacement before structural end-of-life.
Strategic Opportunities
- Indian pharmaceutical corridor expansion:Hyderabad and Ahmedabad bulk drug manufacturers are retrofitting existing facilities to meet US FDA and EU EMA audit standards, creating first-mover advantage for panel suppliers offering turnkey qualification documentation.
- Prefabricated POD system convergence:Modular cleanroom units integrating HVAC, electrical, and envelope systems are compressing deployment timelines from 18 months to 8 weeks for contract manufacturing organizations serving multi-product biologics campaigns.
- ISO 14644-2 continuous monitoring mandate:Revised classification standards requiring real-time particulate sensing are driving panel specification toward embedded sensor conduits and power-over-ethernet routing channels.
Industry Challenges
- Cleanroom certification timeline compression:Third-party ISO 14644-1 compliance testing for new semiconductor fabs now demands 72-hour continuous monitoring protocols that extend project handoff schedules and strain commissioning engineer availability.
- Legacy facility retrofit integration:Demountable panel systems must interface with existing structural steel grids and utility matrices designed for permanent construction, requiring custom engineering that erodes modular cost advantages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Room Panels Market |
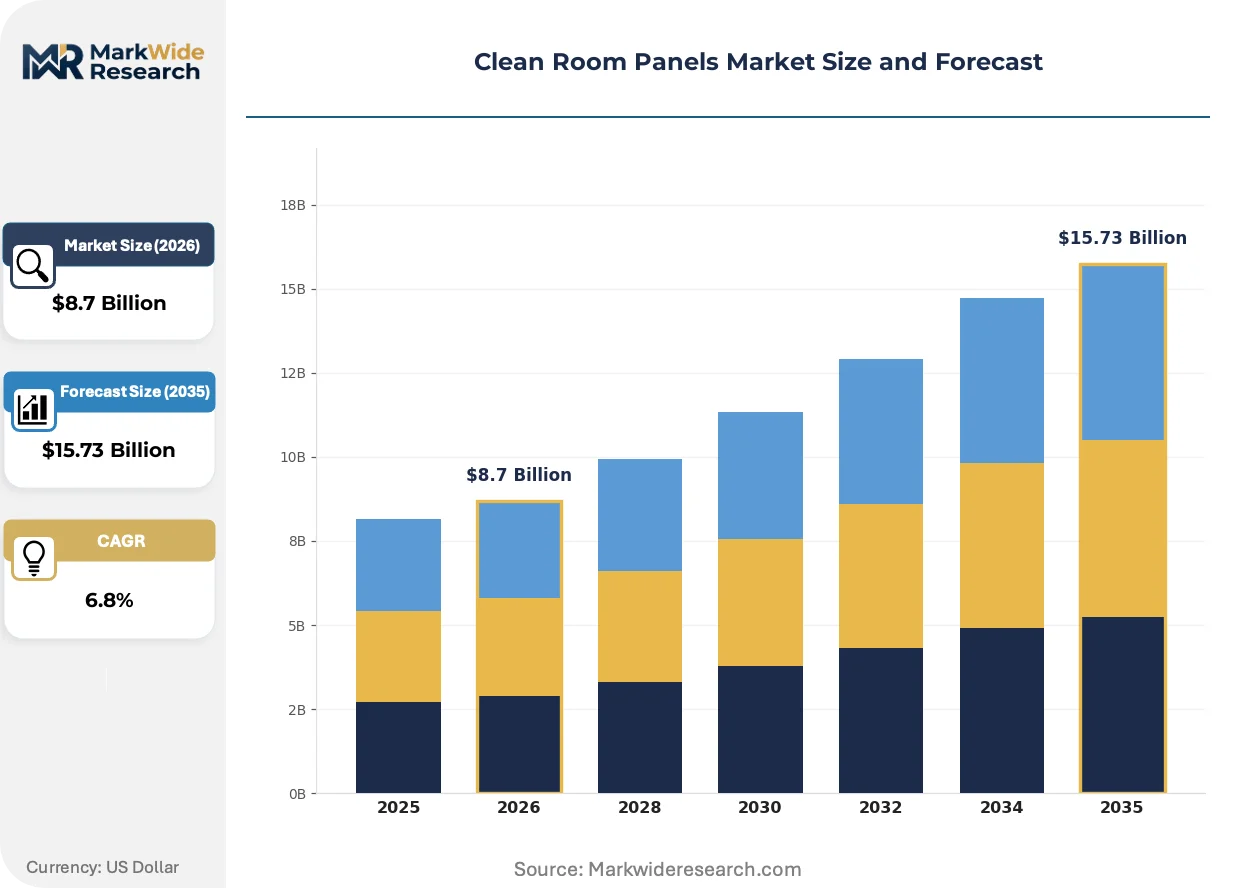
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Flush, Ceiling, Wall Material: Steel, Aluminum, Composite, Vinyl Application: Pharmaceuticals, Biotechnology, Electronics, Aerospace Installation Type: Fixed, Demountable, Portable, Customized |
| Companies Covered | AES Clean Technology, Inc., MRC Cleanrooms, PortaFab Corporation, Pacific Panels Inc., Terra Universal Inc., Plascore, Inc., G-CON Manufacturing, American Cleanroom Systems, Fabtech Technologies International Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Room Panels Market Emerging Trajectories
Panel engineering is pivoting toward active environmental management, with envelope systems evolving from passive barriers to intelligent substrates that integrate sensing, power distribution, and rapid reconfiguration capabilities.
Vacuum-insulated panel technology employing fumed silica core materials and multilayer metallized polymer barriers is rendering obsolete conventional polyurethane foam construction in ultra-low temperature pharmaceutical storage and cryogenic semiconductor process areas. Biologics manufacturers in Basel and Cambridge are specifying these panels for cell banking facilities where thermal bridging compromises batch integrity. The technology compresses envelope thickness by 60% while improving R-value, enabling floorplate efficiency gains in high-rent urban manufacturing locations.
EMA's Annex 1 revision on sterile manufacturing mandates surface materials that withstand repeated application of sporicidal agents including hydrogen peroxide vapor, chlorine dioxide, and peracetic acid. This regulatory pressure is disqualifying painted steel finishes and conventional anodized aluminum in European aseptic filling suites. Panel suppliers are responding with electropolished 316L stainless steel facing and specialized fluoropolymer coatings that maintain surface roughness below 0.8 micrometers Ra after 10,000 sanitization cycles.
Turnkey performance contracting is displacing component procurement for major fab buildouts, with semiconductor manufacturers in Taichung and Yongin bundling panel supply, installation, and ongoing environmental certification under single-source vendor relationships. This model transfers compliance risk to envelope integrators while compressing vendor counts from 12-15 specialty contractors to 3-4 qualified partners. The shift is most pronounced in advanced packaging facilities where rapid technology node transitions demand flexible reconfiguration guarantees written into 10-year service agreements.
Clean Room Panels Market Segmentation
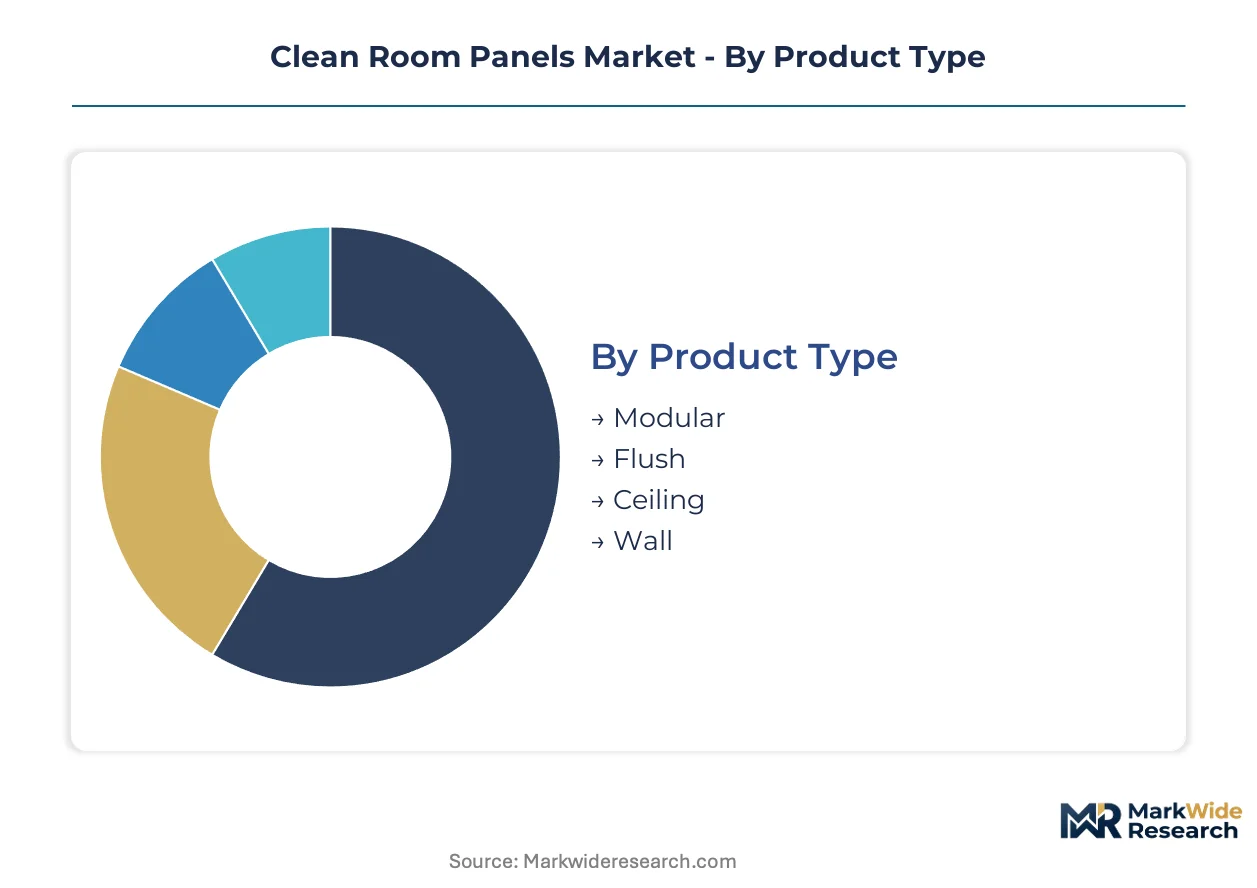
Clean room panel segmentation reflects divergent technical requirements across semiconductor, pharmaceutical, and biologics manufacturing. Specification intensity varies dramatically between aseptic filling suites demanding electropolished surfaces and electronics fabs prioritizing lightweight thermal stability.
Product Type:
Installation geometry determines reconfiguration flexibility and microbial control capability across regulated manufacturing environments.
- Modular:Aluminum honeycomb or steel-faced composite panels with sealed joint geometries enable rapid facility reconfiguration. Demand concentrates in multi-product biologics facilities in Singapore and Boston where campaign flexibility protects capital efficiency against pipeline volatility.
- Flush:Seamless welded joint geometries eliminate crevices that harbor microbial contamination. Pharmaceutical aseptic suites in Basel and Cambridge specify these configurations to meet EMA Annex 1 surface sanitization mandates for repeated sporicidal agent exposure.
- Ceiling:Suspended envelope systems integrating HVAC distribution and lighting conduits. Semiconductor fabs in Hsinchu deploy these to maintain ISO 14644-1 Class 1-3 environments while accommodating tool access requirements.
- Wall:Vertical barrier panels forming primary cleanroom perimeters. Electronics manufacturing in Pyeongtaek utilizes these for cost-effective envelope construction where thermal cycling demands are moderate.
Modular holds installed capacity. Flush is rotating up the share rankings.
Material:
Substrate selection balances structural load, thermal performance, and chemical resistance against process-specific contamination risks.
- Steel:Electropolished 316L stainless steel facing maintains surface roughness below 0.8 micrometers Ra after 10,000 sanitization cycles. European aseptic filling lines specify this material to satisfy EMA Annex 1 revisions disqualifying painted finishes.
- Aluminum:Honeycomb core construction reduces structural load while preserving dimensional integrity across temperature cycling. Advanced packaging cleanrooms in Taiwan prioritize this substrate for ceiling installations where weight reduction enables larger span configurations.
- Composite:Multi-layer metallized polymer barriers surrounding fumed silica cores deliver vacuum-insulated performance. Cell banking facilities specify these for ultra-low temperature envelope applications where thermal bridging compromises batch integrity.
- Vinyl:Cost-effective facing material for lower-classification environments. Contract manufacturing organizations utilize these in secondary processing areas where particulate thresholds remain above ISO 14644-1 Class 7.
Steel dominates pharmaceutical certification requirements. Aluminum is climbing the fastest in semiconductor construction.
Application:
End-use sector dictates cleanroom classification thresholds, sanitization protocols, and reconfiguration frequency.
- Pharmaceuticals:Aseptic filling and sterile manufacturing operations demanding ISO 14644-1 Class 5-7 environments with aggressive vapor-phase hydrogen peroxide sterilization. EU F-Gas Regulation accelerates replacement cycles for legacy polyurethane-insulated panels.
- Biotechnology:Cell therapy production facilities requiring flush-panel suites to eliminate microbial harborage points. Singapore and Boston clusters drive specification pull for seamless welded joint geometries.
- Electronics:Semiconductor fabrication below 3nm nodes forcing panel suppliers to scale bonding capacity for hermetic envelope systems. Taiwan and South Korean mega-fabs concentrate demand for lightweight thermally stable substrates.
- Aerospace:Precision assembly environments for satellite and avionics components. Cleanrooms in this sector balance particulate control with electrostatic discharge management through specialized panel facing treatments.
Electronics commands volume scale. Biotechnology is gaining share fastest on cell therapy facility expansion.
Installation Type:
Mounting methodology determines asset mobility, project timeline compression, and interface complexity with existing infrastructure.
- Demountable:Reconfigurable panel systems enabling facility repurposing across multi-product campaigns. Contract manufacturing organizations prioritize this category to protect capital efficiency against pipeline uncertainty.
- Fixed:Permanent envelope construction for stable, long-duration manufacturing processes. Legacy pharmaceutical facilities in Germany and France retain this approach where reconfiguration frequency remains low.
- Portable:Self-contained cleanroom units for temporary or emergency production capacity. These configurations serve clinical trial material manufacturing where speed-to-qualification outweighs per-square-meter cost premiums.
- Customized:Engineered solutions interfacing with existing structural steel grids and utility matrices. Retrofit projects in Indian pharmaceutical corridors require this approach to meet US FDA audit standards without complete facility reconstruction.
Fixed retains legacy installed base. Demountable is expanding most quickly on prefabricated POD system adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabricators and pharmaceutical manufacturers concentrate procurement in economies with advanced regulatory frameworks and established supplier ecosystems. Taiwan, South Korea, Germany, the United States, and Singapore anchor demand through distinct industrial specializations and compliance environments.
Taiwan
Advanced node semiconductor production below 3nm drives hermetic envelope specifications for ISO 14644-1 Class 1-3 environments. The Industrial Development Bureau supports domestic panel bonding capacity expansion through targeted investment incentives. Hsinchu Science Park hosts mega-fab clusters where lightweight aluminum honeycomb substrates dominate ceiling installations for reduced structural load.
South Korea
Memory and logic chip manufacturing in Pyeongtaek and Yongin requires thermally stable panel systems across temperature cycling regimes. MFDS pharmaceutical manufacturing standards accelerate flush-panel adoption for domestic biologics facilities. Samsung and SK Hynix supply chain proximity concentrates panel integrators near component ecosystems in Gyeonggi Province.
Germany
The EU F-Gas Regulation mandates polyurethane panel replacement with mineral wool and vacuum-insulated alternatives across pharmaceutical corridors. EMA Annex 1 revisions on sterile manufacturing disqualify painted steel finishes in aseptic suites. BASF and Boehringer Ingelheim operations in Ludwigshafen and Ingelheim specify electropolished 316L stainless steel facing for repeated sporicidal agent exposure.
United States
Cell therapy production in Greater Boston and San Francisco Bay Area drives flush-panel specifications to eliminate microbial harborage points. EPA particulate emissions frameworks indirectly elevate clean room integrity requirements for domestic pharmaceutical operations. Prefabricated POD system adoption compresses deployment timelines for contract manufacturing organizations serving multi-product biologics campaigns.
Singapore
Biologics manufacturing expansion for regional export markets prioritizes modular panel configurations protecting capital efficiency against pipeline volatility. The Economic Development Board incentivizes advanced manufacturing infrastructure through tax concession frameworks. Tuas Biomedical Park clusters cell therapy facilities specifying seamless welded joint geometries for aseptic suite construction.
Clean Room Panels Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Turnkey integrators capture margin through bundled design-installation-certification contracts, while component fabricators supply standardized panels to secondary installers. The structure rewards vertical scope in pharmaceutical qualification documentation and geographic density in regional construction markets. Consolidation pressure intensifies as semiconductor project finance narrows vendor qualification to bonded large-scale contractors. Dominant competitive moves include strategic partnerships for POD system convergence and capacity expansion for aluminum honeycomb substrate production.
Among North American turnkey specialists, AES Clean Technology and PortaFab Corporation exemplify contrasting archetypes. AES Clean Technology represents the vertically integrated design-build model spanning envelope engineering through environmental certification. PortaFab Corporation anchors geographic dominance in modular cleanroom construction across United States pharmaceutical and electronics corridors. G-CON Manufacturing occupies a distinct position within the prefabricated POD system segment, compressing deployment timelines for biologics manufacturers requiring rapid facility qualification. These three fabricators illustrate how service model differentiation—turnkey integration versus regional scale versus modular system convergence—shapes competitive positioning without overlapping core value propositions.
| Leading Market Players |
|---|
| AES Clean Technology, Inc. |
| MRC Cleanrooms |
| PortaFab Corporation |
| Pacific Panels Inc. |
| Terra Universal Inc. |
| Plascore, Inc. |
| G-CON Manufacturing |
| American Cleanroom Systems |
| Fabtech Technologies International Ltd |
| Others |
Supply Flow & Price Mechanics
Hsinchu Science Park's aluminum honeycomb bonding capacity expansion directly shapes pricing power for hermetic envelope systems serving Taiwan's advanced node semiconductor fabs. Panel integrators with captive supply of lightweight substrates command premium positioning against competitors exposed to London Metal Exchange aluminum volatility.
Pricing Analysis
Cost-plus contracts with London Metal Exchange aluminum indexation dominate fixed-price fab engagements, transferring raw material risk to buyers on multi-year semiconductor buildouts. Price differentiation hinges on ISO 14644-1 certification tier and geographic proximity to mega-fab clusters, with qualified integrators near Hsinchu and Pyeongtaek capturing substantial premiums. Cost compression in standard-grade polyurethane panels is intensifying because EU F-Gas Regulation phaseout timelines accelerate replacement demand. Contract manufacturing organizations exhibit highest price sensitivity due to campaign-to-campaign volume uncertainty, while advanced node fabs prioritize qualification reliability over per-square-meter cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for Western panel integrators dependent on Asian aluminum foil inputs. High-purity honeycomb core materials concentrate in Japan and South Korea, with specialized sealant chemistries drawing from concentrated Japanese chemical suppliers. Raw material dependencies span aluminum extrusion framing, metallized polymer barrier films, and fumed silica vacuum insulation cores. Single-source vulnerability persists for electropolished 316L stainless steel facing certified to EMA Annex 1 surface roughness standards. Distribution runs through turnkey design-build integrators bundling envelope engineering, installation, and environmental certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as semiconductor project finance narrows vendor qualification to bonded large-scale contractors capable of underwriting 10-year service agreements. Mega-fab procurement consolidation favors integrators with vertical scope across design, installation, and real-time environmental monitoring.
For Market Incumbents: Build regulatory qualification moats through captive documentation capabilities for US FDA and EU EMA audit standards. Deepen backward integration into aluminum honeycomb substrate production to offset London Metal Exchange price volatility on fixed-price contracts. Expand bonding capacity in Gyeonggi Province to secure Samsung and SK Hynix supply chain proximity against emerging Chinese panel fabricators. For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical corridor by offering turnkey qualification documentation for Hyderabad and Ahmedabad bulk drug manufacturers retrofitting to US FDA standards. Target demountable panel systems for contract manufacturing organizations prioritizing asset mobility across multi-product biologics campaigns. Pursue prefabricated POD system convergence as the fastest-penetrating installation category compressing deployment timelines from conventional construction. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because semiconductor project finance requirements are systematically eliminating sub-scale panel integrators incapable of bonding large-scale contracts. Acquisition targets should exhibit vertical integration across envelope engineering and environmental certification, with demonstrated ISO 14644-1 Class 1-3 qualification track records. The signal to watch is turnkey performance contracting displacement of component procurement in Taichung and Yongin advanced packaging facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Honeycomb Production | Mitigates London Metal Exchange volatility exposure on fixed-price semiconductor fab contracts. |
| Prefabricated POD System Convergence | Compresses biologics facility deployment timelines from 18 months to 8 weeks for CMOs. |
| EMA Annex 1 Qualification Documentation | Enables premium positioning in European aseptic filling suites requiring electropolished 316L surfaces. |
| Embedded Sensor Conduit Integration | Aligns panel specifications with ISO 14644-2 continuous particulate monitoring mandates. |
| Regional Capacity Expansion in Gyeonggi Province | Secures supply chain proximity to Samsung and SK Hynix memory and logic chip operations. |
Methodological Framework
The analysis maps modular, flush, ceiling, and wall panel configurations, each validated through primary interviews with cleanroom design engineers, pharmaceutical facility managers, semiconductor fab procurement leads, and environmental certification specialists. Secondary validation draws from SEC filings of publicly traded panel integrators, ISO 14644-1 compliance testing records, EU F-Gas Regulation implementation reports, and customs data on aluminum honeycomb core trade flows. Bottom-up project pipeline tracking across Taiwan, South Korea, and Germany triangulates against top-down market sizing from end-use sector capital expenditure disclosures.
Forecasts assume continued EU F-Gas Regulation enforcement, sustained advanced node semiconductor investment in East Asia, and stable aluminum supply from Japanese and South Korean chemical suppliers across the analysis window. Segmentation modeling spans product type, material substrate, end-use application, and installation methodology, with particular sensitivity to biologics manufacturing expansion rates and semiconductor fab buildout timelines. CAGRs derive from weighted average of project-based capacity additions and replacement cycle frequencies, with explicit treatment of vacuum-insulated panel technology substitution curves and prefabricated POD system adoption rates.
Sensitivities concentrate around aluminum price volatility, regulatory enforcement timelines for EU F-Gas phaseout, and semiconductor capital expenditure cycle turns. Forecasts reflect documented assumptions on bonding capacity expansion rates and qualification timeline compression. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Roofing Materials Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Articulated Concrete Block Mattresses Market
Building & Construction Materials
Asphalt Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Cement Roofing Sheets Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Global PUR and PIR Sandwich Panels Market
Building & Construction Materials
Asia-Pacific Oriented Strand Board Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Europe Construction Chemicals Market