
 North America Mineral Wool Ceiling Tiles Market | 2026-2036
North America Mineral Wool Ceiling Tiles Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mineral Wool Ceiling Tiles Market Intelligence
Healthcare procurement consolidation in the southern United States is decoupling from traditional commercial real estate buying patterns, creating divergent specification requirements for mineral wool ceiling tiles. Armstrong World Industries leverages its extensive distribution network to serve these consolidated hospital systems. USG Corporation anchors its position through specialized infection-control product lines designed for clinical environments. CertainTeed competes by emphasizing sustainable manufacturing credentials that appeal to institutional buyers with ESG mandates.
North America mineral wool ceiling tiles are manufactured from spun mineral fibers, typically basalt or diabase combined with recycled steel slag, formed into rigid boards with densities ranging from 6 to 16 pounds per cubic foot for acoustic and thermal performance. These products primarily serve commercial and institutional interiors where fire resistance ratings, noise reduction coefficients, and ceiling attenuation class ratings determine specification compliance. Acoustic Tiles command the largest volume share as open-plan offices and educational facilities prioritize speech intelligibility and sound privacy. Fire Resistant Tiles capture premium positioning in high-rise construction and critical infrastructure where ASTM E119 and UL 263 assemblies are mandatory. Healthcare Facilities represent the fastest-growing end-user segment as renovation cycles accelerate and new hospital construction emphasizes patient experience metrics.
The National Fire Protection Association, Underwriters Laboratories, and ASTM International collectively govern material performance standards, installation practices, and product certification pathways for mineral wool ceiling assemblies across the United States and Canada. These frameworks elevate compliance costs for imported products while rewarding domestic manufacturers with established testing relationships and localized production. Stakeholders must monitor evolving state-level amendments to the International Building Code, particularly seismic bracing requirements and moisture resistance standards, as these technical provisions increasingly differentiate winning bids from qualified alternates in competitive specification environments.
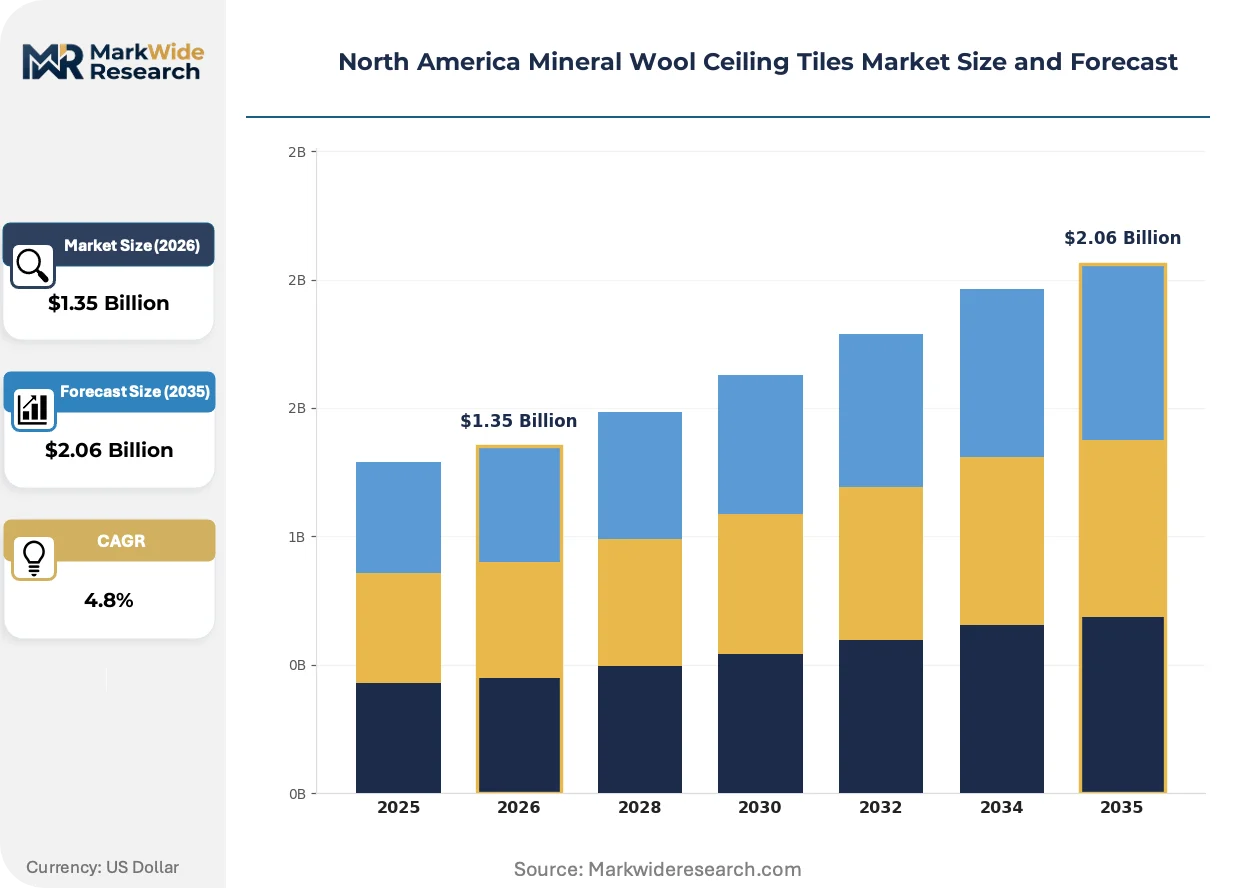
Market Dynamics
Healthcare procurement consolidation across Texas and Florida hospital systems is fragmenting specification pathways, forcing mineral wool ceiling tile manufacturers to maintain parallel product lines for divergent acoustic and infection-control standards.
Growth Catalysts
- ASTM E84 fire-rating mandates:Commercial building codes in the southern United States are tightening surface-burning requirements, pulling higher-density mineral wool formulations into new construction and retrofit pipelines.
- Patient experience metrics:Hospital administrators in Florida and Texas metros are prioritizing noise reduction coefficients above first-cost considerations, accelerating specification of premium acoustic ceiling assemblies.
- Steel slag recycling infrastructure:Domestic supply chains for recycled industrial byproducts are maturing across the Great Lakes and Ohio River Valley, compressing raw material input costs for regional manufacturers.
Market Restraints
- Basalt fiber import concentration:High-purity basalt feedstock concentrates among a limited set of offshore suppliers, exposing North American manufacturers to freight volatility and customs processing delays.
- Seismic bracing compliance:California and Pacific Northwest amendments to the International Building Code are adding material and labor costs for ceiling suspension assemblies in high-risk zones.
- Gypsum board substitution:Lightweight gypsum ceiling panels are capturing share in low-rise commercial applications where fire ratings below one hour suffice.
Strategic Opportunities
- Canadian healthcare expansion:Provincial hospital capital programs in Ontario and British Columbia are accelerating renovation cycles, creating specification windows for infection-control-rated mineral wool products.
- Moisture-resistant formulations:Gulf Coast humidity standards are driving development of encapsulated edge treatments that expand addressable square footage into aquatic center and natatorium applications.
- Direct-to-contractor digital channels:Specialized distributors are building configuration tools that bypass traditional rep networks, compressing quote-to-order cycles for midsize commercial contractors.
Industry Challenges
- Acoustic engineering talent scarcity:Ceiling system designers with expertise in ceiling attenuation class modeling are concentrated among a handful of consulting firms, extending project timelines.
- UL 263 certification backlog:Fire-resistance testing queue times at Underwriters Laboratories facilities are stretching to sixteen weeks, delaying product launches for assembly-rated tile systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mineral Wool Ceiling Tiles Market |
| Market Size in 2026 | $1.35 Billion |
| Market Size in 2035 | $2.06 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acoustic Tiles, Fire Resistant Tiles, Insulation Tiles, Ceiling Panels End User: Commercial Buildings, Residential Buildings, Educational Institutions, Healthcare Facilities Installation Type: Suspended Ceiling, Direct Mounted, Lay-in Ceiling, Grid System Application: Sound Absorption, Thermal Insulation, Aesthetic Enhancement, Fire Protection |
| Companies Covered | Armstrong World Industries Inc., USG Corporation, CertainTeed, Rockfon, OWA Ceiling Systems Inc., Hunter Douglas, SAS International, Knauf Insulation, Gordon Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mineral Wool Ceiling Tiles Market Strategic Shifts & Innovations
Bio-based binders and automated panel-forming equipment are compressing the gap between commodity mineral wool and specialized acoustic-performance products across North American manufacturing footprints.
Micro-perforated facing technologies are integrating mineral wool cores with precision-drilled surface layers to tune absorption coefficients across specific frequency ranges. K-12 school districts in the southern United States are specifying these tuned assemblies for multipurpose gymnasium-auditorium conversions. The technology is integrating acoustic performance with architectural finish requirements, collapsing the traditional trade-off between noise control and visual ceiling continuity.
California Title 24 energy code amendments are mandating higher thermal performance for roof-ceiling assemblies in non-residential buildings. The regulation is pulling multi-layer mineral wool systems into big-box retail and distribution center construction across the Central Valley and Inland Empire. Cold storage and refrigerated warehouse developers are responding by pre-specifying fire-resistant ceiling tiles that simultaneously satisfy R-value and ASTM E119 assembly requirements.
Hospital system procurement departments are consolidating ceiling tile purchasing through national group purchasing organizations, compressing the number of approved suppliers per health network. Specialty distributors serving the acute care segment are losing direct relationships with individual facility managers, replaced by centralized specification committees in Dallas and Nashville headquarters. The shift is most visible in Texas, where Methodist and Baptist health systems have standardized on narrow product portfolios across dozens of affiliated campuses.
North America Mineral Wool Ceiling Tiles Market Segmentation
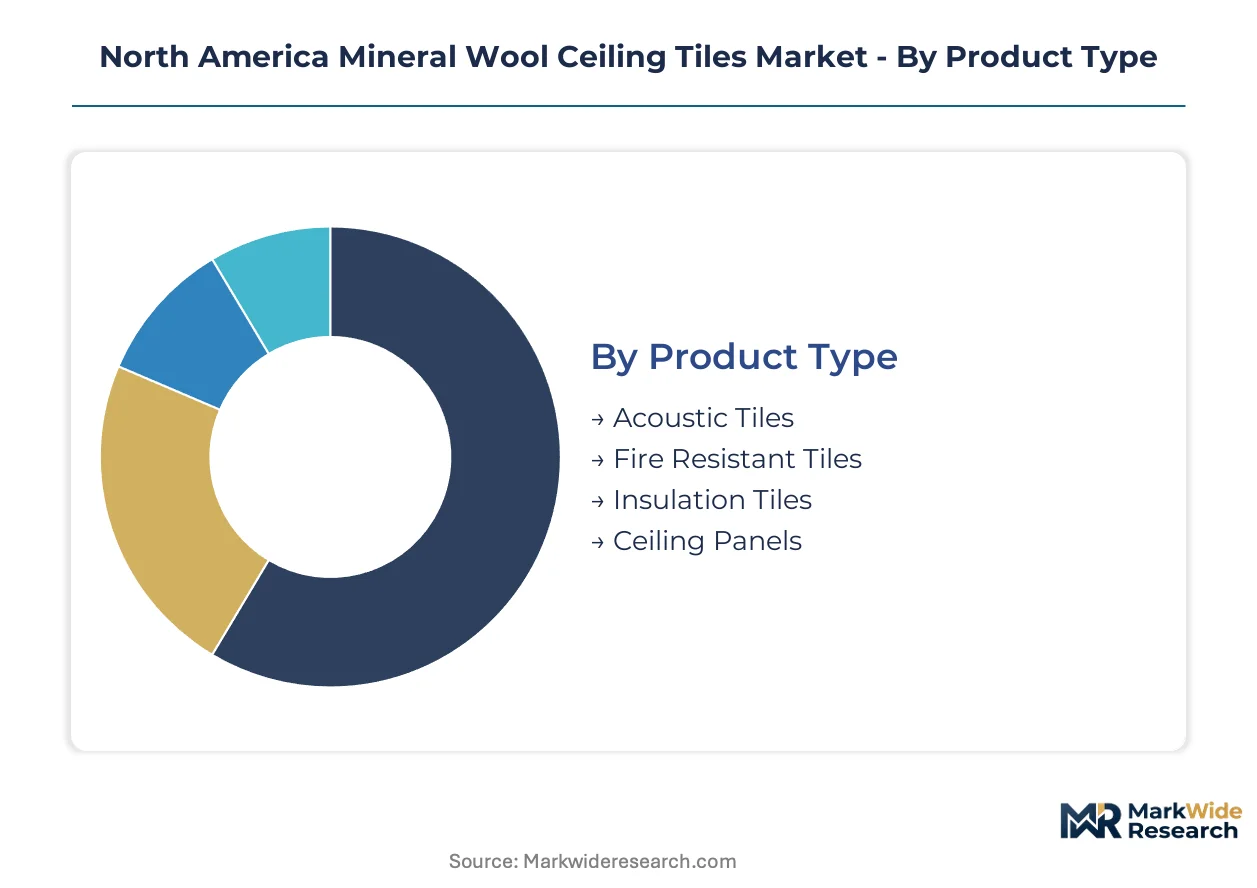
Specification pathways for mineral wool ceiling tiles diverge sharply across building codes, acoustic performance tiers, and installation methodologies. Procurement committees in Texas and Florida hospital systems now demand parallel certifications that fragment traditional product categories into specialized sub-lines.
Product Type:
Density formulations and facing technologies define competitive positioning across the specification landscape.
- Acoustic Tiles:Micro-perforated facings bonded to 6-10 pcf mineral wool cores tune absorption coefficients across speech-frequency ranges. K-12 gymnasium-auditorium conversions in southern United States districts specify these assemblies for multipurpose functionality.
- Fire Resistant Tiles:Higher-density 12-16 pcf boards achieve ASTM E119 and UL 263 assembly ratings mandatory in high-rise construction and critical infrastructure. California Title 24 thermal amendments are pulling multi-layer systems into Central Valley big-box retail.
- Insulation Tiles:Thermal-performance-optimized formulations address roof-ceiling assemblies in refrigerated warehouses.
- Ceiling Panels:Architectural-finish-integrated products collapse trade-offs between noise control and visual continuity.
Mature deployment sits with Acoustic Tiles. Newer deployment is concentrated in Fire Resistant Tiles.
End User:
Procurement consolidation is decoupling institutional buying patterns from traditional commercial real estate specifications.
- Healthcare Facilities:Infection-control-rated products with encapsulated edge treatments address patient experience metrics and renovation cycles. Methodist and Baptist systems in Texas have standardized narrow portfolios across dozens of campuses.
- Commercial Buildings:Open-plan offices prioritize speech intelligibility through NRC-optimized assemblies in southern United States metros.
- Educational Institutions:Tuned acoustic systems serve multipurpose conversion projects.
- Residential Buildings:Limited penetration concentrates in high-rise multifamily fire-rated corridors.
Volume concentration rests with Commercial Buildings. Steepest expansion trajectory belongs to Healthcare Facilities.
Installation Type:
Labor cost structures and seismic compliance requirements differentiate specification pathways.
- Suspended Ceiling:T-bar grid systems dominate commercial interiors where access to mechanical infrastructure is required. California and Pacific Northwest seismic bracing amendments add material and labor costs in high-risk zones.
- Grid System:Modular configurations enable rapid reconfiguration in tenant improvement cycles.
- Lay-in Ceiling:Tool-free installation appeals to fast-track commercial contractors.
- Direct Mounted:Adhesive or mechanical fastening addresses low-clearance retrofits.
Installed base concentrates in Suspended Ceiling. Specification momentum is shifting toward Grid System.
Application:
Functional performance requirements determine formulation density and facing selection.
- Sound Absorption:NRC and CAC ratings drive specification in open-plan offices and educational facilities. Noise reduction coefficients now rank above first-cost in Florida and Texas hospital procurement.
- Fire Protection:ASTM E84 surface-burning mandates tighten across southern United States commercial codes.
- Thermal Insulation:R-value stacking in roof-ceiling assemblies serves cold storage developers.
- Aesthetic Enhancement:Architectural finish integration addresses visual continuity requirements.
Specification volume clusters around Sound Absorption. Code-mandated expansion is accelerating in Fire Protection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for mineral wool ceiling tiles concentrates in the southern United States, where Texas and Florida hospital systems drive specification volumes through consolidated procurement programs. Canadian provincial healthcare expansions and Mexican industrial construction add secondary growth vectors across the North American footprint.
United States
Texas and Florida metros anchor demand through Methodist and Baptist health system expansions requiring infection-control-rated assemblies. ASTM E84 surface-burning mandates tighten across southern commercial codes, pulling higher-density formulations into new construction. Dallas and Nashville headquarters centralize procurement decisions for dozens of affiliated hospital campuses.
Canada
Ontario and British Columbia provincial hospital capital programs accelerate renovation cycles for clinical-grade mineral wool products. Health Canada building code amendments emphasize fire-resistance ratings in institutional construction. Toronto and Vancouver construction clusters specify encapsulated edge treatments for humidity-resistant applications.
Mexico
Nuevo León and Mexico City industrial corridors drive commercial ceiling tile demand through manufacturing facility expansions. Mexican building standards increasingly reference NFPA fire codes for cross-border project consistency. Monterrey construction markets specify acoustic assemblies for multinational corporate interiors.
North America Mineral Wool Ceiling Tiles Market Key Industry Players
United States producers anchor one tier; Canadian and European specialists hold differentiated positions through niche certification pathways. The vendor base concentrates among established building materials conglomerates with pre-existing testing relationships at Underwriters Laboratories. Two strategic archetypes dominate: full-line ceiling system providers and mineral wool insulation specialists extending into finished tile products. Capacity rationalization and fire-rating certification partnerships represent the primary competitive vectors.
Within the full-line system tier, Armstrong World Industries Inc. and USG Corporation exemplify scale-driven positioning through extensive distribution infrastructure. CertainTeed occupies a sustainability-focused archetype appealing to institutional buyers with ESG procurement mandates. These three entities represent divergent strategic responses to healthcare consolidation pressures.
| Leading Market Players |
|---|
| Armstrong World Industries Inc. |
| USG Corporation |
| CertainTeed |
| Rockfon |
| OWA Ceiling Systems Inc. |
| Hunter Douglas |
| SAS International |
| Knauf Insulation |
| Gordon Incorporated |
| Others |
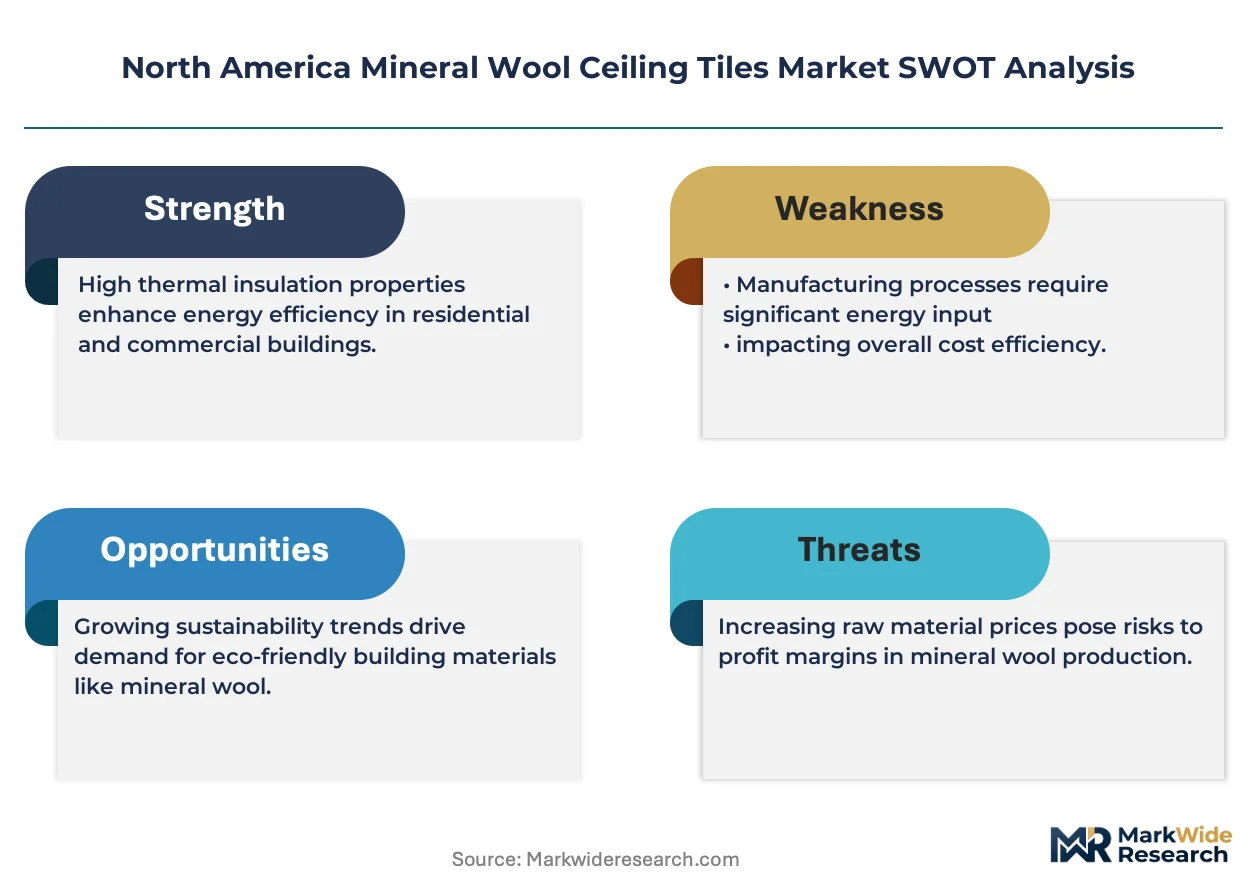
Cost & Logistics Intelligence
Hospital procurement consolidation across Texas and Florida Methodist and Baptist health systems anchors pricing power with volume-commitment contract structures. Three-tier pricing structure across premium, standard, and economy levels reflects ASTM E84 fire-rating tiers and infection-control certification grades.
Pricing Analysis
Volume-margins split sharply between commodity acoustic tiles for commercial offices and premium fire-resistant assemblies for healthcare. Price differentiation hinges on UL 263 certification status and ASTM E119 assembly ratings. Pricing pressure stems from gypsum board substitution in low-rise commercial segments. Commercial contractors exhibit highest price sensitivity; hospital GPOs prioritize performance metrics over first-cost.
Supply Chain Analysis
Single-source vulnerability sits with high-purity basalt fiber imports concentrated among limited offshore suppliers. Domestic manufacturing draws from recycled steel slag sourced across Great Lakes and Ohio River Valley processing infrastructure. Tariff exposure on raw mineral feedstock creates margin volatility. Distribution runs through specialized ceiling system distributors with UL testing relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASTM E84 and UL 263 fire-rating mandates erect a cost-of-compliance barrier that rewards established testing relationships and domestic certification infrastructure. NFPA 90A surface-burning standards deepen this moat for compliant incumbents.
For Market Incumbents: Cement market position by deepening captive supply of recycled steel slag through backward integration into Ohio River Valley slag processing. Expand fire-rating certification partnerships to compress UL 263 testing queue delays. Defend against gypsum substitution by emphasizing multi-hour assembly ratings in high-rise specifications.
For New Entrants and Emerging Players: Capture specification windows in Canadian provincial healthcare expansions where infection-control product lines remain underdeveloped. Target Ontario and British Columbia hospital capital programs with encapsulated edge treatment formulations. Build direct-to-contractor digital channels to bypass entrenched rep networks in midsize commercial segments.
For Investors and Strategic Acquirers: The window for entry favors mineral wool insulation specialists extending into finished tile products with pre-existing ASTM testing relationships. Long-term viability hinges on fire-rating certification infrastructure rather than commodity scale. Watch California Title 24 thermal amendment adoption as inflection signal for multi-layer system demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Slag Supply | Captive steel slag feedstock from Great Lakes processors compresses raw material cost volatility. |
| UL 263 Certification Partnership | Priority testing queue access at Underwriters Laboratories accelerates fire-resistant product launches. |
| Moisture-Resistant Formulation Development | Encapsulated edge treatments unlock Gulf Coast natatorium and aquatic center specification volumes. |
| Direct-to-Contractor Digital Channel | Configuration tools bypass traditional rep networks for faster quote-to-order cycles with midsize contractors. |
| Canadian Healthcare Market Entry | Ontario and British Columbia provincial hospital programs create specification windows for infection-control products. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with ceiling system distributors, hospital GPO procurement managers, commercial contractors, and acoustic engineering consultants validated demand-side assumptions. Secondary sources included ASTM International standards documentation, NFPA code amendments, UL certification directories, and building permit databases. Bottom-up project pipeline analysis triangulated against top-down construction spending forecasts.
Data-stream reconciliation across product type, end-user vertical, installation methodology, and regional building code clusters shaped the analytical framework. Modeled segmentation captured density formulation tiers, fire-rating certification levels, and acoustic performance specifications. CAGRs derived from construction cycle timing, healthcare renovation rates, and code adoption trajectories. Forecast inputs incorporated hospital procurement consolidation patterns and seismic bracing amendment cost impacts.
The model holds under stable regulatory enforcement of ASTM E84 and NFPA 90A standards; deviation in state-level International Building Code adoption timelines or basalt import tariff regimes would shift volume trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Germany Construction Chemicals Market
Building & Construction Materials
North America Plywood Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Global Roofing Market
Building & Construction Materials
Construction Sealants Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Foldable Houses Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Latex Caulk Market
Building & Construction Materials
Vitrified Tiles Market
Building & Construction Materials
Epoxy Grout Market
Building & Construction Materials
Timber Floor Joist Market