
 US Offsite Construction Market | 2026-2036
US Offsite Construction Market Size, Share, and Industry Trends Forecast 2026-2036
US Offsite Construction Market Insights
The direct-to-developer channel is narrowing as manufacturers bypass traditional general contractor networks. Clayton Homes sustains geographic dominance across manufactured housing corridors in the Southeast. Plant Prefab Inc leverages automated fabrication to serve infill residential projects in California. FullStack Modular anchors its position in urban mid-rise construction through controlled factory environments.
Offsite construction encompasses the factory-based fabrication of building elements—ranging from dimensional lumber wall panels to volumetric steel modules with integrated MEP systems—for subsequent transport and assembly at permanent sites. Panelized systems currently occupy the largest production volume share due to lower capital barriers and compatibility with conventional framing crews. Modular units command premium positioning in multifamily and hospitality applications where schedule compression yields direct carry-cost savings. Hybrid structures are gaining specification share as architects blend panelized roofs with volumetric bathrooms to optimize both cost and performance.
FHA, Fannie Mae, and Freddie Mac guidelines increasingly recognize modular construction for conventional mortgage products, dissolving historical financing friction that constrained consumer access. The Department of Housing and Urban Development maintains the Manufactured Home Construction and Safety Standards while state-level adoption of the International Residential Code streamlines modular permitting across jurisdictions. Stakeholders must track evolving federal housing finance rules and local zoning amendments that determine whether factory-built housing achieves parity with site-built alternatives in assessable value and insurability.
Market Dynamics
The US offsite construction sector is being fundamentally restructured by the convergence of FHA and GSE financing guideline revisions with acute regional labor shortages. These forces are compressing project timelines and redrawing competitive boundaries between factory-based and site-built delivery models.
Growth Catalysts
- FHA Modular Recognition:The Federal Housing Administration's expanded mortgage eligibility for modular structures dissolves historical financing barriers. First-time buyers in California and Texas now access conventional loan products previously reserved for site-built homes.
- Hurricane Resilience Mandates:Florida's updated building codes for wind-load resistance favor factory-controlled fabrication over field assembly. Coastal multifamily developers specify steel-frame volumetric modules to satisfy structural engineering requirements.
- Automated Panel Fabrication:CNC-guided cutting and robotic assembly of dimensional lumber wall systems reduce dimensional variance. Southeast corridor manufacturers deploy these systems to serve entry-level housing production at scale.
Market Restraints
- Transportation Cost Volatility:Diesel fuel price swings and oversize load permitting fees erode the delivered-cost advantage of volumetric modules. Texas-to-California haul routes face particular pressure from driver shortage surcharges.
- Supply Concentration in OSB:Oriented strand board production clusters in the Southeast and Pacific Northwest. Hurricane reconstruction demand periodically exhausts regional inventory, forcing modular plants into spot-market purchases at premium pricing.
- Jurisdictional Permitting Friction:Local amendments to the International Residential Code create patchwork approval requirements. Some municipalities impose redundant inspections that duplicate factory quality certifications.
Strategic Opportunities
- Infill Residential in California:Los Angeles and San Francisco zoning reforms permit higher density on formerly single-family lots. Plant-based manufacturers target these parcels with compact modular units that minimize site disruption.
- Integrated MEP Prefabrication:Convergence of BIM coordination with factory-based mechanical-electrical-plumbing rough-in compresses field connection schedules. Urban mid-rise developers capture carry-cost savings from reduced on-site trades.
- Utility-Scale Workforce Housing:Texas renewable energy construction corridors generate demand for rapid-deployment worker accommodations. Modular dormitory and kitchen complexes deploy on 90-day cycles versus 8-month conventional builds.
Industry Challenges
- Factory-to-Site Logistics Coordination:Just-in-time module delivery requires precise sequencing with foundation completion. Weather delays or crane availability gaps force costly yard storage and double-handling.
- Multi-Trade Integration Complexity:Volumetric units arrive with pre-installed finishes that must interface with site-built structural and utility connections. Field crews require cross-training in both factory and conventional construction protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Offsite Construction Market |
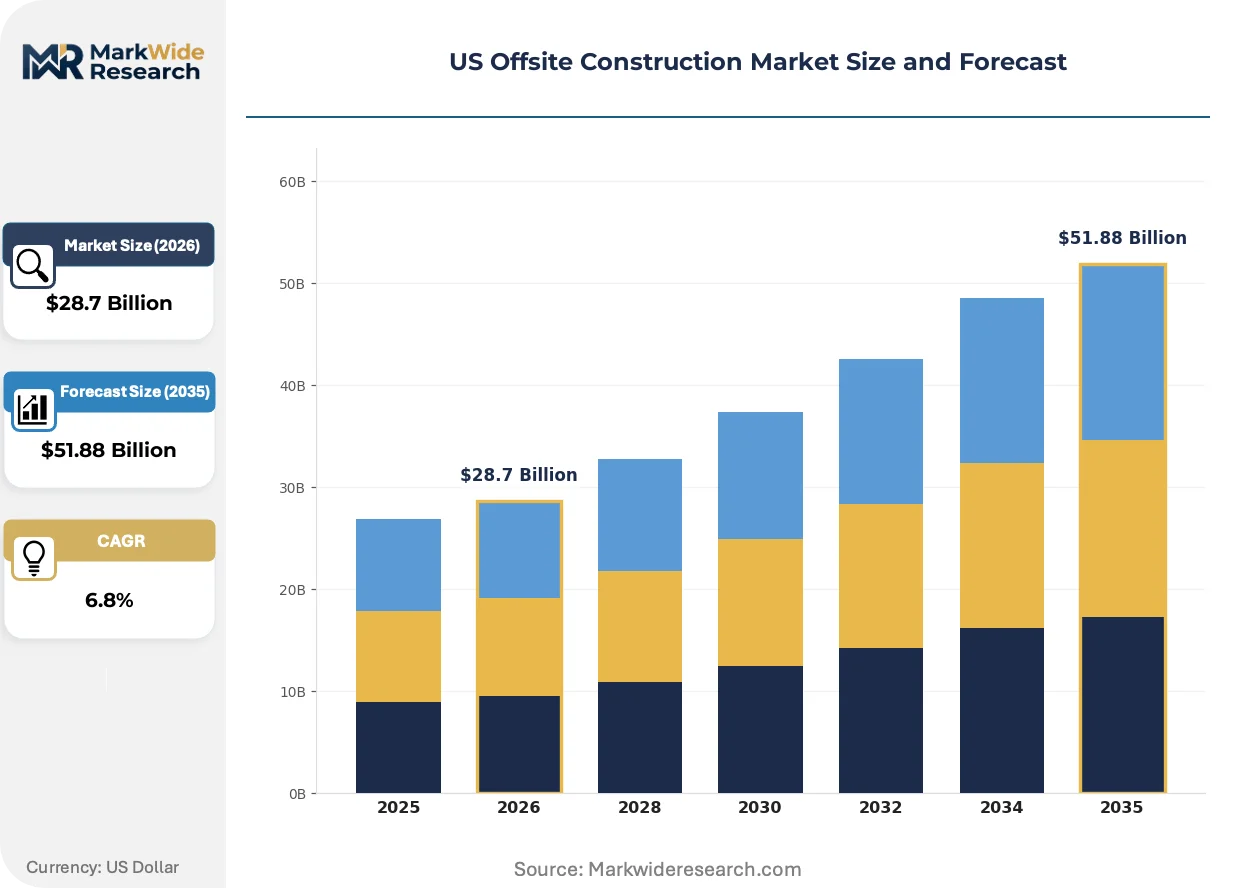
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $51.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Panelized Systems, Modular Units, Prefabricated Components, Hybrid Structures Application: Residential Buildings, Commercial Facilities, Industrial Projects, Disaster Relief Housing Technology: Building Information Modeling, 3D Printing, Automated Fabrication, Smart Building Technologies End User: Construction Firms, Property Developers, Government Agencies, Non-profit Organizations |
| Companies Covered | Plant Prefab Inc, FullStack Modular, Clayton Homes, Project Frog, Modus Structures Inc, Fluor Corporation, Safe & Green Holdings Corp, US-Offsite, Falcon Structures, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Offsite Construction Market Trends and Innovations
Digital fabrication and policy alignment are compressing the traditional design-build-occupy cycle. Three developments are restructuring how factory-built housing moves from specification to occupancy.
Building information modeling is digitizing the handoff between architectural design and CNC production equipment. California multifamily developers now transmit BIM files directly to panel fabrication lines, eliminating dimensional translation errors that previously required field correction. This direct digital thread is compressing pre-construction phases from twelve weeks to four.
The Department of Housing and Urban Development maintains the Manufactured Home Construction and Safety Standards while coordinating with state-level IRC adoption. This dual-framework alignment streamlines modular permitting across jurisdictions that previously operated under conflicting inspection regimes. Affordable housing developers in Florida and Texas leverage this harmonization to accelerate project approvals.
Direct-to-developer contracting is displacing traditional general contractor intermediation in residential procurement. Large-scale affordable housing operators in California now issue design-build contracts directly to modular manufacturers, internalizing project management functions that previously outsourced to construction management firms. This channel compression is most visible in urban infill projects where schedule certainty outweighs first-cost minimization.
US Offsite Construction Market Segmentation
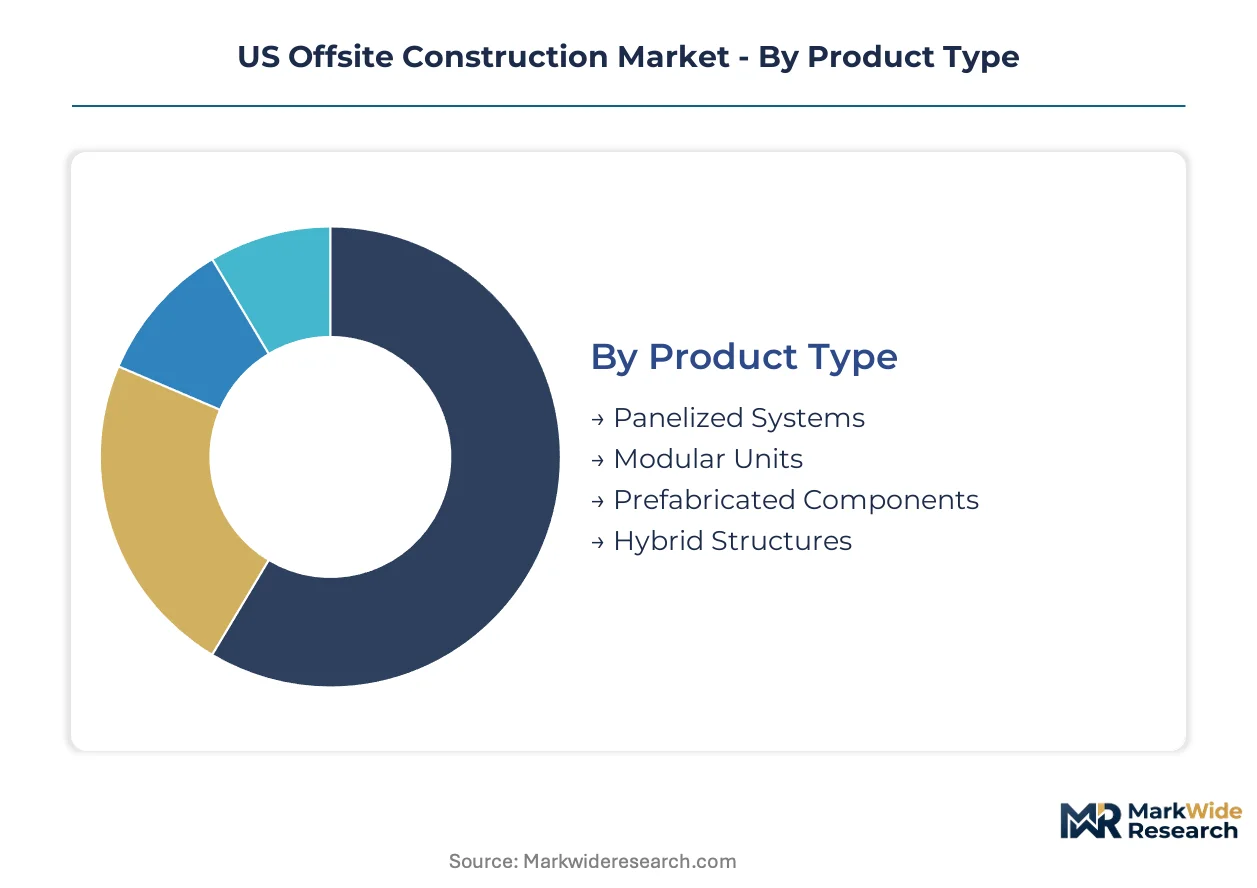
Segmentation in the US offsite construction market reveals how factory-based delivery methods align with project velocity requirements. Different product types, applications, and technologies exhibit distinct procurement cycles that shape manufacturer capacity planning and capital deployment decisions.
Product Type:
Cycle times vary dramatically across factory-fabricated systems, with some segments compressing project schedules by months while others require extended coordination phases.
- Panelized Systems:Dimensional lumber or steel wall panels fabricated with pre-cut openings for windows and doors. California multifamily developers specify these for infill projects where minimizing site disruption outweighs pure speed. Panelized systems currently occupy the largest production volume share due to lower capital barriers and compatibility with conventional framing crews.
- Modular Units:Volumetric steel or wood-frame modules with integrated MEP systems, finished interiors, and structural connections. Florida coastal developers deploy steel-frame volumetric units to satisfy hurricane wind-load mandates while compressing multifamily construction schedules. Modular units command premium positioning in hospitality and mid-rise residential where schedule certainty yields direct carry-cost savings.
- Prefabricated Components:Factory-built sub-assemblies including trusses, floor cassettes, and precast concrete elements. Texas entry-level housing producers source these to reduce on-site labor dependency.
- Hybrid Structures:Architect-blended systems combining panelized roofs with volumetric bathrooms. Southeast corridor manufacturers report rising specification share as designers optimize cost-performance tradeoffs.
Panelized systems dominate installed base. Modular units are where expansion concentrates.
Application:
End-use sectors impose divergent performance standards that filter which offsite technologies achieve specification.
- Residential Buildings:Single-family and multifamily housing delivered through factory-fabricated wall systems or complete volumetric modules. FHA and GSE financing guideline revisions have dissolved historical mortgage barriers for modular residential in California and Texas.
- Commercial Facilities:Office, retail, and hospitality structures where repeat room configurations favor volumetric production. Urban hotel developers in Florida specify modular guest room pods to compress construction schedules.
- Industrial Projects:Manufacturing facilities, warehouses, and distribution centers utilizing pre-engineered metal building systems. Texas renewable energy construction corridors generate demand for rapid-deployment modular support buildings.
- Disaster Relief Housing:Temporary and permanent replacement housing deployed after hurricanes, wildfires, or floods. FEMA and state emergency management agencies maintain pre-qualified manufacturer rosters for accelerated procurement.
Residential applications anchor current volume. Commercial facilities are climbing the fastest as hospitality developers internalize schedule risk.
Technology:
Digital and automated production methods are restructuring how design intent translates to factory output with varying degrees of capital intensity.
- Building Information Modeling:Digital coordination platforms enabling direct transmission of architectural files to CNC production equipment. California multifamily developers now compress pre-construction phases from twelve weeks to four through BIM-to-fabrication workflows.
- Automated Fabrication:CNC-guided cutting and robotic assembly systems reducing dimensional variance in wall panel production. Southeast corridor manufacturers deploy these systems to serve entry-level housing production at scale.
- 3D Printing:Additive manufacturing of concrete or polymer building elements for specialized architectural features and structural components. Early adoption concentrates in demonstration projects and non-load-bearing applications.
- Smart Building Technologies:Factory-integrated sensors, controls, and connectivity infrastructure pre-installed during module production. Urban mid-rise developers specify these to reduce field commissioning complexity.
BIM and automated fabrication dominate capital deployment. Smart building integration is gaining share fastest as developers seek operational technology differentiation.
End User:
Procurement authority is shifting across the construction value chain as direct-to-developer contracting displaces traditional intermediation.
- Construction Firms:General contractors and construction managers integrating offsite systems into conventional project delivery. Some firms face margin pressure as developers bypass them for direct manufacturer contracts.
- Property Developers:Large-scale affordable housing operators and multifamily investors issuing design-build contracts directly to modular manufacturers. California infill residential projects exhibit this channel compression most visibly.
- Government Agencies:Federal, state, and municipal entities procuring offsite construction for public housing, military facilities, and infrastructure. HUD maintains manufactured home construction standards while coordinating with state-level IRC adoption.
- Non-profit Organizations:Affordable housing developers and community development corporations leveraging offsite methods to stretch limited capital. These organizations accelerate modular adoption as FHA financing guidelines loosen.
Construction firms retain largest transaction volume. Property developers are where procurement authority is concentrating.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California commands 40% price premiums over Texas for equivalent volumetric modules, reflecting transport cost asymmetries and labor arbitrage differentials that reshape manufacturer locational decisions across state lines.
California
Los Angeles and San Francisco zoning reforms permit higher density on formerly single-family lots, accelerating infill modular demand. The California Building Standards Code aligns with HUD manufactured home standards while imposing additional seismic and energy efficiency requirements. Plant Prefab Inc anchors automated fabrication capacity in the Los Angeles Basin to serve coastal multifamily developers.
Texas
Renewable energy construction corridors generate demand for rapid-deployment worker accommodations and modular support buildings. The Texas Department of Housing and Community Affairs coordinates with IRC adoption to streamline modular permitting across metropolitan jurisdictions. Houston and Dallas-Fort Worth manufacturing clusters serve entry-level housing production at scale through CNC-guided panel fabrication.
Florida
Coastal multifamily developers specify steel-frame volumetric modules to satisfy updated wind-load resistance mandates in hurricane-prone zones. The Florida Building Code incorporates enhanced structural requirements that favor factory-controlled fabrication precision. Miami-Dade and Tampa Bay industrial zones concentrate module assembly operations serving Caribbean and southeastern US markets.
Southeast Corridor
Georgia and the Carolinas leverage lower land and labor costs to attract panelized system manufacturers serving affordable housing production. State-level adoption of the International Residential Code streamlines interstate module transport and permitting harmonization. Clayton Homes sustains geographic dominance across manufactured housing corridors with vertically integrated production networks.
Pacific Northwest
Oregon and Washington timber access supports mass timber and cross-laminated timber panel fabrication for sustainable multifamily construction. State energy codes and green building incentives align with factory-based quality control for high-performance envelope systems. Seattle and Portland metropolitan areas concentrate design-build firms integrating regional wood products into hybrid offsite structures.
US Offsite Construction Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying fabricated elements to assembly operations. The vendor base distributes across three functional layers: volumetric module producers, panelized system fabricators, and materials-technology suppliers. Two strategic archetypes dominate competitive positioning—geographically concentrated scale players and technology-differentiated regional specialists. Capacity expansion and direct-to-developer channel compression represent the dominant competitive moves reshaping intermediary relationships.
Among California-based fabricators, Plant Prefab Inc exemplifies the automated-production archetype targeting infill residential density. FullStack Modular occupies a position within the urban mid-rise tier, anchoring controlled-factory delivery models for multifamily developers. Clayton Homes represents the scale-driven manufactured housing specialist with corridor dominance across southeastern states. These three entities illustrate how geographic concentration and technology differentiation partition competitive space without requiring uniform strategic postures.
| Leading Market Players |
|---|
| Plant Prefab Inc |
| FullStack Modular |
| Clayton Homes |
| Project Frog |
| Modus Structures Inc |
| Fluor Corporation |
| Safe & Green Holdings Corp |
| US-Offsite |
| Falcon Structures |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in Southeast panel fabrication is compressing supplier margins while elevating price leverage for California volumetric module producers, creating divergent pricing postures across factory-based delivery tiers. Texas-to-California haul routes amplify this asymmetry, as transport cost volatility feeds directly into configured-to-order premiums.
Pricing Analysis
The customization-premium spread between standard panelized systems and architect-specified volumetric modules spans project-based contract structures versus commodity spot purchasing for entry-level housing. Price differentiation centers on BIM coordination depth and Florida wind-load certification tiers, with coastal multifamily developers absorbing premium positioning for schedule certainty. Cost compression in standard panel tiers is intensifying because Southeast corridor manufacturers compete for entry-level production volume. Affordable housing operators exhibit highest price sensitivity, while urban mid-rise developers prioritize carry-cost savings over first-cost minimization.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates lumber input cost volatility for wall panel fabricators operating across northern tier states. Geographic supply concentration in Southeast OSB production and Pacific Northwest dimensional lumber draws from concentrated forest products milling. Raw material dependencies on engineered wood products, steel framing, and precast concrete elements create single-source vulnerability during hurricane reconstruction cycles. Distribution runs through direct-to-developer channels that displace traditional general contractor intermediation in California and Texas procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US offsite construction market is approaching a platform-economics inflection as BIM-to-fabrication workflows standardize interoperability between architectural design files and CNC production equipment, collapsing pre-construction coordination layers.
For Market Incumbents: Build captive factory networks across Texas renewable energy corridors to defend against modular dormitory specialists capturing utility-scale workforce housing demand. Anchor automated panel capacity in Houston-Dallas manufacturing clusters. Pursue backward integration into OSB supply to buffer Southeast hurricane reconstruction demand spikes. For New Entrants and Emerging Players: Pacific Northwest mass timber underpenetration offers white-space entry for cross-laminated timber panel fabricators serving Seattle-Portland sustainable multifamily construction. Target Oregon-Washington green building incentive programs. Deploy design-build contracting to bypass established general contractor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated fabrication sub-segments as CNC-guided systems displace conventional framing capacity. Long-term viability favors technology-differentiated regional specialists with BIM-to-production digital threads over undifferentiated scale players. Monitor FHA financing guideline expansion velocity as inflection indicator for affordable housing developer procurement shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fabrication Scale-Up | CNC-guided panel production reduces dimensional variance for California multifamily developers. |
| Direct-to-Developer Channel Expansion | Bypassing general contractor intermediation compresses procurement cycles in urban infill projects. |
| Integrated MEP Prefabrication | Factory-based mechanical-electrical-plumbing rough-in reduces field commissioning complexity. |
| Backward Integration into Engineered Wood | Captive OSB supply buffers Southeast manufacturers against hurricane reconstruction demand spikes. |
| Geographic Manufacturing Footprint Extension | Texas corridor capacity captures renewable energy workforce housing deployment cycles. |
Research Methodology
Operator-level perspectives from modular plant managers, affordable housing developer procurement leads, general contractor operations directors, and FHA lending officers anchored the qualitative base. These primary insights combined with secondary validation from HUD manufactured home construction standards filings, state-level IRC adoption records, and SEC 10-K disclosures from publicly traded manufacturers. Bottom-up capacity utilization assessments and top-down construction spending allocations were triangulated to establish market sizing.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning product type, application, technology, and end-user procurement authority. CAGRs were derived from production capacity expansion trajectories and regional construction permit velocity. Forecast inputs incorporated FHA financing guideline revision schedules and hurricane resilience code adoption patterns.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-differentiated regional specialists or platform-integrator consolidators would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Tanzania Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
US Modular Construction Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
North America Modular Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
France Prefab Homes Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
GCC Green Buildings Market
Building Construction
Mezzanine Floor Market
Building Construction
Qatar Construction Market
Building Construction
Turkey Construction Market
Building Construction
Precast Construction Market
Building Construction
Malaysia Construction Market