
 Aluminum Board Raised Access Floor Market | 2026-2036
Aluminum Board Raised Access Floor Market Size, Share, and Industry Trends Forecast 2026-2036
Aluminum Board Raised Access Floor Market Analytics
Steel substrates is restructuring cost dynamics across the Aluminum Board Raised Access Floor landscape as alloy price volatility pushes specifiers toward hybrid-core alternatives. Tate leverages captive extrusion capabilities to anchor North American supply for mission-critical installations. MERO-TSK sustains German engineering-grade positioning through precision-tolerance panel systems. HUIYA dominates export volumes from Guangdong province with vertically integrated aluminum smelting-to-panel finishing.
An aluminum board raised access floor consists of a die-cast or extruded aluminum panel surface bonded to a steel or aluminum structural core, engineered to provide an elevated, load-bearing platform with integrated cable management and HVAC distribution pathways beneath the walking surface. Panel thickness typically ranges from 28 mm to 40 mm with static load ratings spanning 1,000 kg to 2,500 kg per square meter depending on core geometry and edge trim reinforcement. Heavy-Duty Panels command the dominant share of data center specification activity where concentrated rack loads and rolling equipment traffic exceed standard duty thresholds. Fire-Resistant Panels represent the fastest-growing product type as NFPA 75 and EN 13501-1 compliance becomes non-negotiable for insurance underwriting in Tier III and Tier IV facilities.
China's SAMR enforces GB/T 36340 load capacity testing protocols that restrict market access for uncertified imports, while the EU's Construction Products Regulation mandates CE marking with declared fire reaction class performance. The US FAA issues advisory circulars on raised floor systems for air traffic control centers that exceed commercial building code requirements. Stakeholders must monitor evolving ESG disclosure rules in the EU and China's dual carbon goals, as embodied aluminum emissions reporting reshapes supplier qualification criteria and procurement weighting schemes.
Market Dynamics
Data center thermal density thresholds are forcing specification upgrades across the aluminum board raised access floor market, as hyperscale operators abandon legacy static-load ratings for dynamic-load-certified panels that withstand concentrated rack deployments and continuous rolling equipment traffic.
Growth Catalysts
- GB/T 36340 Certification Mandate:China's SAMR enforcement of load-capacity testing protocols is disqualifying uncertified imports and redirecting procurement toward domestic and pre-qualified international suppliers.
- Hyperscale Data Center Expansion:Cloud operators in East Asian manufacturing clusters are specifying heavy-duty aluminum-core panels to manage concentrated rack loads exceeding standard duty thresholds.
- NFPA 75 Fire Compliance:Insurance underwriters for Tier III and Tier IV facilities are mandating fire-resistant panel systems, accelerating specification-grade procurement cycles.
Market Restraints
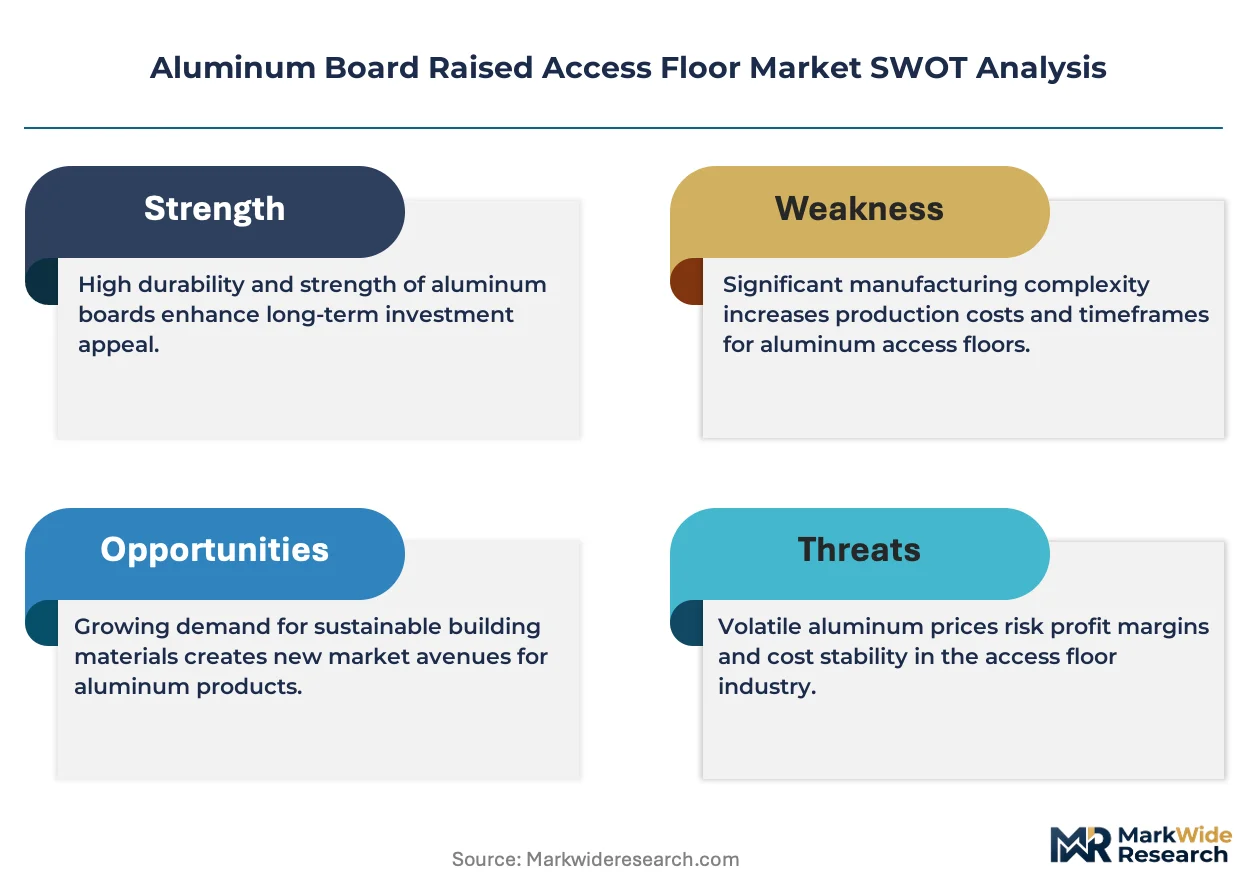
- Aluminum Alloy Price Volatility:LME aluminum price swings are compressing margin structures for extrusion-dependent panel manufacturers and forcing hybrid-core material experimentation.
- East Asian Supply Concentration:Vertically integrated smelting-to-panel production clusters in Guangdong province create geographic vulnerability to regional energy rationing and export control disruptions.
- Steel Substrate Substitution:Cost-conscious specifiers in commercial office retrofits are migrating toward steel-surface access floors for non-mission-critical installations.
Strategic Opportunities
- India Data Center Buildout:PLI scheme incentives for cloud infrastructure are creating specification-grade demand in Mumbai, Hyderabad, and Chennai metro corridors.
- EU Green Deal Embodied Carbon Reporting:ESG disclosure rules are rewarding suppliers with verified low-carbon aluminum sourcing, reshaping procurement weighting schemes.
- Edge Computing Micro-Facilities:Distributed IT deployments in manufacturing plants and telecom huts require compact, rapid-install panel systems with integrated cable management.
Industry Challenges
- Precision Tolerance Manufacturing:German engineering-grade specifications for panel flatness and edge-trim alignment require capital-intensive CNC finishing equipment that mid-tier fabricators struggle to finance.
- CE Marking Timeline Compression:EU Construction Products Regulation fire-reaction class certification delays are extending bid-to-award cycles and freezing project commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aluminum Board Raised Access Floor Market |
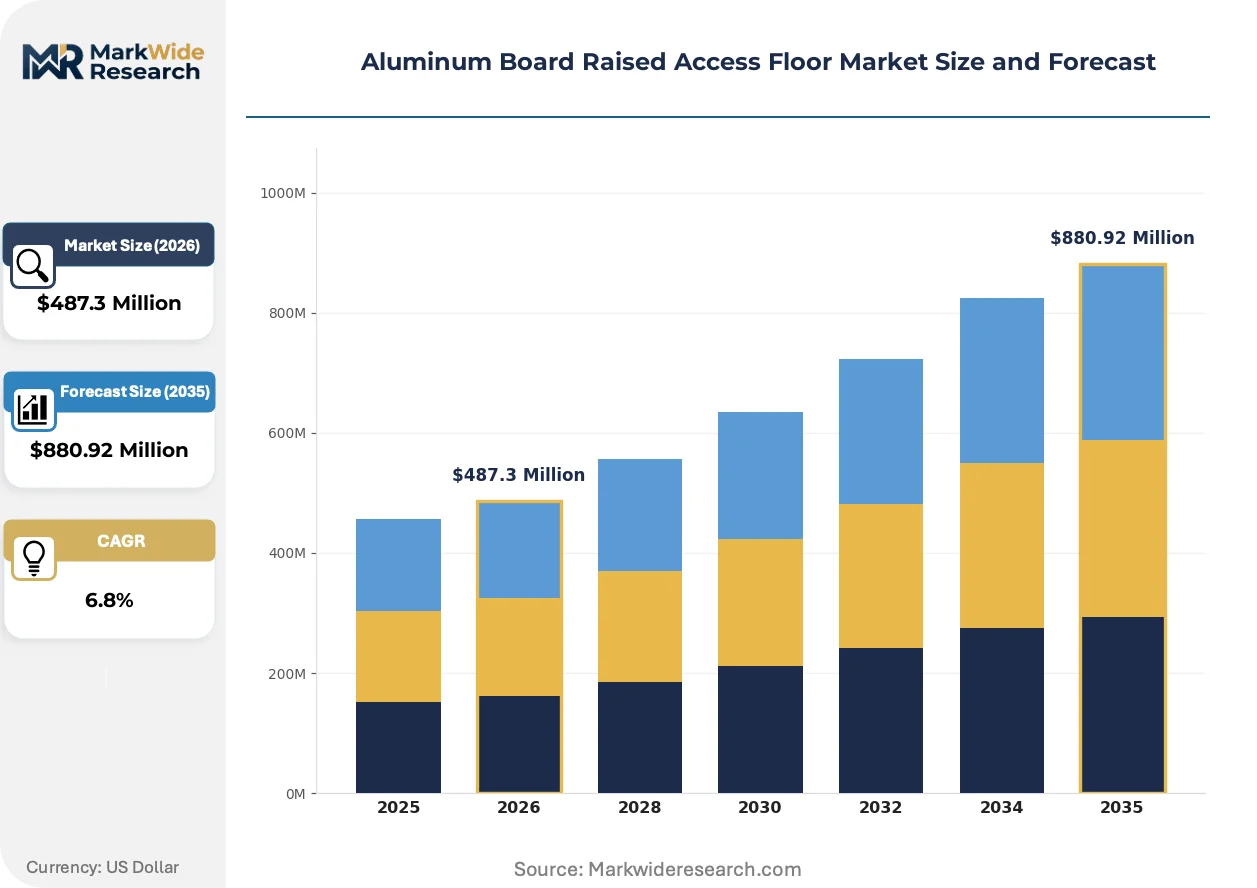
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Panels, Heavy-Duty Panels, Fire-Resistant Panels, Anti-Static Panels Usage Scenario: Commercial Buildings, Data Centers, Educational Institutions, Healthcare Facilities Installation Method: Glue-Down, Click-Lock, Loose Lay, Elevated Load Capacity: Light Duty, Medium Duty, Heavy Duty, Extra Heavy Duty |
| Companies Covered | Polygroup, HUIYA, Tate, DINOR, Rhino Technologies, MERO-TSK, ASP, Lindner, Integra, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aluminum Board Raised Access Floor Market Evolving Landscape
Die-cast aluminum extrusion techniques are converging with steel-core hybridization to produce lighter, higher-load panels that satisfy both thermal management and cable density requirements in hyperscale environments.
Die-cast aluminum panel systems with integrated steel reinforcement cores are unifying structural performance with thermal conductivity optimization. Hyperscale operators in Singapore and Frankfurt are specifying these hybrid constructions for new Tier IV builds. This convergence is unifying previously separate procurement streams for structural and HVAC-integrated flooring into single-source contracts.
REACH restrictions on hexavalent chromium surface treatments are forcing panel finishers to migrate toward trivalent chrome and ceramic conversion coatings. EU-based manufacturers face reformulation costs and supply chain requalification. Heavy-duty panel segments serving Frankfurt and Amsterdam data center corridors are absorbing premium pricing for compliant surface engineering.
Specification-grade buyers are consolidating vendor panels through engineering-procurement-construction contractors rather than direct OEM relationships. Tier 1 EPCs in Northern Virginia and Singapore are pre-qualifying aluminum board suppliers into multi-year framework agreements. This channel compression is most pronounced in hyperscale campus developments where single-source accountability reduces interface risk.
Aluminum Board Raised Access Floor Market Segmentation
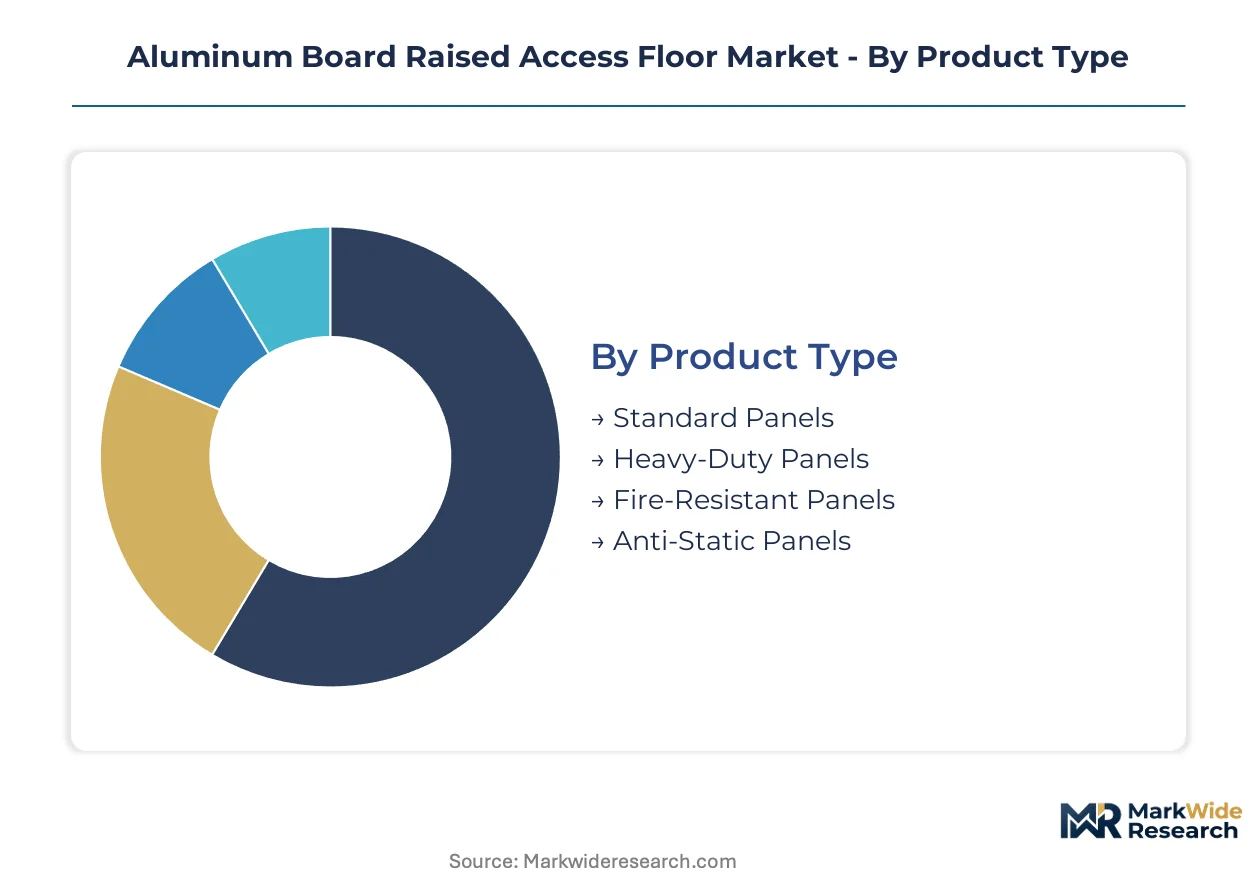
Segmentation in aluminum board raised access floors determines specification pathways, certification burdens, and procurement channel selection. Product type and load capacity classifications dictate which GB/T, NFPA, or EN standards apply, while usage scenario shapes vendor qualification requirements and installation complexity.
Product Type:
Certification requirements fragment sharply across product types, with fire-reaction class testing and dynamic load certification creating divergent compliance timelines for panel manufacturers.
- Heavy-Duty Panels:Extruded aluminum surfaces bonded to steel-reinforced structural cores deliver static load ratings exceeding 2,500 kg per square meter. Hyperscale data centers in Singapore and Northern Virginia specify these for concentrated rack deployments and continuous rolling equipment traffic.
- Fire-Resistant Panels:Intumescent core materials and mineral wool substrates achieve EN 13501-1 A2-s1,d0 or NFPA 75 compliance. Insurance underwriters for Tier III and Tier IV facilities mandate these systems, accelerating specification-grade procurement cycles in Frankfurt and Amsterdam corridors.
- Standard Panels:Die-cast aluminum construction with medium-density cores serves commercial office retrofits where static loads remain below 1,500 kg per square meter.
- Anti-Static Panels:Conductive surface coatings and grounded edge trim dissipate electrostatic discharge for semiconductor cleanroom environments.
Leading the category by volume: Heavy-Duty Panels. Growing fastest: Fire-Resistant Panels.
Usage Scenario:
End-use concentration varies by project scale and performance tier, with mission-critical installations commanding premium specification grades and extended vendor qualification protocols.
- Data Centers:Tier III and Tier IV facilities require dynamic-load-certified panels with integrated cable management and HVAC distribution pathways. Cloud operators in East Asian manufacturing clusters drive specification-grade procurement for new hyperscale campuses.
- Commercial Buildings:Office retrofits and tenant improvements favor standard-duty panels with faster installation cycles and lower per-square-meter installed cost.
- Healthcare Facilities:Infection control protocols and rolling medical equipment traffic demand sealed edge trim and enhanced cleanability surface treatments.
- Educational Institutions:Budget-constrained procurement favors loose-lay installation methods and standard load ratings for computer labs and media centers.
Highest specification intensity: Data Centers. Fastest bid-to-award compression: Commercial Buildings.
Installation Method:
Method selection trades structural permanence against reconfiguration flexibility, with elevated systems dominating mission-critical deployments and adhesive methods penetrating cost-sensitive retrofits.
- Elevated:Pedestal-supported grid systems enable underfloor cable management and HVAC distribution. This method commands data center specification activity where thermal density and infrastructure accessibility are non-negotiable.
- Click-Lock:Interlocking panel edges accelerate installation in edge computing micro-facilities and distributed IT deployments requiring rapid deployment timelines.
- Glue-Down:Permanent adhesion to structural slabs serves healthcare and cleanroom environments where panel displacement risks contamination or equipment damage.
- Loose Lay:Friction-fit panels without mechanical fasteners enable fastest reconfiguration for temporary installations and event spaces.
Dominant by project value: Elevated. Expanding most quickly: Click-Lock.
Load Capacity:
Capacity tiering aligns directly with end-use criticality and equipment density, with concentrated rack loads forcing migration toward higher-duty specifications.
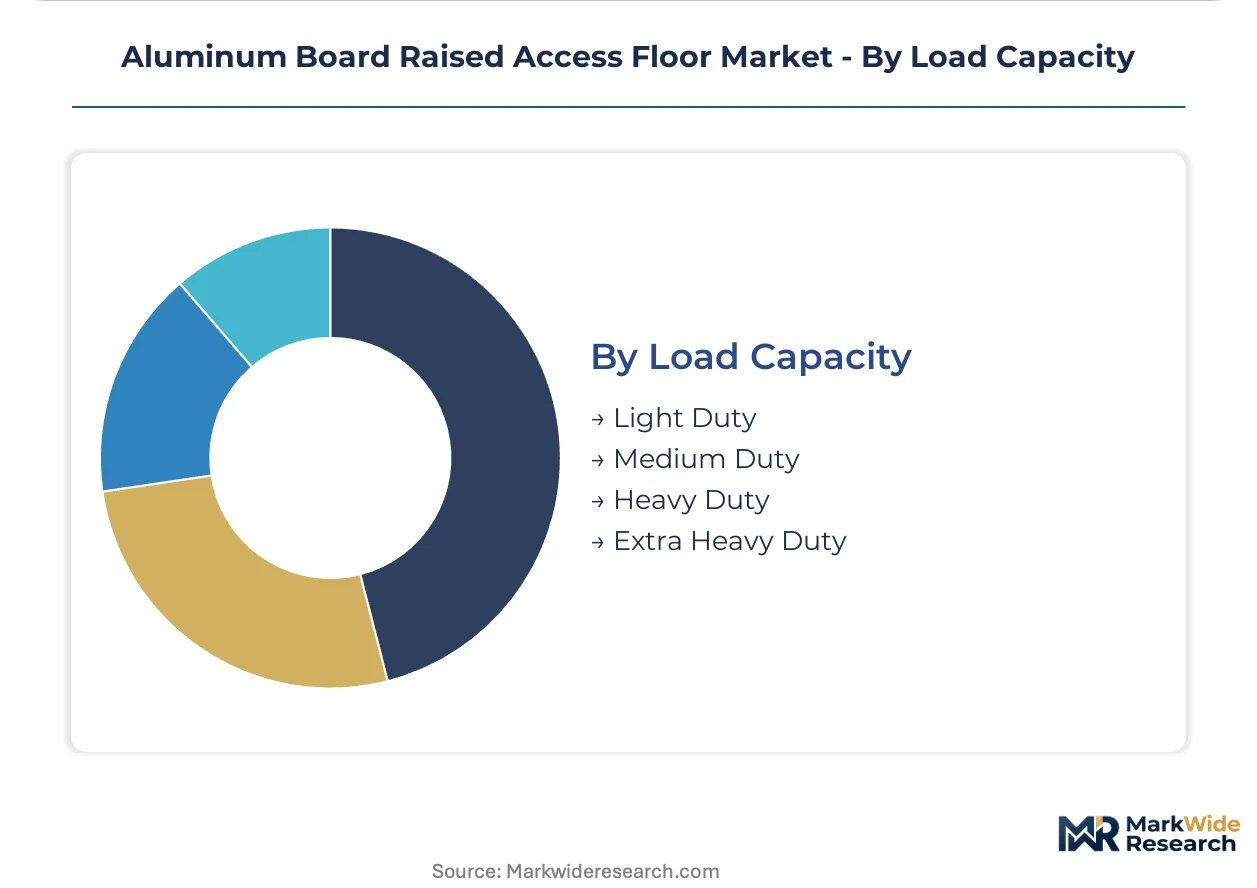
- Heavy Duty:Panels rated 1,500-2,500 kg per square meter satisfy concentrated server rack deployments and continuous rolling traffic. Hyperscale operators specify these for main data halls.
- Extra Heavy Duty:Reinforced core geometries and edge trim configurations exceed 2,500 kg ratings for high-density computing zones and power distribution corridors.
- Medium Duty:1,000-1,500 kg ratings serve general office environments and light equipment rooms where traffic patterns remain intermittent.
- Light Duty:Sub-1,000 kg panels occupy lowest-cost tiers for storage areas, corridors, and non-critical support spaces.
Revenue concentration: Heavy Duty. Steepest expansion trajectory: Extra Heavy Duty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian special economic zones and North American data center tax incentive corridors concentrate procurement for specification-grade aluminum board raised access floor systems.
China
Hyperscale cloud campuses in Guangdong province and Yangtze River Delta semiconductor fabs drive heavy-duty panel demand. SAMR enforces GB/T 36340 load capacity testing protocols that restrict uncertified import access. Shenzhen and Dongguan manufacturing clusters anchor vertically integrated smelting-to-panel production.
United States
Northern Virginia data center alley and Dallas-Fort Worth cloud corridors specify dynamic-load-certified panels for Tier III and Tier IV facilities. FAA advisory circulars for air traffic control centers exceed commercial building code requirements. Ashburn and Manassas sub-markets concentrate hyperscale campus developments.
Germany
Frankfurt and Amsterdam corridor data centers mandate EN 13501-1 fire-reaction class compliance for insurance underwriting. EU Construction Products Regulation CE marking requirements extend certification timelines. Bavaria and Hesse host precision-tolerance panel finishing operations serving engineering-grade specifications.
Singapore
Tropical climate data centers specify corrosion-resistant aluminum-core panels with enhanced thermal conductivity. Energy Market Authority efficiency standards influence HVAC-integrated flooring procurement. Tuas and Changi North industrial zones concentrate new hyperscale builds.
India
PLI scheme incentives for cloud infrastructure create specification-grade demand in Mumbai, Hyderabad, and Chennai metro corridors. BIS certification requirements for building materials tighten import qualification protocols. Maharashtra and Telangana sub-regions lead data center construction permitting.
Aluminum Board Raised Access Floor Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with engineering-grade positioning commanding premium pricing in European corridors while volume-oriented fabricators capture East Asian hyperscale procurement. The vendor base organizes around three strategic archetypes: captive extrusion specialists, precision-tolerance German engineering houses, and vertically integrated Chinese exporters. Capacity expansion and certification pre-qualification represent the dominant competitive vectors as Tier 1 EPCs consolidate supplier panels.
Among North American branded specialists, Tate exemplifies captive extrusion capabilities serving mission-critical installations. MERO-TSK occupies a position within the German engineering-grade tier, representing precision-tolerance manufacturing archetypes. HUIYA anchors the vertically integrated export model from Guangdong province production clusters. These three players illustrate how geographic specialization and backward integration into aluminum smelting shape competitive positioning across procurement channels.
| Leading Market Players |
|---|
| Polygroup |
| HUIYA |
| Tate |
| DINOR |
| Rhino Technologies |
| MERO-TSK |
| ASP |
| Lindner |
| Integra |
| Others |
Value Network & Pricing Analysis
Captive smelting-to-extrusion integration in Guangdong province anchors both supply security and pricing power for Chinese exporters serving hyperscale data center procurement. HUIYA's backward control over aluminum ingot sourcing insulates margin structures against LME volatility while GB/T 36340 certification costs erect compliance barriers that pre-qualified suppliers exploit for premium positioning.
Pricing Analysis
Volume-margins split sharply across duty tiers: heavy-duty panels command project-based contracting with EN 13501-1 or NFPA 75 certification premiums, while standard-duty segments face transactional spot pricing vulnerable to steel-substrate substitution. Price differentiation hinges on fire-reaction class rating and dynamic-load certification status. Cost compression in standard-duty tiers intensifies as commercial office retrofits migrate toward steel-surface alternatives. Data center EPCs exhibit lowest price sensitivity due to single-source accountability requirements; tenant improvement contractors show highest sensitivity to per-square-meter installed cost.
Supply Chain Analysis
Primary aluminum ingot supply rests on Chinese smelters, Russian producers, and Middle Eastern exporters, with secondary alloy sourcing concentrated in European and North American scrap recovery networks. Die-cast extrusion equipment and intumescent core materials constitute critical input dependencies. Single-source vulnerability concentrates in Guangdong province production clusters exposed to regional energy rationing. Distribution runs through Tier 1 EPC framework agreements rather than direct OEM channels for hyperscale campus developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story: GB/T 36340, EN 13501-1, and NFPA 75 certification burdens create barrier-to-entry moats that favor pre-qualified incumbents with capital-intensive testing infrastructure.
For Market Incumbents: Anchor certification pre-qualification pipelines with Tier 1 EPCs in Northern Virginia and Singapore to lock multi-year framework agreements. Defend against steel-substrate substitution by emphasizing dynamic-load certification and thermal conductivity performance in hyperscale specifications. Prioritize captive extrusion capacity additions to maintain margin control against LME volatility. For New Entrants and Emerging Players: Begin with edge computing micro-facility deployments in India and Southeast Asia where rapid-install click-lock systems face lighter certification timelines and less entrenched vendor relationships. Target PLI scheme beneficiaries in Mumbai and Hyderabad corridors with compact panel offerings. Pursue EPC subcontractor qualification rather than direct hyperscale OEM penetration. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to building materials conglomerates seeking data center infrastructure exposure, with secondary IPO routes for scaled Chinese exporters. Long-term viability favors precision-tolerance German engineering houses and vertically integrated Chinese producers with verified low-carbon aluminum sourcing. Watch EU Green Deal embodied carbon disclosure implementation as procurement weighting inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification Investment | GB/T 36340 and EN 13501-1 testing infrastructure locks Tier 1 EPC framework agreements. |
| Backward Integration into Aluminum Smelting | Captive ingot supply from Guangdong clusters insulates margin structures against LME volatility. |
| Fire-Resistant Panel Capacity Expansion | NFPA 75 compliance manufacturing captures insurance-mandated specification-grade procurement. |
| Edge Computing Micro-Facility Product Line | Click-lock rapid-install systems address distributed IT deployments with compressed bid-to-award cycles. |
| Low-Carbon Aluminum Sourcing Verification | EU Green Deal ESG disclosure compliance reshapes supplier qualification criteria in Frankfurt corridor. |
Research Methodology
Multi-period observation of hyperscale data center permitting activity, GB/T 36340 certification issuance rates, and LME aluminum price trajectories anchored the trend analysis, supplemented by interviews with data center EPC procurement directors, raised floor system specifiers, aluminum extrusion plant managers, and SAMR certification auditors. Secondary validation drew from SAMR regulatory filings, EU Construction Products Regulation databases, FAA advisory circulars, and SEC disclosures from listed building materials conglomerates. Bottom-up project pipeline tracking triangulated against top-down construction spend forecasts.
Segment-weighting across product type, load capacity tier, installation method, and usage scenario dimensions shaped the analytical framework. CAGRs derived from regression-adjusted build-out trajectories across hyperscale, colocation, and edge computing facility categories. Forecast inputs incorporated thermal density thresholds, cable management requirements, and regional data center tax incentive program eligibility.
Underlying measurement precision varies by segment; fire-resistant and heavy-duty panel categories carry tighter precision than standard-duty commercial retrofit segments due to certification audit trail density. Forecasts reflect documented assumptions regarding aluminum alloy price bands, regulatory enforcement intensity, and EPC consolidation trends. A small set of triggers warrants ongoing watch: SAMR import restriction expansion, EU embodied carbon reporting implementation, and hyperscale capex cycle inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Opening Trim Weatherstrips Market
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
North America Prefab Wood Building Market
Building & Construction Materials
Italy Prefab Wood Buildings Market
Building & Construction Materials
Acoustic Ceiling Tiles Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
United Kingdom Timber Cladding Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Building Acoustic Insulation Market
Building & Construction Materials
Structural Insulated Panels (Sips) Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Carbon Steel IBC Market
Building & Construction Materials
Foldable Container House Market