
 North America Steel Roofing Market | 2026-2036
North America Steel Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Steel Roofing Market Insights
The Inflation Reduction Act is recalibrating how developers evaluate roofing lifecycle costs across North America. Metal Sales Manufacturing Corporation leverages its extensive distributor network to sustain project flow in the Midwest and Southeast. BlueScope Steel anchors regional supply through its North American mill and coating operations. ATAS International differentiates through architectural panel specialization for commercial facades and roofs.
North America steel roofing comprises coated steel sheet and coil formed into weather-resistant structural coverings, typically manufactured from hot-dip galvanized or Galvalume substrate with minimum yield strengths of 50 ksi, designed to shed precipitation and withstand wind uplift in commercial, industrial, and residential applications. Standing seam panels command premium specification in institutional and high-end commercial projects where weathertight longevity drives value. Corrugated panels dominate agricultural and light industrial volume through lower installed cost and faster erection cycles. Coating type selection increasingly tilts toward Galvalume and Kynar formulations where salt spray resistance and color retention justify higher material outlays.
ICC evaluation reports and UL 580 wind uplift certifications govern product acceptance across U.S. jurisdictions, while Canada's National Building Code and CSA standards enforce comparable performance thresholds. EPA Energy Star and Cool Roof Rating Council specifications shape reflective coating demand in sun-belt states where thermal emittance codes tighten. Stakeholders must track evolving state-level stretch codes and utility rebate structures that reward above-code thermal performance in steel roof assemblies.
Market Dynamics
The Inflation Reduction Act's energy-efficient building incentives are restructuring procurement calculus across North American steel roofing. Contractors now weigh lifecycle thermal performance against first-cost premiums, redirecting specification toward high-emissivity coatings and insulated panel systems in commercial and industrial buildouts.
Growth Catalysts
- IRA Tax Credits:The Inflation Reduction Act's Section 179D deduction accelerates specification of cool roof assemblies meeting Energy Star thresholds in warehouse and distribution center construction.
- Texas Triangle Industrial Buildouts:Manufacturing reshoring and e-commerce fulfillment center expansion across Dallas-Houston-San Antonio corridors concentrates demand for long-span steel roofing systems.
- Galvalume Substrate Advances:Improved aluminum-zinc coating formulations extend service life in coastal and high-humidity environments, expanding addressable markets beyond traditional inland strongholds.
Market Restraints
- Hot-Rolled Coil Volatility:Steel input costs fluctuate with scrap metal pricing and electric arc furnace capacity utilization, compressing fabricator margins on fixed-price contracts.
- Canadian Import Dependencies:Regional supply chains rely on cross-border coil shipments subject to tariff uncertainty and customs processing delays at Michigan and New York entry points.
- Standing Seam Skill Shortages:Specialized seaming equipment and certified installer scarcity limits premium panel uptake in secondary metropolitan markets.
Strategic Opportunities
- Southeast Manufacturing Corridors:Battery plant and automotive supplier facility construction across Georgia, Tennessee, and South Carolina creates demand for fire-resistant roofing in hazardous material zones.
- Utility Rebate Stacking:State-level stretch codes in California, Washington, and New York layer performance incentives atop federal credits for above-code thermal assemblies.
- Building-Integrated Photovoltaics Convergence:Standing seam panels with factory-applied mounting channels streamline solar attachment, reducing balance-of-system costs for commercial rooftop PV.
Industry Challenges
- UL 580 Certification Timelines:Wind uplift testing and ICC evaluation report issuance create 12-18 month product qualification delays for new panel profiles.
- Installer Certification Gaps:Manufacturer-specific training programs for mechanical seaming and concealed fastener systems limit scalable workforce development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Steel Roofing Market |
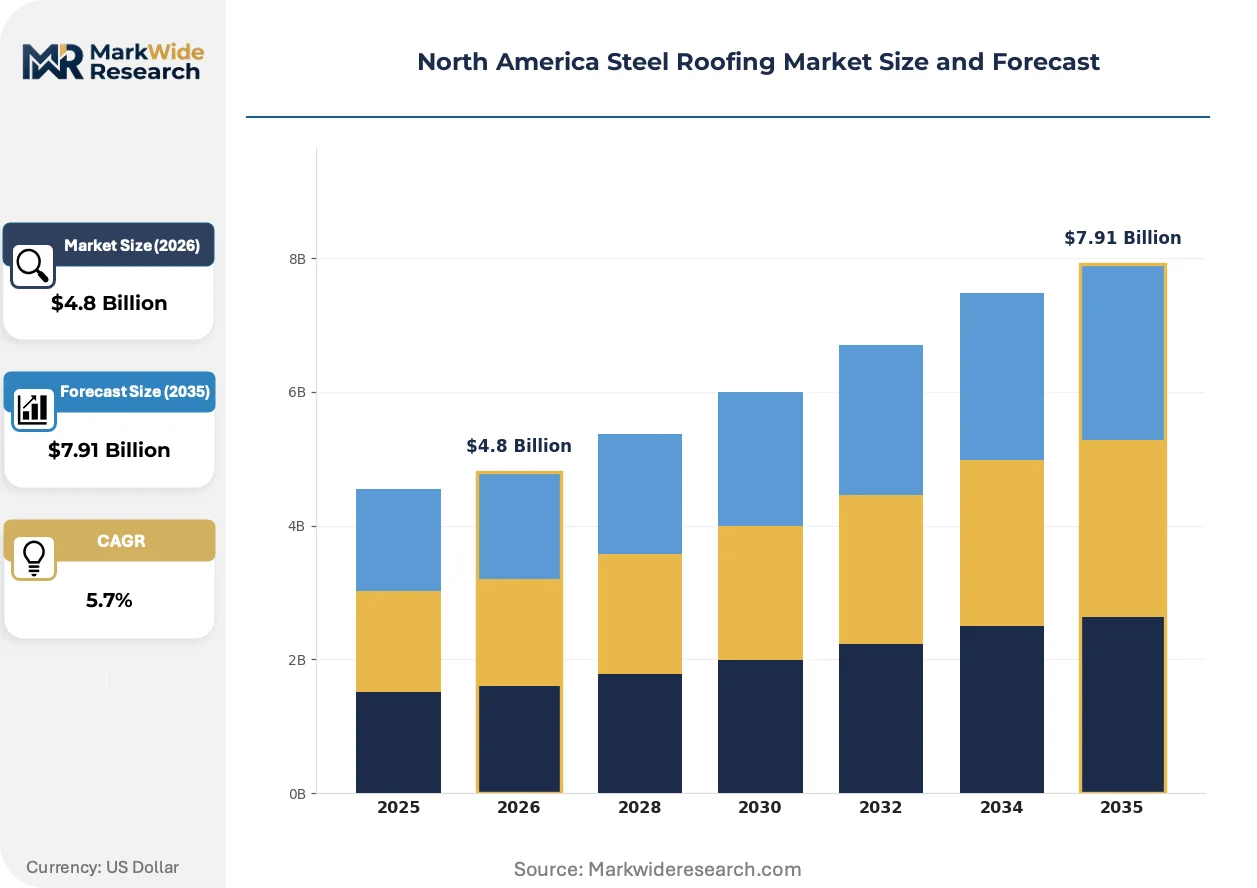
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corrugated Panels, Standing Seam Panels, Tile Sheets, Metal Shingles Installation Method: Self-Adhered, Mechanically Attached, Loosely Laid, Fully Adhered End Use: Residential, Commercial, Industrial, Agricultural Coating Type: Galvalume, Galvanized, Kynar, Polyester |
| Companies Covered | CertainTeed, Metal Sales Manufacturing Corporation, BlueScope Steel, Owens Corning, ATAS International, McElroy Metal, Drexel Metals, TAMKO Building Products, Firestone Building Products, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Steel Roofing Market Trends and Innovations
Digital specification tools and performance-based procurement are compressing traditional sales cycles in North American steel roofing. Material science advances and code evolution are converging to reward thermal performance over installed cost in commercial segments.
Cool roof pigment technology is decentralizing specification authority from architects to energy consultants and utility program administrators. Kynar-based formulations achieving 0.85 solar reflectance and 0.75 thermal emittance now qualify for tiered rebates in California's Title 24 jurisdictions. Building owners in Phoenix, Las Vegas, and Miami increasingly prioritize these metrics over aesthetic matching, compressing the traditional color selection process.
The Inflation Reduction Act's domestic content bonus credits are reshaping supply chain geography for federal and federally-funded projects. Steel roofing assemblies incorporating North American-produced substrate and coating now command preference in GSA schedules and military construction specifications. Fabricators with captive mill relationships or toll-coating agreements near the Great Lakes and Gulf Coast are securing preferred vendor status.
Prefabricated roof panel systems with integrated insulation and air barriers are displacing field-assembled multilayer assemblies in warehouse construction. Design-build contractors in the Texas Triangle and Inland Empire specify these packages to compress erection schedules and reduce weather risk. The model transfers liability to single-source panel suppliers, altering traditional subcontractor relationships and warranty structures in light industrial buildouts.
North America Steel Roofing Market Segmentation
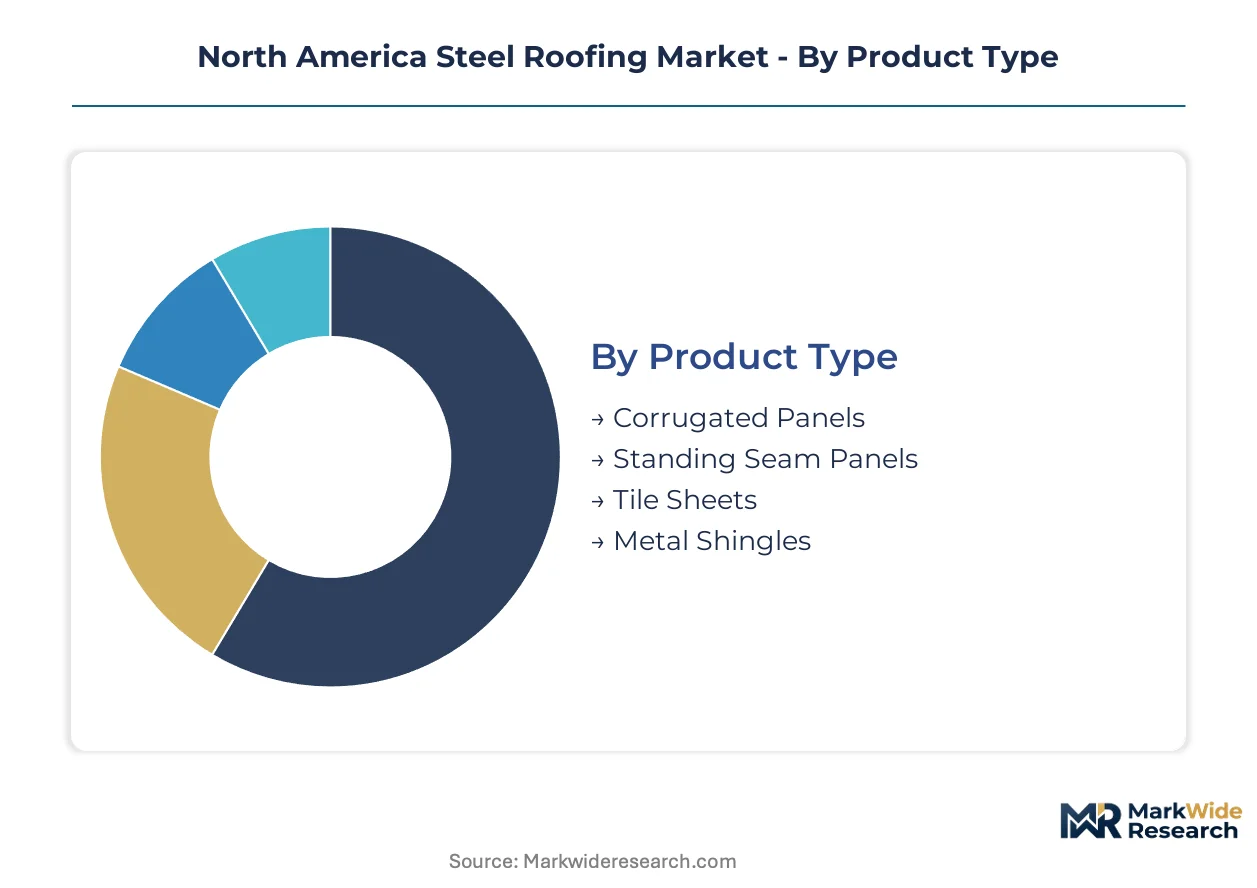
Steel roofing specification in North America fragments across performance tiers, installation complexity, and regulatory exposure. Each segment carries distinct certification burdens and margin profiles that reshape procurement patterns across the Texas Triangle and Southeast manufacturing corridors.
Product Type:
UL 580 wind uplift certification and ICC evaluation reports gate market access unevenly across product categories, with standing seam assemblies facing the most stringent testing protocols while corrugated alternatives qualify through broader product family approvals.
- Standing Seam Panels:Concealed fastener systems with mechanical seaming deliver weathertight performance for institutional and high-end commercial projects. Demand concentrates in Dallas, Houston, and Atlanta data centers where 50-year service life specifications override first-cost premiums. UL 580 Class 90 certification is mandatory for federal and military construction.
- Corrugated Panels:Exposed fastener profiles manufactured from 26-29 gauge substrate dominate agricultural and light industrial volume through rapid erection cycles. Texas Triangle warehouse builders specify these for 500,000+ square foot distribution shells where speed-to-occupancy drives procurement. ICC-ESR reports suffice for most jurisdictions.
- Tile Sheets:Profiled panels mimicking clay or concrete tile aesthetics serve residential retrofit markets in Florida and California. Energy Star reflectance thresholds increasingly filter specification authority to utility rebate administrators rather than architects.
- Metal Shingles:Modular interlocking systems bridge residential asphalt replacement demand with metal durability claims. Southeast hurricane zones drive Miami-Dade County product approval requirements that extend qualification timelines.
Corrugated panels sit at the top of the volume ranking, with standing seam panels climbing the fastest as thermal performance incentives restructure lifecycle cost calculations.
Installation Method:
Cost tier stratification separates field labor intensity from material specification, with mechanically attached systems commanding premium pricing in high-wind zones while self-adhered alternatives capture maintenance and retrofit volume.
- Mechanically Attached:Concealed clip systems anchor standing seam panels to structural substrates with engineered uplift resistance. Gulf Coast commercial projects specify these for 150 mph wind ratings where insurance underwriters mandate proven fastening geometry. Fastener pattern density directly correlates with labor cost and schedule risk.
- Self-Adhered:Peel-and-stick membrane systems streamline residential re-roofing and low-slope commercial recovery applications. California Title 24 jurisdictions favor these for cool roof compliance in single-family retrofit programs with utility rebate stacking.
- Fully Adhered:Bonded assemblies eliminate fastener penetration for maximum weathertight integrity in standing seam valleys and critical detail conditions. Institutional clients in hurricane-prone sub-regions specify these for enhanced warranty coverage.
- Loosely Laid:Ballasted systems retain limited steel roofing application, primarily in temporary or non-structural agricultural shelters where wind exposure permits minimal anchorage.
Mechanically attached systems anchor the largest installed base, with self-adhered methods expanding most quickly in residential energy retrofit programs.
End Use:
Application-specific fire resistance and structural load requirements segment the market across occupancy types, with industrial facilities facing the most demanding hazardous material zone specifications.
- Industrial:Long-span structural systems with factory-insulated panels serve battery plant and automotive supplier construction across Georgia, Tennessee, and South Carolina. FM Global data sheet approvals govern fire-resistant roofing in chemical storage and manufacturing zones. The Inflation Reduction Act's domestic content bonuses concentrate procurement on North American substrate sources.
- Commercial:Cool roof assemblies with Kynar coatings dominate warehouse and distribution center specification in the Inland Empire and Texas Triangle. Section 179D deductions accelerate above-code thermal performance investment.
- Residential:Metal shingles and tile profiles compete with asphalt in replacement markets where insurance discounts for impact resistance offset material premiums. Florida and Texas coastal counties drive demand for 140+ mph wind-rated systems.
- Agricultural:Corrugated panels on rigid frame structures prioritize installed cost over thermal performance in grain storage and livestock facilities across the Midwest and Great Plains.
Industrial end use commands the steepest expansion trajectory, with agricultural applications holding steady volume in replacement cycles.
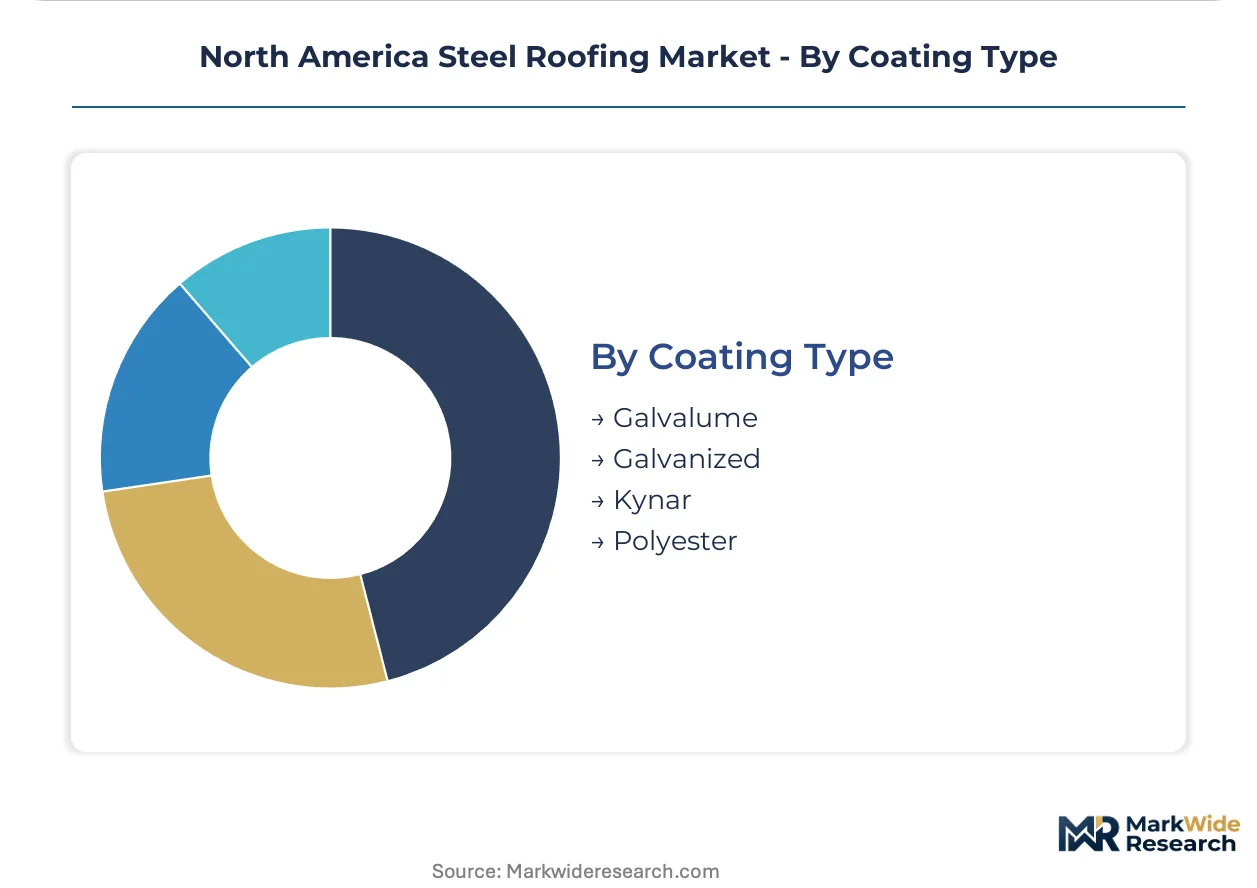
Coating Type:
Margin structure varies sharply by formulation chemistry, with Kynar fluoropolymer systems capturing premium specification in color-critical commercial facades while Galvalume substrate coatings extend service life in high-humidity environments.
- Kynar:PVDF resin-based coatings achieve 0.85 solar reflectance and 0.75 thermal emittance for maximum cool roof rebates in California, Arizona, and Nevada. Architectural panel fabricators specify these for 20-year color retention warranties on institutional projects.
- Galvalume:Aluminum-zinc alloy coatings provide sacrificial corrosion protection extending substrate life in coastal and high-humidity environments. Southeast manufacturing corridor demand favors these for 40+ year service life claims in aggressive atmospheric conditions.
- Galvanized:Zinc coatings retain cost-sensitive agricultural and light industrial specification where interior humidity control limits condensation exposure. Zinc layer thickness (G60, G90, G235) stratifies pricing within the category.
- Polyester:Silicone-modified polyester formulations serve economy-tier residential and agricultural markets with 10-15 year color warranties. Price compression from imports limits domestic manufacturer participation.
Galvalume coatings lead by installed square footage, with Kynar formulations gaining share fastest as thermal emittance codes tighten across sun-belt jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American steel roofing industry traces its modern scaling to post-war industrial construction across the Great Lakes manufacturing belt, where integrated steel mills and sheet metal fabricators established the substrate-coating-forming supply chain that still anchors regional production today.
United States
Texas Triangle warehouse construction and Southeast battery plant buildouts concentrate demand for long-span steel roofing systems. The Inflation Reduction Act's Section 179D deduction accelerates cool roof specification in Dallas-Houston-San Antonio distribution corridors. Georgia, Tennessee, and South Carolina manufacturing zones specify FM Global-approved fire-resistant assemblies for hazardous material handling facilities.
Canada
Cross-border coil shipments from Ontario and Quebec mills supply regional fabricators serving prairie agricultural markets and British Columbia coastal construction. The National Building Code and CSA standards enforce wind uplift and thermal performance thresholds comparable to U.S. jurisdictions. Toronto and Vancouver metropolitan areas drive commercial retrofit demand for above-code insulated panel systems.
Mexico
Nearshoring manufacturing expansion across Nuevo León and the Bajío Region generates demand for industrial roofing in automotive supplier parks and electronics assembly facilities. Mexican construction codes adopt modified versions of ICC evaluation protocols for wind and seismic performance. Monterrey anchors northern Mexico's steel service center distribution network for coated coil processing.
North America Steel Roofing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across coating formulation and certification complexity, with architectural Kynar specialists and standing seam fabricators commanding pricing power over agricultural corrugated suppliers. The vendor base stratifies into three tiers: integrated mill-coating-forming operations with captive substrate supply; independent roll-formers sourcing toll-coated coil; and import-dependent distributors serving price-sensitive replacement markets. Two strategic archetypes dominate: specification-driven architectural panel specialists and volume-driven warehouse construction suppliers. Competitive moves concentrate on distributor network expansion and certified installer program scaling.
Within the integrated mill tier, BlueScope Steel anchors regional substrate supply through its North American coating operations. Metal Sales Manufacturing Corporation exemplifies the distributor-network archetype with extensive Midwest and Southeast coverage. ATAS International occupies a position among architectural specialists focused on commercial facade and roof panel differentiation.
| Leading Market Players |
|---|
| CertainTeed |
| Metal Sales Manufacturing Corporation |
| BlueScope Steel |
| Owens Corning |
| ATAS International |
| McElroy Metal |
| Drexel Metals |
| TAMKO Building Products |
| Firestone Building Products |
| Others |
Pricing and Supply Chain Analysis
Captive mill-coating-forming integration anchors both supply security and pricing power for North American steel roofing fabricators. BlueScope Steel's upstream control over substrate production insulates its downstream panel operations from hot-rolled coil volatility that compresses margins at independent roll-formers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Kynar-coated architectural panels from Galvalume industrial systems from polyester agricultural profiles. Price differentiation hinges on UL 580 certification tier and coating chemistry, with standing seam assemblies commanding substantial premiums over corrugated alternatives. Cost compression in the polyester tier intensifies because of import competition from Asian coil suppliers. Agricultural buyers in the Great Plains exhibit highest price sensitivity, while data center developers in Dallas and Atlanta prioritize lifecycle performance over first cost.
Supply Chain Analysis
Certified installer shortages across the Texas Triangle and Southeast manufacturing corridors constrain standing seam panel deployment despite robust order books. Geographic supply concentration centers on Great Lakes coating operations and Gulf Coast mill complexes, with cross-border Canadian coil shipments feeding regional fabricators. Raw material dependencies draw from scrap metal markets, aluminum-zinc alloy feedstock, and fluoropolymer resin supply. Tariff exposure on Canadian substrate imports creates qualification delays at Michigan and New York entry points. Distribution runs through manufacturer-direct specification for large commercial projects and independent distributor networks for replacement volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America steel roofing market reads as a late-cycle quality story as IRA thermal performance incentives redirect procurement toward certified cool roof assemblies with extended warranty coverage.
For Market Incumbents: To counter margin compression from hot-rolled coil volatility, BlueScope Steel and Metal Sales Manufacturing Corporation should deepen captive substrate supply through toll-coating agreements near the Great Lakes. Certification investment in UL 580 Class 90 and FM Global data sheet approvals for battery plant construction in Georgia and Tennessee secures preferred vendor status in hazardous material zones. For New Entrants and Emerging Players: Building-integrated photovoltaics mounting channel technology offers a technology-first wedge into the standing seam retrofit market, where factory-applied solar attachment hardware reduces balance-of-system costs for commercial rooftop PV. Target the Inland Empire warehouse recovery segment through utility rebate stacking expertise and design-build contractor relationships. White-space exists in prefabricated insulated panel systems for Texas Triangle distribution centers seeking compressed erection schedules. For Investors and Strategic Acquirers: Roll-up economics work for regional roll-formers with certified installer networks because standing seam skill scarcity limits scalable workforce development and creates local monopoly positions. Platform consolidation of independent fabricators in the Midwest and Southeast generates procurement leverage on toll-coated coil supply. Watch IRA domestic content bonus credit enforcement as the inflection indicator for supply chain geography restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Operations | Captive Galvalume and Kynar capacity insulates margins from resin and alloy feedstock volatility. |
| Certified Installer Program Scaling | Manufacturer-specific training for mechanical seaming equipment addresses UL 580 qualification bottlenecks in secondary markets. |
| Prefabricated Insulated Panel Expansion | Factory-integrated air barriers and insulation compress warehouse erection schedules in the Texas Triangle. |
| Utility Rebate Stacking Expertise | California Title 24 and federal Section 179D layering captures above-code thermal performance premiums. |
| Domestic Content Compliance Investment | North American substrate sourcing secures GSA schedule and military construction preference under IRA bonus credits. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each market informing demand calibration. The research combined structured interviews with roofing contractors, distributor procurement managers, coating plant operations directors, and energy consultant specification advisors with secondary validation from EPA Energy Star certifications, UL 580 test reports, ICC evaluation report databases, and state-level utility rebate program filings. Bottom-up project pipeline tracking across the Texas Triangle and Southeast manufacturing corridors triangulated against top-down construction spending data.
Granularity-level modeling deployed product type, installation method, end use, coating chemistry, and regional regulatory cluster as core segmentation dimensions. Value projections across the analysis window derived from unit pricing by performance tier and volume buildups from identified project pipelines. CAGRs were computed from segment-level growth trajectories weighted by current revenue mix. Forecast inputs incorporated IRA incentive phase-in schedules, state stretch code adoption timelines, and manufacturing reshoring facility announcements.
The model holds under sustained IRA credit availability and stable hot-rolled coil supply; deviation in tariff policy on Canadian imports or scrap metal price spikes would shift fabrication margin assumptions and project qualification timelines. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Iron and Steel Casting Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Composite Slate Roofing Market
Building & Construction Materials
Building and Construction Plastic Fasteners Market
Building & Construction Materials
Blanket Insulation Market
Building & Construction Materials
ASEAN Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
Finishing Lines Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
Red Brick Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Polished Concrete Market
Building & Construction Materials
Construction Elastomers Market
Building & Construction Materials
Non-Residential Polished Concrete Market