
 Global HVAC Filter Market | 2026-2036
Global HVAC Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global HVAC Filter Market Foresight
A shortage of certified filtration engineers is redrawing competitive boundaries in the Global HVAC Filter Market. Mann+Hummel leverages its captive R&D infrastructure in Germany to develop multi-layer synthetic media for high-efficiency applications. Filtration Group anchors North American demand through specialized distribution networks serving healthcare and pharmaceutical end users. 3M Company dominates the pleated filter segment with proprietary electret-charged microfiber technology that extends service intervals.
HVAC filters are replaceable porous media devices engineered to remove airborne particulates, volatile organic compounds, and biological contaminants from conditioned air streams, typically rated by minimum efficiency reporting value (MERV) or ISO 16890 ePM classifications based on particle size capture performance. Mechanical filtration using dense glass fiber or synthetic nonwoven mats remains the dominant technology architecture, while UV light purification is gaining traction in healthcare and laboratory applications where microbial control is paramount. HEPA filters command premium positioning in pharmaceutical plants and cleanroom environments where ISO 14644 compliance is mandatory. Pleated filters occupy the volume core across commercial complexes and office spaces, balancing pressure drop performance with disposable convenience.
The EPA's Energy Star certification requirements for HVAC systems and the EU Green Deal's building renovation targets are tightening filter efficiency minimums and accelerating replacement schedules across regulated jurisdictions. China's GB/T 14295 standard for air filters and the NMPA's cleanroom requirements for pharmaceutical manufacturing are reshaping procurement specifications in Asia-Pacific markets. Stakeholders must monitor evolving regional test protocols and energy efficiency thresholds to align product portfolios with diverging compliance landscapes.
Market Dynamics
Regulatory fragmentation across the United States, Germany, and China is forcing manufacturers to maintain parallel certification tracks for MERV, ISO 16890, and GB/T 14295 standards simultaneously, compressing product development timelines and raising compliance overhead.
Growth Catalysts
- Post-pandemic IAQ mandates:US state-level building code amendments in California, New York, and Illinois now mandate MERV-13 minimum filtration in commercial renovations, accelerating replacement cycles in aging office stock.
- EU F-Gas Regulation:Tightening restrictions on fluorinated greenhouse gases are pushing HVAC system redesigns that require higher-efficiency filtration media to compensate for refrigerant performance trade-offs.
- Data center expansion:Hyperscale operators in Ashburn, Frankfurt, and Singapore are specifying ePM1 80%+ filters to protect server environments from corrosive particulate contamination.
Market Restraints
- Glass fiber supply concentration:High-purity borosilicate fiber production clusters in southeastern China, creating single-source vulnerability for HEPA-grade media.
- Electret charge decay:Synthetic microfiber filters lose electrostatic capture efficiency within 90 days in high-humidity environments, limiting service interval extension claims.
- REACH chemical restrictions:ECHA scrutiny of per- and polyfluoroalkyl substances is constraining hydrophobic coating options for moisture-resistant pleated filters.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO cleanroom requirements and PLI scheme incentives are expanding filter demand in Hyderabad and Ahmedabad clusters.
- UV-photocatalytic convergence:Integration of UV-C arrays with titanium dioxide-coated media offers pathogen neutralization beyond mechanical capture in healthcare settings.
- Direct procurement platforms:Facility management software vendors are embedding filter specification tools that bypass traditional distribution tiers for standard pleated products.
Industry Challenges
- Certified filtration engineer scarcity:ISO 16890 test protocol expertise concentrates in German and Swiss laboratories, creating bottlenecks for product validation.
- Legacy building retrofit compatibility:MERV-16 and HEPA specifications often exceed static pressure capacity of pre-1990 air handling units, requiring costly fan upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HVAC Filter Market |
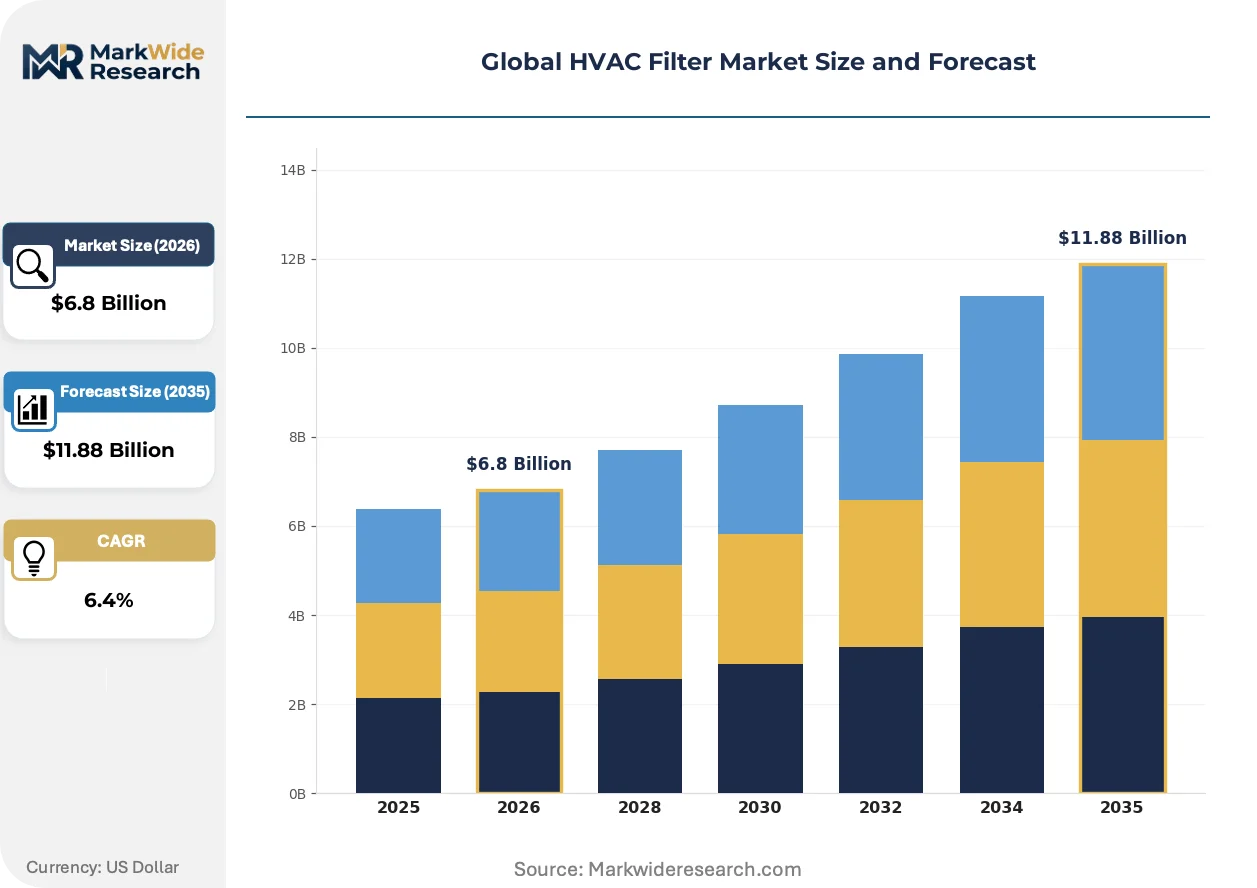
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HEPA Filters, Carbon Filters, Pleated Filters, Electrostatic Filters, Washable Filters Technology: Mechanical Filtration, Media Filtration, Electrostatic Precipitation, UV Light Purification, Ionization Application: Residential Buildings, Commercial Complexes, Data Centers, Educational Institutions, Hospitality Facilities End User Industry: Manufacturing Units, Pharmaceutical Plants, Food Processing, Laboratories, Office Spaces |
| Companies Covered | Mann+Hummel, Filtration Group, 3M Company, Lennox International Inc., American Air Filter Company, Inc., Camfil AB, Donaldson Company, Inc., Freudenberg Filtration Technologies, Parker-Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HVAC Filter Market Shifts & Advancements
Active filtration architectures are fragmenting as end-users weigh energy penalties against capture efficiency, creating openings for novel media formulations and hybrid purification systems.
Electret-charged synthetic nonwoven media is decomposing the traditional glass fiber dominance in commercial MERV 8-13 applications. Property managers in Dallas and Atlanta are specifying these lighter-weight alternatives to reduce HVAC fan energy consumption. The technology is decomposing incumbent supply relationships as regional converters gain capability to produce competitive grades without proprietary licensing.
The EU Green Deal's building renovation targets are tightening minimum filter efficiency thresholds across member states. France's RE2020 environmental regulation and Germany's Buildings Energy Act are mandating higher-grade filtration in deep renovation projects. Pharmaceutical manufacturers in Basel and Lyon are responding by pre-qualifying ePM1 85%+ suppliers ahead of scheduled facility upgrades.
Facility managers are consolidating filter procurement through integrated workplace management platforms that automate specification matching and reorder triggers. Commercial real estate operators in London and Sydney are displacing traditional distributor relationships with API-connected direct fulfillment. Healthcare systems in Ontario are piloting this model for standardized pleated filter categories while retaining specialist distributors for HEPA cleanroom applications.
Global HVAC Filter Market Segmentation
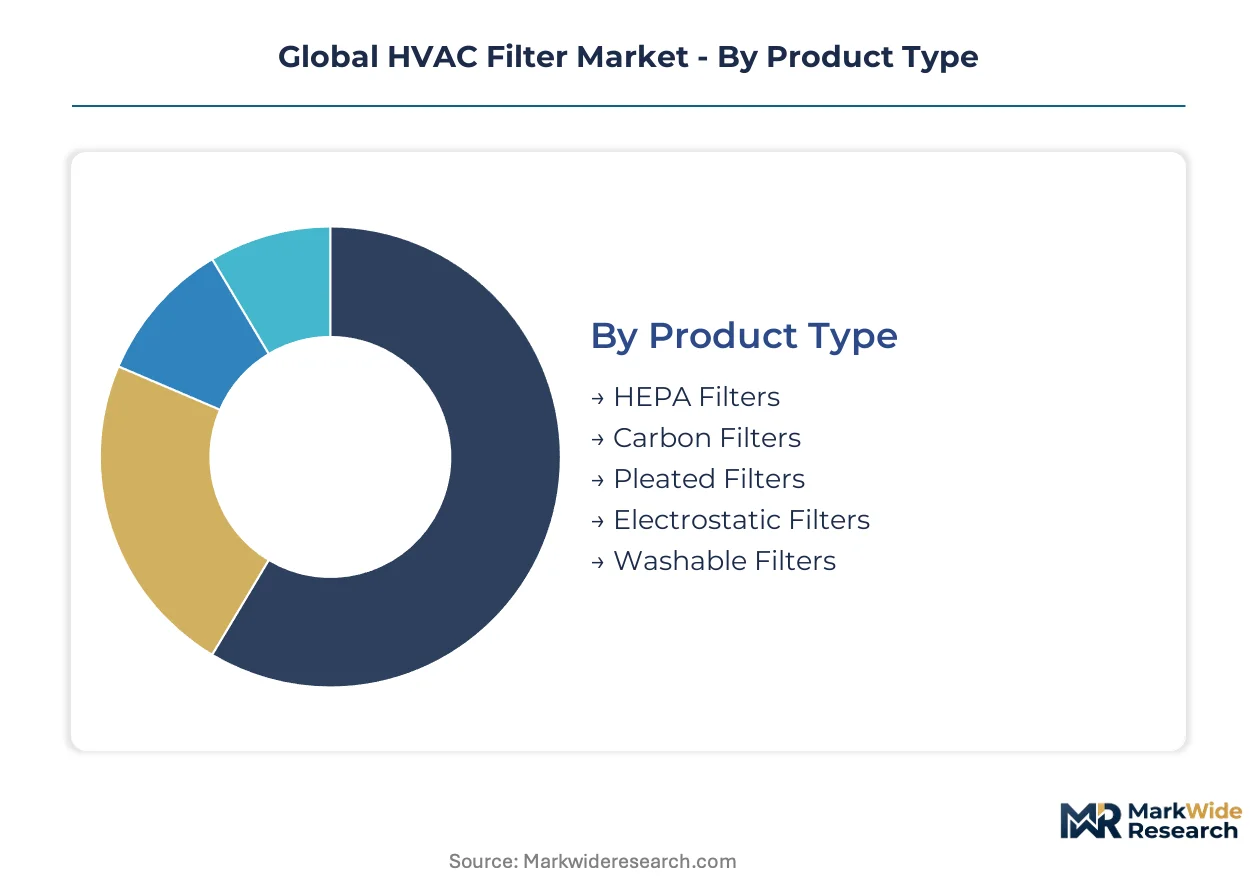
Filter specification varies sharply across end-use environments, with pharmaceutical cleanrooms demanding HEPA-grade capture while commercial offices prioritize pressure-drop economics. Understanding where margin pools concentrate within each dimension enables manufacturers to align R&D investment with procurement willingness-to-pay.
Product Type:
Margin pools concentrate in certified high-efficiency grades where validation protocols create switching costs, while standard pleated products compete on logistics scale.
- HEPA Filters:Dense glass fiber or PTFE membrane media rated for 99.97% capture at 0.3 microns, mandatory for ISO 14644 cleanrooms in Basel pharmaceutical clusters. Demand concentrates in Singapore biologics manufacturing where NMPA-aligned inspections require documented filter integrity testing.
- Pleated Filters:Synthetic nonwoven media in cardboard or metal frames, dominating commercial building retrofits in Dallas and Chicago where MERV-13 mandates meet legacy air handler constraints. Property managers specify these for balance of capture efficiency and disposable convenience.
- Carbon Filters:Activated carbon impregnated media targeting VOC and odor removal in hospitality and food processing settings.
- Electrostatic Filters:Permanently charged synthetic fibers or wire-plate configurations, gaining traction in residential HVAC upgrades.
- Washable Filters:Aluminum mesh or foam constructions, specified in industrial pre-filtration stages where particulate loading is coarse and water-based cleaning is practical.
The dominant share belongs to pleated filters, while HEPA filters are closing the gap fastest through pharmaceutical capacity expansion.
Technology:
Technology selection tracks end-use contamination risk, with healthcare and data center operators accepting energy penalties for capture certainty while commercial buildings optimize for fan load reduction.
- Mechanical Filtration:Dense fiber mats physically blocking particles, the baseline architecture for HEPA and ULPA grades in Swiss pharmaceutical cleanrooms. Basel manufacturers specify borosilicate glass fiber depth-loading designs where service life directly correlates with production uptime.
- UV Light Purification:UV-C arrays integrated into air handlers for microbial neutralization, expanding in Toronto hospital renovations where CSA Z317.2 ventilation standards emphasize pathogen control beyond mechanical capture.
- Media Filtration:Synthetic nonwoven depth filters, the workhorse for commercial MERV 8-13 applications.
- Electrostatic Precipitation:Ionization-based particle charging and collection, deployed in heavy industrial environments with high dust loading.
- Ionization:Bipolar ion generators for airborne pathogen reduction, piloted in Atlanta educational facilities.
Mechanical filtration retains the largest installed base, though UV light purification is expanding most quickly in healthcare specification.
Application:
Application-driven procurement splits between mission-critical environments with zero-tolerance contamination protocols and cost-sensitive volume segments with standardized replacement cycles.
- Data Centers:ePM1 80%+ and chemically impregnated media protecting server hardware from corrosive sulfur and salt particulates, with hyperscale operators in Ashburn and Frankfurt specifying 6-month replacement intervals regardless of pressure-drop readings.
- Commercial Complexes:MERV 11-13 pleated filters in office towers across New York and London, where post-pandemic lease negotiations now embed IAQ commitments requiring documented filtration maintenance.
- Residential Buildings:Standard pleated and fiberglass panel filters, price-sensitive segments with limited specification engagement.
- Educational Institutions:MERV-13 minimum upgrades in California and Illinois public school districts, funded through state facility modernization bonds.
- Hospitality Facilities:Carbon-integrated pleated designs addressing guest room odor control alongside particulate capture.
Commercial complexes command the greatest procurement volume, yet data centers are gaining share fastest through hyperscale construction.
End User Industry:
End-user industry segmentation reflects regulatory intensity, with pharmaceutical and food processing facing mandatory HACCP and GMP filtration standards that standard office environments escape.
- Pharmaceutical Plants:Terminal HEPA filtration in Grade A/B cleanrooms, with Lyon and Hyderabad manufacturers pre-qualifying dual-certified suppliers to both EU GMP Annex 1 and CDSCO requirements ahead of scheduled capacity additions.
- Food Processing:High-temperature resistant pleated media and activated carbon for odor control, mandatory under FDA Food Safety Modernization Act preventive controls for facilities in Wisconsin and California Central Valley.
- Manufacturing Units:Heavy-duty pre-filters and bag filters for industrial dust control, specified by automotive and electronics producers.
- Laboratories:HEPA and ULPA grades for research containment, with BSL-3 facilities requiring documented filter integrity.
- Office Spaces:Standard commercial pleated filters, the most price-competitive segment with procurement consolidation through facility management platforms.
Pharmaceutical plants anchor premium segment profitability, while food processing is climbing the fastest through regulatory enforcement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA mandates and aging commercial infrastructure anchor United States demand, while EU F-Gas Regulation and tightening ISO 16890 standards reshape procurement cycles across European installations.
United States
Post-pandemic indoor air quality mandates and MERV-13 minimum requirements in California, New York, and Illinois accelerate replacement cycles. EPA Energy Star certification tightens efficiency thresholds for HVAC systems. Dallas and Chicago property managers specify pleated filters balancing capture performance with legacy air handler constraints.
Germany
The EU F-Gas Regulation pushes HVAC system redesigns requiring higher-efficiency filtration media. Germany's Buildings Energy Act mandates upgraded filtration in deep renovation projects. Mann+Hummel leverages captive R&D infrastructure in German facilities to develop multi-layer synthetic media for high-efficiency applications.
China
GB/T 14295 standards for air filters reshape procurement specifications alongside NMPA cleanroom requirements for pharmaceutical manufacturing. High-purity borosilicate fiber production clusters in southeastern China create single-source vulnerability for HEPA-grade media. Data center operators in Singapore specify ePM1 80%+ filters sourced through regional supply chains.
India
CDSCO cleanroom requirements and PLI scheme incentives expand filter demand in pharmaceutical manufacturing. Hyderabad and Ahmedabad clusters pre-qualify dual-certified suppliers to EU GMP Annex 1 and domestic standards ahead of capacity additions. State facility modernization bonds fund MERV-13 upgrades in educational institutions.
United Kingdom
Commercial real estate operators in London displace traditional distributor relationships through API-connected direct fulfillment platforms. Post-pandemic lease negotiations embed IAQ commitments requiring documented filtration maintenance. Healthcare systems pilot automated procurement models for standardized pleated categories.
Global HVAC Filter Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the market structure consolidating around filtration technology conglomerates and regional application specialists. Three archetypes dominate: diversified industrial conglomerates with captive filtration divisions, pure-play air quality specialists, and automotive suppliers extending HVAC filtration capabilities. Competitive moves concentrate on strategic partnerships for distribution access and portfolio diversification into active purification technologies.
Among Germany-based filtration conglomerates, Mann+Hummel GmbH exemplifies the integrated R&D-intensive archetype. Filtration Group anchors North American positioning through specialized distribution networks. 3M Company represents the materials science conglomerate model, occupying a position in electret-charged media segments where proprietary microfiber technology extends service intervals.
| Leading Market Players |
|---|
| Mann+Hummel |
| Filtration Group |
| 3M Company |
| Lennox International Inc. |
| American Air Filter Company, Inc. |
| Camfil AB |
| Donaldson Company, Inc. |
| Freudenberg Filtration Technologies |
| Parker-Hannifin Corporation |
| Others |
Supply & Pricing Matrix
Electret-charged synthetic media substitution for borosilicate glass fiber is redrawing supply geography toward Southeast Asian converter clusters while compressing premium capture margins in commercial MERV 8-13 segments. This material transition simultaneously erodes legacy glass fiber pricing power in Germany and Switzerland while elevating synthetic nonwoven throughput in Vietnam and Thailand.
Pricing Analysis
Price spreads between German-certified HEPA grades and Chinese-produced commercial pleated filters exceed 400% at wholesale, reflecting ISO 16890 validation costs against commodity MERV-13 volume production. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier and documented integrity testing. Cost compression in standard pleated tiers is intensifying because regional converters in Vietnam now replicate electret-charged formulations without proprietary licensing. Healthcare and pharmaceutical buyers show lowest price sensitivity due to GMP compliance requirements, while property managers in Dallas and Atlanta drive aggressive standard-tier negotiation.
Supply Chain Analysis
Inventory buffers for high-purity borosilicate fiber have compressed to six-week levels following southeastern China production disruptions, exposing HEPA-grade media to allocation risk. Supply concentrates in China for glass fiber raw material, Germany for multi-layer synthetic R&D, and Vietnam for electret-charged converter output. Finished filter assembly draws from aluminum frame stamping in Mexico, cardboard fabrication in Poland, and final pleating in regional hubs proximate to demand. Single-source vulnerability in Chinese borosilicate fiber creates structural risk for pharmaceutical cleanroom specifications. Distribution runs through specialized HVAC distributors in North America, integrated facility management platforms in the United Kingdom, and direct procurement channels for hyperscale data center operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ISO 16890 test protocol expertise scarcity in German and Swiss laboratories creates asymmetric capability advantages for incumbent validation holders, constraining competitive entry in certified high-efficiency segments.
For Market Incumbents: Compound captive R&D infrastructure advantages by securing dual-certification capacity for both EU GMP Annex 1 and CDSCO requirements ahead of Indian pharmaceutical expansion. Deepen backward integration into electret-charged synthetic media production to defend margin position against Vietnamese converter encroachment in commercial MERV 8-13 tiers. For New Entrants and Emerging Players: CDSCO fast-track certification partnerships with Hyderabad pharmaceutical clusters offer the most penetrable entry vector for HEPA-grade suppliers lacking EU validation heritage. Target data center ePM1 80%+ specifications in Frankfurt and Singapore where hyperscale operators prioritize documented integrity testing over incumbent brand loyalty. Pursue direct procurement platform API integration to bypass legacy distributor markups in standardized pleated categories. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated filtration conglomerates with captive synthetic media R&D and multi-regional certification assets. Long-term viability hinges on exposure to pharmaceutical and data center end-use rather than commercial building retrofit cyclicality. Monitor ECHA REACH restriction progression on per- and polyfluoroalkyl substances as inflection indicator for hydrophobic coating technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Pre-qualification for EU GMP Annex 1 and CDSCO requirements secures Indian pharmaceutical expansion participation. |
| Backward Integration into Synthetic Media | In-house electret-charged production defends margin compression from Vietnamese converter competition. |
| Direct Procurement Platform Integration | API connectivity with facility management software vendors displaces traditional distributor relationships in commercial segments. |
| UV-Photocatalytic Convergence Development | Integration of UV-C arrays with titanium dioxide-coated media addresses healthcare pathogen neutralization beyond mechanical capture. |
| Regional Converter Acquisition | Thailand and Vietnam synthetic nonwoven capacity acquisition accelerates commercial MERV 8-13 market share capture. |
Research Methodology
Operator-level perspectives from facility managers at hyperscale data centers, pharmaceutical cleanroom engineers, HVAC maintenance directors, and procurement leads at commercial real estate investment trusts anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EPA Energy Star certification databases, EU ECHA REACH restriction filings, and ISO 16890 test laboratory accreditation records. Bottom-up demand modeling triangulated against top-down regulatory impact assessment across the analysis window.
Sensitivity analysis across filter efficiency tier, end-use application, and regional regulatory cluster shaped the analytical framework throughout the forecast period. Segmentation dimensions modeled include product type, technology architecture, application environment, and end-user industry vertical. CAGRs were derived from replacement cycle acceleration factors tied to MERV-13 mandate enforcement and F-Gas Regulation system redesign requirements. Industry-specific inputs incorporated pharmaceutical capacity expansion timelines and data center construction pipelines.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement intensity and stable borosilicate fiber supply; material deviation in REACH restriction scope or Chinese production allocation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Water Softener Equipment Market
HVAC Equipment
Canada Outdoor Air Source Heat Pump Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
United Kingdom HVAC Market
HVAC Equipment
Latin America Heat Exchanger Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
Warm Air Heater Market
HVAC Equipment
Italy HVAC Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
HVAC Pumps Market
HVAC Equipment
Water Chiller Market
HVAC Equipment
Air Humidifier and Dehumidifier Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Scrubber Dryer Market
HVAC Equipment
Shell and Tube Heat Exchangers Market
HVAC Equipment
Helical Screw Blowers Market