
 Germany Construction Chemicals Market | 2026-2036
Germany Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Construction Chemicals Market Foresight
Public infrastructure authorities and asset management firms is bifurcating demand away from traditional residential developers across Germany. BASF SE anchors its position through backward integration into polymer feedstocks for admixtures. Sika AG dominates specification-driven channels for structural strengthening and waterproofing systems. Evonik Industries AG differentiates via high-performance silane chemistry for surface treatment applications.
Germany construction chemicals encompass formulated additives and protective systems blended to modify cementitious substrates, with typical admixture dosages ranging from 0.5% to 5% by weight of cement content. These formulations extend service life, accelerate curing, or impart hydrophobicity to concrete and masonry structures. Admixtures and waterproofing agents command the largest volume positions given their ubiquity in transport infrastructure and commercial foundations. Protective coatings and surface treatment chemicals capture disproportionate margin pools due to stringent durability specifications under Germany's federal energy renovation mandates. Grouts and sealants occupy narrower but defensible niches in tunneling and industrial flooring rehabilitation.
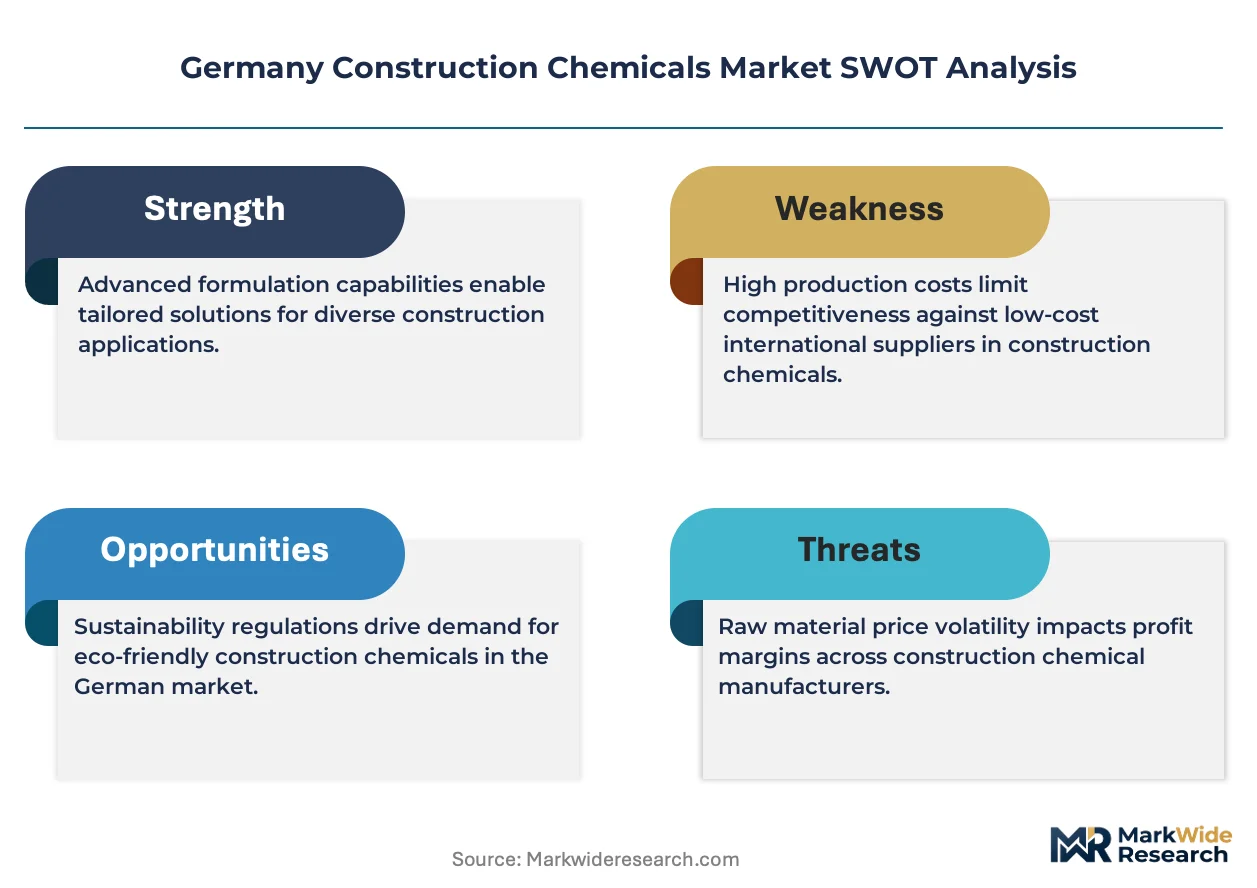
Germany's construction chemicals sector operates under REACH chemical registration requirements, the national Building Energy Act (GEG) transposing EU efficiency directives, and KBA-influenced infrastructure material standards for transport assets. ECHA substance restrictions and GEG thermal performance thresholds are tightening permissible formulations and driving reformulation cycles across sealants and insulation binders. Stakeholders must monitor forthcoming EU-wide carbon footprint disclosure rules for construction products and assess how embodied carbon metrics will reshape specification criteria for federal procurement.
Market Dynamics
Federal infrastructure procurement under Germany's Building Energy Act (GEG) is compressing specification cycles and forcing rapid reformulation of cement modifiers across admixture portfolios.
Growth Catalysts
- Transport infrastructure rehabilitation:KBA-influenced durability standards for bridges and tunnels mandate high-performance waterproofing systems across Bavaria and North Rhine-Westphalia.
- EU Green Deal retrofit mandates:Thermal renovation obligations under national building codes are accelerating specification of low-carbon grouts and insulation binders in commercial building envelopes.
- Silane chemistry advancement:Hydrophobic surface treatments are penetrating industrial flooring and heritage restoration segments previously served by conventional sealants.
Market Restraints
- Petrochemical feedstock volatility:Polymer precursors for superplasticizers and latex modifiers face price instability tied to naphtha and propylene supply disruptions.
- REACH registration burdens:ECHA substance evaluation timelines extend 18-36 months for novel silane and epoxy formulations, delaying commercialization.
- Substitution by geopolymers:Alkali-activated binders in select infrastructure applications are displacing Portland cement systems that require chemical admixtures.
Strategic Opportunities
- Eastern federal state penetration:Saxony and Thuringia transport corridors remain underdeveloped relative to western industrial clusters for structural strengthening contractors.
- Carbon disclosure readiness:Anticipated EU-wide embodied carbon reporting for construction products creates first-mover advantage for manufacturers with lifecycle-assessed formulations.
- Digital specification platforms:BIM-integrated material selection tools are displacing traditional architect-specifier relationships in federal procurement channels.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in silane-epoxy hybrid systems and low-VOC acrylic binders commands premium compensation and lengthens R&D timelines.
- Multi-certification complexity:Concurrent GEG energy performance, KBA infrastructure durability, and ECHA REACH compliance requires parallel testing streams that compress margin structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Construction Chemicals Market |
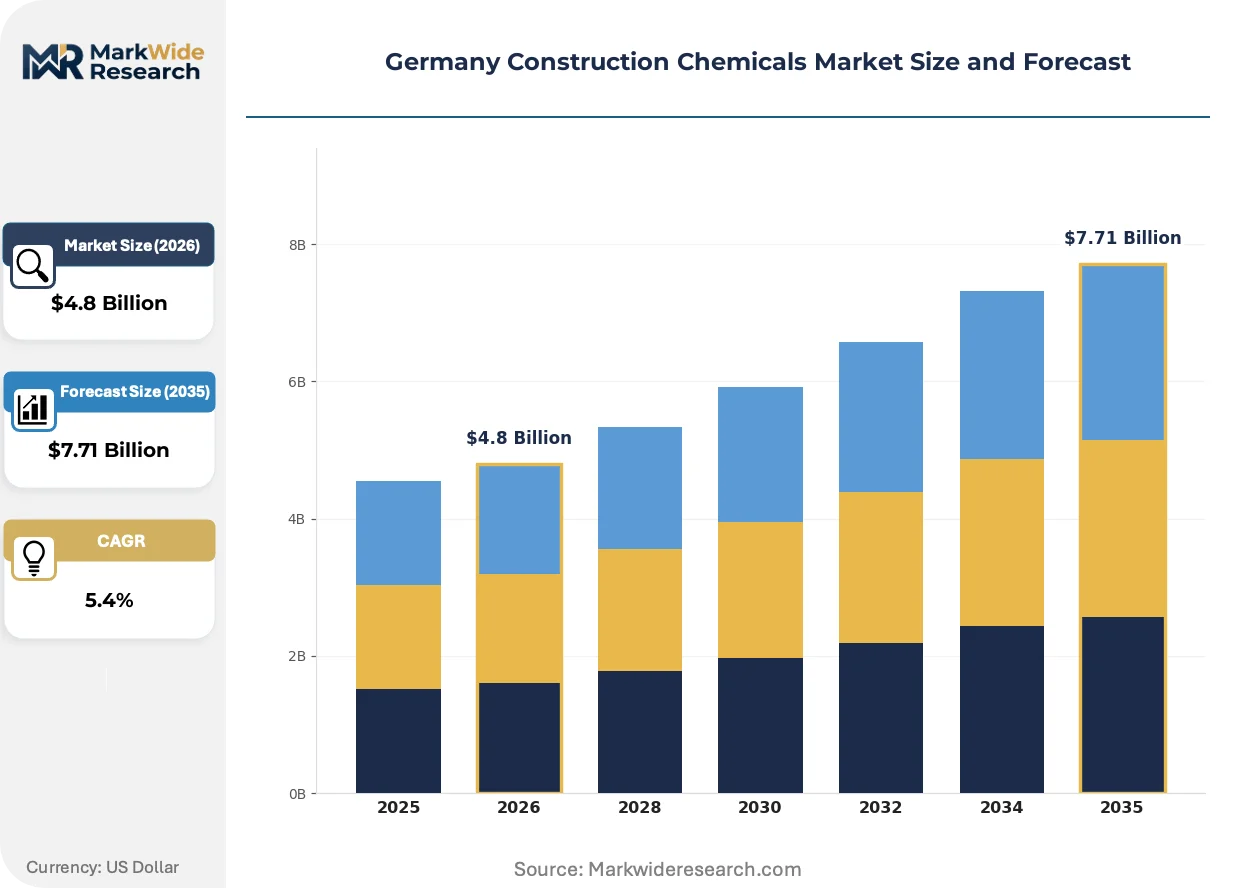
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Sealants, Waterproofing Agents, Surface Treatment Chemicals, Protective Coatings, Grouts Application: Concrete Repair, Flooring, Masonry, Structural Strengthening, Anti-Corrosion, Thermal Insulation End User Industry: Commercial Construction, Residential Developers, Infrastructure Projects, Asset Management Firms Distribution Channel: Specialty Distributors, Direct Sales, Retailers, Online Marketplaces |
| Companies Covered | Evonik Industries AG, MAPEI SpA, BASF SE, Remmers GmbH, MC-Bauchemie Müller GmbH & Co. KG, Sika AG, Lanxess AG, Wacker Chemie AG, Henkel AG & Co. KGaA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Construction Chemicals Market Shifts & Advancements
Digital tools and low-carbon chemistry are compressing traditional specification hierarchies while opening new service models around performance guarantees rather than product sales.
Self-healing concrete admixtures incorporating encapsulated bacterial spores or mineral precursors are advancing from demonstration projects to commercial specification. Municipal water infrastructure authorities in Hamburg and Stuttgart are piloting these systems for sewer and reservoir assets. The technology is miniaturizing repair intervention cycles from decades to years, shifting maintenance liability toward chemical suppliers.
Germany's transposition of EU energy efficiency directives through the GEG is tightening permissible thermal conductivity thresholds for renovation materials. Sealant and insulation binder manufacturers face mandatory reformulation to meet lambda-value specifications in commercial envelope retrofits. Bavarian housing associations are accelerating procurement of compliant systems ahead of 2030 enforcement milestones.
Asset management firms and federal procurement offices are consolidating specification authority previously dispersed among regional contractors. Direct vendor relationships with large-scale infrastructure operators are displacing traditional distribution through merchant builders in transport and industrial construction. This concentration is most pronounced in North Rhine-Westphalia's Rhine-Ruhr logistics corridor, where volume commitments now drive pricing negotiations.
Germany Construction Chemicals Market Segmentation
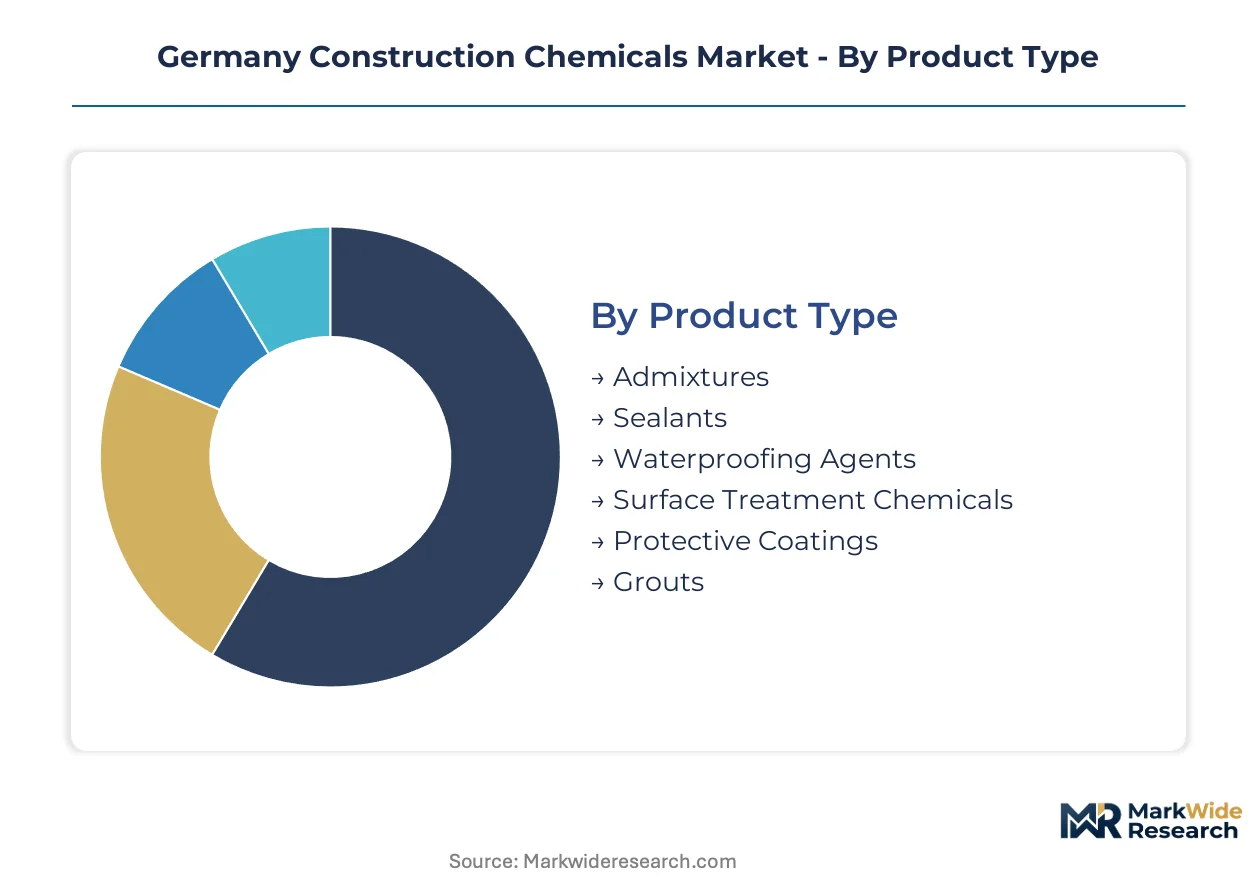
Germany's construction chemicals market fragments across product chemistry, application specificity, and procurement channel. Segment boundaries are blurring as waterproofing admixtures and surface treatments converge under unified performance specifications mandated by KBA infrastructure standards and GEG energy codes.
Product Type:
Margin pools concentrate in high-specification formulations where REACH registration costs and technical service requirements erect barriers to commodity competition.
- Admixtures:Superplasticizers and retarders modify cement hydration kinetics at dosages between 0.5% and 5% by weight. Transport infrastructure authorities in Bavaria and North Rhine-Westphalia specify polycarboxylate-ether based systems for high-strength concrete in bridge decks and tunnel linings. KBA-influenced durability standards are compressing specification cycles and forcing rapid reformulation of cement modifiers.
- Waterproofing Agents:Crystalline and hydrophobic pore-blocking formulations command premium positioning in below-grade commercial foundations and municipal water infrastructure. Hamburg and Stuttgart municipal authorities are piloting advanced systems for sewer and reservoir assets, shifting maintenance liability toward chemical suppliers.
- Sealants:Polyurethane and silicone formulations for movement joints and expansion control in building envelopes.
- Surface Treatment Chemicals:Silane and siloxane penetrants imparting hydrophobicity to masonry and concrete substrates without altering surface appearance.
- Protective Coatings:Epoxy and polyurethane film-forming systems for industrial flooring and chemical containment structures.
- Grouts:Cementitious and epoxy injection materials for crack repair and structural void filling in tunnel rehabilitation.
Admixtures hold installed capacity. Waterproofing agents are rotating up the share rankings.
Application:
Volume concentrates in repair and rehabilitation applications where Germany's aging infrastructure stock and GEG retrofit mandates sustain procurement regardless of new construction cycles.
- Concrete Repair:Injection grouts, patching compounds, and corrosion inhibitors address chloride-induced deterioration in bridge substructures and parking garages. Asset management firms in the Rhine-Ruhr corridor are consolidating specification authority and driving direct vendor relationships for high-volume repair programs.
- Structural Strengthening:Carbon fiber-reinforced polymer bonding systems and epoxy injection protocols restore load capacity to deteriorated concrete elements. Bavarian transport authorities specify these systems for autobahn bridge upgrades under federal infrastructure procurement.
- Flooring:Self-leveling underlayments and industrial coating systems for manufacturing and logistics facilities.
- Masonry:Consolidants, water repellents, and cleaning agents for heritage restoration and facade maintenance.
- Anti-Corrosion:Cathodic protection and coating systems for steel reinforcement in marine and de-icing salt environments.
- Thermal Insulation:Adhesive and protective finish systems for external thermal insulation composite systems in building envelope retrofits.
Concrete repair absorbs the largest procurement volumes. Structural strengthening is gaining share fastest as bridge replacement costs escalate.
End User Industry:
Procurement authority is migrating from dispersed regional contractors toward consolidated asset owners and federal procurement offices.
- Infrastructure Projects:Federal and state transport authorities specify construction chemicals for autobahn, rail, and water infrastructure under KBA-influenced material standards. North Rhine-Westphalia's Rhine-Ruhr logistics corridor generates concentrated demand for high-performance waterproofing and structural strengthening systems.
- Asset Management Firms:Institutional owners of commercial and industrial property portfolios are internalizing specification decisions previously delegated to general contractors. Direct vendor relationships with large-scale infrastructure operators are displacing traditional distribution through merchant builders.
- Commercial Construction:Office, retail, and logistics facility developers procuring materials for new build and renovation.
- Residential Developers:Multi-family housing construction with specification constrained by cost-driven procurement.
Infrastructure projects command the deepest technical specifications. Asset management firms are rotating up the share rankings as portfolio-scale procurement consolidates.
Distribution Channel:
Channel economics diverge sharply between specification-driven infrastructure procurement and price-sensitive residential construction.
- Direct Sales:Technical service-intensive products including structural strengthening systems and self-healing concrete admixtures move through manufacturer-direct relationships with asset owners and federal procurement offices. Specification authority concentration in North Rhine-Westphalia and Bavaria favors this channel for high-value systems.
- Specialty Distributors:Regional distributors with formulation expertise and local technical support serve mid-tier commercial contractors and municipal maintenance programs.
- Retailers:Hardware and builders merchant channels for standard sealants, grouts, and surface treatments in residential renovation.
- Online Marketplaces:Emerging procurement route for standardized products with established performance documentation.
Direct sales holds installed capacity. Specialty distributors are rotating up the share rankings as mid-tier commercial procurement consolidates regionally.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German construction chemicals flow primarily toward domestic infrastructure authorities and asset management firms across federal states, with limited export orientation toward neighboring EU construction markets.
Bavaria
Autobahn bridge rehabilitation and tunnel lining projects drive specification of polycarboxylate-ether superplasticizers. KBA-influenced durability standards mandate high-performance waterproofing systems for transport infrastructure. Munich and Nuremberg metropolitan clusters concentrate procurement authority for federal highway maintenance programs.
North Rhine-Westphalia
Rhine-Ruhr logistics corridor generates concentrated demand for structural strengthening and industrial flooring systems. Asset management firms consolidate specification decisions previously delegated to regional contractors. Düsseldorf and Cologne serve as procurement hubs for portfolio-scale commercial envelope retrofits under GEG thermal renovation mandates.
Baden-Württemberg
Automotive manufacturing facilities sustain industrial flooring and chemical containment coating procurement. The state's building energy codes accelerate low-carbon grout specification in commercial renovations. Stuttgart municipal authorities pilot self-healing concrete admixtures for water infrastructure assets.
Lower Saxony
Offshore wind foundation construction and port infrastructure expansion drive marine-grade protective coating demand. ECHA REACH compliance timelines extend reformulation cycles for epoxy-based systems. Hamburg harbor authorities specify high-performance anti-corrosion systems for steel reinforcement in salt-exposed environments.
Hesse
Frankfurt commercial real estate portfolios sustain thermal insulation adhesive procurement for facade retrofit programs. Federal procurement offices centralize specification authority for large-scale renovation frameworks. Rhine-Main logistics hubs generate maintenance chemical demand for warehouse flooring rehabilitation.
Germany Construction Chemicals Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive polymer feedstock positions. Three tiers structure competitive positioning: multinational diversified chemical groups with backward integration into naphtha derivatives, mid-cap construction specialists with specification-driven technical service capabilities, and regional formulation houses serving price-sensitive renovation segments. Dominant competitive moves include M&A targeting silane chemistry specialists and capacity expansion for low-VOC acrylic binder production.
Among Germany-based chemical conglomerates, BASF SE, Evonik Industries AG, and Lanxess AG exemplify the integrated archetype with upstream control over polymer precursors. Sika AG and MC-Bauchemie Müller GmbH & Co. KG occupy positions within the specification-intensive tier, anchoring technical service relationships with federal infrastructure authorities. MAPEI SpA represents the specialist multinational with concentrated construction chemicals focus. Remmers GmbH, Wacker Chemie AG, and Henkel AG & Co. KGaA sit within differentiated niches spanning surface treatments, silicone chemistry, and adhesive systems respectively.
| Leading Market Players |
|---|
| Evonik Industries AG |
| MAPEI SpA |
| BASF SE |
| Remmers GmbH |
| MC-Bauchemie Müller GmbH & Co. KG |
| Sika AG |
| Lanxess AG |
| Wacker Chemie AG |
| Henkel AG & Co. KGaA |
| Others |
Supply & Pricing Matrix
Polycarboxylate-ether superplasticizer capacity utilization in Bavaria and North Rhine-Westphalia anchors regional price floors, compressing margin structures for mid-tier admixture suppliers while concentrating procurement leverage among federal infrastructure authorities with volume-scale commitments.
Pricing Analysis
Next-generation silane-epoxy hybrid formulations command 40-60% premiums over conventional acrylic sealants, while legacy Portland cement modifiers face commoditization pressure from alkali-activated binder substitution. Three-tier pricing structure across premium, standard, and economy levels stratifies by REACH registration tier and KBA durability certification. Price erosion runs through standard-grade waterproofing agents as Eastern European imports penetrate Saxony and Thuringia markets. Asset management firms exhibit lowest price sensitivity given lifecycle-cost procurement frameworks, whereas residential developers remain highly cost-responsive.
Supply Chain Analysis
Germany and the Netherlands anchor polymer precursor production for superplasticizers and latex modifiers, with Belgium serving as the primary naphtha derivatives hub for the Rhine-Ruhr industrial cluster. Formulation chemistry draws from propylene oxide, ethylene oxide, and specialty silane monomers. Single-source vulnerability concentrates in silane feedstocks where Evonik and Wacker maintain dominant positions. Distribution runs through manufacturer-direct channels for specification-intensive structural strengthening systems, with specialty distributors handling mid-tier commercial procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemist scarcity in silane-epoxy hybrid systems compresses R&D timelines and inflates compensation premiums, creating structural bottlenecks for manufacturers attempting rapid GEG-compliant reformulation cycles.
For Market Incumbents: Consolidate technical service capabilities around KBA-influenced infrastructure procurement channels in Bavaria and North Rhine-Westphalia, while accelerating backward integration into naphtha derivatives to offset petrochemical feedstock volatility. Defensive positioning requires parallel GEG energy performance and REACH registration investments to maintain specification authority against emerging low-carbon grout specialists. For New Entrants and Emerging Players: Lead with carbon disclosure readiness as a first-mover wedge in anticipated EU-wide embodied carbon reporting frameworks, targeting underdeveloped Eastern federal state transport corridors in Saxony and Thuringia. Specification-driven penetration favors BIM-integrated material selection platforms that displace traditional architect-specifier relationships in federal procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors silane chemistry specialists with captive monomer supply and established ECHA registration portfolios. Long-term viability hinges on lifecycle-assessed formulation libraries that align with tightening thermal performance thresholds. The inflection signal to monitor is EU-wide carbon footprint disclosure rule finalization for construction products.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive naphtha derivative supply insulates BASF and Lanxess from propylene price volatility. |
| Green Manufacturing Transition | Low-VOC acrylic binder capacity expansion aligns with GEG thermal renovation mandates. |
| Long-term Supply Agreement | Volume commitments with North Rhine-Westphalia asset management firms compress competitor access. |
| Joint Venture | BIM platform partnerships with federal procurement offices displace traditional distribution channels. |
| Acquisition of Specialist Firm | Silane chemistry targets fill formulation gaps in heritage restoration and industrial flooring segments. |
Research Methodology
The analysis maps admixture, waterproofing, sealant, and surface treatment sub-sectors, each validated through technical R&D directors, federal procurement officers, plant managers at integrated chemical conglomerates, and distribution channel partners. Primary interview intelligence triangulates against customs and trade data, Cefic sector reports, SEC 10-K filings, and KBA infrastructure material standards. Bottom-up volume modeling reconciles with top-down federal construction expenditure frameworks.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions include product chemistry grade, end-use application specificity, procurement channel type, and federal state concentration cluster. CAGRs derive from infrastructure rehabilitation cycle analysis and GEG retrofit mandate implementation trajectories. Silane chemistry advancement rates and geopolymer substitution penetration serve as industry-specific forecast sensitivity inputs.
Forecasts assume regulatory continuity in REACH registration requirements and GEG thermal performance thresholds; material policy shifts in ECHA substance restrictions or EU carbon disclosure rules would require re-modeling. Specific risks include petrochemical feedstock supply disruptions, formulation chemist labor market tightening, and alkali-activated binder technology maturation. Recalibration cycles align with material shifts in federal infrastructure procurement volumes and energy code enforcement milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Artificial Wood Beams Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
North America Luxury Vinyl Tile (LVT) Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
Construction Bolts Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
Education Building Design Market
Building & Construction Materials
Asia Pacific Sanitaryware Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
Decorative Tiles Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
PVC Window Market