
 Steel Processing Market | 2026-2036
Steel Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Processing Market Intelligence
Process optimization software-as-a-service is decoupling the sale of processed steel from the provision of ongoing yield management and quality control services. ArcelorMittal leverages its global footprint to serve multinational construction and automotive clients. Nucor Corporation specializes in electric arc furnace production, aligning with North American recycling infrastructure. China Baowu Steel Group dominates with immense production scale, influencing raw material procurement globally.
Steel processing transforms crude steel into finished or semi-finished products through methods like rolling, coating, and heat treatment. This involves shaping steel at temperatures above its recrystallization point for hot-rolled products or below it for cold-rolled steel to achieve specific mechanical properties and surface finishes. Hot Rolled Steel constitutes a foundational volume segment due to its widespread use in construction. Higher-margin applications in machinery and energy equipment drive demand for specialized Alloy Steel and Galvanized Steel products.
Regulations such as the EU's Carbon Border Adjustment Mechanism (CBAM) and China's dual carbon goals are reshaping production economics. Simultaneously, adherence to ISO 9001 quality standards and specific GB standards in China is critical for market access and supply chain qualification. Processors must now balance investments in decarbonization technologies with the need to maintain cost competitiveness in a fragmented market.
Market Dynamics
The central tension in steel processing is the concurrent push for decarbonization via EAFs and the demand from machinery sectors for high-strength alloys, which challenges traditional production routes and investment cycles.
Growth Catalysts
- Infrastructure Programs:India's national infrastructure pipeline creates volume demand for construction-grade steel, benefiting processors of long products.
- Automotive Lightweighting:The electric vehicle transition requires advanced high-strength steels to offset battery weight, pulling demand for specialized cold-rolled products.
- EAF Technology Shift:Sustainability goals under the EU Green Deal encourage investment in Electric Arc Furnace production, leveraging regional scrap availability.
Market Restraints
- Input Cost Volatility:Unpredictable pricing for metallurgical coal and iron ore creates margin pressure for operators of traditional blast furnaces.
- Carbon Pricing Mechanisms:The EU's Carbon Border Adjustment Mechanism imposes reporting burdens and potential tariffs, affecting the economics of imported steel.
- EAF Production Limits:Electric Arc Furnaces face challenges in producing certain ultra-high-purity grades without access to high-cost direct reduced iron.
Strategic Opportunities
- Hydrogen Economy Components:The build-out of hydrogen infrastructure requires specialized alloy steels for high-pressure storage tanks and pipelines.
- Digital Service Models:Process optimization software-as-a-service unbundles yield management from physical steel sales, creating recurring revenue.
- Southeast Asian Manufacturing:Supplying specialized steels to the region's expanding automotive and electronics sectors presents a geographic growth opportunity.
Industry Challenges
- Decarbonization Capital:Retrofitting mills or building new facilities with low-carbon technologies like EAFs requires massive, long-term capital investment.
- Specialized Talent Scarcity:A shortage of metallurgists and data scientists hinders the management of automated processing lines and quality control systems.
- Divergent Standards Compliance:Processors must navigate different global standards, such as ISO 9001 and China’s GB standards, to ensure market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Processing Market |
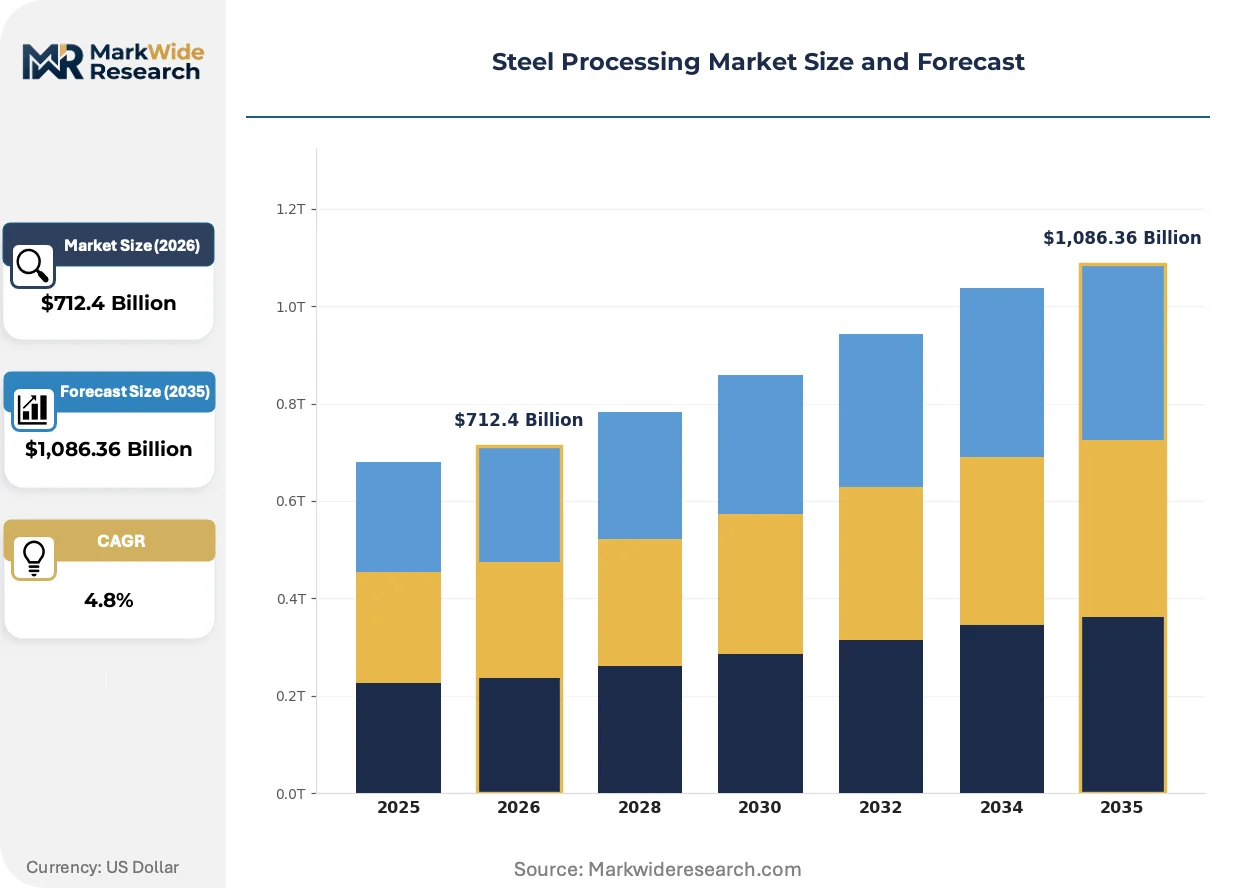
| Market Size in 2026 | $712.4 Billion |
| Market Size in 2035 | $1,086.36 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled Steel, Cold Rolled Steel, Galvanized Steel, Stainless Steel, Alloy Steel Technology: Continuous Casting, Electric Arc Furnace, Oxygen Steelmaking, Induction Furnace, Vacuum Degassing Application: Construction, Shipbuilding, Machinery, Energy Equipment, Household Appliances End User: Manufacturers, Fabricators, Infrastructure Developers, Equipment Suppliers, Tool Makers |
| Companies Covered | ArcelorMittal, China Baowu Steel Group, Nippon Steel Corporation, POSCO Holdings, Nucor Corporation, Tata Steel, JSW Steel, Steel Dynamics, Ansteel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Processing Market Strategic Shifts & Innovations
The industry's evolution is defined by the dual forces of digitalization in production and intensifying sustainability pressures. These elements are fundamentally altering process economics and the basis of competition among steel processors.
AI-driven process control software provides real-time adjustments for rolling mills and heat treatment furnaces. Producers of high-margin alloy and galvanized steels are the primary adopters, seeking to improve consistency. This advanced software is automating quality assurance and yield optimization, significantly reducing material waste and energy consumption per ton.
China's "dual carbon" policy framework is accelerating the closure of older, less efficient blast furnaces. This national strategy directly incentivizes investment in scrap-fed Electric Arc Furnace capacity. The production economics for long products used in domestic construction are most affected, favoring processors with established access to high-quality scrap material.
A shift towards unbundling services from physical steel sales is gaining traction among large buyers. Automotive and construction customers increasingly source commodity steel from one vendor while contracting separately with specialists for services like just-in-time processing. This procurement pattern is most visible in North America and Europe.
Steel Processing Market Segmentation
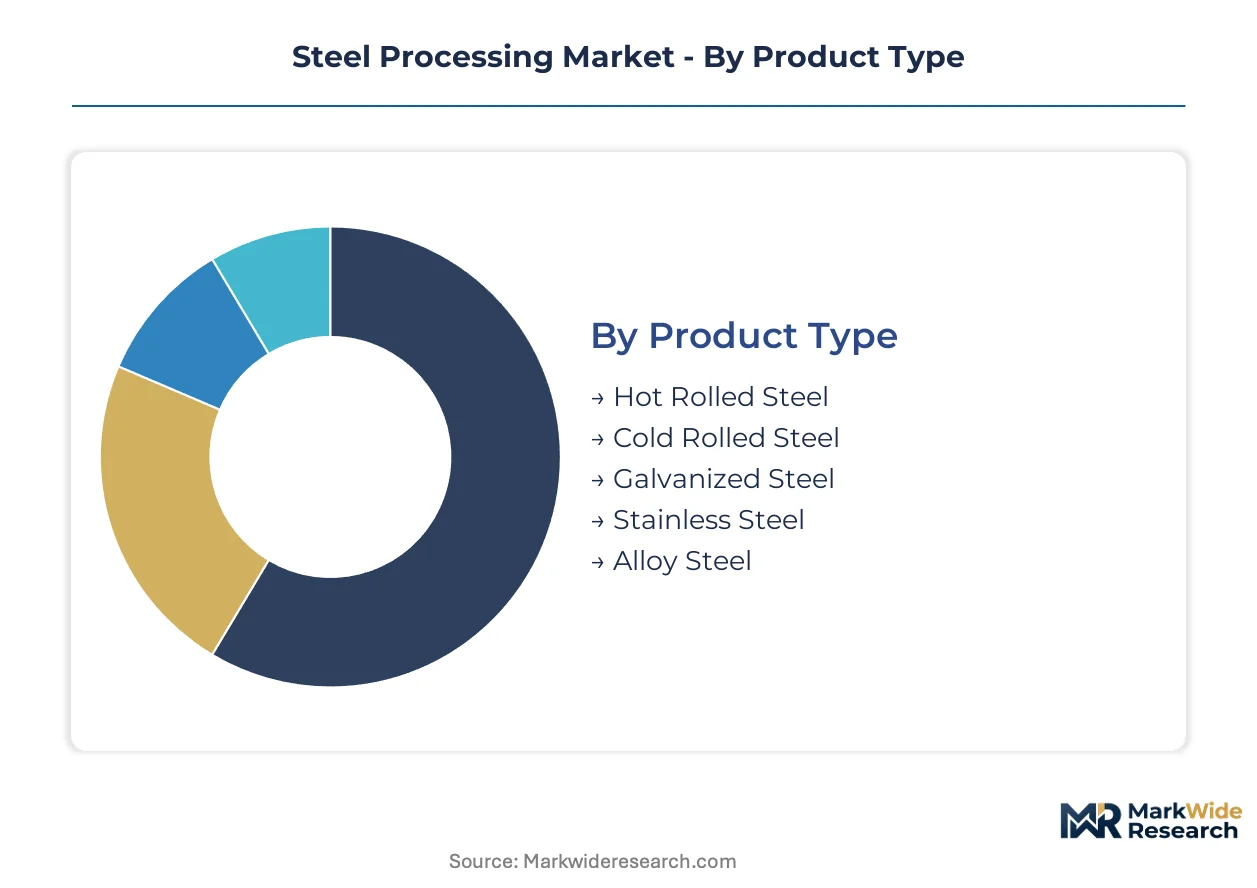
Segmentation of the steel processing market illuminates the specialized demands across various industrial applications. Understanding product types, technologies, applications, and end-users is essential for processors to align production with specific market needs. This granular view highlights areas of high growth and technological advancement.
Product Type:
Compliance with stringent quality standards like ISO 9001 and specific GB standards in China is critical for product types, particularly for specialized steels used in regulated industries.
- Hot Rolled Steel:Foundational product formed at high temperatures, offering ductility and ease of fabrication. Demand concentrates in construction and infrastructure programs in India due to its cost-effectiveness and structural suitability.
- Alloy Steel:Contains additional elements like chromium, nickel, or molybdenum to enhance strength and corrosion resistance. Automotive lightweighting initiatives in Europe drive demand for specialized high-strength alloy steels.
- Cold Rolled Steel:Processed at room temperature for improved surface finish, dimensional accuracy, and strength. Automotive and appliance manufacturing require its superior aesthetic and mechanical properties.
- Galvanized Steel:Coated with zinc for enhanced corrosion protection, making it suitable for outdoor and corrosive environments. Construction and automotive body panels widely utilize this durable material.
- Stainless Steel:Known for its high corrosion resistance and aesthetic appeal due to chromium content. Food processing equipment and architectural applications frequently specify stainless steel.
Hot Rolled Steel sits at the top of the volume ranking, with Alloy Steel climbing the fastest.
Technology:
The maturity of steel processing technologies varies significantly, influencing capital expenditure and operational efficiency across different production scales.
- Electric Arc Furnace:Utilizes electric current to melt scrap steel, offering a more sustainable and flexible production route. Investment in EAF technology is concentrating in North America and Europe, driven by decarbonization goals and regional scrap availability.
- Continuous Casting:A highly efficient process that solidifies molten steel into semi-finished products directly, reducing energy consumption and production steps. Global steel production relies heavily on continuous casting for its economic benefits and product consistency.
- Oxygen Steelmaking:A primary steel production method using oxygen to refine molten iron into steel, common in integrated mills.
- Induction Furnace:Employs electromagnetic induction to melt metals, often used for specialized alloys and smaller batch production.
- Vacuum Degassing:Removes dissolved gases like hydrogen and nitrogen from molten steel, improving steel purity for high-performance applications.
Continuous Casting represents the most established technology, while Electric Arc Furnace adoption is gaining share fastest.
Application:
Volume demand for processed steel is heavily influenced by the specific requirements and scale of various industrial applications.
- Construction:Requires high volumes of hot rolled and galvanized steels for structural components, rebar, and roofing. India's infrastructure pipeline generates substantial demand for construction-grade steel products.
- Machinery:Demands specialized alloy steels for components requiring high strength, wear resistance, and precision. European machinery manufacturers drive demand for advanced steel grades.
- Shipbuilding:Utilizes specific grades of high-strength and corrosion-resistant steels for hull structures and marine components.
- Energy Equipment:Requires specialized steels for high-pressure vessels, pipelines, and structural supports in oil, gas, and renewable energy sectors.
- Household Appliances:Uses cold rolled and galvanized steels for casings, internal components, and aesthetic finishes in consumer goods.
Construction applications account for the largest share of processed steel consumption, with Energy Equipment showing a steepest expansion trajectory.
End User:
The diverse needs of end-users shape procurement patterns and the demand for specific processed steel products and services.
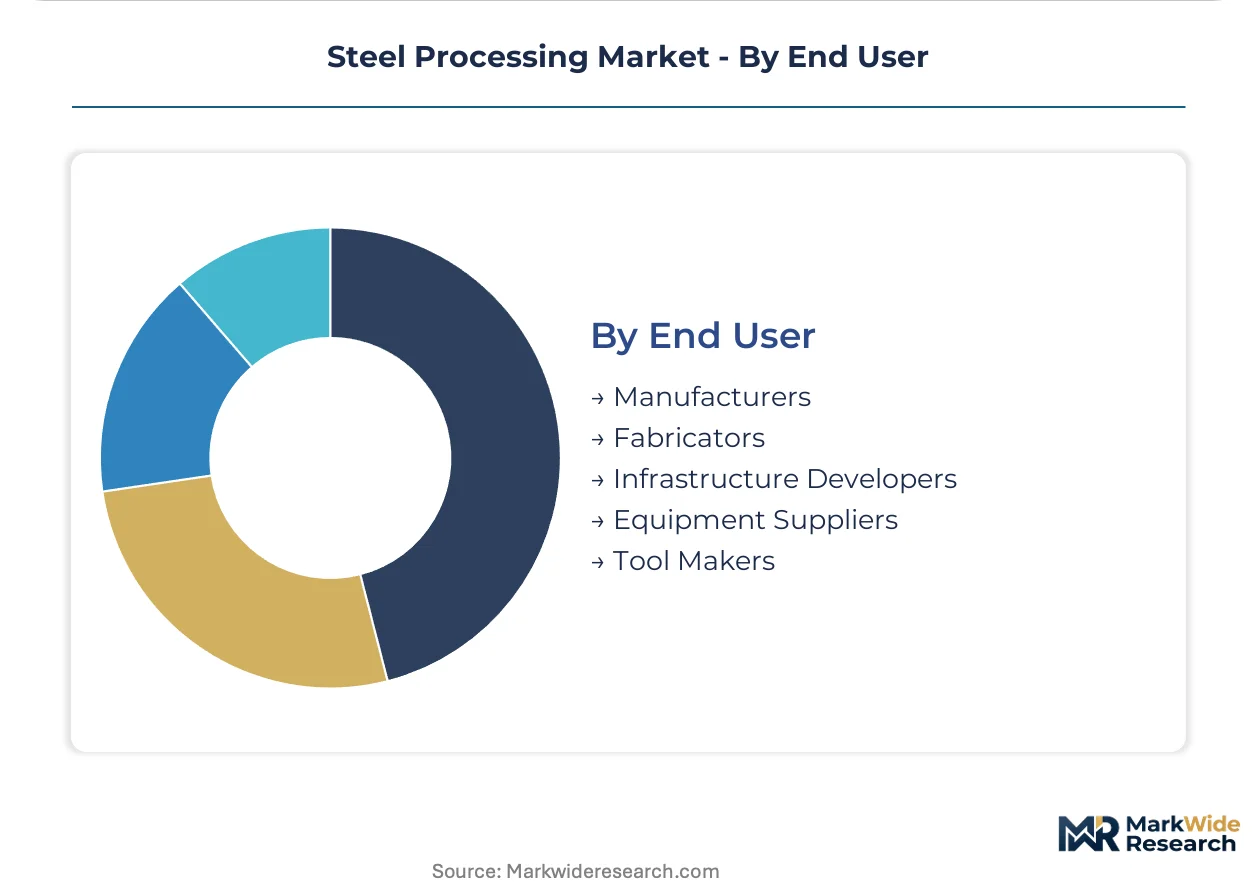
- Manufacturers:Automotive and appliance manufacturers require consistent quality, just-in-time delivery, and specialized steel grades. North American and European manufacturers increasingly seek unbundled processing services.
- Infrastructure Developers:Require large volumes of standardized steel products for long-term projects like bridges, roads, and utilities. Indian infrastructure programs are a significant driver for this end-user segment.
- Fabricators:Purchase semi-finished steel products for further cutting, welding, and assembly into custom components and structures.
- Equipment Suppliers:Procure processed steel for manufacturing industrial machinery, agricultural equipment, and specialized tools.
- Tool Makers:Demand high-purity and specialized alloy steels for creating durable and precise cutting tools, dies, and molds.
Manufacturers represent the largest end-user group, while Infrastructure Developers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The push for decarbonization and varying regulatory frameworks creates a cost-of-compliance gap, driving some steel processing production migration. Countries with stringent environmental policies are seeing investments in EAF technology, while those with less restrictive rules attract traditional methods. This dynamic reshapes global supply chains and investment flows for processed steel.
China
China's immense production scale and ongoing infrastructure projects drive significant demand for processed steel. China's dual carbon goals accelerate the closure of less efficient blast furnaces. The Yangtze River Delta region is witnessing substantial investment in scrap-fed Electric Arc Furnace capacity.
India
India's national infrastructure pipeline creates vast volume demand for construction-grade steel. The PLI scheme encourages domestic steel processing and manufacturing growth. Industrial hubs in Maharashtra are experiencing concentrated demand for long products.
United States
Automotive lightweighting and machinery sectors in the United States require specialized high-strength steels. Environmental Protection Agency (EPA) regulations encourage sustainable production methods, including EAF technology. The Great Lakes region, with its strong automotive presence, is a focal point for advanced high-strength steel production.
Germany
European machinery manufacturers and automotive lightweighting initiatives drive demand for specialized alloy steels in Germany. The EU Green Deal encourages investment in Electric Arc Furnace production. Industrial clusters in North Rhine-Westphalia are seeing increased adoption of EAFs leveraging regional scrap availability.
Japan
Japan's high-precision manufacturing and specialized automotive components demand advanced steel products. METI policies promote advanced materials research and efficient steel production technologies. The Kansai region's automotive and electronics sectors demand high-purity and specialized steel grades.
Steel Processing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, influencing competitive positioning within steel processing. The market exhibits a tiered structure, with large integrated steelmakers coexisting with specialized downstream processors. Strategic archetypes include global giants leveraging extensive raw material procurement and regional EAF-based producers focusing on scrap availability. Capacity expansion and strategic partnerships are dominant competitive moves.
At the scale-driven end, ArcelorMittal represents a global footprint, serving multinational construction and automotive clients with diverse steel products. China Baowu Steel Group, a Chinese state-owned enterprise, exemplifies immense production scale influencing raw material procurement globally. Nucor Corporation, a North American entity, occupies a position specializing in electric arc furnace production, aligning with regional recycling infrastructure. These companies anchor different segments of the processed steel market, from commodity volumes to specialized high-strength alloys. Their operational models reflect distinct approaches to supply chain management and decarbonization initiatives.
| Leading Market Players |
|---|
| ArcelorMittal |
| China Baowu Steel Group |
| Nippon Steel Corporation |
| POSCO Holdings |
| Nucor Corporation |
| Tata Steel |
| JSW Steel |
| Steel Dynamics |
| Ansteel Group |
| Others |
Cost & Logistics Intelligence
Automotive lightweighting initiatives in Europe increasingly demand specialized high-strength steels, forcing processors to invest in advanced production routes and driving up material costs across the supply chain.
Pricing Analysis
Direct-to-OEM contract pricing dominates for specialized steel products, reflecting long-term supply agreements and stringent quality assurance needs. Price differentiation stems from ISO 9001 certification and the level of customization required for specific applications like energy equipment. Pricing softness runs through commodity hot rolled steel due to overcapacity in certain regions. Infrastructure developers are highly price-sensitive for volume purchases, while machinery manufacturers prioritize performance over cost for critical components.
Supply Chain Analysis
Adherence to ISO 9001 quality standards and China's GB standards gates market access for steel processors, particularly for high-performance applications. Geographic supply concentrates in China, India, and the United States, drawing heavily from iron ore and scrap steel. Commodity price volatility for metallurgical coal represents a structural supply chain risk for traditional blast furnace operators. Distribution runs through a mix of direct sales to large manufacturers and specialized distributors serving smaller fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Steel Processing Market presents a geographic-arbitrage opportunity, as stringent EU Green Deal regulations drive EAF investments in Europe, while less restrictive environments in Southeast Asia attract traditional methods.
For Market Incumbents: Anticipate further consolidation among global steelmakers to leverage economies of scale and optimize raw material procurement. Implement advanced process optimization software across existing facilities to counter input cost volatility for traditional blast furnaces. Invest in decarbonization technologies within key production hubs to mitigate future carbon pricing risks. Deepen vertical integration into high-purity scrap collection to secure feedstock for EAF operations.
For New Entrants and Emerging Players: AI-driven process control software offers a technology-first wedge for new entrants specializing in yield optimization and quality control services. Target underserved segments in Southeast Asian manufacturing for specialized alloy steels, leveraging the region's expanding automotive and electronics sectors. Develop niche products for hydrogen economy components, focusing on high-pressure storage tanks and pipelines. Offer unbundled yield management services as a go-to-market strategy for large manufacturers.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated mid-cap specialists focused on niche alloy production and sustainable EAF technologies. Long-term viability depends on the ability to adapt to evolving decarbonization mandates and specialized material demands over the next decade. Target regional EAF producers with strong scrap access or digital service providers offering process optimization solutions. A signal to watch for inflection is the accelerated adoption of carbon pricing mechanisms globally.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Investing in new EAF facilities in North America reduces carbon emissions and leverages regional scrap. |
| Green Manufacturing Transition | Adopting hydrogen-based direct reduced iron (DRI) processes enhances sustainability credentials for steel products. |
| Strategic Partnership | Collaborating with software firms improves AI-driven process control for rolling mills and heat treatment. |
| Long-term Supply Agreement | Securing high-quality scrap material ensures consistent EAF feedstock and stable production economics. |
| Product Diversification | Developing specialized alloy steels supports the growing hydrogen infrastructure and advanced machinery sectors. |
Research Approach
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core for this Steel Processing Market analysis. Primary interviews with metallurgists, procurement leads at automotive OEMs, and infrastructure developers provided crucial insights, validated against extensive secondary research. Stakeholder roles included plant managers, R&D directors, automotive purchasing managers, and construction project leads. Secondary data sources encompassed government infrastructure reports from India, EU Green Deal policy documents, and company financial filings.
Historical trendline analysis, coupled with a forward-looking assessment of technological shifts, informed the quantitative framework for this study. The analytical framework projected market dynamics across the analysis window, segmenting by product type, technology, application, end-user, and regional decarbonization policies. Compound annual growth rates were derived from projected volume and value changes across these defined segments. Scrap steel availability and EAF adoption rates served as key industry-specific forecast inputs.
The model holds under current decarbonization policy trajectories and raw material supply stability; deviation in global trade policies or energy costs would shift projections. Forecasts reflect assumptions regarding infrastructure spending and electric vehicle adoption rates. A model refresh is warranted upon material change in EAF investment patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Heat Shrink Tubing and Sleeves Market
Industrial Materials
Global High Temperature Gaskets Market
Industrial Materials
Global Melamine Market
Industrial Materials
Lip Seals Market
Industrial Materials
Expanded PTFE (Eptfe) Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
Chalk Reel and Line Chalk Market
Industrial Materials
Industrial Films Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Wood Fiber Insulation Market
Industrial Materials
Steel Cord Market
Industrial Materials
UHP Graphite Electrode Market
Industrial Materials
Stainless Steel Cable Ties Market