
 North America Mexoryl SX (Ecamsule) Market | 2026-2036
North America Mexoryl SX (Ecamsule) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mexoryl SX (Ecamsule) Market Insights
Buyer concentration among dermatology clinics and specialty skincare retailers is hardening as institutional procurement replaces fragmented individual purchasing. L'Oréal leverages its captive R&D pipeline to sustain formulation leadership in photostable UVA filters. Johnson & Johnson anchors its position through pharmacy-centric distribution networks that prioritize clinician endorsement. Procter & Gamble competes via mass-market brand recognition that drives retail shelf placement.
Mexoryl SX (Ecamsule) is a benzylidene camphor-derived organic UV filter, synthesized through sulfonation of 4-methylbenzylidene camphor to achieve peak absorbance at 345 nm with photostable broad-spectrum UVA I protection. The compound serves primarily as an active pharmaceutical ingredient in topical photoprotective formulations where UVA-filter degradation resistance determines clinical efficacy. Sunscreen cream formulations occupy the dominant margin pool due to higher active-ingredient loading capacity and premium positioning in dermatology channels. Online stores represent the fastest-expanding distribution vector as telehealth referrals and subscription skincare models redirect patient purchasing behavior away from traditional pharmacies.
FDA sunscreen monograph revisions and Health Canada's Natural Health Products Directorate both mandate rigorous UVA-filter efficacy documentation, creating compliance barriers that favor established formulators with dedicated regulatory affairs infrastructure. The EPA's incidental environmental exposure assessments for UV-filter aquatic toxicity are additionally shaping ingredient selection criteria for brands targeting reef-safe positioning. Stakeholders must monitor pending monograph finalization timelines and state-level environmental ingredient restrictions to anticipate reformulation cycles and channel reallocation requirements.
Market Dynamics
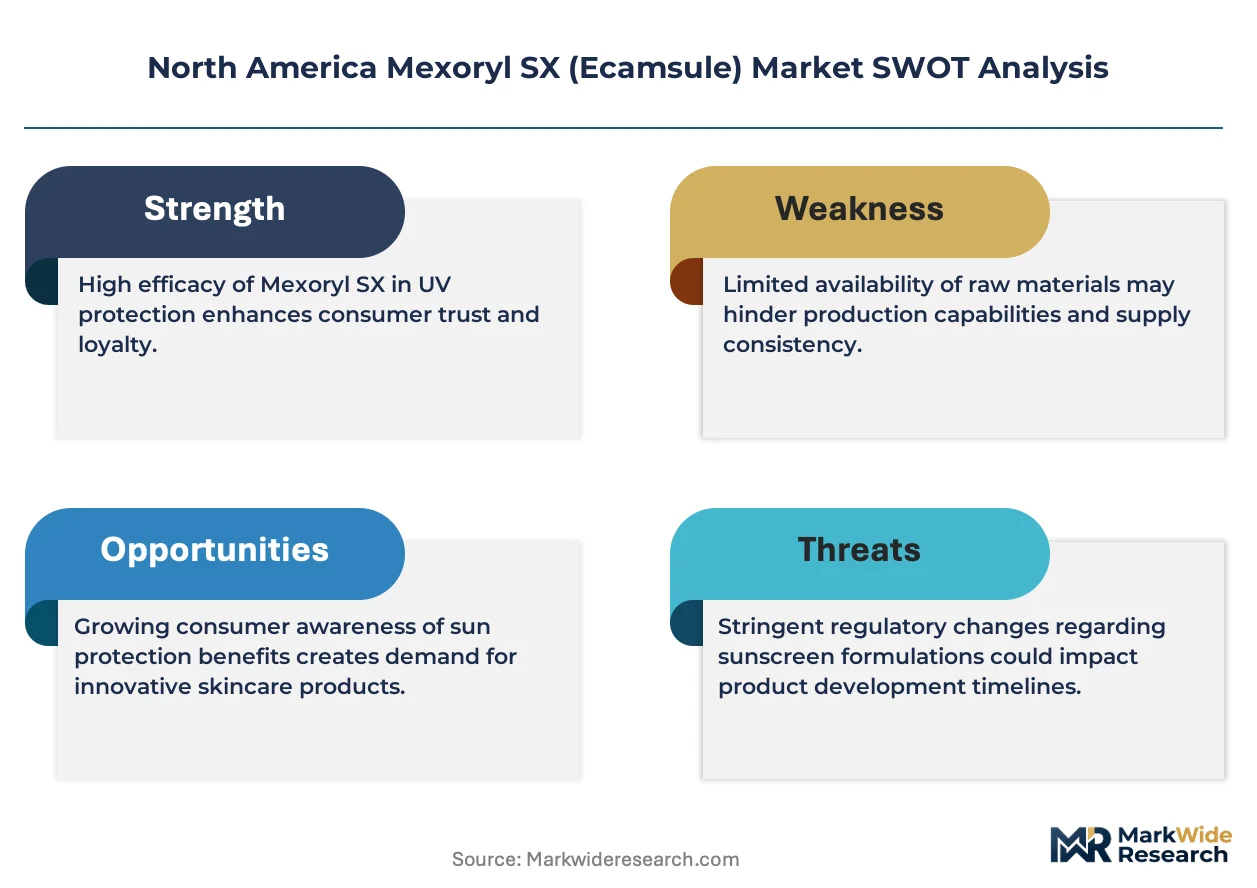
FDA's sunscreen monograph modernization is forcing formulators to demonstrate superior UVA-filter photostability, concentrating procurement power among dermatology clinics capable of validating clinical-grade claims. This regulatory pressure is restructuring competitive advantage around captive R&D infrastructure and regulatory affairs capabilities.
Growth Catalysts
- Telehealth dermatology expansion:Virtual consultations in California and Texas are generating prescription-grade sunscreen referrals that bypass traditional pharmacy channels. Dermatologists increasingly dispense professional formulations directly through affiliated e-commerce portals.
- Reef-safe ingredient mandates:Hawaii's ban on oxybenzone and octinoxate is redirecting formulator R&D toward photostable alternatives with favorable aquatic toxicity profiles. Mexoryl SX's absence from restricted substance lists positions it for substitution-driven volume.
- Outdoor recreation participation:Sustained hiking and water sports engagement across the American Southwest is elevating consumer willingness to pay for dermatologist-validated UVA protection. Specialty retailers in these markets report premium sunscreen category expansion.
Market Restraints
- Sulfonated benzylidene camphor synthesis complexity:The multi-step organic chemistry required for Mexoryl SX production limits viable contract manufacturing options. Active pharmaceutical ingredient suppliers with dedicated photostable UV filter capabilities concentrate in France and Switzerland.
- FDA monograph approval timeline uncertainty:Pending finalization of broad-spectrum efficacy testing protocols is freezing new product launch schedules. Formulators await definitive UVA I protection labeling requirements before committing to reformulation cycles.
- Mineral filter substitution pressure:Zinc oxide and titanium dioxide formulations are capturing reef-safe positioning in mass retail channels. These inorganic alternatives bypass organic UV filter regulatory complexity while satisfying clean beauty marketing narratives.
Strategic Opportunities
- Subscription skincare model penetration:Direct-to-consumer platforms are capturing recurring revenue from telehealth-referred patients seeking consistent photoprotection regimens. California-based dermatology practices are piloting automated refill programs for prescription-grade formulations.
- Health Canada Natural Health Products Directorate alignment:Harmonized UVA efficacy documentation requirements between Canadian and American regulators could streamline cross-border product registration. Formulators with established Health Canada compliance infrastructure gain first-mover advantage in unified North American positioning.
- Photostabilizer synergy formulations:Combining Mexoryl SX with complementary UVB filters and antioxidant boosters is enabling differentiated clinical claims. R&D pipelines focusing on multi-active complexes can command premium positioning in professional channels.
Industry Challenges
- Photochemistry specialization scarcity:Formulation chemists with expertise in sulfonated camphor derivative stability testing are concentrated among legacy sunscreen manufacturers. Talent acquisition friction is delaying new entrant product development timelines.
- Clinical validation study costs:FDA-mandated in vivo UVA protection factor testing requires substantial capital deployment for human subject trials. Smaller formulators face barriers to generating compliant efficacy documentation.
- Legacy pharmacy distribution dependence:Established brands with entrenched clinician endorsement relationships are resisting channel disintermediation. New market entrants must navigate complex pharmacy benefit manager and group purchasing organization structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mexoryl SX (Ecamsule) Market |
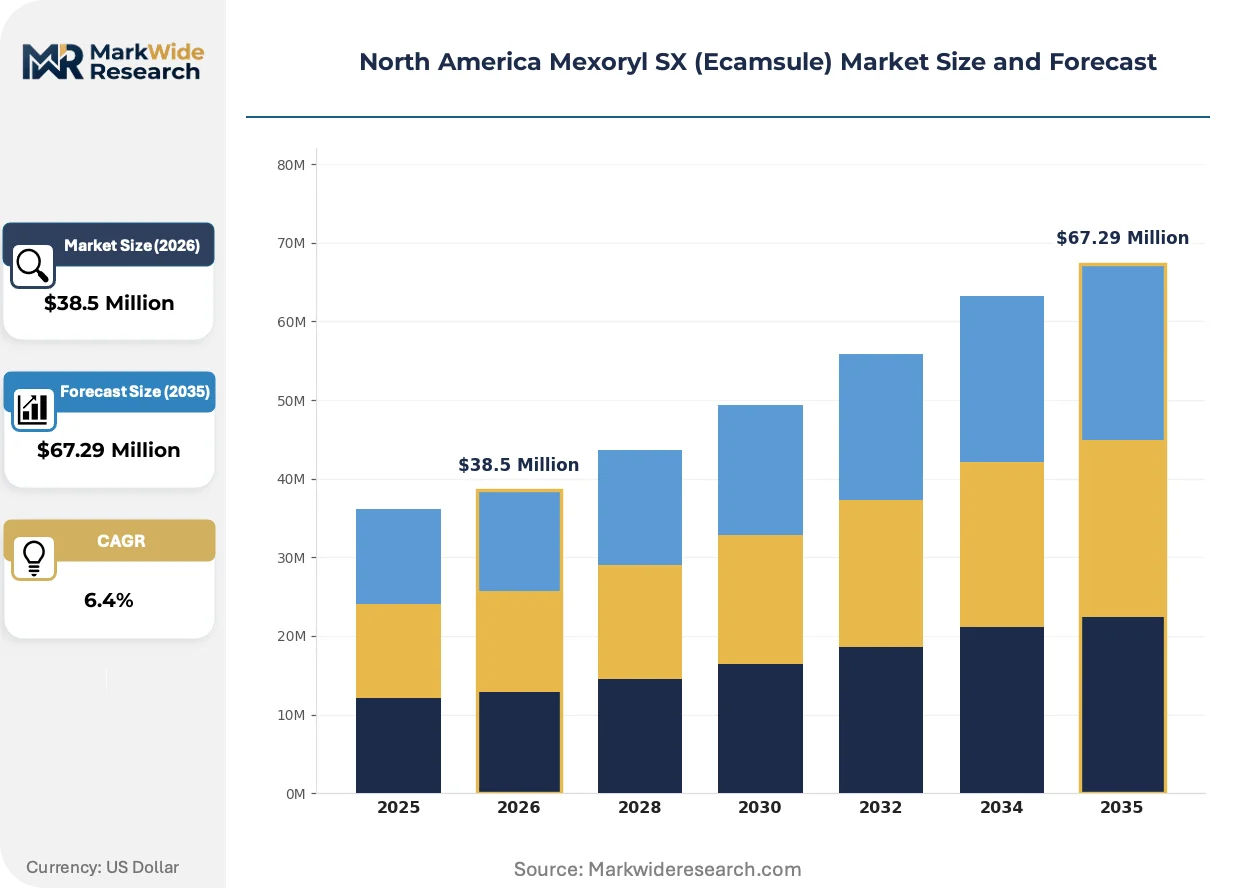
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $67.29 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sunscreen Cream, Lotion, Gel, Spray End User: Adults, Children, Dermatology Clinics, Retail Consumers Application: Skin Protection, Cosmetics, Skincare, Outdoor Activities Distribution Channel: Online Stores, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | L'Oréal, Johnson & Johnson, Procter & Gamble, Beiersdorf, Unilever, Colgate-Palmolive, Avon Products, Estée Lauder, Coty, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mexoryl SX (Ecamsule) Market Trends and Innovations
Photostabilization technology and distribution channel restructuring are converging to reshape competitive positioning in professional-grade sun protection. Formulators are racing to demonstrate clinical efficacy while bypassing traditional retail intermediaries.
Encapsulated Mexoryl SX delivery systems are expanding into high-SPF daily wear formulations previously dominated by less photostable organic filters. Dermatology clinics in Texas and Florida are adopting these complexes for patient compliance programs targeting photosensitive skin conditions. The technology is expanding into cosmetic-grade tinted moisturizers, compressing the historical separation between therapeutic and aesthetic sun protection categories.
EPA's incidental environmental exposure assessments for UV-filter aquatic toxicity are compelling reformulation strategies across reef-conscious brand portfolios. Manufacturers are restructuring active ingredient portfolios to preempt state-level environmental restrictions beyond Hawaii's existing oxybenzone ban. California's proposed Safer Consumer Products regulations are accelerating ingredient substitution timelines for brands targeting coastal market positioning.
Patient purchasing behavior is migrating toward telehealth-integrated e-commerce platforms that bundle prescription-grade photoprotection with virtual follow-up consultations. Dermatology practices in metropolitan Texas markets are displacing traditional pharmacy fulfillment with proprietary dispensing portals. This channel rotation is most visible among millennial and Gen Z patient demographics seeking seamless digital health experiences.
North America Mexoryl SX (Ecamsule) Market Segmentation
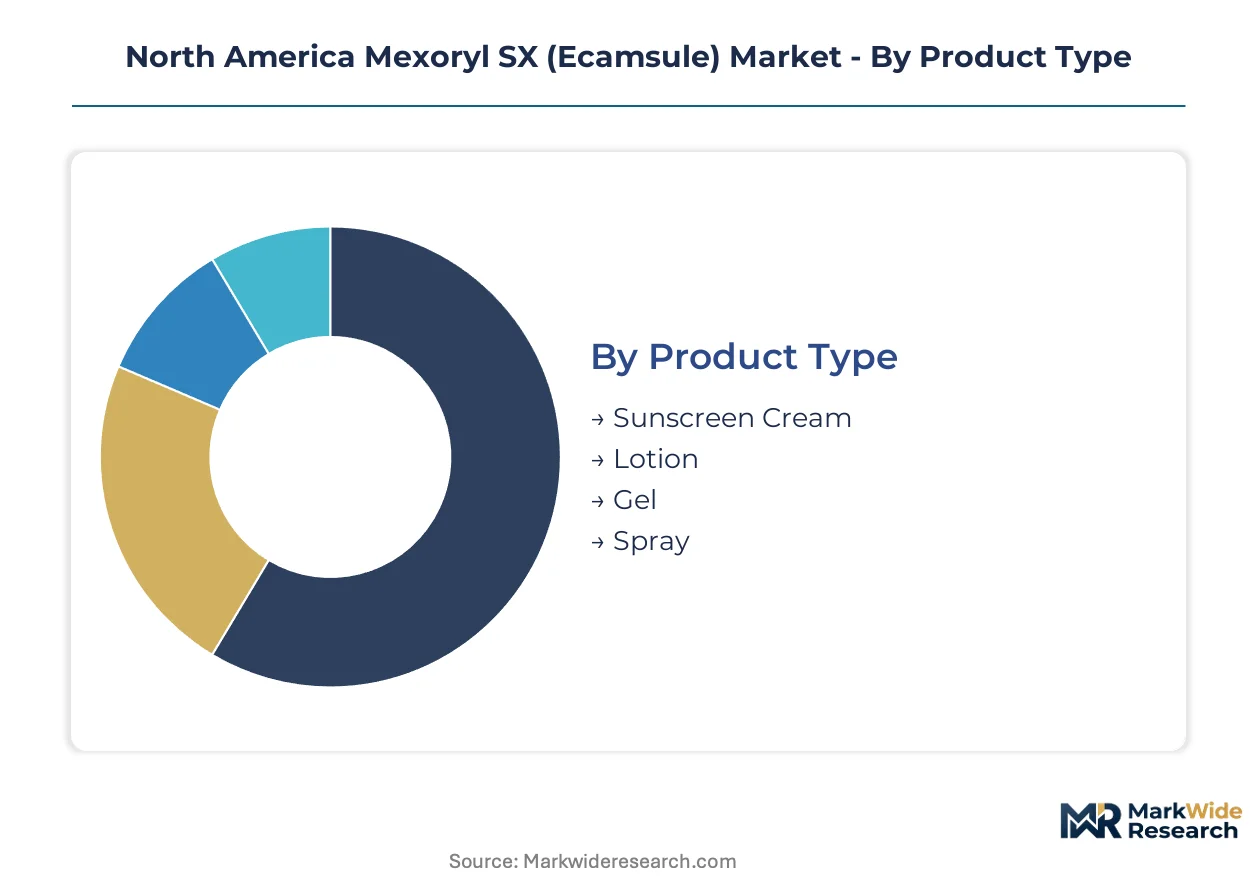
North American Mexoryl SX procurement patterns diverge sharply between institutional dermatology channels and mass retail, with regulatory compliance burdens determining viable segment participation. Formulators must align product specifications with FDA monograph requirements and state-level environmental restrictions to access concentrated demand pockets.
Product Type:
FDA's sunscreen monograph modernization imposes distinct UVA-filter efficacy documentation requirements across formulation bases, with cream and lotion formats facing the most stringent photostability validation protocols.
- Sunscreen Cream:Oil-in-water emulsion systems accommodate higher active-ingredient loading densities for Mexoryl SX, supporting peak absorbance at 345 nm in dermatology-dispensed protocols across California and Texas.
- Lotion:Lower viscosity formulations penetrate faster into skin tissue, capturing demand from outdoor recreation participants in the American Southwest who prioritize reapplication convenience during sustained sun exposure.
- Gel:Alcohol-based matrices suit acne-prone patient demographics seeking non-comedogenic photoprotection through telehealth referral channels.
- Spray:Aerosol and pump-delivery formats face heightened EPA scrutiny for inhalation exposure and volatile organic compound emissions, limiting professional channel adoption.
Sunscreen cream sits at the top of the volume ranking, with lotion climbing the fastest.
End User:
Procurement authority concentrates among institutional buyers with validated clinical claims infrastructure, while retail consumer segments respond to reef-safe positioning and subscription model convenience.
- Adults:Photosensitive patient populations and outdoor workers drive prescription-grade demand through dermatology clinics in metropolitan Texas markets with elevated UV index exposure.
- Children:Pediatric formulations require specialized safety testing under FDA guidelines, creating compliance barriers that favor established manufacturers with dedicated juvenile product divisions.
- Dermatology Clinics:Institutional dispensing protocols in California and Florida bypass traditional pharmacy channels, capturing recurring revenue through proprietary e-commerce portals integrated with telehealth workflows.
- Retail Consumers:Reef-conscious purchasing in Hawaii and coastal California redirects volume toward photostable alternatives absent from state-level restricted substance lists.
Dermatology clinics command the premium tier by margin, with retail consumers gaining share fastest through direct-to-consumer platform expansion.
Application:
Functional differentiation between therapeutic and aesthetic use cases determines Mexoryl SX loading concentrations and companion ingredient selection in formulation design.
- Skin Protection:Medical-grade photoprotection for photosensitive conditions requires documented UVA I efficacy under FDA broad-spectrum testing protocols, anchoring procurement in institutional channels.
- Cosmetics:Tinted moisturizer and foundation integrations compress the historical separation between therapeutic and aesthetic categories, with Texas dermatology clinics piloting compliance programs in this hybrid space.
- Skincare:Daily wear serums and anti-aging formulations incorporate Mexoryl SX for photostable antioxidant protection, capturing subscription model revenue through California-based telehealth platforms.
- Outdoor Activities:Water-resistant specifications for hiking and water sports engagement in the American Southwest demand enhanced film-forming technologies to sustain UVA-filter efficacy during perspiration and immersion.
Skin protection maintains volume leadership, with cosmetics expanding most quickly through tinted formulation adoption.
Distribution Channel:
Channel restructuring reflects telehealth integration and patient demographic shifts, with digital platforms displacing legacy pharmacy fulfillment among younger consumer cohorts.
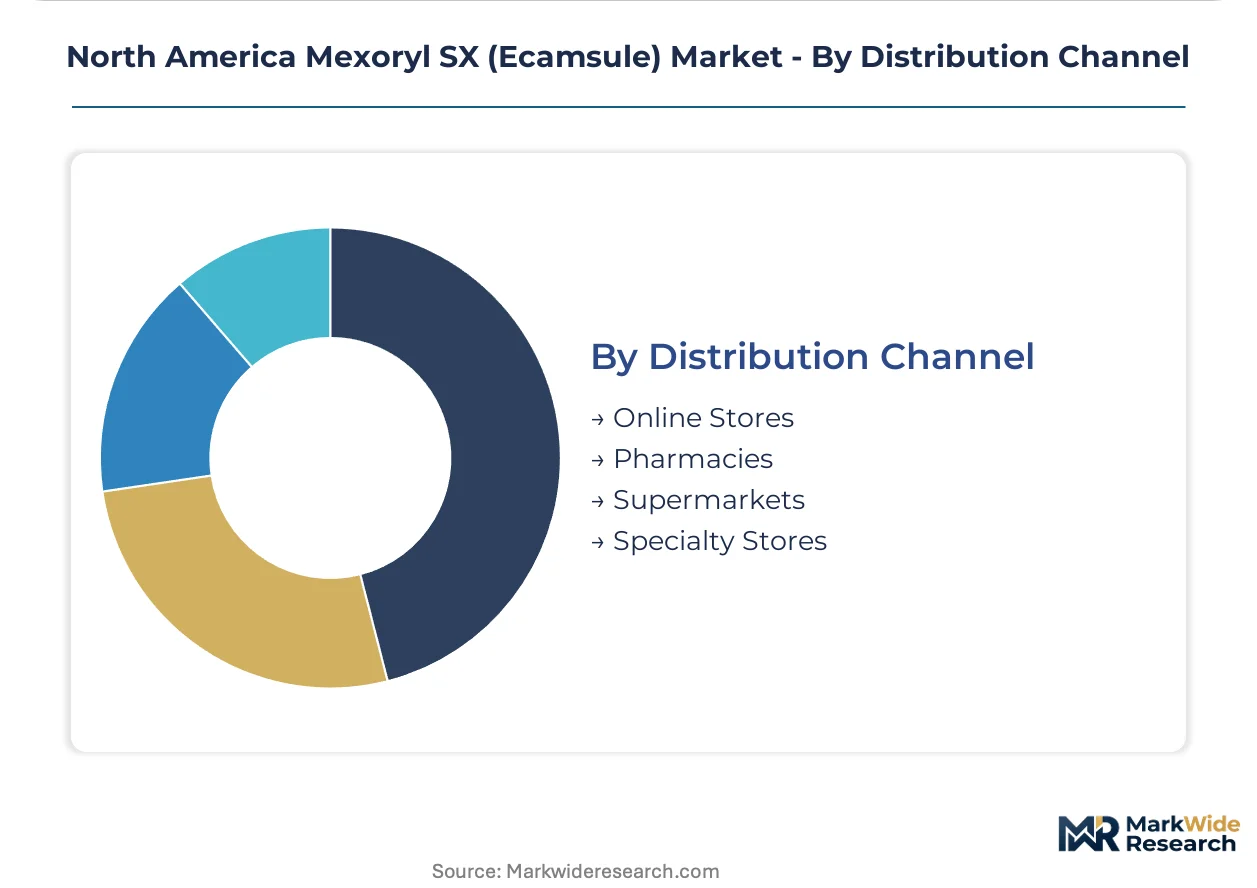
- Online Stores:Direct-to-consumer platforms capture recurring revenue from telehealth-referred patients, with California dermatology practices deploying automated refill programs for prescription-grade formulations.
- Pharmacies:Chain and independent drugstores retain clinician endorsement dependencies, though pharmacy benefit manager structures create procurement friction for new market entrants.
- Supermarkets:Mass retail shelf placement rewards brand recognition and marketing expenditure, with reef-safe positioning driving category resets in Hawaii and coastal California locations.
- Specialty Stores:Outdoor recreation retailers in Texas and Arizona markets report premium sunscreen category expansion, validating consumer willingness to pay for dermatologist-validated UVA protection.
Online stores lead the steepest expansion trajectory, while pharmacies retain the largest absolute volume position through established clinician relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada trails the United States in dermatology clinic density but exceeds it in reef-safe regulatory momentum, while Mexico's emerging professional skincare channel remains underdeveloped for photostable UVA filter adoption.
United States
California and Texas concentrate demand through elevated outdoor recreation participation and dense clinical dermatology networks. FDA's sunscreen monograph modernization drives formulators toward photostability documentation that favors established R&D infrastructure. Los Angeles and Houston metropolitan areas anchor telehealth-integrated dispensing portals displacing traditional pharmacy channels.
Canada
Health Canada's Natural Health Products Directorate harmonizes UVA efficacy requirements with emerging FDA protocols, streamlining cross-border product registration for compliant formulators. Ontario and Quebec host the majority of dermatology practices piloting professional-grade sunscreen dispensing. Toronto's telehealth platforms are replicating California's subscription refill models for prescription-grade photoprotection.
Mexico
Professional skincare channels in Mexico City and Monterrey remain fragmented, with retail pharmacy dominance limiting institutional procurement growth. Mexico's national pharmaceutical regulator has not yet adopted stringent UVA-filter efficacy documentation requirements comparable to FDA or Health Canada standards. Border state distributors serve as conduits for U.S.-formulated products entering the Mexican market through informal channels.
North America Mexoryl SX (Ecamsule) Market Competitive Landscape
French producers anchor the photostable UV filter tier; American and German specialists hold formulation and distribution positions respectively. Market structure concentrates around legacy sunscreen manufacturers with captive R&D infrastructure and dedicated regulatory affairs capabilities. Three archetypes dominate: vertically integrated beauty conglomerates, pharmacy-centric healthcare consumer goods firms, and mass-market brand recognition players. Competitive moves center on telehealth channel partnerships and reef-safe portfolio repositioning.
Within the vertically integrated tier, L'Oréal exemplifies captive R&D pipeline control over photostable UVA filter technology. Johnson & Johnson occupies a position bridging healthcare credibility with pharmacy-centric distribution networks. Procter & Gamble anchors mass-market shelf placement through brand recognition expenditure. These three entities represent distinct strategic approaches to the Mexoryl SX value chain without implying specific market share figures or operational details.
| Leading Market Players |
|---|
| L'Oréal |
| Johnson & Johnson |
| Procter & Gamble |
| Beiersdorf |
| Unilever |
| Colgate-Palmolive |
| Avon Products |
| Estée Lauder |
| Coty |
| Others |
Pricing and Supply Chain Analysis
Captive R&D integration among French photostable UV filter producers anchors both supply security and premium pricing power across the North American Mexoryl SX value chain. L'Oréal's in-house sulfonated benzylidene camphor synthesis capabilities insulate formulation costs from API spot market volatility while supporting dermatology-channel premium positioning.
Pricing Analysis
Capacity additions in Switzerland and France are reshaping price floors for pharmaceutical-grade Mexoryl SX, though contract manufacturing scarcity sustains premium tiers. Three-tier pricing structure across prescription-grade, professional-dispensed, and mass retail levels separates FDA-validated clinical formulations from cosmetic-grade alternatives. Cost compression in mass retail channels intensifies because zinc oxide substitution campaigns capture reef-safe positioning. Dermatology clinics exhibit lowest price sensitivity due to reimbursement integration and patient compliance program anchoring.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers mandate multi-supplier qualification across French and Swiss API manufacturers, though viable alternatives remain limited. Sulfonated benzylidene camphor production draws from 4-methylbenzylidene camphor precursors, sulfur trioxide reagents, and specialized photostability testing infrastructure. Single-source vulnerability concentrates in European contract manufacturing with dedicated UV filter chemistry capabilities. Distribution runs through dermatology-affiliated e-commerce portals displacing legacy pharmacy fulfillment among telehealth-referred patient cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's streamlined Natural Health Products Directorate registration creates geographic arbitrage against FDA monograph uncertainty, rewarding formulators with established cross-border compliance infrastructure.
For Market Incumbents: Anticipate mineral filter substitution threats in mass retail by accelerating photostabilizer synergy R&D for differentiated clinical claims. Consolidate telehealth channel partnerships in Texas and California metropolitan markets before pharmacy benefit manager structures freeze new entrant access. Prioritize captive regulatory affairs capabilities to navigate pending EPA aquatic toxicity assessments.
For New Entrants and Emerging Players: Capture subscription skincare white space through direct-to-consumer platforms serving millennial and Gen Z telehealth patients seeking automated refill convenience. Target underpenetrated Canadian dermatology practices replicating California dispensing portal models. Pursue Health Canada-first registration strategy to leverage harmonized UVA efficacy documentation against FDA timeline uncertainty.
For Investors and Strategic Acquirers: Roll-up economics work for mid-scale formulators with Health Canada compliance infrastructure because cross-border product registration streamlines North American market access. Five-to-ten year viability hinges on telehealth channel integration depth rather than retail shelf presence alone. Monitor FDA monograph finalization timelines as inflection indicator for reformulation cycle capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Telehealth Channel Integration | California dermatology practices displace pharmacy fulfillment through proprietary e-commerce portals. |
| Reef-Safe Portfolio Repositioning | Hawaii's oxybenzone ban redirects R&D toward photostable alternatives with favorable EPA aquatic profiles. |
| Cross-Border Regulatory Harmonization | Health Canada alignment streamlines product registration for FDA-compliant formulators seeking unified positioning. |
| Photostabilizer Synergy Development | Multi-active complexes combining Mexoryl SX with UVB filters command premium dermatology channel placement. |
| Subscription Model Infrastructure | Automated refill programs capture recurring revenue from telehealth-referred patient compliance regimens. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market cluster. Formulation chemists at legacy sunscreen manufacturers, regulatory affairs directors navigating FDA monograph modernization, dermatology clinic procurement managers, and pharmacy benefit manager contract specialists provided qualitative grounding. Secondary validation drew from FDA sunscreen monograph dockets, Health Canada Natural Health Products Directorate guidance documents, EPA incidental environmental exposure assessments, and state-level cosmetic ingredient restriction registers. Bottom-up demand modeling across product type, end user, application, and distribution channel segments triangulated against top-down market sizing.
Rate-of-change decomposition across the projection horizon separated volume drivers from price evolution factors. Segmentation dimensions modeled include formulation base, procurement authority archetype, functional use case, and fulfillment channel structure. CAGRs derived from regression analysis of historical regulatory approval timelines, telehealth platform expansion rates, and outdoor recreation participation indices. Reef-safe regulatory momentum and photostability documentation requirements served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; dermatology clinic procurement and online store expansion carry tighter precision than Mexican retail pharmacy penetration. Forecasts reflect assumptions regarding FDA monograph finalization pacing, EPA aquatic toxicity assessment outcomes, and telehealth reimbursement policy stability. Deviation in FDA broad-spectrum efficacy testing protocol timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Octocrylene Market
Specialty Chemicals
Global Blowing Agent Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Superoxide Dismutase Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Ethylhexane Diol Market
Specialty Chemicals
Optical Whitening Agents Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Global Silicone Defoamer Market