
 Global High Pressure Seals Market | 2026-2036
Global High Pressure Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Pressure Seals Market Foresight
The EU Green Deal is realigning material roadmaps across the seal supply base, pushing compounders toward low-carbon PTFE and bio-derived polyurethane feedstocks. Parker Hannifin Corporation leverages its captive elastomer blending capacity to shorten qualification cycles for REACH-compliant formulations. Trelleborg AB anchors Nordic offshore wind demand with specialized spring seal designs rated for subsea pressure cycling. SKF Group dominates rotating equipment aftermarket channels through integrated seal-bearing service bundles.
High pressure seals are precision-engineered closure devices designed to contain pressurized fluids or gases above 3,000 psi in static or dynamic interfaces, typically fabricated from fluoropolymer composites, hydrogenated nitrile, or metal-reinforced elastomer laminates via compression molding and CNC finish machining. Their primary purpose is to prevent leakage, exclude contaminants, and maintain system integrity in extreme-pressure process equipment. Mechanical seals command the largest value pool in oilfield and chemical processing deployments due to replacement frequency and failure-cost exposure. PTFE formulations are displacing conventional nitrile in hydraulic systems where mineral oil compatibility and temperature extremes converge. Aerospace assemblies represent the fastest-growing application segment as OEMs specify lighter, fire-resistant seal architectures for next-generation propulsion systems.
EPA rules under the Clean Air Act and OSHA process safety mandates govern material selection and emissions containment in United States process plants. EMA medical device standards and REACH substance restrictions in Europe constrain plasticizer and curing-agent chemistries, favoring perfluoroelastomer migration in critical-service seals. China's GB standards and MEE environmental enforcement are raising the compliance threshold for imported seal assemblies in petrochemical projects. Stakeholders must monitor regulatory divergence across these three jurisdictions to avoid stranded inventory and qualification gaps.
Market Dynamics
Fluoropolymer substitution driven by REACH substance restrictions and EPA emissions containment mandates is restructuring supplier qualification protocols and material roadmaps across the seal supply base.
Growth Catalysts
- Deepwater oilfield investment:Capital deployment in Brazil's pre-salt basins and the Gulf of Mexico offshore cluster is lifting procurement volumes for mechanical and spring seal assemblies rated for subsea pressure cycling.
- REACH compliance acceleration:ECHA substance restrictions on plasticizers and curing agents are forcing compounders toward perfluoroelastomer formulations, expanding the addressable market for high-performance seal architectures.
- Aerospace propulsion specifications:Next-generation engine programs are specifying lighter, fire-resistant seal designs, creating new demand for PTFE composite laminates in turbine and fuel system interfaces.
Market Restraints
- Fluoropolymer feedstock concentration:Virgin PTFE resin supply concentrates among a limited set of chemical producers, exposing seal fabricators to price volatility and allocation risk during raw material tightness.
- Qualification timeline compression:OEM validation cycles for subsea and aerospace applications extend 18-36 months, creating working capital intensity and revenue recognition delays for seal suppliers.
- Metal-reinforced elastomer substitution limits:Hydrogenated nitrile remains entrenched in legacy hydraulic systems due to established compatibility protocols, slowing full fluoropolymer penetration in mineral oil environments.
Strategic Opportunities
- Offshore wind installation growth:Nordic and North Sea offshore wind corridors require specialized spring seal designs for subsea cable and turbine foundation interfaces, opening white space beyond traditional oilfield demand.
- EU Green Deal material incentives:Low-carbon PTFE and bio-derived polyurethane feedstock development qualifies for EU innovation funding, creating cost-offset opportunities for compliant compounders.
- Integrated seal-bearing service bundling:Rotating equipment aftermarket channels present convergence potential for seal suppliers with diagnostic and predictive maintenance capabilities.
Industry Challenges
- Multi-jurisdiction compliance synchronization:Seal suppliers must simultaneously satisfy EPA process safety mandates, REACH substance restrictions, and China's GB standards to avoid stranded inventory in petrochemical project pipelines.
- Subsea pressure cycling fatigue expertise:Qualified engineers capable of designing for deepwater pressure and temperature extremes remain scarce, constraining capacity expansion for specialized seal fabricators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Pressure Seals Market |
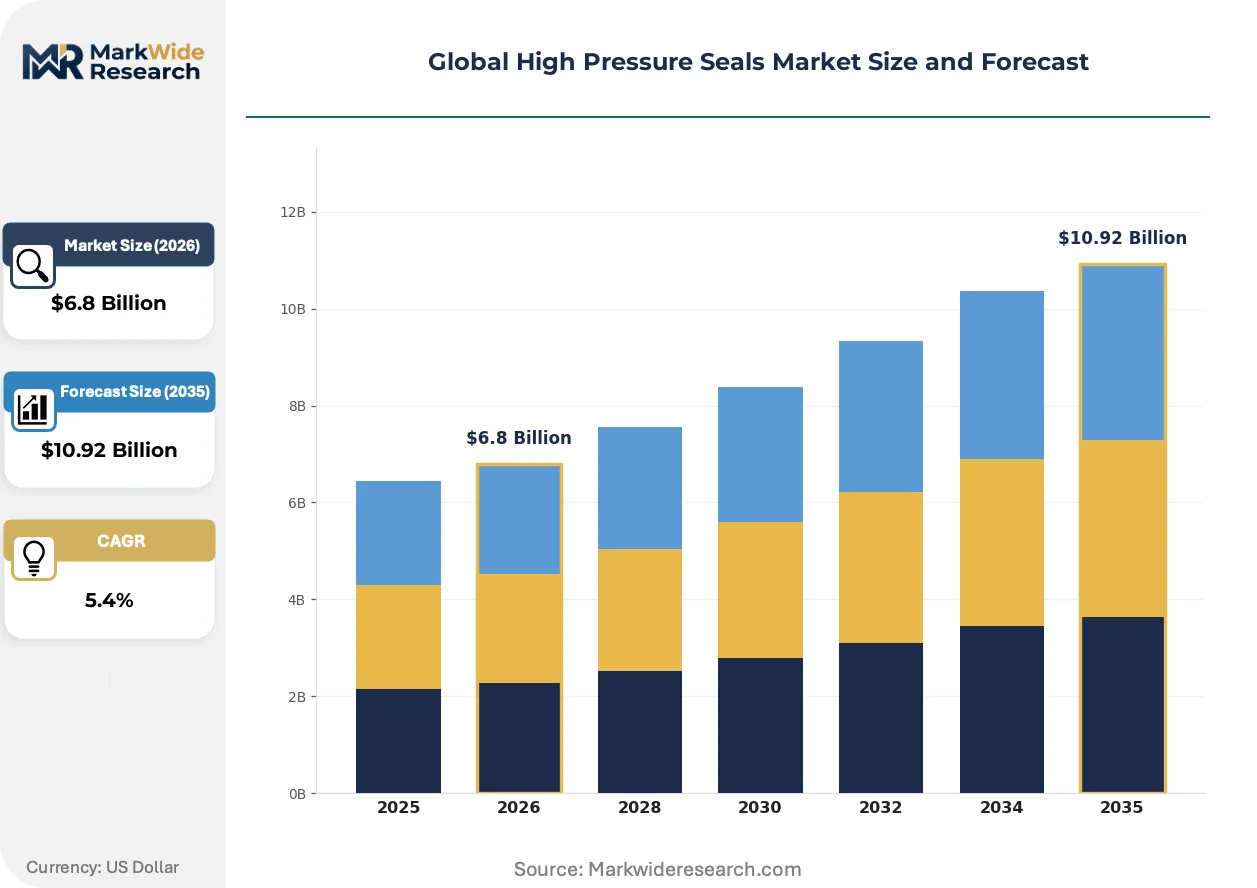
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Lip Seals, Mechanical Seals, Ring Seals, Spring Seals Material: PTFE, Nitrile Rubber, Viton, Silicone, EPDM, Polyurethane Application: Oilfield Equipment, Hydraulic Systems, Aerospace Assemblies, Chemical Processing, Power Generation, Marine Engineering End User Industry: Petrochemical Plants, Aerospace OEMs, Renewable Energy Firms, Heavy Equipment Fabricators, Marine Contractors, Food Processing Units |
| Companies Covered | Parker Hannifin Corporation, Trelleborg AB, SKF Group, John Crane Inc., Flowserve Corporation, EagleBurgmann Germany GmbH & Co. KG, Freudenberg Sealing Technologies GmbH & Co. KG, James Walker Group Ltd., Garlock Sealing Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Pressure Seals Market Shifts & Advancements
Material science advances and regulatory chemistry constraints are compressing traditional seal design cycles while elevating performance specifications across oilfield, chemical, and aerospace end-uses.
Metal-reinforced elastomer laminates with embedded spring energizers are converging with fluoropolymer surface treatments to create hybrid architectures capable of surviving 10,000+ psi pressure cycling in subsea Christmas tree assemblies. Offshore equipment OEMs in the Gulf of Mexico and Brazil are specifying these configurations for 25-year design life requirements. The convergence is compressing replacement frequency and shifting value capture toward initial equipment specification rather than aftermarket parts.
EPA rules under the Clean Air Act and evolving OSHA process safety mandates are tightening emissions containment specifications for valve and pump seal interfaces in United States chemical processing plants. Mechanical seal suppliers must now document fugitive emission rates below 1,000 ppmv to maintain qualified vendor status with major petrochemical operators. Hydrogen service applications are experiencing the most acute compliance pressure, driving perfluoroelastomer migration in refinery hydrocracker units.
Buyer consolidation among supermajor oil companies and integrated chemical producers is compressing supplier rosters and elevating qualification barriers for tier-two seal fabricators. Procurement functions at ExxonMobil, Shell, and Dow are unbundling after-sales service from hardware supply, forcing seal vendors to compete on lifecycle cost models rather than unit pricing. This behavioral shift is most visible in Middle Eastern petrochemical corridors where state-owned operators are centralizing maintenance spend under single-source framework agreements.
Global High Pressure Seals Market Segmentation
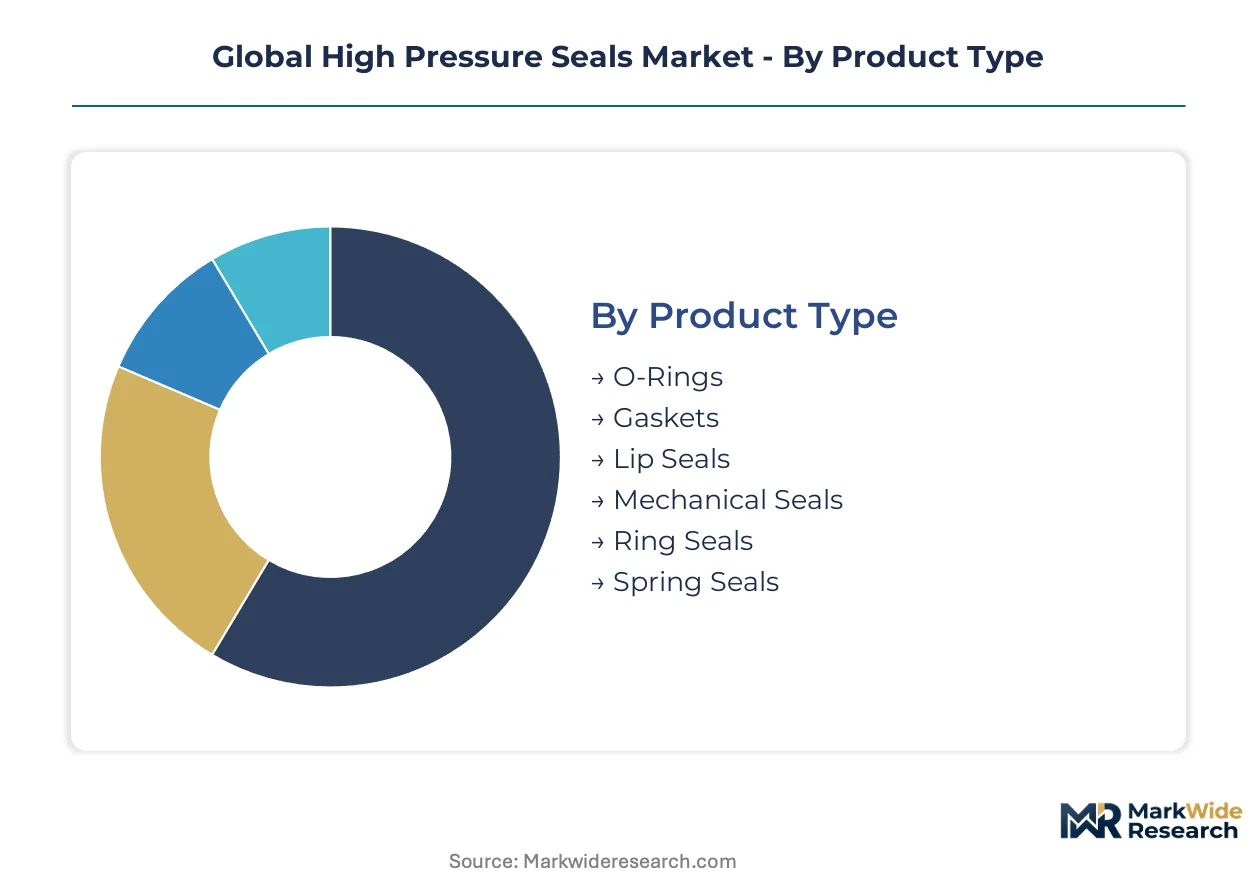
High pressure seals serve radically different duty cycles across subsea Christmas trees, aircraft turbine interfaces, and refinery hydrocracker units. Segmentation reveals where fluoropolymer substitution commands premium pricing versus where nitrile rubber retains volume dominance through legacy compatibility protocols.
Product Type:
Mechanical seals capture the largest value pool through replacement frequency and failure-cost exposure, while spring seals concentrate in subsea installations requiring 25-year design life.
- Mechanical Seals:Rotating equipment closures combining stationary and rotating faces with spring-loaded contact pressure. Demand concentrates in Gulf of Mexico offshore clusters and Middle Eastern petrochemical corridors where fugitive emission regulations mandate documented containment below 1,000 ppmv.
- Spring Seals:Energized fluoropolymer architectures with metallic coil springs maintaining face load across pressure cycling. Nordic offshore wind installations and Brazil's pre-salt basins specify these for subsea cable interfaces and Christmas tree assemblies facing 10,000+ psi extremes.
- O-Rings:Circular elastomer loops seated in machined grooves for static sealing.
- Gaskets:Compressible sheet or ring materials bolted between flanged surfaces.
- Lip Seals:Flexible elastomer lips with reinforced cases for rotary shaft retention.
- Ring Seals:Solid cross-section rings for piston and rod sealing in hydraulic cylinders.
Today's leader: Mechanical Seals. Tomorrow's challenger: Spring Seals.
Material:
Compound selection tracks regulatory chemistry constraints, with REACH substance restrictions and EPA emissions mandates accelerating fluoropolymer migration away from plasticizer-dependent formulations.
- PTFE:Virgin and filled polytetrafluoroethylene composites delivering chemical inertness across -200°C to 260°C. Aerospace OEMs specify PTFE laminates for next-generation propulsion systems where fire resistance and weight reduction converge.
- Nitrile Rubber:Hydrogenated nitrile elastomers (HNBR) with saturated polymer backbones resisting mineral oil attack. Legacy hydraulic systems in heavy equipment fabrication retain entrenched HNBR specifications due to established compatibility protocols and qualification timeline compression.
- Viton:Fluorocarbon elastomer with fluorine substituents for fuel and solvent resistance.
- Silicone:Polysiloxane chains for extreme temperature flexibility in food processing.
- EPDM:Ethylene-propylene-diene terpolymer for steam and phosphate ester compatibility.
- Polyurethane:Cast or injection-molded urethane elastomers for abrasion resistance in high-pressure hydraulics.
PTFE commands the premium tier. Nitrile Rubber anchors volume throughput.
Application:
End-use segmentation separates capital-intensive subsea deployments with extended qualification cycles from aftermarket-intensive rotating equipment with compressed replacement intervals.
- Oilfield Equipment:Subsea wellheads, manifolds, and production trees requiring metal-reinforced elastomer laminates. Brazil's pre-salt basins and Gulf of Mexico deepwater projects specify hybrid architectures surviving pressure cycling across 25-year field life.
- Aerospace Assemblies:Turbine blade roots, fuel system interfaces, and actuation hardware demanding fire-resistant seal architectures. OEM propulsion programs specify lighter PTFE composite laminates as airframe efficiency targets tighten.
- Hydraulic Systems:Cylinder seals, pump shaft retention, and valve spool closures in mobile and industrial equipment.
- Chemical Processing:Reactor agitators, pump casings, and valve bonnets under OSHA process safety mandates.
- Power Generation:Steam turbine glands, feedwater pump seals, and generator hydrogen containment.
- Marine Engineering:Propulsion shaft seals, stern tube bearings, and desalination plant closures.
Oilfield Equipment absorbs the heaviest engineering investment. Aerospace Assemblies expand most quickly.
End User Industry:
Customer consolidation among supermajor operators and integrated producers compresses supplier rosters while elevating lifecycle cost evaluation over unit pricing.
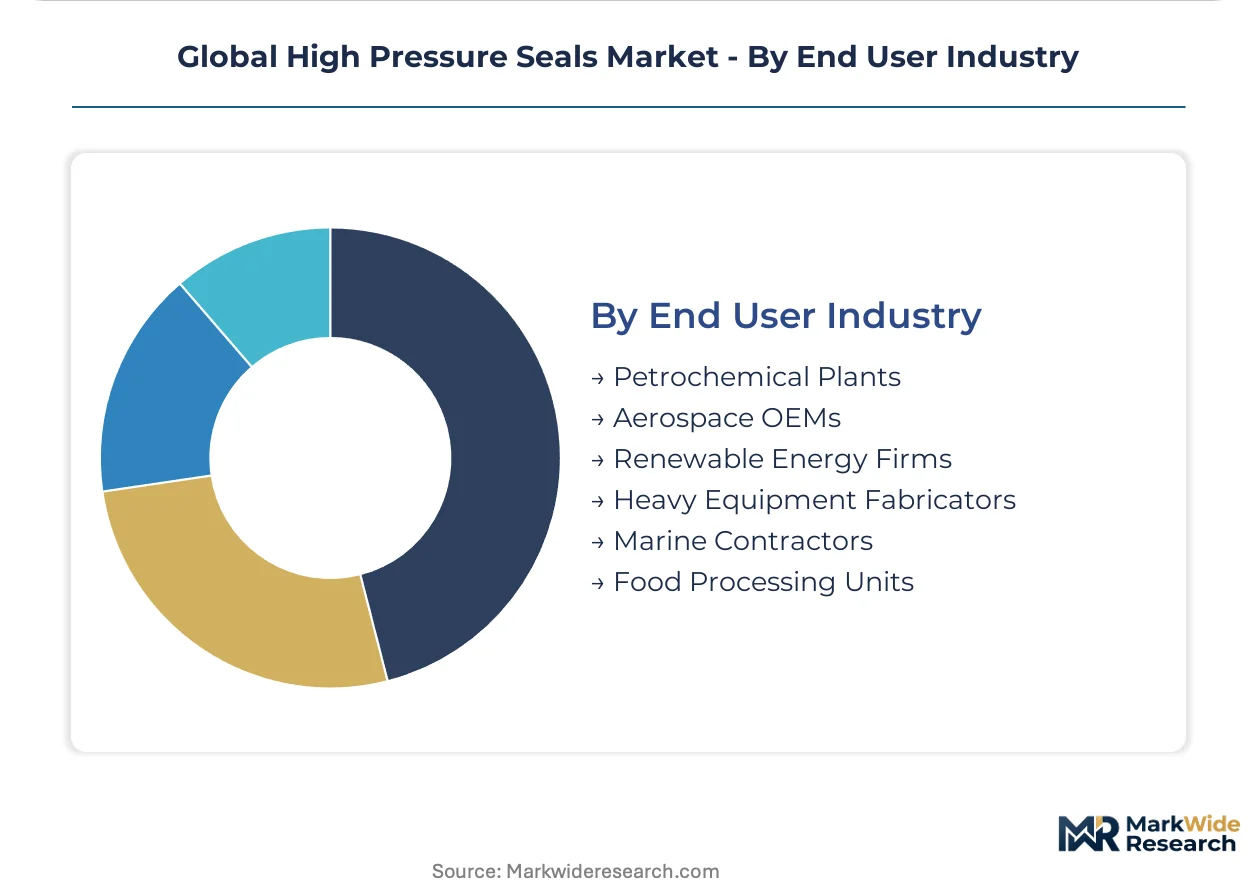
- Petrochemical Plants:Integrated chemical producers and refinery operators in Middle Eastern corridors and United States Gulf Coast. State-owned operators centralize maintenance spend under single-source framework agreements unbundling hardware from after-sales service.
- Aerospace OEMs:Engine manufacturers and airframers specifying next-generation seal architectures. FAA certification requirements and fire resistance specifications drive perfluoroelastomer penetration in critical turbine interfaces.
- Renewable Energy Firms:Offshore wind developers requiring specialized spring seal designs for turbine foundation and cable interfaces.
- Heavy Equipment Fabricators:Construction and mining OEMs with established HNBR hydraulic specifications.
- Marine Contractors:Shipyards and offshore installation specialists facing classification society requirements.
- Food Processing Units:Dairy, beverage, and pharmaceutical packaging equipment under FDA and EFSA material contact regulations.
Petrochemical Plants dominate procurement scale. Aerospace OEMs set performance specifications that cascade downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The high pressure seals industry traces its modern scale to post-war petrochemical buildouts along the United States Gulf Coast and subsequent North Sea offshore development, with manufacturing expertise later dispersing to German industrial clusters and East Asian shipbuilding centers.
United States
Deepwater capital deployment in the Gulf of Mexico offshore cluster sustains procurement volumes for mechanical seal assemblies rated for subsea pressure cycling. EPA rules under the Clean Air Act and OSHA process safety mandates tighten fugitive emission specifications below 1,000 ppmv for qualified vendor status. Houston anchors the largest concentration of seal fabricators serving petrochemical corridors along the Texas and Louisiana coasts.
Brazil
Pre-salt basin development drives specification of spring seal designs surviving 10,000+ psi pressure extremes across 25-year field life requirements. ANVISA and environmental licensing under IBAMA frameworks constrain material import protocols for offshore installations. Rio de Janeiro and Macaé host engineering centers coordinating procurement for floating production units.
Germany
REACH substance restrictions on plasticizers and curing agents accelerate perfluoroelastomer migration away from legacy nitrile formulations. ECHA compliance protocols force compounders toward low-carbon PTFE feedstocks qualifying for EU Green Deal innovation funding. Stuttgart and Munich industrial corridors concentrate captive elastomer blending capacity serving chemical processing OEMs.
China
GB standards and MEE environmental enforcement raise compliance thresholds for imported seal assemblies in petrochemical project pipelines. Dual carbon goals and domestic substitution policies favor local fabrication of metal-reinforced elastomer laminates. Shanghai and Ningbo manufacturing clusters scale compression molding capacity for hydraulic system exports.
Saudi Arabia
State-owned operators centralize maintenance spend under single-source framework agreements unbundling hardware from after-sales service. SFDA and SASO conformity requirements govern material specifications for refinery and chemical plant deployments. Jubail Industrial City and Yanbu concentrate demand for rotating equipment seal replacements in integrated petrochemical complexes.
Global High Pressure Seals Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the seal supply base, with integrated compounders controlling captive elastomer blending capacity while specialized fabricators rely on external resin supply. Market structure tilts toward consolidation among supermajor oil company procurement functions, compressing supplier rosters and elevating lifecycle cost evaluation over unit pricing. Three archetypes dominate: diversified industrial conglomerates with cross-sector seal portfolios, pure-play sealing specialists with deep material science expertise, and regional fabricators serving legacy hydraulic replacement demand. Competitive moves concentrate on backward integration into fluoropolymer resin supply and diagnostic service bundling for rotating equipment aftermarket channels.
Among diversified industrial conglomerates, Parker Hannifin Corporation and SKF Group occupy positions spanning aerospace, oilfield, and industrial end-uses through integrated seal-bearing service architectures. Trelleborg AB exemplifies the pure-play specialist archetype, anchoring Nordic offshore wind and subsea demand with focused spring seal design capabilities. EagleBurgmann Germany GmbH & Co. KG represents German engineering-centered positioning within the premium-tier mechanical seal segment.
| Leading Market Players |
|---|
| Parker Hannifin Corporation |
| Trelleborg AB |
| SKF Group |
| John Crane Inc. |
| Flowserve Corporation |
| EagleBurgmann Germany GmbH & Co. KG |
| Freudenberg Sealing Technologies GmbH & Co. KG |
| James Walker Group Ltd. |
| Garlock Sealing Technologies LLC |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-compliant fluoropolymer formulations and legacy nitrile specifications manifests in divergent margin structures and sourcing footprints across the seal supply base. Premium-tier compounders with captive elastomer blending capacity in Germany and the United States command pricing power through shortened qualification cycles, while commodity fabricators in China face compression from mineral oil compatibility constraints and extended OEM validation timelines.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs the high pressure seals market, with differentiation driven by certification tier (REACH-compliant perfluoroelastomer versus conventional HNBR) and after-sales service bundling. Cost compression in the standard tier intensifies as Brazilian pre-salt and Gulf of Mexico operators unbundle hardware from lifecycle service contracts. Petrochemical procurement functions exhibit the highest price sensitivity due to centralized framework agreements, while aerospace OEMs prioritize fire-resistance specifications over unit cost.
Supply Chain Analysis
EPA emissions documentation and REACH substance restrictions function as procurement gates that filter supplier rosters before volume allocation decisions. Virgin PTFE resin concentrates among chemical producers in the United States, Germany, and Japan, while metal-reinforced elastomer laminates draw from Chinese and South Korean compression molding clusters. Single-source vulnerability in fluoropolymer feedstock exposes fabricators to allocation risk during raw material tightness. Distribution runs through rotating equipment OEMs and specialized industrial distributors serving aftermarket replacement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance acceleration in Europe against EPA timeline compression in the United States creates arbitrage opportunities for compounders with dual-qualification capacity, rewarding geographic positioning that bridges regulatory divergence.
For Market Incumbents: Deepen backward integration into fluoropolymer resin supply to secure allocation priority during feedstock tightness and compress qualification cycles for next-generation perfluoroelastomer formulations. Expand captive blending capacity in Stuttgart and Houston industrial corridors to defend margin position against emerging Chinese fabricators with GB-standard compliance. Prioritize diagnostic service bundling for rotating equipment aftermarket channels where buyer consolidation elevates lifecycle cost evaluation. For New Entrants and Emerging Players: EU Green Deal innovation funding in Germany opens a window for low-carbon PTFE and bio-derived polyurethane feedstock development, creating cost-offset opportunities against established compounders. Nordic offshore wind installations represent the most penetrable white-space target, with specialized spring seal demand outpacing incumbent capacity for subsea cable interfaces. Pursue direct qualification with state-owned operators in Saudi Arabia and Brazil through local engineering partnerships rather than distributor channels. For Investors and Strategic Acquirers: Consolidation pressure builds where buyer roster compression among supermajor oil companies and integrated chemical producers strands tier-two fabricators without framework agreement access. Long-term viability favors vertically integrated specialists with material science depth and diagnostic service capabilities over pure-play hardware suppliers. Watch for inflection signals in subsea pressure cycling fatigue expertise scarcity, where qualified engineering capacity constraints specialist fabricator expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Secures allocation priority during virgin PTFE tightness for REACH-compliant compounders. |
| Diagnostic Service Bundling | Captures rotating equipment aftermarket value as ExxonMobil and Shell unbundle hardware from lifecycle contracts. |
| EU Green Deal Feedstock Development | Qualifies low-carbon PTFE and bio-polyurethane for innovation funding in German industrial corridors. |
| Subsea Pressure Cycling Qualification | Opens Nordic offshore wind and Brazil pre-salt demand requiring 25-year design life spring seals. |
| Dual-Jurisdiction Compliance Investment | Straddles EPA emissions mandates and REACH substance restrictions to avoid stranded inventory. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with seal fabricator technical directors, petrochemical procurement leads, aerospace OEM specification engineers, and aftermarket service heads with secondary validation through customs trade data, SEC filings of diversified industrial conglomerates, and ECHA substance restriction databases. Bottom-up triangulation across product type, material grade, and application segmentation converged with top-down macroeconomic anchoring.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product architecture (mechanical versus spring seal), material chemistry tier (fluoropolymer versus hydrogenated nitrile versus metal-reinforced laminate), end-use duty cycle (subsea capital deployment versus rotating equipment aftermarket), and geographic regulatory cluster (EPA-mandated, REACH-constrained, GB-standard). CAGRs derived from volume-weighted trajectory analysis incorporating deepwater capital deployment schedules and aerospace propulsion program timelines.
Revisions become necessary when regulatory divergence across EPA, REACH, and GB jurisdictions accelerates qualification timeline compression beyond modeled assumptions, or when fluoropolymer feedstock concentration triggers allocation constraints unreflected in base-case supply elasticity. A model refresh is warranted upon material change in offshore wind installation cadence or supermajor procurement centralization behavior.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Conveyor Belt Materials Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Saudi Arabia Industrial Insulation Market
Industrial Materials
High Shear Mixer Market
Industrial Materials
Lip Seals Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Global Graphite Electrodes Market
Industrial Materials
High Speed Steels Market
Industrial Materials
United States Graphite Electrodes Market
Industrial Materials
Paint Knife Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
GCC Welding Consumables Market
Industrial Materials
Global Thermally Modified Wood Market
Industrial Materials
Natural Industrial Absorbents Market
Industrial Materials
Global High Temperature Gaskets Market