
 Heat Shrink Tubing and Sleeves Market | 2026-2036
Heat Shrink Tubing and Sleeves Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Shrink Tubing and Sleeves Market Outlook
Multi-source procurement for specialty polymer feedstocks is shifting toward vertically integrated compounders with captive resin production. TE Connectivity leverages backward integration into polyolefin compounding to secure batch consistency for aerospace-grade tubing. Sumitomo Electric Industries anchors its position through fluoropolymer extrusion expertise serving Japan's precision electronics sector. HellermannTyton competes via global distribution density across industrial maintenance channels.
Heat shrink tubing and sleeves are cross-linked polymer tubes that contract radially when heated, typically to one-half or less of their supplied diameter, creating a tight environmental seal over substrates. Manufacturers irradiate or chemically cross-link base polymers to establish memory properties, then expand and cool the tubing for final sizing. Polyolefin formulations dominate volume due to cost-performance balance across electrical insulation applications, while fluoropolymer variants command premium positioning in chemical resistance segments where FEP and PTFE specifications justify higher unit economics. The automotive end-user segment exhibits the fastest structural expansion as high-voltage architectures multiply connection points per vehicle platform.
REACH registration requirements in Europe, RoHS substance restrictions, and UL 224 flammability standards collectively elevate compliance costs for new market entrants while reinforcing incumbent certification portfolios. The FAA's material fireworthiness regulations and NHTSA's wire harness durability standards in the United States add parallel certification layers for aerospace and automotive suppliers. Stakeholders must monitor evolving halogen-free mandates across multiple jurisdictions and assess compound reformulation timelines against existing qualification cycles.
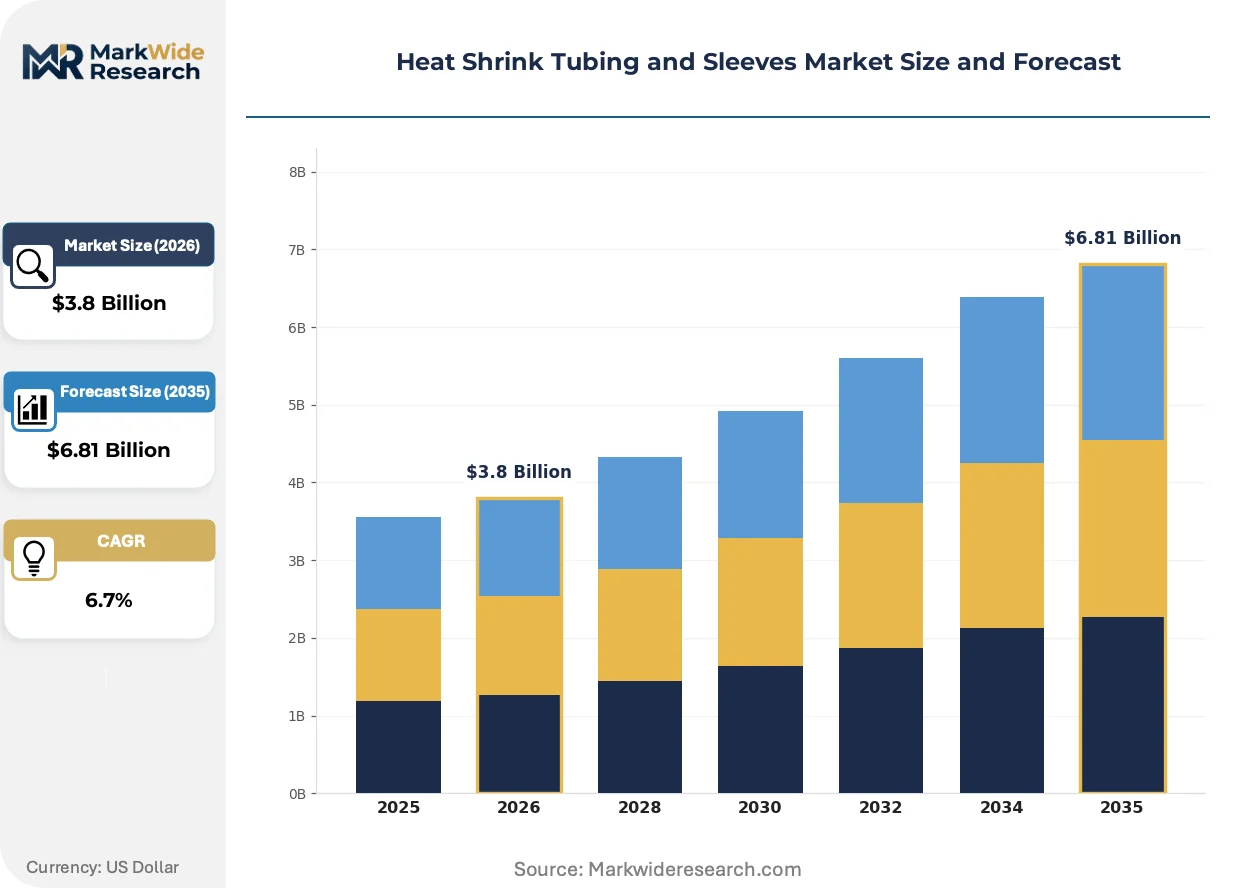
Market Dynamics
The automotive sector's high-voltage electrification is restructuring procurement volumes, with wire harness complexity multiplying connection points per vehicle platform and forcing compounders to secure fluoropolymer resin supply chains.
Growth Catalysts
- High-Voltage Automotive Architectures:Battery electric vehicle platforms require sealed interconnect protection across 800V systems, expanding fluoropolymer sleeve specifications at tier-1 harness suppliers.
- REACH Article 33 Disclosure Obligations:ECHA enforcement of Substances of Very High Concern reporting is accelerating halogen-free formulation adoption across German automotive supplier corridors.
- Irradiation Cross-Linking Advancement:Electron beam processing improvements are reducing manufacturing cycle times for polyolefin tubing, enabling cost-competitive aerospace-grade batch consistency.
Market Restraints
- Fluoropolymer Feedstock Concentration:FEP and PTFE resin supply concentrates among limited specialty chemical producers, exposing processors to allocation risk during semiconductor sector demand surges.
- UL 224 Recertification Burden:Flammability rating updates require 18-24 month requalification cycles, freezing formulation changes for incumbent suppliers.
- Silicone Elastomer Substitution:Cold-shrink alternatives eliminate heating equipment requirements in field installations, compressing addressable market for traditional heat-shrink in utility maintenance applications.
Strategic Opportunities
- India PLI Scheme for Automotive:Production-linked incentives for electric vehicle component manufacturing are attracting wire harness investments in Tamil Nadu and Gujarat, creating localized sleeve demand.
- CSRD Supply Chain Disclosure:EU corporate sustainability reporting mandates are forcing OEMs to document polymer provenance, rewarding compounders with certified circular feedstock streams.
- Dual-Wall Adhesive-Lined Convergence:Sealing technology integration with thermoplastic adhesive layers is opening marine and submersible applications previously served by molded boots.
Industry Challenges
- Radiation Processing Technician Scarcity:Electron beam facility operation requires specialized safety certification that outpaces vocational training program output in North American manufacturing regions.
- Multi-Jurisdiction Qualification Overlap:Simultaneous FAA fireworthiness, NHTSA durability, and OEM-specific material approvals create timeline conflicts for new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Shrink Tubing and Sleeves Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyolefin, PVC, Nylon, Fluoropolymer Application: Electrical Insulation, Mechanical Protection, Fluid Management, Chemical Resistance End User: Telecommunications, Automotive, Aerospace, Industrial Equipment Size: Small, Medium, Large, Extra Large |
| Companies Covered | TE Connectivity, 3M Company, Sumitomo Electric Industries, HellermannTyton, Molex LLC, Amphenol Corporation, ABB Ltd., Panduit Corp., Alpha Wire Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Shrink Tubing and Sleeves Market Strategic Shifts
Material science advances and regulatory disclosure requirements are restructuring competitive advantage around certified supply chain transparency and application-specific performance validation.
Cross-linked polyolefin formulations with enhanced thermal endurance ratings are displacing standard-grade materials in engine compartment applications. Automotive harness manufacturers in Stuttgart's supplier corridor specify these grades for 150°C continuous operation. This material upgrade is converging with lightweighting mandates that eliminate heavier conduit alternatives.
ECHA's tightening SVHC candidate list is forcing systematic substitution of halogenated flame retardants across European electrical insulation supply chains. Compounders must reformulate with phosphorus-nitrogen synergists while maintaining UL 224 VW-1 ratings. German automotive suppliers are responding by consolidating procurement with vertically integrated compounders holding validated REACH registration dossiers.
Long-term supply agreements with fixed-volume commitments are displacing spot-market resin purchasing among aerospace-grade tubing processors. Tier-1 harness manufacturers in Japan's precision electronics sector now demand 36-month compound supply guarantees. This contractual shift is most visible in fluoropolymer categories where resin allocation determines production continuity.
Heat Shrink Tubing and Sleeves Market Segmentation
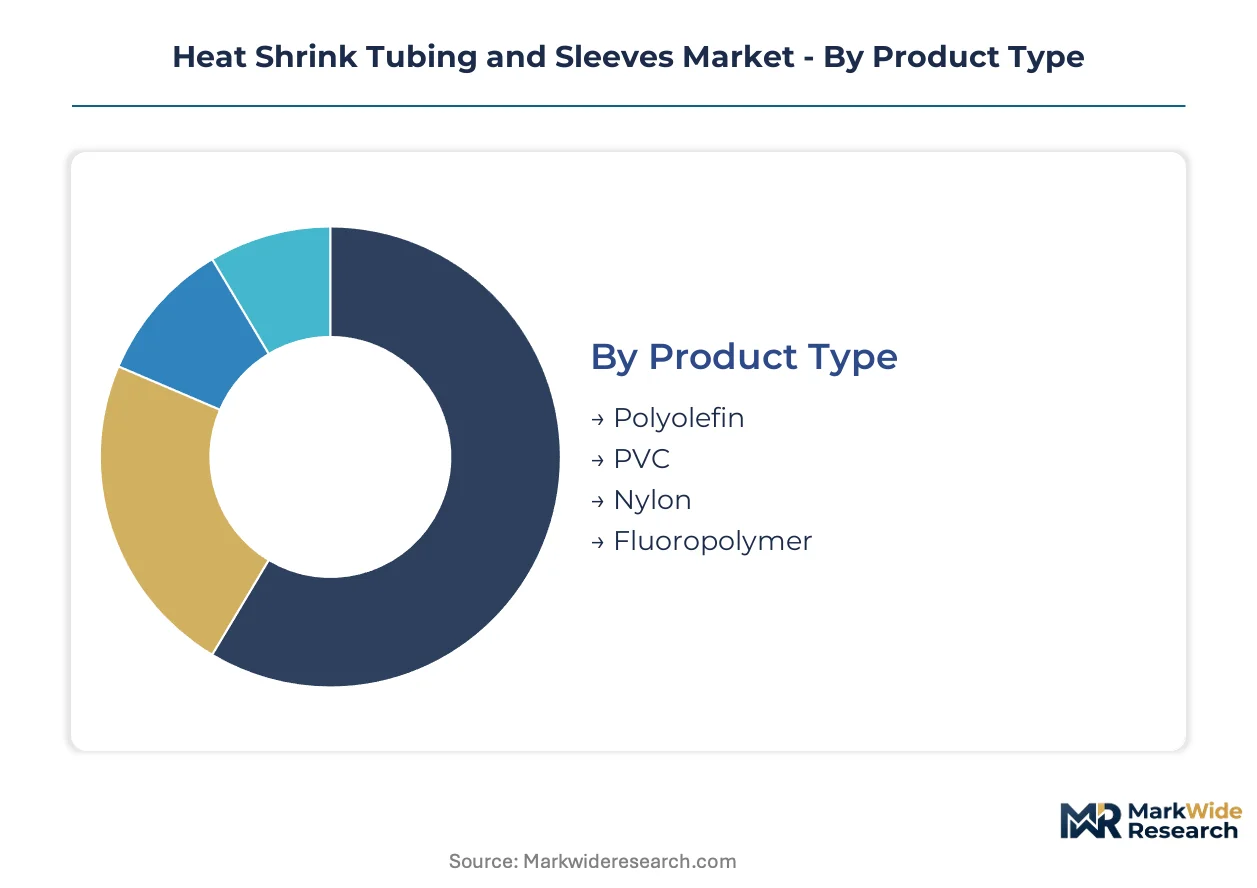
Segmentation in heat shrink tubing and sleeves follows material chemistry and functional specification rather than brand differentiation. Procurement decisions at tier-1 harness manufacturers prioritize thermal rating, chemical resistance, and regulatory certification over unit cost.
Product Type:
Cross-linking chemistry and base polymer selection determine performance ceilings for temperature exposure, dielectric strength, and environmental sealing.
- Polyolefin:Electron-beam cross-linked polyethylene and polypropylene formulations deliver cost-performance balance across general electrical insulation. German automotive suppliers around Stuttgart specify enhanced thermal grades for 150°C continuous operation in engine bay harnesses.
- Fluoropolymer:FEP and PTFE extrusions command premium positioning through exceptional chemical inertness and 200°C+ service temperatures. Battery electric vehicle wire harness manufacturers are expanding procurement volumes for 800V system protection.
- PVC:Plasticized formulations offer economical flame-retardant insulation for consumer electronics and low-voltage applications. REACH SVHC restrictions are accelerating substitution in European supply chains.
- Nylon:Abrasion-resistant grades serve mechanical protection in industrial robotics and cable management systems requiring flexural endurance.
Mature deployment sits with polyolefin. Newer deployment is concentrated in fluoropolymer.
Application:
Functional requirements separate commodity insulation from engineered sealing solutions in harsh environment specifications.
- Electrical Insulation:Dielectric barrier applications dominate volume consumption across wire harness manufacturing. TE Connectivity's backward integration into polyolefin compounding secures batch consistency for aerospace-grade specifications.
- Mechanical Protection:Abrasion and strain relief functions protect cable assemblies in industrial automation and robotics installations. Japan's precision electronics sector demands tight tolerance control for miniature harness applications.
- Chemical Resistance:Fluoropolymer sleeves in chemical processing and semiconductor fabrication resist aggressive solvent exposure. FEP specifications justify higher unit economics where PTFE rigidity limits conformability.
- Fluid Management:Dual-wall adhesive-lined constructions create environmental seals in marine and submersible applications previously served by molded boots.
Volume concentration rests with electrical insulation. Steepest expansion trajectory is visible in fluid management.
End User:
Industry-specific certification requirements fragment procurement patterns across regulated and unregulated application environments.
- Automotive:High-voltage electrification multiplies connection points per vehicle platform and forces compounders to secure fluoropolymer resin supply chains. NHTSA wire harness durability standards add parallel certification layers for tier-1 suppliers.
- Aerospace:FAA material fireworthiness regulations mandate low-smoke zero-halogen formulations for cabin and avionics harness protection. Long-term supply agreements with fixed-volume commitments now displace spot-market resin purchasing.
- Industrial Equipment:Factory automation and process control applications specify general-purpose polyolefin for cost-sensitive cable management.
- Telecommunications:Fiber optic and copper network infrastructure drives demand for UV-resistant outdoor grades and color-coded identification sleeves.
Procurement scale favors automotive. Certification complexity peaks in aerospace.
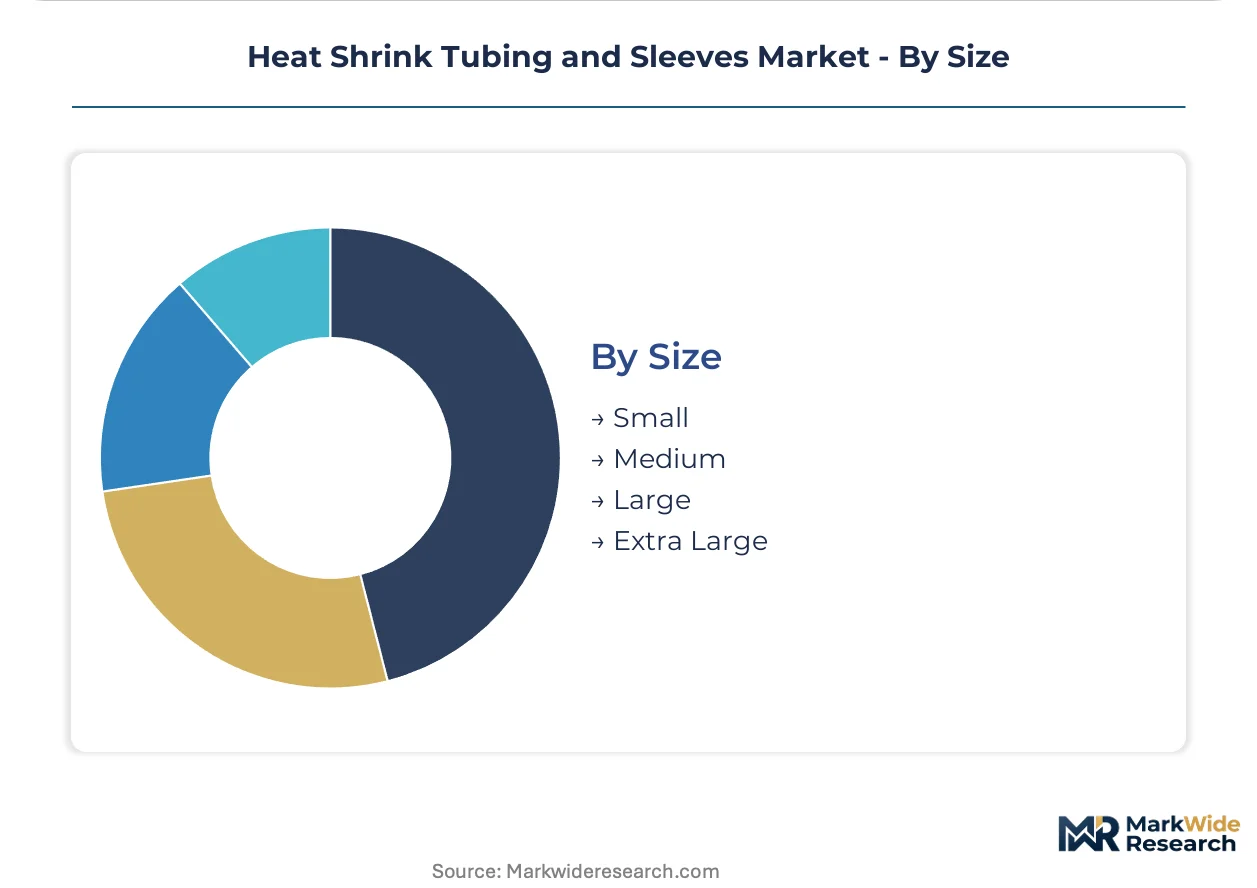
Size:
Shrink ratio and recovered diameter specifications align with conductor gauge and bundle geometry in harness design.
- Small:Diameters under 6mm recovered dimension serve miniature electronics and sensor wiring in medical devices and precision instrumentation.
- Medium:6-25mm range addresses standard automotive and industrial power distribution harnesses with moderate conductor counts.
- Large:25-50mm specifications protect heavy-gauge battery cables and multi-conductor industrial control bundles.
- Extra Large:Above 50mm accommodates submarine cable terminations and large-diameter hydraulic hose protection in marine and offshore applications.
Production throughput concentrates in medium diameters. Technical differentiation increases toward extra large formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fluoropolymer resin production concentrates in Germany, Japan, and the United States, anchoring regional supply chains for high-performance tubing specifications. Automotive electrification and aerospace certification demands are restructuring procurement patterns across these manufacturing centers.
United States
FAA fireworthiness regulations for low-smoke zero-halogen formulations drive demand in commercial aviation wire harness applications. NHTSA durability standards for high-voltage automotive systems add parallel certification requirements for domestic suppliers. TE Connectivity's backward integration into polyolefin compounding secures batch consistency from facilities serving aerospace-grade specifications.
Germany
REACH Article 33 disclosure obligations and RoHS substance restrictions accelerate halogen-free formulation adoption across automotive supply chains. ECHA enforcement of Substances of Very High Concern reporting forces systematic compound reformulation. Stuttgart's supplier corridor specifies enhanced thermal grades for 150°C continuous operation in battery electric vehicle engine bay harnesses.
Japan
Precision electronics manufacturing demands tight tolerance control for miniature harness applications in robotics and semiconductor equipment. METI industrial standards govern material specifications for high-reliability electrical insulation. Sumitomo Electric Industries anchors fluoropolymer extrusion expertise serving domestic tier-1 harness manufacturers with 36-month compound supply guarantees.
China
GB standards for electrical insulation materials and MIIT automotive regulations shape domestic formulation requirements. Dual carbon goals accelerate substitution of halogenated flame retardants in export-oriented supply chains. Yangtze River Delta wire harness producers are expanding fluoropolymer sleeve procurement for 800V battery electric vehicle platforms.
India
PLI scheme production-linked incentives for electric vehicle component manufacturing attract wire harness investments in Tamil Nadu and Gujarat. BIS certification requirements for electrical insulation materials elevate entry barriers for imported formulations. Domestic compounders are securing long-term resin supply agreements to serve localized sleeve demand from automotive OEMs.
Heat Shrink Tubing and Sleeves Market Competitive Environment
Backward integration into captive resin production dominates the current landscape as compounders secure supply chain continuity against fluoropolymer allocation risk. The vendor base separates into three structural tiers: vertically integrated specialists with in-house polymer compounding, regional processors dependent on spot-market feedstock purchasing, and distribution-focused assemblers serving maintenance channels. Strategic archetypes include resin-integrated compounders, extrusion-specialist fabricators, and global logistics platforms. M&A activity concentrates on securing electron beam processing capacity, while capacity expansion targets fluoropolymer extrusion lines for automotive electrification demand.
Among resin-integrated specialists, TE Connectivity and Sumitomo Electric Industries exemplify the backward-integrated archetype through captive polyolefin and fluoropolymer supply chains. HellermannTyton occupies a position within the distribution-density tier, leveraging global channel presence across industrial maintenance segments. These three entities represent distinct competitive vectors: compound-level control, application-specific extrusion expertise, and logistics scale.
| Leading Market Players |
|---|
| TE Connectivity |
| 3M Company |
| Sumitomo Electric Industries |
| HellermannTyton |
| Molex LLC |
| Amphenol Corporation |
| ABB Ltd. |
| Panduit Corp. |
| Alpha Wire Company |
| Others |
Value Chain & Pricing Dynamics
Fluoropolymer resin costs cascade through three distinct pricing tiers as compounders with captive supply chains command premium positioning against spot-market dependent processors serving economy-grade polyolefin segments.
Pricing Analysis
Extended warranty and technical certification bundling separates premium fluoropolymer sleeves from unbundled commodity polyolefin offerings. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume commitment scale. Pricing pressure stems from silicone cold-shrink alternatives compressing utility maintenance demand. Tier-1 automotive harness manufacturers exhibit lowest price sensitivity due to NHTSA durability mandates, while industrial maintenance channels show highest elasticity.
Supply Chain Analysis
India's PLI scheme domestic-content thresholds are redirecting fluoropolymer sleeve procurement toward Tamil Nadu and Gujarat manufacturing clusters. Resin supply concentrates in Germany, Japan, and the United States. Feedstock draws from FEP and PTFE specialty chemical producers, electron beam processing facilities, and halogen-free additive compounders. Single-source vulnerability in fluoropolymer resin allocation during semiconductor demand surges poses structural risk. Distribution runs through tier-1 harness manufacturers direct to OEMs, bypassing traditional industrial distribution for automotive-grade specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a backward-integration race where control over fluoropolymer resin supply chains determines tier positioning and pricing power against spot-market dependent competitors.
For Market Incumbents: Deepen captive resin production through long-term offtake agreements with specialty chemical producers to secure allocation priority during semiconductor sector demand surges. Expand electron beam processing capacity in Germany's automotive supplier corridor to capture REACH-compliant halogen-free formulation demand from Stuttgart OEMs. Consolidate certification portfolios across FAA fireworthiness and NHTSA durability standards to extend qualification moats against emerging compounders. For New Entrants and Emerging Players: Begin with India's PLI scheme beneficiaries in Tamil Nadu and Gujarat, where localized sleeve demand from electric vehicle component manufacturing outpaces domestic fluoropolymer extrusion capacity. Target marine and submersible fluid management applications where dual-wall adhesive-lined constructions displace molded boots with lower certification barriers. Pursue technical partnership routes with established irradiation cross-linking facilities rather than greenfield processing investments. For Investors and Strategic Acquirers: Electron beam facility acquisition announcements from automotive-focused compounders are the leading indicator that fluoropolymer allocation risk is reshaping competitive economics. Long-term viability centers on vertically integrated specialists with validated REACH registration dossiers and 36-month supply guarantee contracts. Target acquisition archetype: regional processors with established UL 224 certifications and underutilized extrusion capacity in India or Southeast Asia.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin | Captive supply chains eliminate allocation risk during semiconductor demand surges from Intel and TSMC expansions. |
| Electron Beam Processing Capacity Expansion | Faster cross-linking cycle times enable cost-competitive aerospace-grade batch consistency for TE Connectivity specifications. |
| Halogen-Free Formulation Certification | ECHA SVHC compliance opens procurement access to Stuttgart automotive supplier corridor and German OEMs. |
| Long-Term Supply Agreements | Fixed-volume commitments displace spot purchasing among Japan's precision electronics tier-1 harness manufacturers. |
| Geographic Manufacturing Footprint in India | PLI scheme incentives attract wire harness investments in Tamil Nadu and Gujarat for localized sleeve demand. |
Study Parameters
Independent corroboration across primary interviews with wire harness procurement directors, electron beam facility operations managers, and fluoropolymer compounder technical leads underwrites the qualitative findings. Secondary validation draws from ECHA SVHC candidate list updates, UL 224 flammability standard revisions, FAA material fireworthiness regulations, and NHTSA wire harness durability guidance documents. Bottom-up volume modeling from tier-1 supplier production data triangulates against top-down automotive electrification content-per-vehicle estimates.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline capacity utilization and post-2020 automotive production recovery trajectories. The analytical framework segments by material chemistry, functional specification, end-user industry certification requirements, and regional regulatory cluster across the projection horizon. CAGRs derive from compound annual growth trajectory modeling. Key inputs include battery electric vehicle platform ramp schedules and 800V architecture penetration assumptions.
Underlying measurement precision varies by segment; fluoropolymer categories with concentrated resin supply carry tighter precision than dispersed polyolefin grades. Forecasts reflect documented assumptions regarding REACH enforcement intensity and automotive electrification adoption curves. Raw material price volatility in specialty chemical feedstocks and electron beam technician training program output could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Global Jet Mill Market
Industrial Materials
Wood Shavings Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Steel Processing Market
Industrial Materials
Industrial Absorbents Market
Industrial Materials
Carbide Inserts Market
Industrial Materials
Global Polyurethane Screen Panels Market
Industrial Materials
Self Locking Nuts Market
Industrial Materials
Tooling Board Market
Industrial Materials
Middle East Activated Carbon Market
Industrial Materials
Twin Screw Extruders Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Industrial Continuous Furnaces Market
Industrial Materials
2-in-1 Material Rack Correction Machine Market
Industrial Materials
Atomizing Metal Powder Market
Industrial Materials
Plastic Injection Mold Market